
 Europe EV Insurance Market | 2026-2036
Europe EV Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe EV Insurance Market Analytics
Agent networks across continental Europe are tilting toward digital-first distribution as EV policy complexity outpaces traditional underwriting workflows. Allianz SE leverages its captive telematics infrastructure to price battery degradation risk with granularity that direct competitors struggle to match. Direct Line Insurance Group plc anchors its competitive stance in the United Kingdom through specialized EV repair networks that compress claims cycle times. AXA competes by embedding usage-based insurance modules into OEM companion apps, capturing driver behavior data at the source.
Europe EV Insurance encompasses risk-transfer instruments engineered specifically for battery-electric vehicles, incorporating coverage for high-voltage system failure, thermal runaway events, and specialized recovery protocols that internal combustion policies exclude. These instruments serve primarily to indemnify asset holders against repair cost inflation driven by proprietary EV architectures and limited certified repair capacity. Comprehensive coverage dominates premium income pools due to mandated battery protection endorsements across major European jurisdictions, while personal injury protection represents the fastest-growing line as medical cost inflation outpaces bodily injury liability trends. Distribution through online channels is accelerating fastest among fleet customer segments, where multi-vehicle policy administration demands algorithmic quoting platforms that broker networks only partially provide.
EMA's evolving pharmacovigilance frameworks do not govern this sector; instead, national insurance regulators and EU-level standard-setters shape market access conditions. EIOPA's stress-testing protocols for climate-transition risk are forcing insurers to recalibrate EV portfolio reserves, while CE marking requirements for onboard telematics hardware influence data-capture standards that underpin usage-based products. REACH compliance obligations for battery materials cascade into salvage and total-loss valuation methodologies that insurers must operationalize. Stakeholders should monitor how national transpositions of the EU AI Act constrain automated claims adjudication models before committing capital to algorithmic underwriting platforms.
Market Dynamics
The EU Green Deal's embedded vehicle-emission benchmarks are forcing insurers to rebuild risk models around battery degradation curves and thermal runaway probabilities rather than traditional mechanical failure rates.
Growth Catalysts
- Fleet electrification mandates:Commercial transport operators across Germany, France, and the Netherlands face binding decarbonization timelines that accelerate multi-vehicle policy issuance and algorithmic quoting platform adoption.
- REACH compliance for battery materials:Salvage valuation methodologies now incorporate rare earth recovery economics, creating specialized coverage products for total-loss scenarios that internal combustion policies cannot address.
- Telematics hardware standardization:CE marking requirements for onboard data-capture devices enable usage-based insurance modules that price risk at the individual driver level rather than vehicle class averages.
Market Restraints
- Certified repair capacity scarcity:Proprietary EV architectures from OEMs limit the number of authorized service centers, inflating repair cost uncertainty and compressing loss-ratio predictability for underwriters.
- High-voltage technician training gaps:The specialized skill requirements for battery system diagnostics create labor bottlenecks that extend claims cycle times beyond traditional auto insurance benchmarks.
- EIOPA climate-transition stress tests:Mandatory portfolio reserve recalibrations for EV exposure are diverting capital from product innovation toward regulatory compliance buffers.
Strategic Opportunities
- Poland and Eastern European fleet markets:Underpenetrated commercial EV adoption relative to Western Europe offers first-mover positioning for insurers building algorithmic multi-vehicle administration platforms.
- OEM companion app integration:Embedded insurance modules that capture real-time driver behavior data at the source bypass traditional broker networks and reduce customer acquisition costs.
- EU AI Act automated adjudication pathways:National transpositions creating compliant frameworks for algorithmic claims processing will reward early infrastructure investment with operational cost advantages.
Industry Challenges
- Cross-border data governance fragmentation:GDPR interpretation variance across member states complicates telematics data pooling for usage-based pricing models that rely on pan-European driver behavior datasets.
- Battery state-of-health verification standardization:Absence of unified diagnostic protocols forces insurers to develop proprietary degradation assessment tools, raising operational complexity and vendor management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe EV Insurance Market |
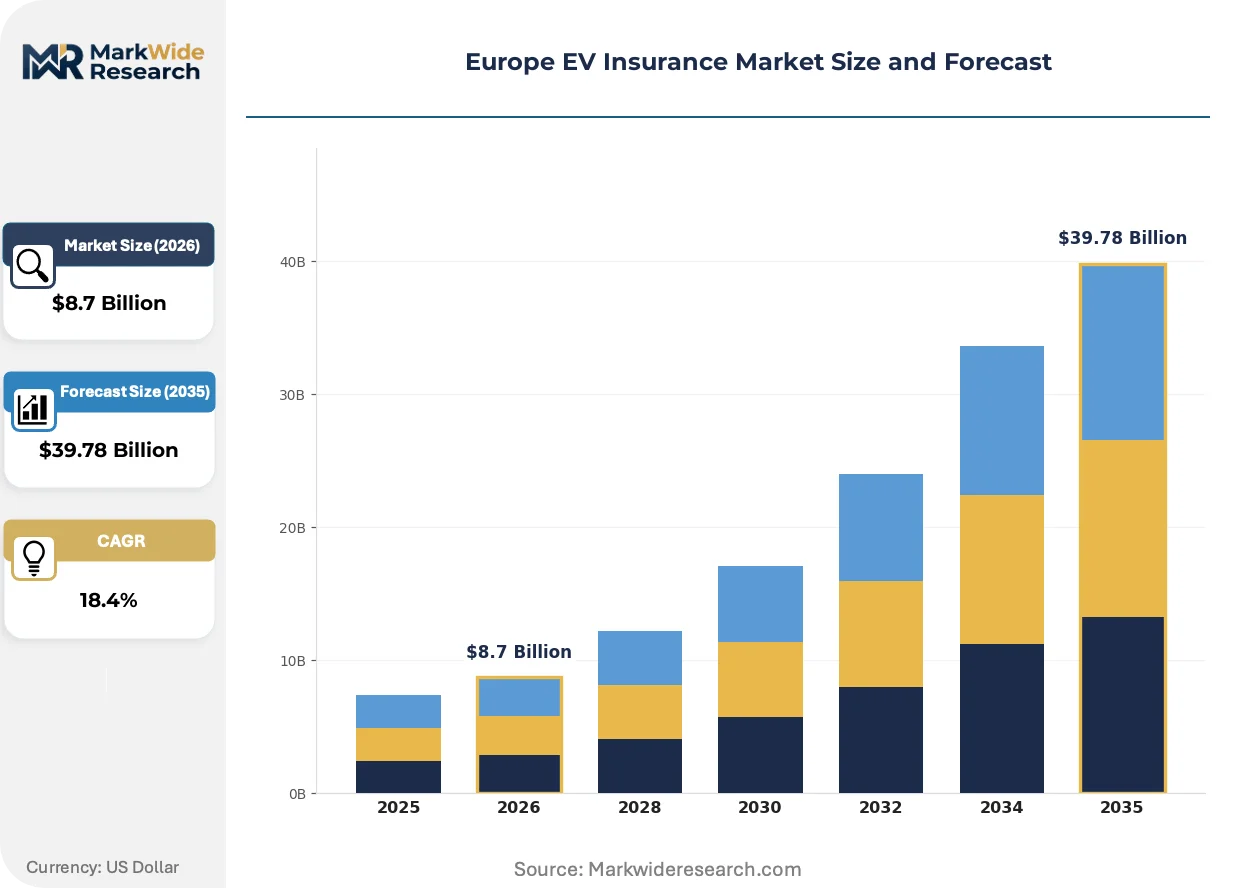
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Comprehensive, Third Party Liability, Collision, Personal Injury Protection Coverage Type: Bodily Injury, Property Damage, Theft, Natural Disasters Customer Type: Individuals, Fleets, Businesses, Government Distribution Channel: Online, Agents, Brokers, Direct Sales |
| Companies Covered | Aviva plc, Direct Line Insurance Group plc, Allianz SE, MAPFRE, Admiral Group plc, AXA, Esure Group plc, Zego, Zurich Insurance Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe EV Insurance Market Evolving Landscape
Agent networks across continental Europe are tilting toward digital-first distribution as EV policy complexity outpaces traditional underwriting workflows. The convergence of embedded telematics, regulatory data mandates, and fleet procurement centralization is compressing the policy lifecycle from quotation to claims settlement.
Telematics-enabled dynamic pricing is digitizing risk assessment for battery-electric vehicles. Fleet operators in Germany and the Netherlands are adopting real-time driver behavior monitoring at the fastest clip. This technology is digitizing premium calculation from annual vehicle-class averages to kilometer-specific, driving-pattern-adjusted rates that align cost with actual exposure.
EIOPA's climate-transition stress-testing protocols are reshaping capital allocation across European insurers. Mandatory EV portfolio reserve recalibrations are diverting investment from product development toward compliance infrastructure. German and French carriers are responding by consolidating battery-risk modeling functions into specialized actuarial units separate from legacy auto divisions.
Fleet procurement centralization is altering distribution economics for commercial EV coverage. Large transport operators in Scandinavia and the Benelux region are bypassing traditional broker networks in favor of direct API connections to insurer quoting engines. This shift is most visible in Denmark, where municipal fleet consolidation has reduced the number of policy administration touchpoints by over half while demanding algorithmic multi-vehicle management capabilities that legacy broker infrastructure cannot provision.
Europe EV Insurance Market Segmentation
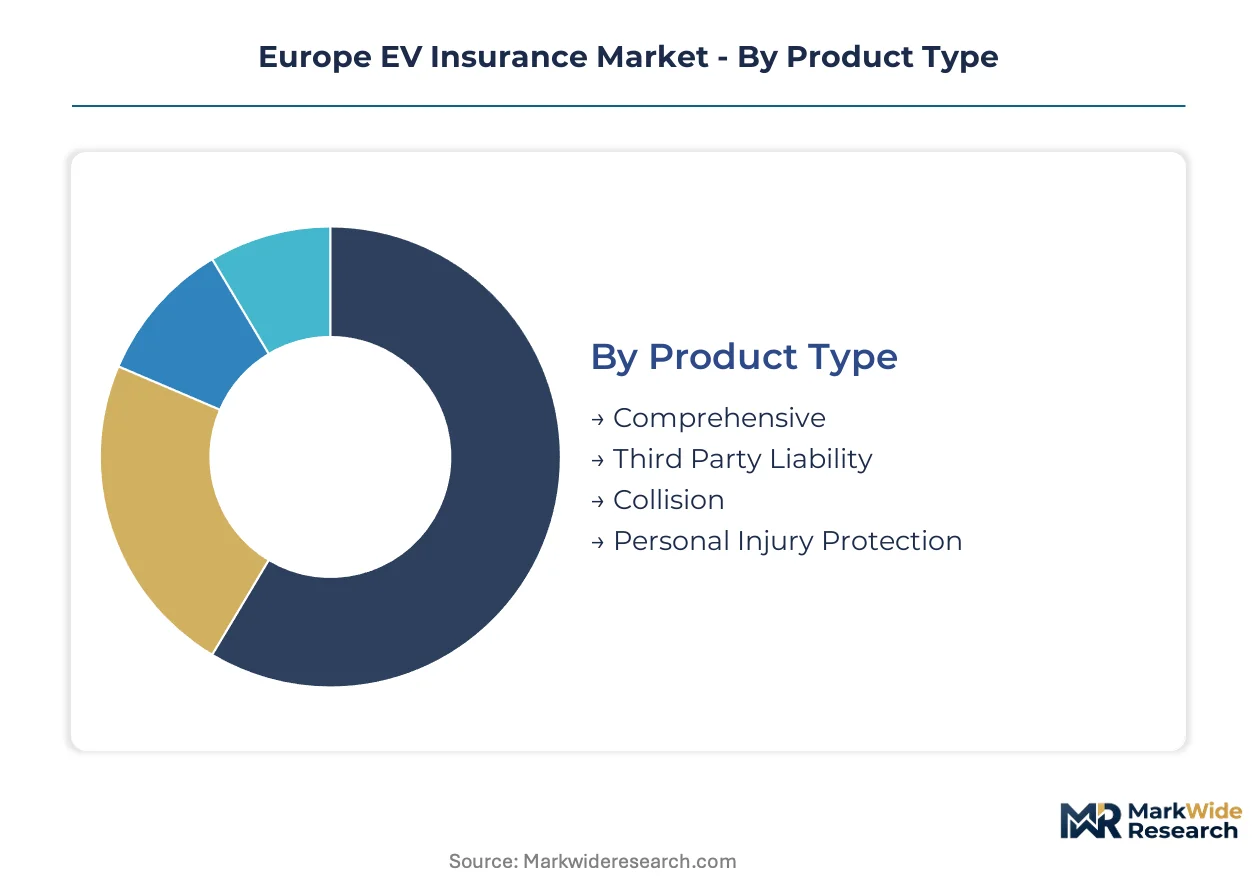
Segmentation in the Europe EV Insurance Market reflects how electrification is fragmenting risk profiles across product architectures, coverage scopes, and procurement behaviors. Each dimension captures distinct underwriting economics and distribution requirements that legacy auto insurance frameworks rarely address.
Product Type:
Cost tier differentiation separates policies by the depth of financial protection offered against EV-specific repair inflation and battery system failures.
- Comprehensive:Bundles battery protection endorsements with standard vehicle coverage, addressing thermal runaway damage and high-voltage system failures that proprietary OEM architectures make prohibitively expensive to repair. German and French regulators mandate these endorsements, concentrating premium income in jurisdictions with binding EV warranty requirements.
- Third Party Liability:Covers bodily injury and property damage to external parties without protecting the policyholder's own asset. Fleet operators in the Netherlands select this tier for secondary vehicles in electrified commercial pools where self-insured retention programs absorb direct damage.
- Collision:Isolates damage from accidents involving another vehicle or fixed object. Demand clusters among individual owners of mid-range battery-electric models in urban Italian and Spanish markets where comprehensive premiums strain household budgets.
- Personal Injury Protection:Medical cost coverage for occupants regardless of fault. Medical inflation outpaces bodily injury liability trends across EU member states, accelerating policy attachment rates in Scandinavian markets with universal healthcare cost-sharing mechanisms.
Comprehensive commands the established base. The steepest expansion runs through Personal Injury Protection.
Coverage Type:
Application-specific risk transfer mechanisms align indemnity structures with the distinct loss patterns that electrified drivetrains introduce.
- Bodily Injury:Liability arising from operator or third-party physical harm. EVs' instant torque delivery and altered pedestrian collision dynamics reshape severity curves, prompting German actuarial units to develop specialized frequency models separate from legacy internal combustion benchmarks.
- Property Damage:External asset destruction including other vehicles and infrastructure. High-voltage system failures can trigger cascading damage in parking structures, driving demand for sub-limits in dense Belgian and Dutch urban centers.
- Theft:Coverage for vehicle or component loss. Battery theft for rare earth recovery creates distinct exposure patterns in Eastern European markets where REACH-compliant salvage channels remain underdeveloped.
- Natural Disasters:Flood, fire, and weather-related damage. Thermal runaway risk during water ingress events elevates this coverage priority in flood-prone regions of Northern Italy and the Danube basin.
Property Damage anchors current underwriting volumes. Bodily Injury is climbing the fastest as medical cost inflation accelerates.
Customer Type:
Volume concentration and procurement centralization determine policy administration complexity and pricing granularity.
- Fleets:Multi-vehicle commercial operators with centralized procurement. Municipal consolidation in Denmark and corporate electrification mandates across Germany compress policy administration touchpoints while demanding algorithmic multi-vehicle management capabilities.
- Individuals:Private owners of single battery-electric vehicles. Telematics-enabled dynamic pricing adoption concentrates in German and Dutch residential markets where real-time driver behavior monitoring aligns premium with kilometer-specific exposure.
- Businesses:Small and medium enterprises with limited vehicle counts. Repair network access constraints and certified technician scarcity inflate claims uncertainty for underwriters serving this segment in fragmented Southern European markets.
- Government:Public sector procurement at national and municipal levels. EU Green Deal emission benchmarks drive binding decarbonization timelines that accelerate policy issuance through direct insurer relationships bypassing traditional broker networks.
Individuals hold the volume base. Fleet electrification mandates are gaining share fastest among customer categories.
Distribution Channel:
Customer acquisition economics and data capture capabilities separate channels by their alignment with EV policy complexity.
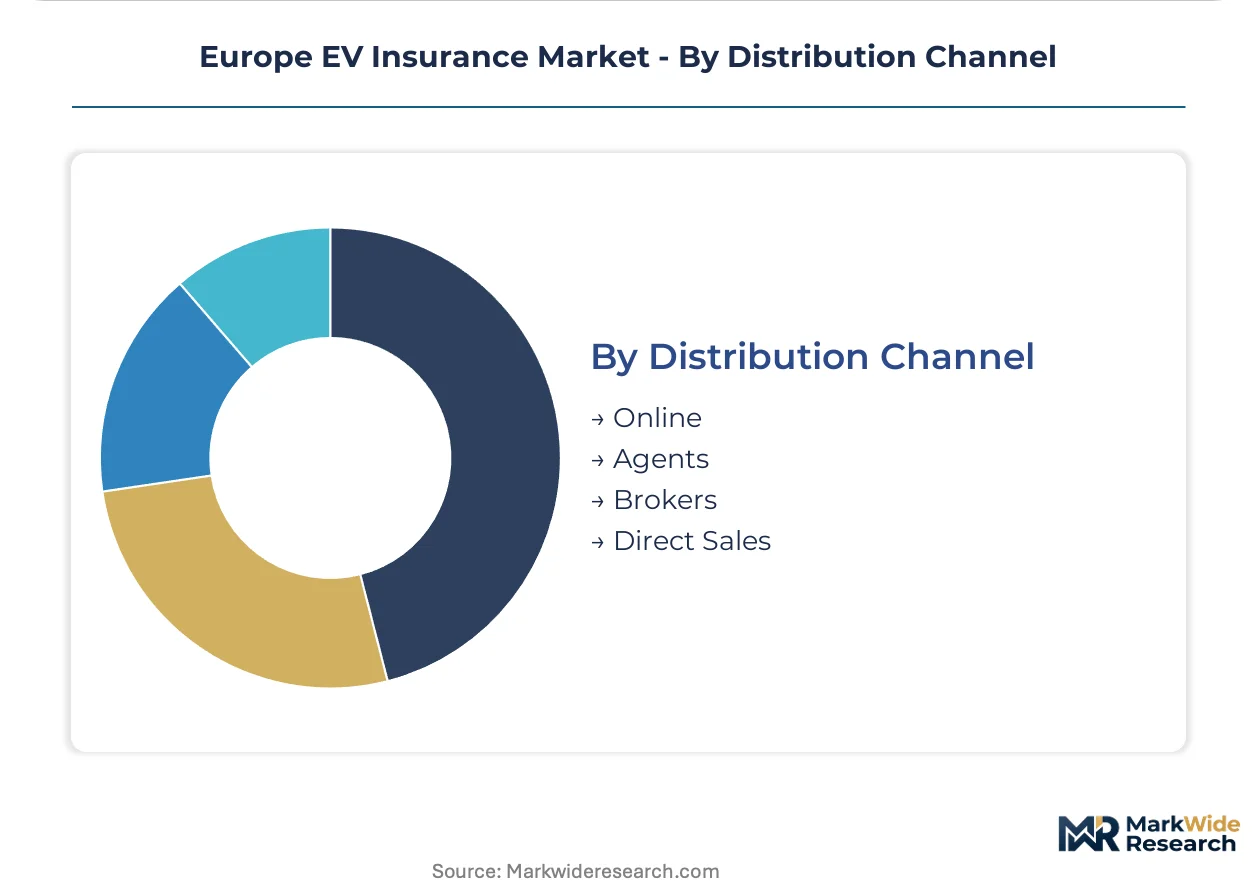
- Online:Direct digital platforms with algorithmic quoting engines. Fleet customer segments adopt this channel fastest where multi-vehicle policy administration demands automated underwriting workflows that broker networks only partially provide.
- Agents:Tied or independent representatives with advisory relationships. Continental European networks are tilting toward digital-first distribution as battery degradation risk assessment complexity outpaces traditional underwriting training.
- Brokers:Intermediaries with multi-carrier market access. Large transport operators in Scandinavia and the Benelux region bypass this channel for direct API connections to insurer quoting engines.
- Direct Sales:Captive channels including OEM companion app integration. Embedded insurance modules that capture real-time driver behavior data at the source reduce customer acquisition costs and bypass traditional distribution entirely.
Agent networks retain the established base. Online platforms show the steepest expansion trajectory as fleet procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's binding vehicle-emission benchmarks are accelerating EV insurance policy issuance unevenly across member states, with national subsidy regimes and fleet electrification timelines creating distinct market maturity gradients.
Germany
Fleet electrification mandates for commercial transport operators are compressing policy administration cycles. The KBA enforces stringent type-approval standards for onboard telematics hardware that insurers must integrate into usage-based products. Munich and Stuttgart host concentrated actuarial units developing battery degradation risk models separate from legacy auto divisions.
United Kingdom
Specialized EV repair networks are shortening claims cycle times in London and Birmingham metropolitan areas. The Financial Conduct Authority's consumer duty rules are reshaping disclosure requirements for battery protection endorsements. Direct digital distribution channels capture increasing share among fleet operators seeking algorithmic multi-vehicle administration.
France
Comprehensive coverage mandates for battery protection are concentrating premium income in jurisdictions with binding EV warranty requirements. ANSM and national insurance supervisors coordinate pharmacovigilance-adjacent frameworks for high-voltage system risk disclosure. The Lyon-Grenoble corridor clusters emerging telematics infrastructure providers serving continental insurers.
Netherlands
Municipal fleet consolidation in Amsterdam and Rotterdam has halved policy administration touchpoints while demanding algorithmic management capabilities. REACH compliance obligations for battery materials are cascading into salvage valuation methodologies that total-loss coverage must address. Telematics-enabled dynamic pricing adoption concentrates among residential EV owners in Randstad urban cores.
Poland
Underpenetrated commercial EV adoption relative to Western Europe offers positioning for insurers building algorithmic multi-vehicle platforms. National transpositions of EU AI Act provisions are creating compliant frameworks for automated claims adjudication. Warsaw and Krakow industrial zones concentrate emerging fleet electrification programs driven by logistics operator decarbonization commitments.
Europe EV Insurance Market Competitive Landscape
On the supply side, the industry is consolidating around multi-national carriers with captive telematics infrastructure and specialized repair networks. Three strategic archetypes dominate: integrated insurers with proprietary data-capture platforms, legacy carriers retrofitting EV-specific endorsements onto existing auto portfolios, and insurtech specialists targeting fleet algorithmic administration. Competitive moves center on OEM companion app integration partnerships and multi-vehicle policy administration platform development.
Among UK-based insurers, Direct Line Insurance Group plc and Admiral Group plc occupy positions emphasizing specialized repair network access and direct digital distribution. German carriers Allianz SE and Zurich Insurance Group exemplify the integrated archetype through captive telematics infrastructure. France's AXA represents embedded insurance modules capturing driver behavior data at the source through OEM partnerships.
| Leading Market Players |
|---|
| Aviva plc |
| Direct Line Insurance Group plc |
| Allianz SE |
| MAPFRE |
| Admiral Group plc |
| AXA |
| Esure Group plc |
| Zego |
| Zurich Insurance Group |
| Others |
Value Network & Pricing Analysis
Munich and Stuttgart's concentrated actuarial infrastructure shapes downstream pricing power for battery degradation risk models across continental Europe. German carriers leverage captive telematics platforms to extract premium spreads that competitors in fragmented Southern European markets cannot replicate.
Pricing Analysis
Certification level for high-voltage technician credentials creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects repair network access depth and battery protection endorsement scope. Cost compression in economy tiers is intensifying because certified repair capacity scarcity inflates loss-ratio uncertainty. Fleet operators demonstrate lowest price sensitivity due to mandated electrification timelines, while individual owners of mid-range battery-electric models in Italian and Spanish urban markets exhibit highest sensitivity to comprehensive premium loads.
Supply Chain Analysis
Contract manufacturing concentration for telematics hardware rests with specialized electronics manufacturing service providers clustered in Germany, the Netherlands, and Taiwan. Raw material dependencies center on lithium-ion cell supply from South Korea and Japan, rare earth elements for battery recovery, and semiconductor components for onboard data-capture devices. Single-source vulnerability in CE-marked telematics modules creates exposure to regulatory re-certification delays. Distribution runs through direct API connections to fleet procurement platforms and OEM companion app integrations that bypass traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification mandates across Germany, France, and the Netherlands are driving a cyclical recovery in commercial EV policy issuance. Binding decarbonization timelines compress procurement cycles and concentrate volume with algorithmic-ready carriers.
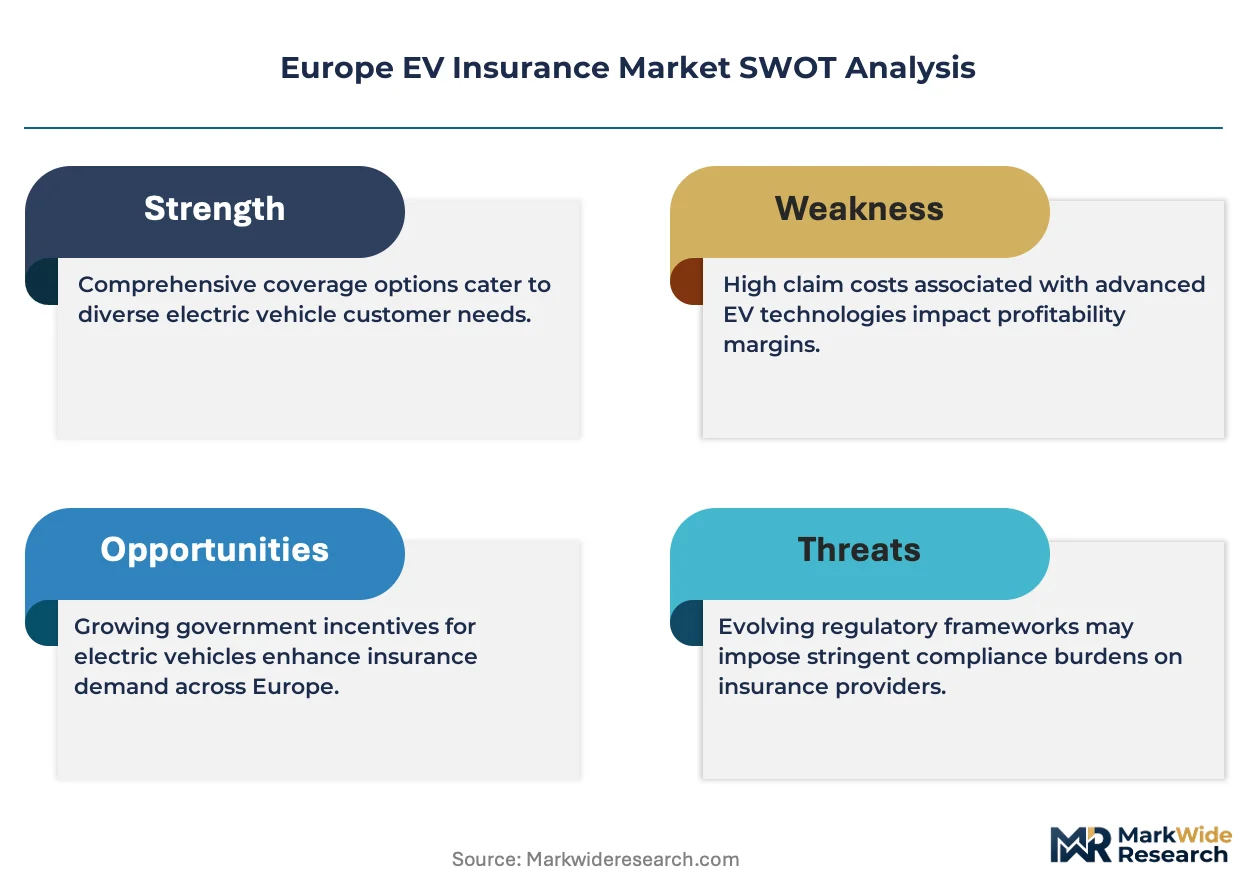
For Market Incumbents: Insulate portfolio profitability by consolidating battery-risk modeling functions into specialized actuarial units separate from legacy auto divisions. Invest in captive telematics infrastructure to maintain pricing granularity against insurtech specialists. EIOPA's climate-transition stress tests threaten capital diversion toward compliance buffers unless reserve recalibrations are anticipated. For New Entrants and Emerging Players: Build out algorithmic multi-vehicle administration platforms targeting Poland and Eastern European fleet markets where commercial EV adoption remains underpenetrated relative to Western Europe. Municipal electrification programs in Warsaw and Krakow industrial zones offer first-mover positioning. Go-to-market through direct API connections bypasses broker infrastructure that legacy carriers depend upon. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated insurers with proprietary data-capture platforms over legacy carriers retrofitting EV endorsements onto existing portfolios. Long-term viability hinges on OEM companion app integration partnerships that lock in driver behavior data at the source. Monitor national transpositions of the EU AI Act for compliant automated claims adjudication frameworks as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Companion App Integration | Embedded insurance modules capture real-time driver behavior data at the source, reducing acquisition costs. |
| Algorithmic Multi-Vehicle Platform Development | Fleet procurement centralization in Denmark and the Netherlands demands automated policy administration capabilities. |
| Specialized EV Repair Network Expansion | Direct Line Insurance Group plc's UK repair network compression of claims cycle times creates service differentiation. |
| Telematics Infrastructure Investment | Allianz SE's captive data-capture platforms enable battery degradation risk pricing granularity competitors cannot match. |
| EU AI Act Compliance Infrastructure | Early algorithmic claims adjudication platform investment rewards carriers with operational cost advantages. |
Research Methodology
Desk research of regulatory filings from EIOPA and national insurance supervisors, vehicle registration databases, and CE marking documentation preceded structured interviews with fleet procurement directors, actuarial unit heads, telematics platform engineers, and high-voltage repair network managers. Secondary validation drew from EU Green Deal implementation trackers, REACH compliance databases, and insurer portfolio disclosure reports. Bottom-up policy issuance modeling and top-down market sizing triangulated volume estimates across the analysis window.
Assumptions around fleet electrification mandate adherence rates, battery degradation curve trajectories, and telematics adoption velocities were held fixed while stress-testing sensitivity to regulatory timeline acceleration and repair capacity expansion scenarios. Segmentation dimensions modeled encompass product type, coverage scope, customer category, and distribution channel, with regional regulatory cluster as an additional insurance-specific dimension. CAGRs were derived from logistic diffusion curves fitted to historical EV registration penetration and projected policy attachment rates.
Stress conditions across EIOPA reserve recalibration stringency, certified repair capacity growth, and GDPR interpretation variance for telematics data pooling were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including battery state-of-health verification standardization delays and cross-border data governance fragmentation. Quarterly review of fleet electrification mandate compliance rates and national AI Act transposition progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Travel Insurance Market
Insurance
Djibouti Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Insurance Protection Products Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
India Health Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Europe Car Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Horse Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
Spain Group Health Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Event Insurance Market
Insurance
United States Dental Insurance Market