
 Electric Car Charging Pile Market | 2026-2036
Electric Car Charging Pile Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Car Charging Pile Market Insights
Buyer concentration is shifting as corporate fleets and real estate developers displace individual consumers as the dominant procurement channel for charging infrastructure. Tesla leverages its Supercharger network to anchor high-throughway corridor deployment across North America. Siemens competes on grid-integration software that manages load balancing for multi-point installations. BYD sustains manufacturing scale advantages through captive battery supply and in-house production of power electronics.
An electric car charging pile is a fixed electrical supply unit that delivers controlled AC or DC power to battery electric vehicles, typically incorporating power conversion modules rated from 7 kW residential units to 350 kW ultra-fast systems with liquid-cooled cables. Its primary commercial purpose is to replenish vehicle energy stores while enabling grid services such as demand response and vehicle-to-grid power flow. DC Fast Charger installations command premium capital allocation due to highway corridor priority and fleet turnaround requirements. Workplace Charging represents an emerging margin pool as employers bundle charging with parking assets to attract talent and meet carbon commitments. Wireless Charger deployment remains nascent, constrained by interoperability gaps and higher unit economics relative to conductive alternatives.
The US Department of Transportation, the EU through its Alternative Fuels Infrastructure Regulation, and China's National Development and Reform Commission each mandate minimum charging density targets along transport corridors and within urban cores. These frameworks shape product standards by prescribing connector compatibility, payment interoperability, and minimum power output thresholds that equipment must satisfy for public funding eligibility. Stakeholders must monitor evolving grid connection codes and utility rate structures, as these will determine site economics more decisively than hardware cost curves alone.
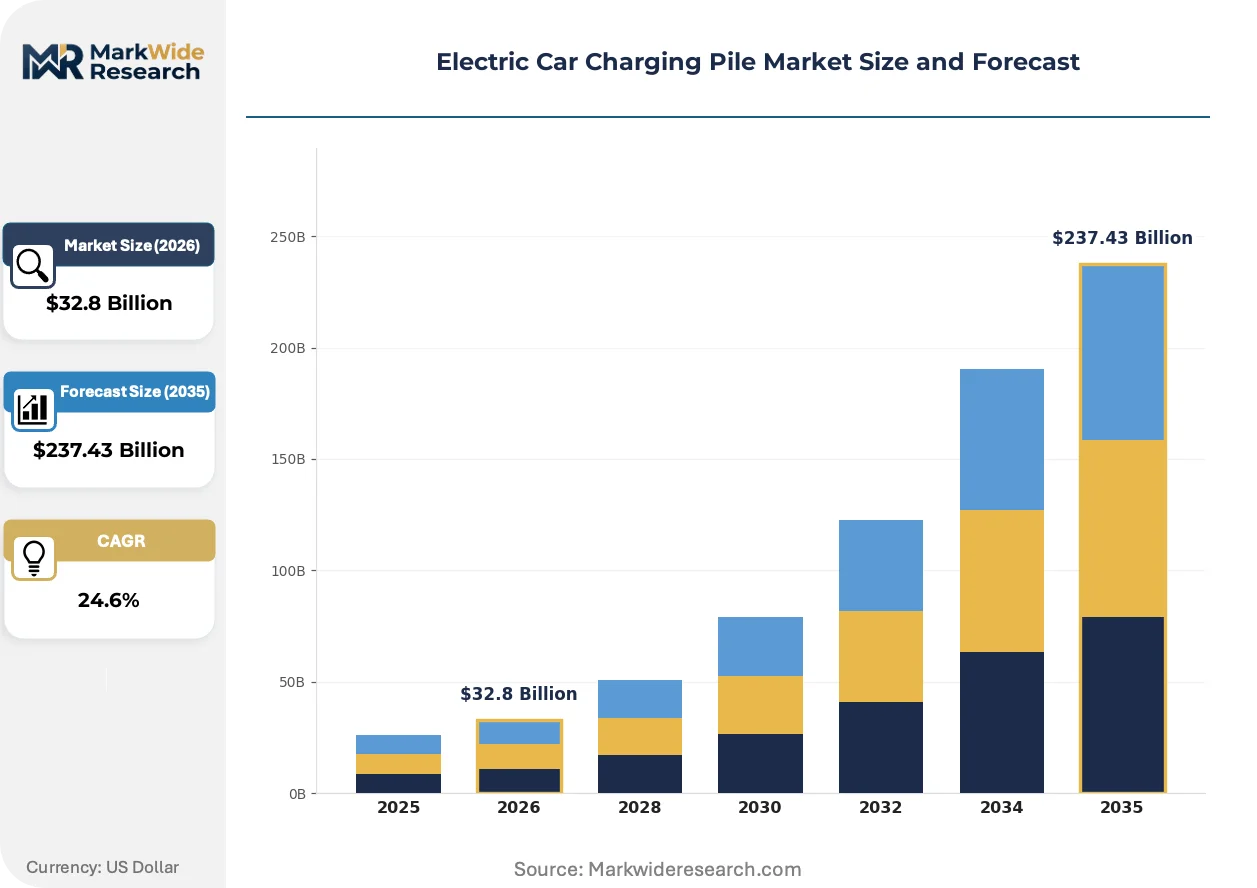
Market Dynamics
Fleet electrification mandates are compressing procurement cycles for high-power charging infrastructure, forcing equipment vendors to accelerate power density roadmaps and service bundling capabilities to capture multi-year supply contracts.
Growth Catalysts
- AFIR corridor mandates:Europe's Alternative Fuels Infrastructure Regulation requires charging stations every 60 kilometers along core transport networks, compelling highway operators to deploy 150 kW+ systems ahead of vehicle fleet turnover.
- China's dual carbon goals:The National Development and Reform Commission has embedded charging infrastructure targets into provincial emissions accountability frameworks, directing state-owned utilities to prioritize grid interconnection approvals for public charging clusters.
- Lithium iron phosphate chemistry:Battery pack cost reductions are enabling commercial vehicle OEMs to offer competitive total cost of ownership, expanding addressable fleet demand for depot charging hardware.
Market Restraints
- Copper and silicon carbide supply concentration:Power electronics manufacturing depends on processing capacity concentrated in China, exposing non-Chinese charging system integrators to input cost volatility and quota restrictions.
- Grid connection queue delays:Distribution network reinforcement timelines in Germany and California extend commercial commissioning by 12-24 months, eroding project returns for site hosts.
- Interoperability certification fragmentation:Multiple competing communication protocols (ISO 15118, OCPP 2.0.1, proprietary variants) force redundant hardware testing, inflating R&D overhead for multi-market vendors.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive technology manufacturing are attracting charging equipment assembly investments to serve domestic electric two-wheeler and three-wheeler electrification.
- Vehicle-to-grid aggregation:Bidirectional charging hardware paired with virtual power plant software creates new revenue streams from frequency regulation services in deregulated electricity markets.
- Workplace charging as employee benefit:Real estate developers in California are pre-wiring parking structures to capture corporate tenants seeking Scope 3 emissions reductions through commuting electrification.
Industry Challenges
- Power electronics engineering talent scarcity:Design of liquid-cooled cable systems and wide bandgap semiconductor applications requires specialized expertise concentrated among automotive inverter veterans.
- Utility rate structure misalignment:Demand charge mechanisms in US commercial electricity tariffs penalize high-power charging peaks, complicating site economic models for fleet depot installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Car Charging Pile Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $237.43 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: AC Charger, DC Fast Charger, Wireless Charger, Portable Charger, Ultra-Fast Charger Connector Standard: Type 1, Type 2, CHAdeMO, CCS, GB/T Application: Public Stations, Fleet Charging, Residential Charging, Workplace Charging, Commercial Complexes End User: EV Manufacturers, Charging Operators, Corporate Fleets, Real Estate Developers, Government Agencies |
| Companies Covered | Tesla, ABB, ChargePoint, BYD, Siemens, EVBox, BP Pulse, Shell Recharge, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Car Charging Pile Market Trends and Innovations
Hardware architectures are fragmenting into interchangeable subsystems, enabling faster upgrade cycles and reducing stranded asset risk for charging network operators managing decade-long infrastructure commitments.
Power conversion hardware is modularizing into swappable 25-50 kW building blocks that operators can field-upgrade without full cabinet replacement. Fleet managers in Germany are specifying these configurations to match charging capacity to evolving battery pack sizes. This architecture is compressing capital deployment risk by deferring peak power investments until vehicle duty cycles justify the expenditure.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in liquid-cooled charging cables, accelerating adoption of CO2-based thermal management systems. Equipment vendors are redesigning cooling loops to maintain 350 kW output under restricted refrigerant quotas. High-throughput corridor operators in France and the Netherlands face the most acute compliance timelines for retrofitting existing installations.
Asset-light service contracts are displacing direct equipment purchases among multi-site fleet operators seeking to offload uptime accountability. Third-party charge point operators in California are capturing long-term service agreements by guaranteeing availability metrics and absorbing maintenance capex. This model concentrates most visibly among last-mile delivery consolidators operating 500+ vehicle depots across the state.
Electric Car Charging Pile Market Segmentation
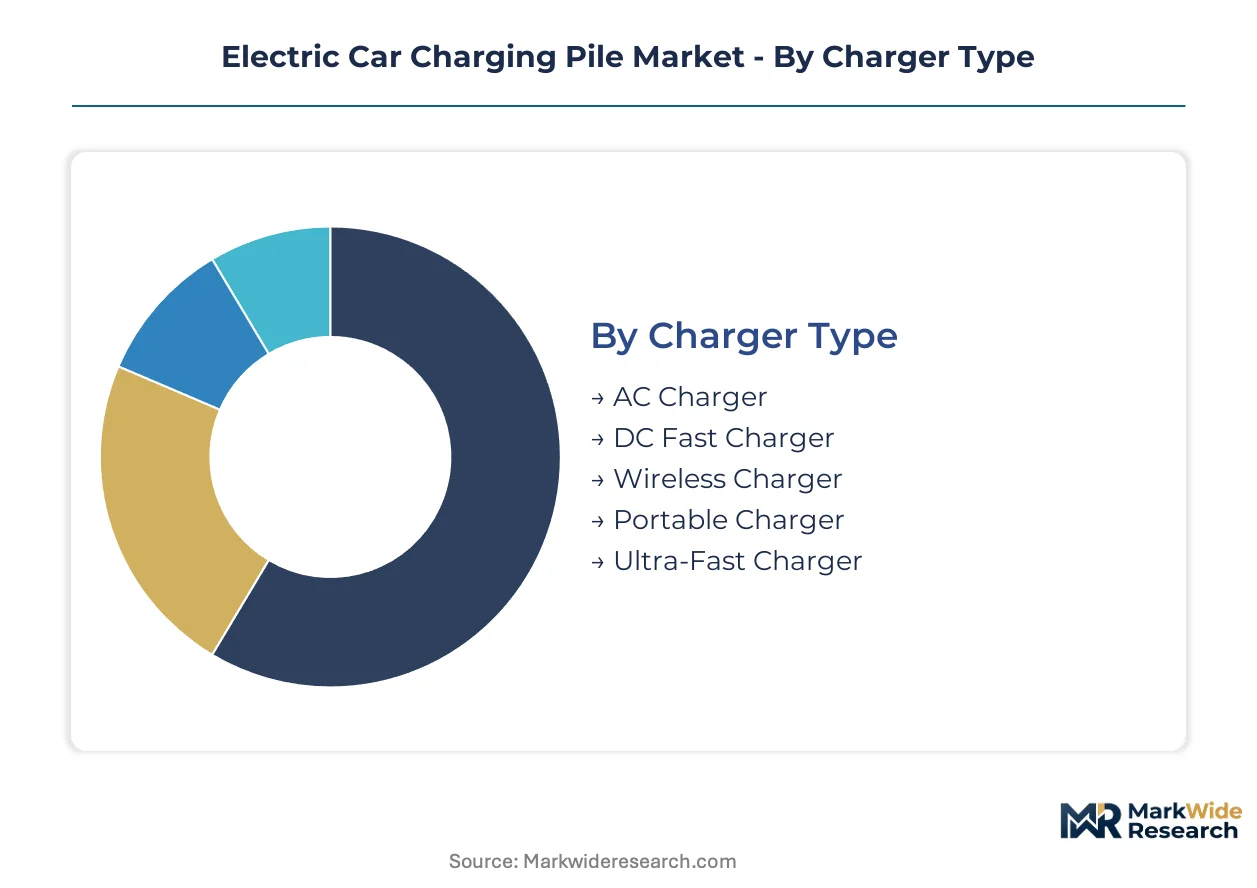
Charging pile segmentation reveals divergent capital requirements and payback profiles across deployment contexts. Equipment vendors must align product roadmaps with distinct procurement rhythms and technical specifications governing each category.
Charger Type:
Capital intensity escalates sharply with power output, creating tiered barriers to entry across manufacturer portfolios.
- AC Charger:Single-phase and three-phase units deliver 7-22 kW through onboard vehicle rectifiers. Residential and workplace installations in Germany concentrate procurement volume as landlords electrify parking assets under building energy codes.
- DC Fast Charger:Offboard power conversion enables 50-150 kW direct current delivery, bypassing vehicle inverter limitations. Highway corridor operators in California and France prioritize these units to capture transit traffic and comply with AFIR density mandates.
- Wireless Charger:Inductive pad systems transfer power across air gaps at efficiencies below conductive alternatives. Deployment concentrates in premium residential and autonomous vehicle test fleets.
- Portable Charger:Mobile emergency units provide 3-7 kW through standard outlets. Demand tracks early EV adoption markets lacking fixed infrastructure.
- Ultra-Fast Charger:Liquid-cooled 350 kW systems enable sub-20 minute replenishment for commercial vehicle packs. Fleet operators in China specify these for depot installations serving long-haul electric trucks.
Mature deployment sits with AC Chargers. Newer deployment is concentrated in Ultra-Fast Charger configurations.
Connector Standard:
Regional regulatory choices have frozen connector diversity, forcing multi-standard hardware strategies for cross-border equipment vendors.
- Type 1:Single-phase North American connector rated to 19.2 kW. Japanese and US markets sustain demand through legacy vehicle fleet compatibility requirements.
- Type 2:Three-phase European standard supporting 43 kW AC and 150 kW DC through CCS Combo 2. German and French highway networks mandate this interface for public funding eligibility.
- CHAdeMO:Japanese DC standard offering bidirectional power flow capabilities. Nissan and Mitsubishi vehicle owners in Japan and select European markets drive residual demand.
- CCS:Combined Charging System integrates AC and DC pins into unified inlet. US and European OEMs have standardized on this for new vehicle platforms.
- GB/T:Chinese national standard specifying unique DC pin configuration. Domestic manufacturers BYD and NIO anchor procurement volume through captive vehicle production.
Type 2 and CCS dominate European and North American new installations. GB/T commands absolute share within China.
Application:
Site economics vary dramatically by dwell time and utilization predictability, shaping hardware specification and service bundling.
- Public Stations:High-visibility urban and highway locations with 24-hour access requirements. Operators in California and the Netherlands prioritize these for brand presence and subsidy capture.
- Fleet Charging:Dedicated depot infrastructure serving scheduled vehicle return patterns. Logistics operators in Germany specify high-power clusters to minimize asset downtime.
- Residential Charging:Single-family and multi-unit dwelling installations with overnight dwell windows. Chinese state-owned utilities streamline grid connections for these low-voltage applications.
- Workplace Charging:Employer-subsidized parking integration attracting talent and Scope 3 compliance. Real estate developers in California pre-wire structures to capture corporate tenant demand.
- Commercial Complexes:Retail and hospitality locations monetizing dwell time through charging services. Shopping mall operators in France deploy these to extend customer visit duration.
Residential Charging holds the deepest installed base. Workplace Charging is climbing the fastest as employer benefit programs expand.
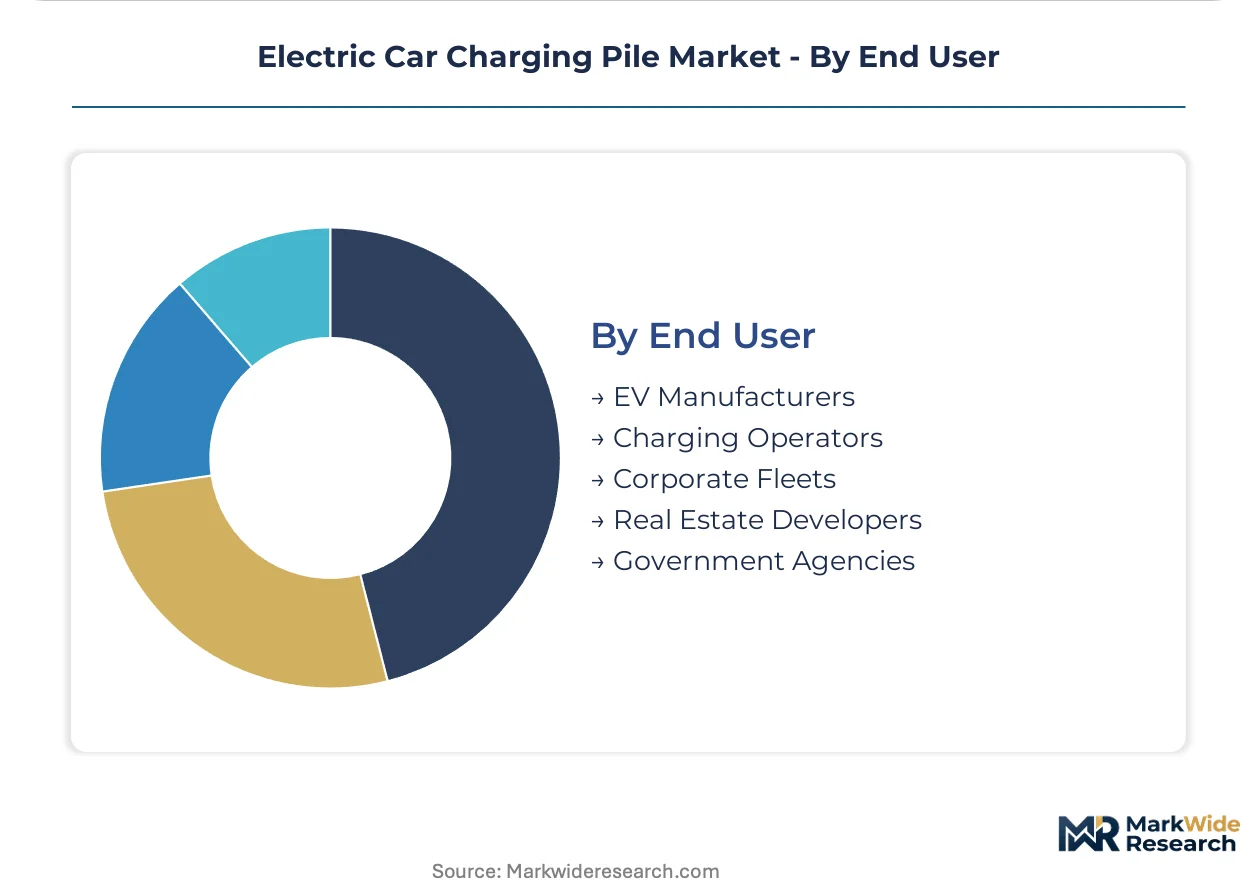
End User:
Procurement authority is consolidating toward entities with multi-site deployment capacity and long-dated infrastructure commitments.
- EV Manufacturers:Automakers bundling charging access with vehicle sales to reduce purchase friction. Tesla's Supercharger network anchors this vertical integration strategy in North America.
- Charging Operators:Specialized firms aggregating capital for network buildout and uptime accountability. Charge point operators in California capture fleet service contracts spanning 500+ vehicle depots.
- Corporate Fleets:Logistics and delivery companies electrifying under mandate pressure and TCO optimization. Last-mile operators in Germany compress procurement cycles for high-power depot hardware.
- Real Estate Developers:Property owners pre-wiring parking structures to meet tenant carbon commitments and building codes. California developers lead this segment through state-level emissions accountability frameworks.
- Government Agencies:Municipal and national entities deploying public infrastructure under policy directive. China's National Development and Reform Commission directs state-owned utility prioritization of interconnection approvals.
EV Manufacturers pioneered vertical network control. Charging Operators are gaining share fastest as asset-light service models displace direct purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in jurisdictions where vehicle electrification mandates intersect with utility-scale grid investment programs. China, Germany, and the United States anchor procurement volume through distinct regulatory mechanisms and infrastructure deployment timelines.
China
Provincial emissions accountability frameworks embedded under dual carbon goals direct state-owned utilities to accelerate interconnection approvals for public charging clusters. The National Development and Reform Commission mandates charging density targets within urban cores and along transport corridors. Yangtze River Delta municipalities including Shanghai and Suzhou host the densest ultra-fast charger deployment serving long-haul electric truck depots.
Germany
Highway corridor operators compress procurement cycles for 150 kW+ systems to comply with AFIR density mandates requiring stations every 60 kilometers. The KBA enforces connector compatibility and payment interoperability standards for public funding eligibility. Bavaria and North Rhine-Westphalia concentrate manufacturing of modular power conversion hardware for fleet depot installations.
United States
California's building energy codes and emissions accountability frameworks drive real estate developers to pre-wire parking structures for workplace charging. The Department of Transportation administers corridor infrastructure grants prescribing minimum power output thresholds. Los Angeles and San Francisco Bay Area metropolitan clusters lead in fleet depot electrification serving last-mile delivery consolidators.
France
Shopping mall operators deploy charging assets to extend customer visit duration and monetize dwell time. The F-Gas Regulation imposes acute compliance timelines for retrofitting existing liquid-cooled installations with CO2-based thermal management. Île-de-France and Provence-Alpes-Côte d'Azur host high-throughput corridor operators facing the most immediate refrigerant quota restrictions.
India
Production-linked incentives for advanced automotive technology manufacturing attract charging equipment assembly investments serving electric two-wheeler and three-wheeler electrification. The Bureau of Indian Standards develops connector compatibility protocols for domestic market interoperability. Maharashtra and Gujarat concentrate initial deployment around automotive manufacturing hubs and port logistics corridors.
Electric Car Charging Pile Market Competitive Landscape
Chinese producers anchor one tier through captive battery supply and in-house power electronics manufacturing; European and North American specialists hold differentiated positions in grid-integration software and highway corridor deployment. The vendor structure fragments across three strategic tiers: integrated automakers operating proprietary networks, dedicated charging operators aggregating capital for multi-site buildout, and industrial conglomerates supplying hardware under utility-scale contracts. Dominant competitive moves include backward integration into semiconductor sourcing and asset-light service contracting that offloads uptime accountability to third-party operators.
Within the integrated automaker tier, Tesla exemplifies vertical network control through corridor-focused deployment. Among industrial conglomerates, ABB and Siemens occupy positions spanning power conversion hardware and grid management software. These three names represent distinct archetypes: proprietary network verticalization, heavy electrical engineering heritage, and grid-integration specialization respectively.
| Leading Market Players |
|---|
| Tesla |
| ABB |
| ChargePoint |
| BYD |
| Siemens |
| EVBox |
| BP Pulse |
| Shell Recharge |
| Eaton |
| Others |
Pricing and Supply Chain Analysis
Performance-tier bifurcation between liquid-cooled ultra-fast systems and commodity AC hardware manifests in divergent margin structures and sourcing footprints across the value chain. Premium 350 kW systems command hardware margins anchored to silicon carbide module costs and refrigerant compliance investments, while residential 7-22 kW units compete on copper winding efficiency and logistics scale.
Pricing Analysis
Volume-mix splits between hardware-only transactions and bundled service contracts reshape profitability profiles across manufacturer tiers. Three-tier pricing structure across premium liquid-cooled, standard DC fast, and economy AC levels reflects certification grade differentiation and after-sales uptime guarantees. Pricing pressure stems from silicon carbide supply quotas constraining power electronics output. Fleet operators exhibit lowest price sensitivity due to TCO-driven procurement mandates, while residential installers face acute cost compression from building code standardization.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's dual carbon accountability frameworks are rerouting component sourcing toward in-country assembly partnerships. Manufacturing concentration centers on China for power electronics, Germany for precision cooling systems, and South Korea for wide bandgap semiconductors. Critical dependencies include copper busbars, liquid-cooled cable assemblies, and refrigerant-grade CO2. Single-source vulnerability sits with silicon carbide wafer processing. Distribution runs through utility-scale EPC contractors for fleet depot projects and electrical wholesalers for residential channel fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a technology-transition phase where wide bandgap semiconductors displace silicon-based power conversion architectures, compressing upgrade cycles and stranding legacy inventory.
For Market Incumbents: Cement grid-integration software differentiation through API-layer investments that lock in utility-scale fleet contracts. Deepen backward integration into semiconductor sourcing to insulate margin structures from silicon carbide quota volatility. Counter the threat of modular hardware startups by pre-empting swappable power block specifications in procurement standards.
For New Entrants and Emerging Players: Capture workplace charging infrastructure as the most penetrable deployment context, where real estate developer relationships and employer benefit bundling lower customer acquisition costs relative to highway corridor saturation. Target California and Germany sub-markets where building energy codes mandate pre-wiring. Lead with asset-light service contracting that absorbs uptime accountability rather than capital-heavy hardware sales.
For Investors and Strategic Acquirers: Re-rating potential sits with charge point operators possessing virtual power plant software capabilities given vehicle-to-grid regulatory enablement. Long-term viability favors entities with decade-long fleet service contracts spanning 500-plus vehicle depots. Watch F-Gas Regulation compliance timelines as the inflection signal for thermal management technology refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Long-term offtake contracts with wafer processors insulate power electronics margins from quota restrictions. |
| CO2 Thermal System Certification | F-Gas Regulation compliance unlocks 350 kW corridor deployment eligibility in France and Netherlands markets. |
| Virtual Power Plant Integration | Bidirectional charging software enables frequency regulation revenue streams in deregulated electricity markets. |
| Modular Power Block Architecture | Swappable 25-50 kW units defer capital deployment until fleet duty cycles justify peak power investment. |
| Workplace Charging Pre-Wiring Partnership | Real estate developer alliances capture corporate tenant demand under California building energy codes. |
Research Methodology
Independent corroboration across charging network operators, utility interconnection planners, and fleet procurement directors underwrites the qualitative findings. Primary fieldwork encompassed equipment vendor sales executives, power electronics engineers, and commercial real estate development leads. Secondary validation drew from NHTSA corridor infrastructure grant disclosures, FERC interconnection queue filings, EU AFIR implementation progress reports, and China's NDRC provincial emissions accountability frameworks. Bottom-up unit deployment tallies triangulated against top-down infrastructure investment flow estimates.
Comparable-period anchoring to historical charger installation trajectories informed the projection horizon calibration. The analytical framework modeled segmentation across charger type, connector standard, application context, and end-user procurement authority. CAGRs derived from power density adoption curves, fleet electrification mandate timelines, and grid reinforcement investment patterns. Industry-specific inputs included silicon carbide supply expansion schedules and refrigerant phase-down compliance deadlines.
The model holds under sustained policy incentive continuity and grid interconnection approval velocity; deviation in utility rate structure reform or semiconductor export controls would shift deployment trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Asia-Pacific Portable EV Charger Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Charging As a Service Market
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market