
 Global Automotive Charging System Market | 2026-2036
Global Automotive Charging System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Charging System Market Intelligence
The sourcing model for charger sub-assemblies is pivoting from outsourced manufacturing towards greater in-house production control by system integrators. Tesla Motors, Inc. leverages its captive supply of components to control both vehicle and charging technology. ABB Ltd. specializes in high-power DC fast-charging solutions for commercial and public infrastructure projects. Schneider Electric competes through its extensive portfolio of residential and commercial Level 2 charging hardware.
An automotive charging system is an assembly of hardware and software that transfers electrical energy to an electric vehicle's battery pack. These systems manage power conversion from AC or DC sources, operating at power levels from 3.7 kW for residential units up to 350 kW for ultra-fast chargers. DC chargers represent the fastest-growing product type, driven by demand for rapid public charging. Within technology, smart charging and bi-directional charging capabilities are becoming key differentiators for both fleet operators and residential users.
Product design and market access are shaped by a complex web of safety standards and interoperability protocols. These include NHTSA safety guidelines in the United States, mandatory CE marking for market entry in Europe, and China's specific GB standards for charging connectors. Future competitive advantage will hinge on the ability to engineer systems compliant with evolving regional standards while advancing bi-directional charging capabilities.
Market Dynamics
The market's core tension arises from the need for globally interoperable charging protocols conflicting with regionally specific safety standards and grid requirements. This dynamic forces manufacturers to engineer modular systems adaptable to diverse regulatory and electrical environments, shaping both product design and market access strategies.
Growth Catalysts
- Fleet Electrification Mandates:Regulations like the EU Green Deal force commercial fleet operators to adopt electric vehicles, creating a direct and large-scale demand for depot and public charging infrastructure.
- State-Sponsored Infrastructure:China's national policy for a rapid public charging network expansion creates massive, state-backed demand for DC fast-charging hardware, concentrating a significant portion of global volume growth.
- Smart Charging Adoption:Fleet operators adopt smart charging to optimize energy costs and manage vehicle availability, pulling demand for advanced software-enabled hardware that integrates with grid management systems.
Market Restraints
- Grid Capacity Bottlenecks:Insufficient local grid capacity often delays or increases the cost of deploying high-power DC fast-charging stations, constraining network expansion in many regions.
- Protocol Fragmentation:Competing standards like CCS, CHAdeMO, and GB/T create interoperability challenges, complicating hardware design and hindering a seamless user experience across geographies.
- High Installation Costs:The substantial capital required for site preparation and utility upgrades for DC fast chargers remains a significant barrier for potential site hosts.
Strategic Opportunities
- Bi-Directional Charging (V2G):Developing vehicle-to-grid capabilities creates a new value stream, enabling EV owners and fleets to sell energy back to the grid.
- Heavy-Duty Applications:Designing high-power charging systems for electric trucks and buses opens a nascent, high-value industrial segment.
- Emerging Market Entry:Infrastructure build-out in underpenetrated EV markets in Southeast Asia and Latin America represents a significant greenfield opportunity.
Industry Challenges
- Regulatory Compliance Complexity:Navigating the intricate and divergent safety standards and certification processes, including NHTSA guidelines, CE marking, and China's GB standards, is a major operational hurdle.
- Software and System Integration:Ensuring seamless software interoperability between charging hardware, vehicle onboard chargers, and network management platforms remains a persistent technical challenge for developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Charging System Market |
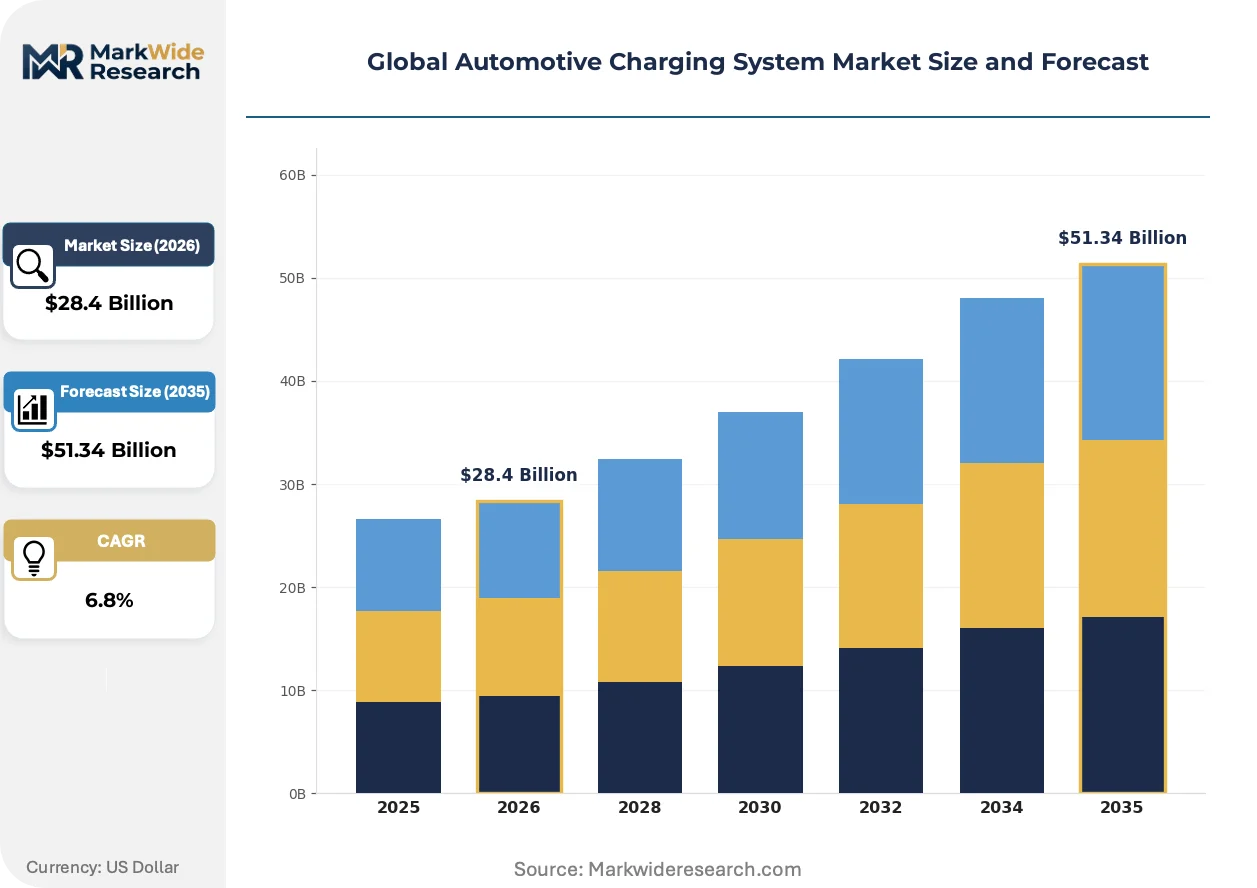
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Charger, DC Charger, Wireless Charger, Portable Charger End User: Individual Consumers, Fleet Operators, Charging Station Providers, OEMs Installation: Residential, Commercial, Public, Multi-family Technology: Fast Charging, Level 2 Charging, Smart Charging, Bi-directional Charging |
| Companies Covered | Delta Electronics, Inc., Schneider Electric, Robert Bosch GmbH, General Electric Company, AeroVironment Inc., ABB Ltd., Tesla Motors, Inc., Delphi Technologies, Evatran Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Charging System Market Strategic Shifts & Innovations
The market is shifting from providing simple energy replenishment to developing intelligent, grid-aware energy transfer systems. This evolution prioritizes software-defined functionality, network optimization, and integration with broader energy ecosystems over standalone hardware performance.
Smart charging technology allows for dynamic management of charging sessions based on grid conditions, electricity pricing, and user preferences. Fleet operators and residential users are adopting this to reduce operational costs and avoid peak demand charges. This core functionality is expanding into a prerequisite for participation in utility demand-response programs and vehicle-to-grid energy services.
Regulatory frameworks like the United States' Inflation Reduction Act (IRA) are directly influencing investment decisions and supply chain geography. The act's provisions for domestic manufacturing credits incentivize onshore production of charging hardware and components. Consequently, commercial fleet operators and charging network providers are aligning procurement strategies to maximize these federal incentives.
A demand-side shift from one-time hardware sales to recurring revenue models like Charging-as-a-Service (CaaS) is gaining traction. This model, which bundles hardware, software, and maintenance into a subscription, is displacing traditional capital expenditure procurement. This trend is most prominent among commercial fleet operators and multi-unit residential properties in North America and Europe.
Global Automotive Charging System Market Segmentation
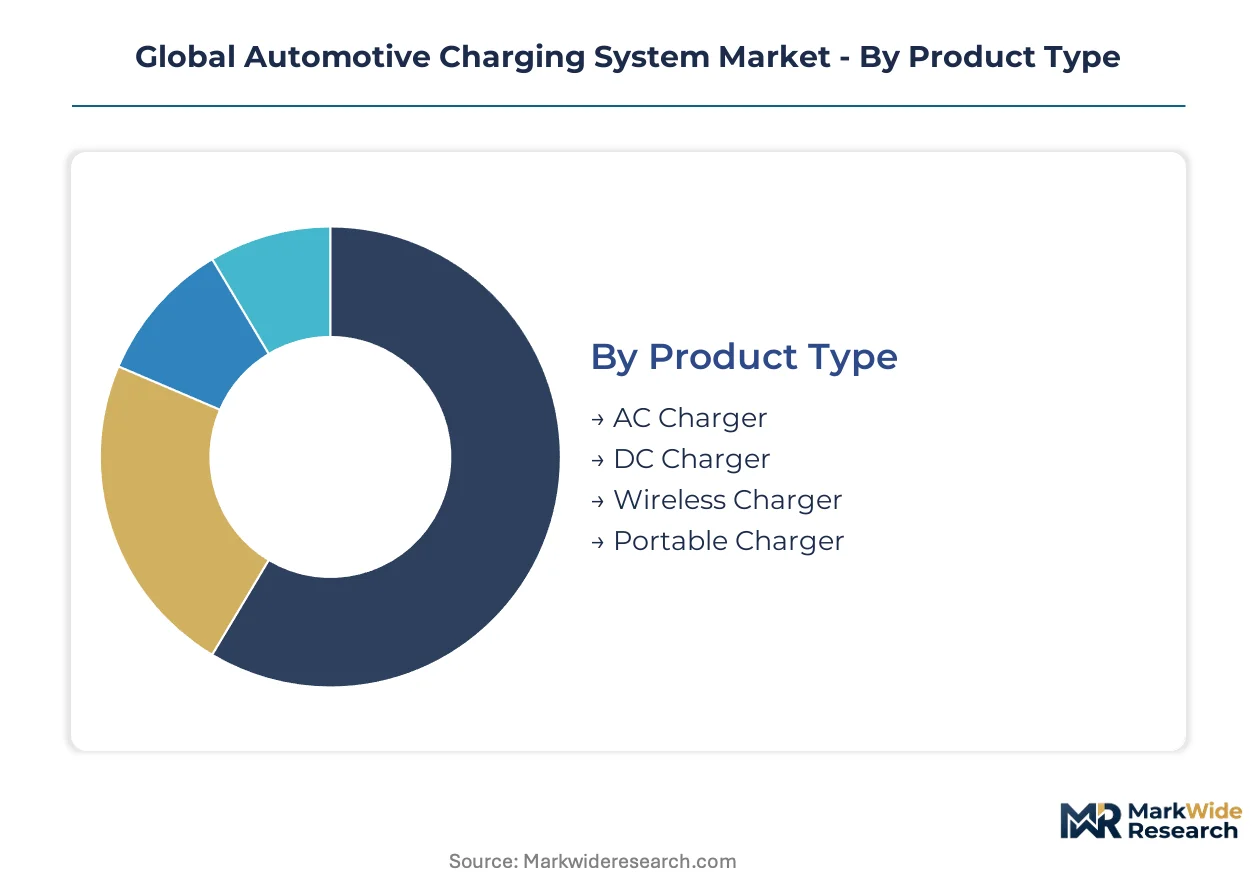
Understanding the varied segments within the global automotive charging system market is crucial for identifying targeted growth strategies and product development priorities. Each segment presents distinct technical requirements, user behaviors, and regulatory landscapes that manufacturers must address.
Product Type:
The supply chain for automotive charging systems is heavily influenced by the manufacturing complexity and component sourcing for different product types, impacting production gravity.
- AC Charger:These units convert grid AC power to DC power within the vehicle's onboard charger, typically offering slower charging speeds suitable for overnight or workplace use. Demand is widespread among residential users in Germany and the United States, driven by convenience and lower installation costs.
- DC Charger:These systems convert AC power from the grid to DC power for direct transfer to the EV battery, enabling significantly faster charging times than AC units. Demand is concentrating in public charging networks across China, driven by national policy supporting rapid infrastructure expansion.
- Wireless Charger:This technology enables inductive power transfer without physical cables, offering convenience for parking and automated charging scenarios.
- Portable Charger:Compact, mobile charging devices provide emergency or supplemental power, appealing to users seeking flexibility away from fixed infrastructure.
Today's leader: DC Charger. Tomorrow's challenger: Wireless Charger.
End User:
The distinct requirements of various end-user types significantly shape the development and deployment strategies for charging solutions across the market.
- Fleet Operators:These users require robust, high-utilization charging infrastructure for commercial vehicles, often integrating smart charging capabilities for cost optimization and vehicle management. Demand is accelerating from fleet electrification mandates in Europe, compelling companies to upgrade their depots.
- Charging Station Providers:These entities deploy and manage public and semi-public charging networks, focusing on reliability, interoperability, and revenue generation from charging services. Investment is concentrating in regions like the United States, supported by federal incentives for network expansion.
- Individual Consumers:Residential and personal vehicle owners primarily seek convenient and cost-effective charging solutions for home use.
- OEMs:Original Equipment Manufacturers integrate charging solutions directly into their vehicle offerings or develop proprietary charging networks, aiming for ecosystem control.
Fleet operators are driving immediate demand, while OEMs are increasingly integrating charging solutions directly into vehicle platforms.
Installation:
Installation applications dictate specific power requirements and infrastructure investments across the charging ecosystem, influencing deployment patterns.
- Residential:Charging solutions installed at private homes, typically lower power AC units for overnight charging.
- Commercial:Charging infrastructure deployed at workplaces, retail centers, or private depots for employee, customer, or fleet use, often requiring Level 2 or DC fast chargers. Demand from commercial entities in the United States is influenced by tax credits for workplace charging.
- Public:Accessible charging stations located in public spaces, highways, or urban centers, predominantly featuring high-power DC fast chargers to facilitate rapid top-ups. Infrastructure investment concentrates in China, where national policy supports rapid network buildout.
- Multi-family:Charging solutions tailored for apartment buildings and condominiums, addressing shared access and billing complexities.
Public installations are expanding rapidly, with multi-family units representing a growing niche for integrated solutions.
Technology:
The volume of data and power managed by different charging technologies is a primary differentiator in market offerings, influencing competitive positioning.
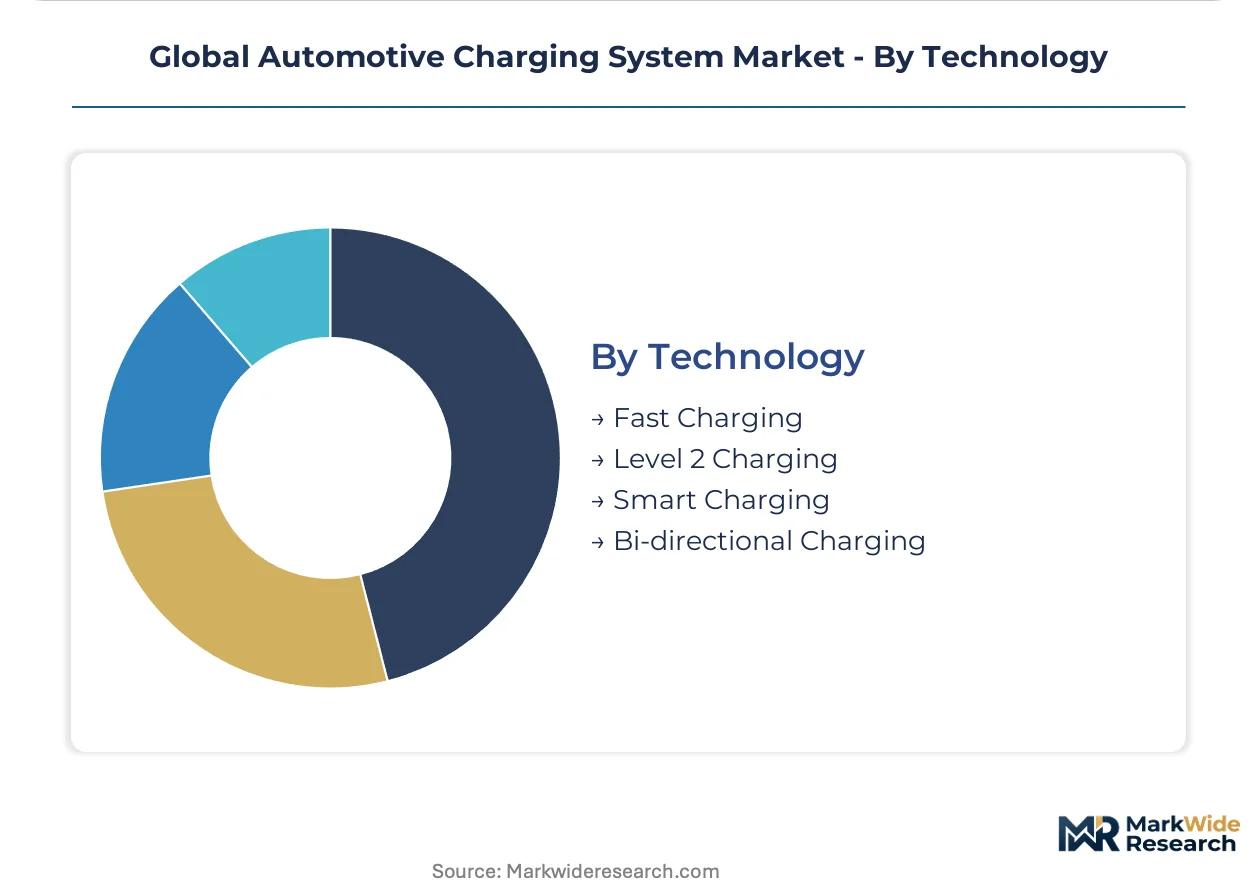
- Fast Charging:Technologies enabling rapid energy transfer to EV batteries, significantly reducing charging times, primarily through high-power DC systems. Demand for fast charging is driven by the expansion of long-distance EV travel and fleet operational requirements.
- Level 2 Charging:Standard AC charging technology offering moderate speeds, suitable for residential, workplace, and public destinations where vehicles are parked for several hours. This technology remains a foundational component of most charging ecosystems.
- Smart Charging:Systems that intelligently manage power delivery based on grid conditions, electricity prices, and user preferences, optimizing energy consumption. Fleet operators in Europe adopt smart charging to reduce operational costs and manage vehicle availability.
- Bi-directional Charging:Technology allowing energy flow both to and from the vehicle battery, enabling vehicle-to-grid (V2G) or vehicle-to-home (V2H) applications. This capability is becoming a key differentiator for both fleet operators and residential users, creating new value streams.
Fast Charging currently dominates adoption, but Bi-directional Charging offers the steepest expansion trajectory for future grid integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rapid buildout of public charging networks drives significant global volume for automotive charging systems. This expansion is complemented by robust demand from fleet electrification mandates in Europe and strategic infrastructure investments in North America. These regional dynamics shape product design and deployment strategies worldwide.
China
China's national policy for a rapid public charging network expansion generates massive demand for DC fast-charging hardware. The country's GB standards for charging connectors dictate specific product design requirements. Infrastructure development concentrates heavily in the Yangtze River Delta region, focusing on high-power charging solutions.
United States
Federal incentives for network expansion stimulate significant investment in public charging infrastructure across the United States. The Inflation Reduction Act (IRA) provisions incentivize onshore production of charging hardware and components. California leads in smart charging adoption, driven by progressive state policies and a high concentration of EV owners.
Germany
Residential users in Germany drive widespread demand for AC chargers, valuing convenience and lower installation costs. Mandatory CE marking ensures compliance for all charging systems entering the European market. The Baden-Württemberg region sees concentrated investment in smart charging solutions for both private and commercial users.
Japan
Japan exhibits demand for advanced charging technologies, including early adoption of the CHAdeMO standard for rapid DC charging. The country's regulatory framework supports the integration of smart charging capabilities. The Tokyo metropolitan area is a hub for innovation in wireless charging and vehicle-to-grid applications.
South Korea
South Korea demonstrates strong demand for integrated charging solutions, driven by aggressive EV adoption targets and OEM initiatives. Government policies promote the expansion of public charging networks and smart grid integration. The Seoul Capital Area is a focal point for developing advanced bi-directional charging technologies.
Global Automotive Charging System Market Key Industry Players
Global majors compete with regional champions across technology specialization and market access strategies. The market exhibits a tiered structure, with established industrial conglomerates alongside specialized EV charging providers. Consolidation is occurring as larger players acquire niche technology firms. Strategic archetypes include integrated ecosystem providers, high-power DC charging specialists, and residential/commercial Level 2 hardware suppliers. Dominant competitive moves involve strategic partnerships for interoperability and significant capacity expansion to meet escalating demand.
Specialists in high-power solutions include ABB Ltd., a global company that anchors commercial and public infrastructure projects. Tesla Motors, Inc. exemplifies the integrated ecosystem approach, controlling both vehicle and charging technology across its captive supply. Schneider Electric, a French multinational corporation, occupies a position as a leading supplier of residential and commercial Level 2 charging hardware. These entities represent distinct approaches to market penetration, from proprietary networks to broad portfolio offerings for diverse end-users.
| Leading Market Players |
|---|
| Delta Electronics, Inc. |
| Schneider Electric |
| Robert Bosch GmbH |
| General Electric Company |
| AeroVironment Inc. |
| ABB Ltd. |
| Tesla Motors, Inc. |
| Delphi Technologies |
| Evatran Group, Inc. |
| Others |
Cost & Logistics Intelligence
The divergence between high-power DC fast-charging solutions and lower-power AC units creates distinct pricing and supply chain configurations. This bifurcation reflects varying infrastructure demands and component sourcing complexities across global regions.
Pricing Analysis
Input cost pass-through for power electronics and grid connection components directly influences final system pricing. The market operates on a hybrid model of project-based pricing for large infrastructure deployments and subscription-tiered models for Charging-as-a-Service. Price differentiation stems from charging power levels and regional certification requirements like CE marking. Cost compression in hardware is intensifying due to increased competition, making individual consumers highly price-sensitive for residential units.
Supply Chain Analysis
Single-source vulnerability sits with specialized power semiconductor manufacturers, particularly those concentrated in East Asia. Geographic supply concentration for critical sub-assemblies is prevalent in China and Taiwan. Key raw material dependencies include rare earth elements for magnetics and specific battery management system components. Regulatory compliance complexity, particularly with GB standards, poses a structural risk for market access. Distribution runs through direct sales to fleet operators and charging network providers, increasingly shifting towards subscription-based service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU Green Deal's fleet electrification mandates driving significant infrastructure investment. These regulations accelerate the transition to electric vehicles, creating sustained demand for advanced charging systems.
For Market Incumbents: Extend high-power DC charging network capabilities through strategic partnerships for interoperability. Invest in software-defined functionality to integrate smart charging with grid management systems, mitigating grid capacity bottlenecks. This proactive approach counters the threat of protocol fragmentation and leverages R&D in bi-directional charging.
For New Entrants and Emerging Players: The United States' Inflation Reduction Act (IRA) opens a window for specialized hardware manufacturers focusing on domestic production. Target underpenetrated segments like multi-family residential units and heavy-duty vehicle applications in emerging markets. A go-to-market angle focusing on modular, standards-compliant systems offered via Charging-as-a-Service (CaaS) models can secure early market share.
For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary technology offers clear differentiation in smart charging and bi-directional capabilities. Long-term viability depends on acquiring firms with deep software integration expertise for grid-aware energy transfer systems. Acquisition targets should include niche technology firms specializing in advanced power electronics or network management platforms. A signal to watch is the widespread adoption of vehicle-to-grid (V2G) programs across major economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meeting escalating demand for high-power DC fast chargers is critical. |
| Software Platform Integration | Enabling smart charging and grid interoperability enhances system value. |
| Bi-directional Charging R&D | Unlocking new value streams like vehicle-to-grid applications is paramount. |
| Strategic Partnerships | Ensuring interoperability across diverse charging protocols improves user experience. |
| Domestic Manufacturing Investment | Leveraging incentives like the US Inflation Reduction Act strengthens supply chains. |
Research Approach
Multiple input streams — primary interviews, secondary market intelligence, and proprietary databases — were reconciled to construct the market's current state. This involved extensive conversations with EV fleet managers, charging network operators, automotive OEMs, and grid utility planners. Secondary validation utilized regulatory filings from NHTSA and CE marking documentation, alongside industry association reports and company financial disclosures. Data was triangulated through both bottom-up and top-down approaches.
Data stream reconciliation involved quantitative modeling, projecting market evolution across the analysis window. Segmentation dimensions modeled included product type, end-user, installation, technology, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends, projected EV sales volumes, and anticipated infrastructure investment. Industry-specific forecast inputs incorporated government infrastructure spending targets and battery capacity advancements.
Revisions become necessary when significant regulatory shifts or unforeseen technological breakthroughs materialize. Forecasts reflect assumptions regarding grid capacity limits and geopolitical stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
North America Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Electric Vehicle Charging Products Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
France Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market