
 Secure Digital Card Market | 2026-2036
Secure Digital Card Market Size, Share, and Industry Trends Forecast 2026-2036
Secure Digital Card Market Analysis
OEM supply channels for secure digital card components is tilting toward vertically integrated semiconductor manufacturers. Samsung Electronics leverages captive NAND flash production to control cost structures across card portfolios. Western Digital sustains R&D intensity in controller architecture for high-reliability enterprise segments. Kingston Technology Corp. anchors its position through deep distributor relationships across North American and Asian commercial channels.
A secure digital card is a physical or virtual payment instrument embedding integrated circuits, magnetic stripes, or near-field communication antennas to authenticate and execute electronic transactions, typically manufactured through injection-molded PVC lamination with embedded chip modules and holographic security layers. EMV cards lead transaction volume globally due to regulatory mandates, while contactless cards represent the fastest-growing product type as tap-to-pay infrastructure proliferates at retail point-of-sale terminals. Digital wallets command concentrated margin pools through platform fees and data monetization, though virtual cards face slower enterprise adoption cycles tied to legacy procurement system integration.
FDA, PCI Security Standards Council, and ISO frameworks govern secure digital card manufacturing, data encryption protocols, and interoperability standards, with PCI DSS compliance functioning as a market access gate for any issuer or processor handling cardholder data. ISO 7816 and ISO 14443 specifications define physical and electrical interface requirements that manufacturers must satisfy for terminal compatibility across payment networks. Stakeholders must monitor evolving central bank digital currency pilots and their potential to displace traditional card rails in high-volume consumer payment corridors.
Market Dynamics
Contactless payment infrastructure deployment is compressing transaction authentication cycles and forcing chip manufacturers to rebalance power consumption against processing speed in next-generation secure elements.
Growth Catalysts
- PCI DSS Compliance Mandates:Payment network operators in the United States face escalating audit frequency for cardholder data environments. Terminal manufacturers accelerate EMV certification timelines to maintain network acceptance.
- NAND Flash Cost Curves:Semiconductor foundries in South Korea and Taiwan achieve yield improvements on 3D stacked memory architectures. Secure digital card producers capture margin expansion through component cost deflation.
- Transit Authority Procurement:Metropolitan transportation agencies across Germany, Japan, and Brazil issue open-loop contactless card tenders. Dual-interface card volumes rise as transit-integrated payment credentials replace closed-loop systems.
Market Restraints
- Controller ASIC Supply Concentration:Fabless design houses depend on a concentrated Taiwan-based foundry base for secure microcontroller fabrication. Geopolitical friction threatens wafer allocation priority for payment-grade silicon.
- PVC Resin Price Volatility:Petrochemical feedstock fluctuations transmit directly into card body lamination costs. Issuers face margin compression on high-volume commodity card programs.
- Central Bank Digital Currency Substitution:Pilot programs by the People's Bank of China and European Central Bank test account-based retail payment rails. Tokenized card credentials face displacement risk in high-frequency consumer corridors.
Strategic Opportunities
- India Stack Integration:The National Payments Corporation of India expands RuPay contactless acceptance into tier-2 and tier-3 urban centers. Domestic card personalization bureaus scale capacity to serve unbanked population segments.
- Biometric-Payment Convergence:Fingerprint-on-card sensors from Swedish and Norwegian component suppliers achieve cost thresholds for mass issuance. Dual-authentication credentials command premium positioning in high-value transaction segments.
- Cloud-Based Card Management APIs:Virtual card provisioning platforms embed directly into enterprise expense management software. Real-time issuance capabilities displace physical card fulfillment for travel and procurement applications.
Industry Challenges
- EMV Certification Backlogs:Laboratory testing queues at accredited facilities extend product launch timelines by six to nine months. Fintech issuers face working capital strain during pre-revenue compliance phases.
- Legacy Core Banking Integration:Mainframe-based authorization systems at regional banks require middleware development for tokenized credential support. Technical debt impedes contactless feature rollout for mid-tier issuers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secure Digital Card Market |
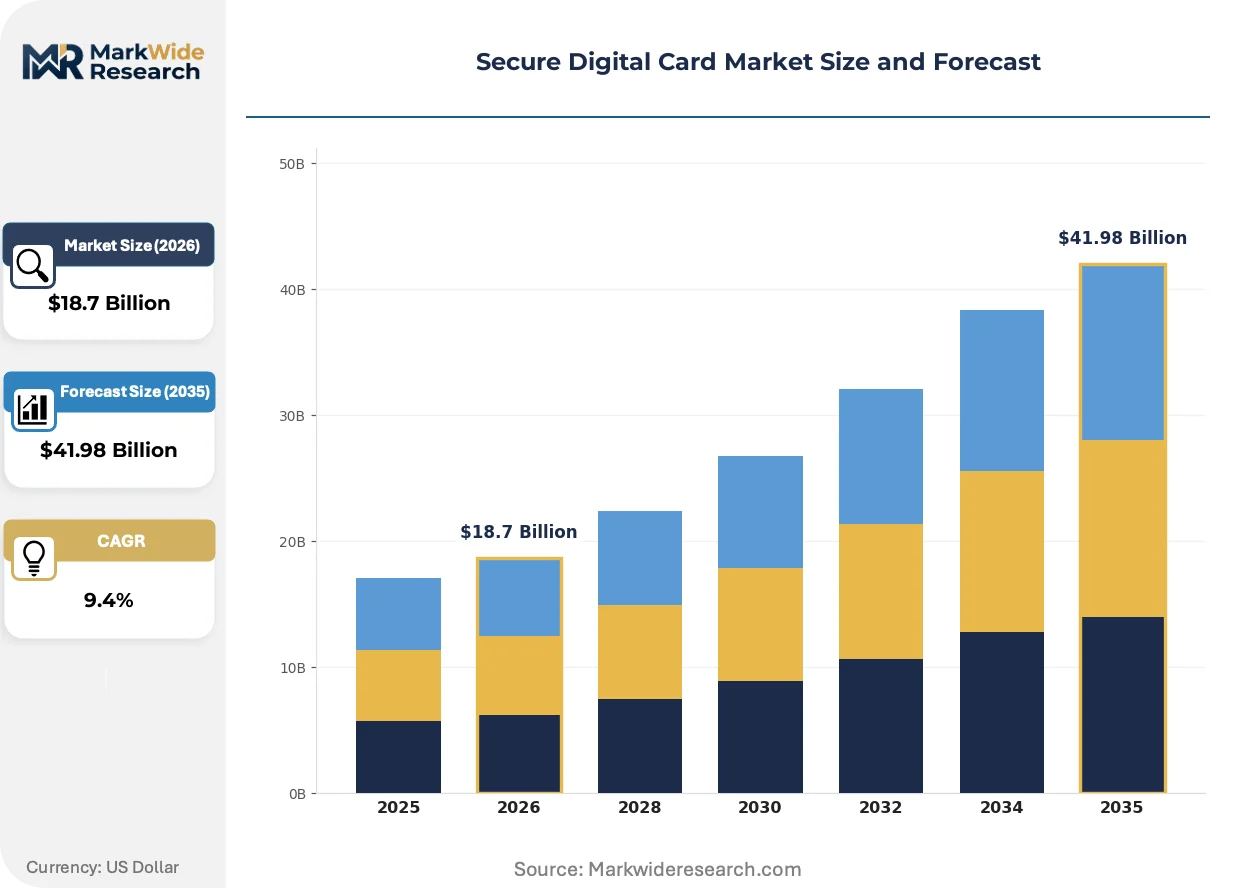
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless Cards, EMV Cards, Digital Wallets, Virtual Cards Technology: Near Field Communication, Magnetic Stripe, Chip, QR Code Application: Retail Payments, Online Shopping, Mobile Payments, Corporate Expenses End User: Consumers, Businesses, Financial Institutions, Government Agencies |
| Companies Covered | Samsung Electronics Co., Ltd., Western Digital Corporation, Kingston Technology Corp., Micron Technology, Inc., Sony Corporation, Kioxia Holdings Corp., Transcend Information, Inc., Lexar, PNY Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secure Digital Card Market Emerging Trajectories
Secure credential architectures are fragmenting across physical-digital boundaries as issuers experiment with software-defined payment instruments that decouple authentication from plastic form factors.
Embedded secure elements in smartphone handsets and wearable devices are virtualizing card-present transaction authentication. Transit operators in London and Sydney now accept device-based credentials at fare gates without plastic card issuance. This shift is virtualizing terminal hardware requirements and compressing demand for dual-interface plastic cards in urban mobility corridors.
GDPR data localization requirements are forcing payment processors to rearchitect cardholder data storage across European jurisdictions. Cloud infrastructure providers establish sovereign data enclaves in Frankfurt, Amsterdam, and Stockholm to satisfy residency mandates. Token service providers absorb compliance costs that regional issuers cannot shoulder independently.
Enterprise procurement departments now demand instant virtual card issuance with spend controls embedded in API parameters. Travel management platforms in the United States and United Kingdom replace physical corporate cards with single-use digital credentials for hotel and airline bookings. Finance teams capture granular expense attribution without reconciliation delays from traditional card reconciliation cycles.
Secure Digital Card Market Segmentation
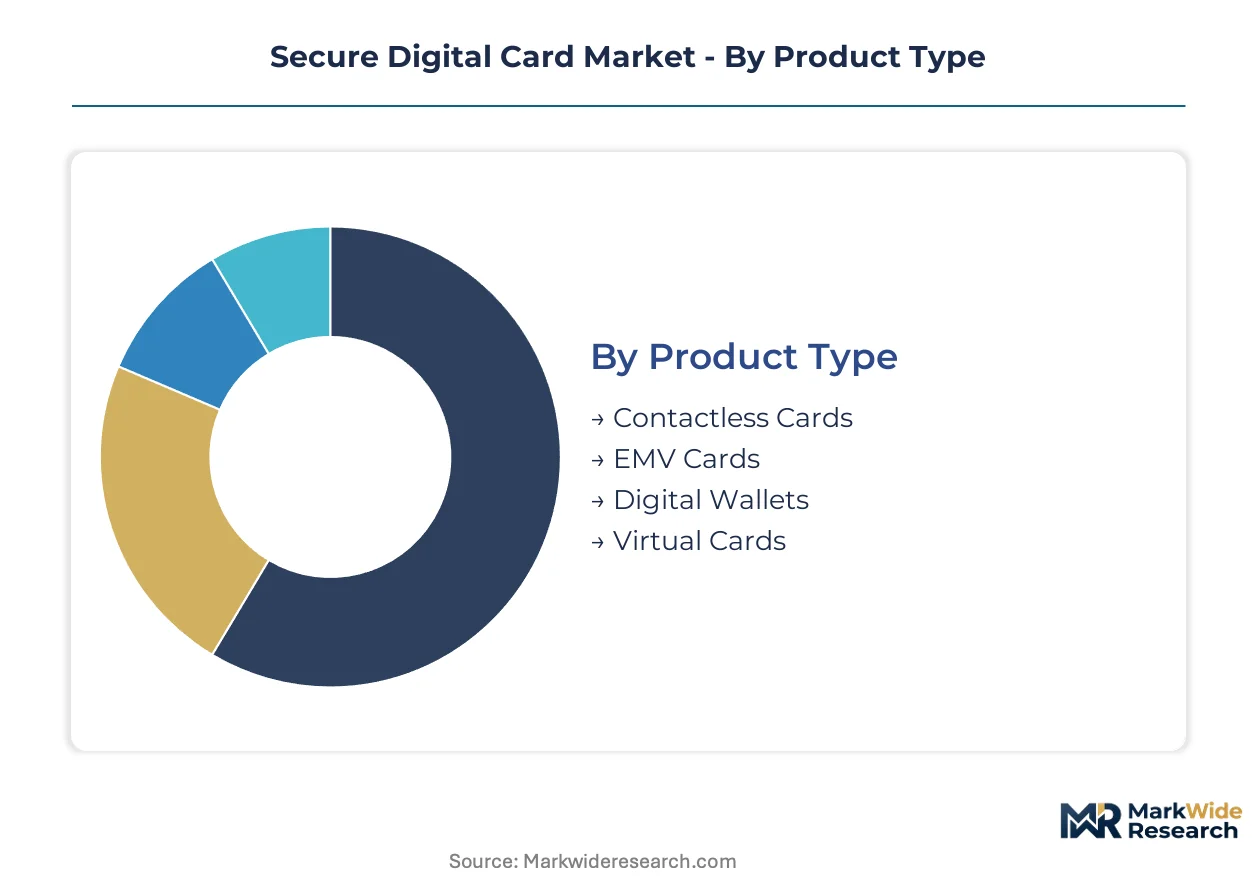
Payment credential architectures fragment across physical form factors, authentication protocols, and deployment contexts. Each segment carries distinct compliance burdens, margin structures, and infrastructure dependencies that reshape competitive positioning across issuance channels.
Product Type:
Cost tier differentiation separates premium credential platforms from commodity plastic issuance programs.
- Contactless Cards:Dual-interface plastic credentials embedding both EMV chip and NFC antenna arrays enable tap-to-pay authentication at retail point-of-sale terminals. Transit authorities in London, Sydney, and São Paulo drive procurement volume as open-loop fare collection replaces closed-loop systems.
- EMV Cards:Chip-based payment instruments complying with PCI Security Standards Council specifications for counterfeit fraud prevention. United States issuers face accelerating compliance audits for cardholder data environments, compressing certification timelines for terminal manufacturers.
- Digital Wallets:Software-based credential vaults on smartphone handsets and wearable devices.
- Virtual Cards:Single-use or limited-duration account numbers provisioned through API interfaces for enterprise procurement.
EMV cards command the established base. The steepest expansion runs through contactless cards.
Technology:
Authentication modality determines terminal hardware requirements, transaction latency, and fraud exposure profiles across deployment scenarios.
- Near Field Communication:13.56 MHz radio frequency protocol enabling proximity data exchange between card and reader. South Korean and Taiwanese semiconductor foundries achieve yield improvements on secure element fabrication, deflating component costs for card manufacturers.
- Chip:Embedded secure microcontrollers executing cryptographic protocols for card-present transaction verification. EMV certification backlogs at accredited testing laboratories extend product launch timelines by six to nine months for fintech issuers.
- Magnetic Stripe:Legacy track-based data storage on laminated plastic substrates.
- QR Code:Two-dimensional barcode scanning for account credential transmission in low-infrastructure environments.
Chip technology anchors current transaction volumes. NFC is gaining share fastest as contactless infrastructure proliferates.
Application:
End-use context shapes credential lifecycle management, spend control granularity, and reconciliation automation requirements.
- Retail Payments:Card-present and card-not-present transactions at physical merchant locations and e-commerce platforms. Mobile payment adoption among United States retail consumers accelerates uptake as contactless infrastructure deployment expands across metropolitan networks.
- Corporate Expenses:T&E and procurement credential programs with embedded policy controls. Travel management platforms in the United Kingdom and United States replace physical corporate cards with single-use digital credentials for hotel and airline bookings.
- Online Shopping:E-commerce checkout authentication through tokenized card credentials.
- Mobile Payments:Device-based transaction initiation through smartphone handsets and wearable form factors.
Retail payments command the established base. Corporate expenses show the steepest expansion trajectory through API-integrated virtual issuance.
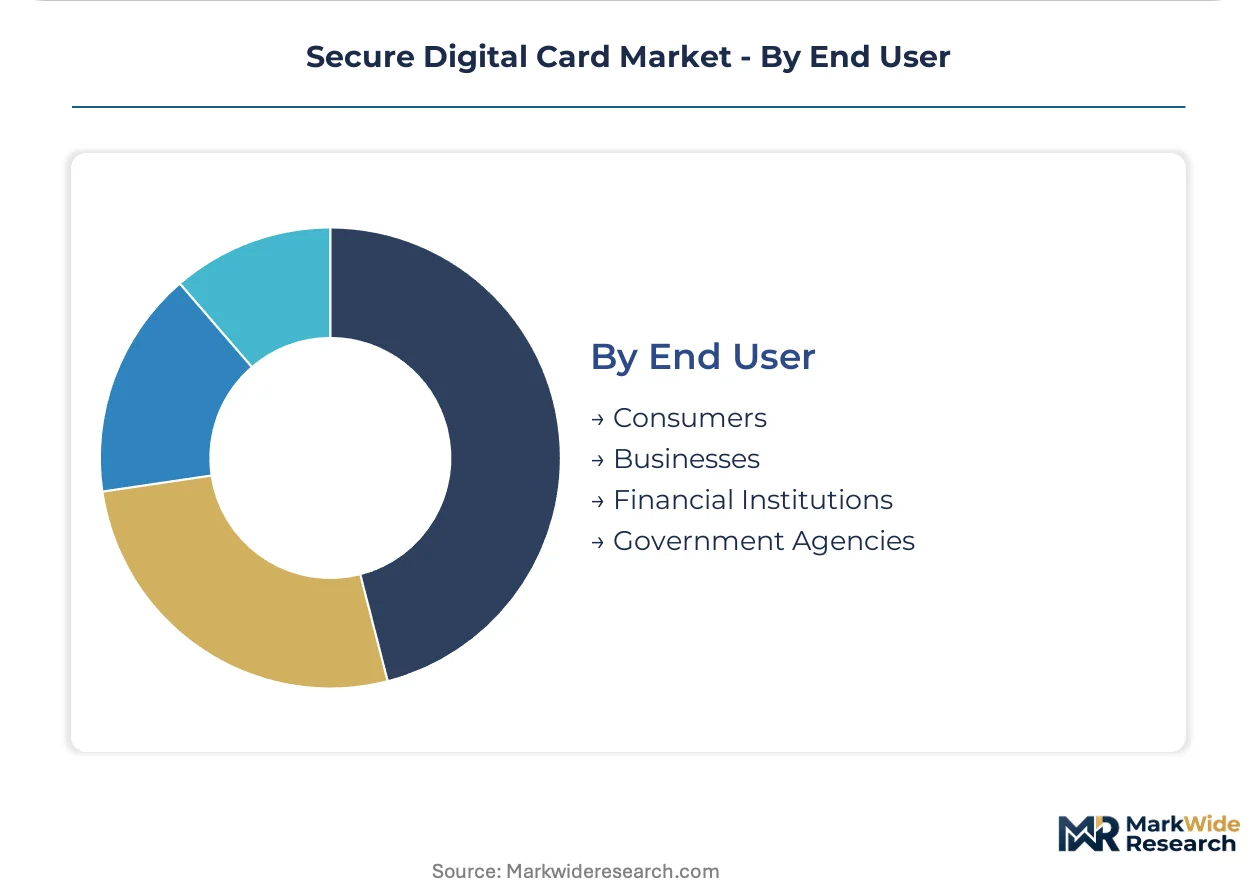
End User:
Customer type dictates procurement channel structure, compliance sophistication, and credential customization depth.
- Financial Institutions:Banks and credit unions issuing branded payment credentials to retail and commercial account holders. Regional banks in the United States face technical debt in mainframe-based authorization systems, requiring middleware development for tokenized credential support.
- Consumers:Individual account holders seeking physical or virtual payment instruments for personal transaction needs. India's National Payments Corporation expands RuPay contactless acceptance into tier-2 and tier-3 urban centers, scaling domestic personalization bureau capacity.
- Businesses:Commercial entities procuring corporate card programs for employee expense management.
- Government Agencies:Public sector entities distributing benefit disbursement and procurement credentials.
Financial institutions command the established base. Consumer segments are expanding most quickly through mobile-first issuance models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New York City subway's open-loop contactless payment rollout anchors North American infrastructure deployment. London's Oyster card migration to bank-issued credentials underwrites European transit-integrated payment corridors. Tokyo's Suica and Pasmo networks demonstrate Asia-Pacific closed-loop to open-loop transition pathways.
United States
Metropolitan transit agencies in Chicago, Boston, and Los Angeles accelerate dual-interface card procurement for fare gate modernization. PCI Security Standards Council audit frequency escalates for cardholder data environments, compressing EMV certification timelines. Silicon Valley semiconductor design houses concentrate secure element architecture development for next-generation payment credentials.
Germany
Deutsche Bahn's Deutschland-Ticket program drives contactless credential volume through integrated transit-retail payment rails. GDPR data localization mandates force processors to establish sovereign storage enclaves in Frankfurt and Amsterdam. Munich and Stuttgart personalization bureaus scale capacity for biometric-payment card pilot programs.
India
National Payments Corporation of India expands RuPay contactless into tier-2 and tier-3 urban centers, scaling domestic bureau capacity. RBI guidelines on tokenized card credentials accelerate fintech issuer participation in open banking frameworks. Bangalore and Hyderabad semiconductor assembly facilities capture component localization incentives under PLI scheme provisions.
Japan
JR East and private railway operators migrate from proprietary FeliCa to EMV-compatible dual-interface standards. METI standardization initiatives harmonize transit-retail interoperability requirements across metropolitan networks. Osaka and Nagoya terminal manufacturers achieve yield improvements on NFC antenna module fabrication.
Brazil
São Paulo and Rio de Janeiro transit authorities issue open-loop contactless tenders replacing closed-loop Bilhete Único systems. Central Bank of Brazil Pix instant payment integration creates hybrid credential architectures linking card rails to account-based settlement. Campinas and Porto Alegre personalization facilities expand throughput for Latin American export markets.
Secure Digital Card Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated semiconductor manufacturers with captive NAND flash production and fabless design houses dependent on concentrated foundry capacity. Three archetypes dominate: memory-integrated conglomerates controlling cost structures through backward integration into wafer fabrication; controller-specialist firms sustaining R&D intensity in high-reliability enterprise segments; and distributor-anchored assemblers leveraging deep commercial channel relationships. Competitive moves concentrate on strategic partnerships for secure element architecture licensing and geographic expansion into India Stack-integrated issuance corridors.
Among memory-integrated conglomerates, Samsung Electronics Co., Ltd. and Kioxia Holdings Corp. exemplify the captive production archetype through in-house NAND flash supply control. Western Digital Corporation occupies a position within the controller-specialist tier, while Kingston Technology Corp. anchors the distributor-relationship archetype across North American and Asian commercial channels.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Western Digital Corporation |
| Kingston Technology Corp. |
| Micron Technology, Inc. |
| Sony Corporation |
| Kioxia Holdings Corp. |
| Transcend Information, Inc. |
| Lexar |
| PNY Technologies |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors transmit petrochemical feedstock volatility directly into card body lamination costs, forcing issuers to rebalance procurement between captive NAND flash producers and merchant component suppliers while downstream pricing power concentrates with transit-integrated credential platforms.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement contracts from retail consumer issuance programs. Three-tier pricing stratification across premium biometric-authentication credentials, standard dual-interface EMV cards, and economy magnetic-stripe products reflects certification grade and chip module performance. Cost compression in commodity card tiers intensifies as South Korean foundry yield improvements deflate NAND flash component costs. Small and mid-tier fintech issuers exhibit highest price sensitivity due to working capital constraints during EMV certification phases.
Supply Chain Analysis
Extended payment terms from Taiwan-based foundries to fabless controller design houses strain working capital across the secure element fabrication tier. Geographic supply concentration centers on Taiwan for secure microcontroller wafer production, South Korea for 3D NAND flash memory, and Japan for NFC antenna module substrates. Raw material dependencies encompass PVC resin from petrochemical complexes, gold wire bonding materials, and holographic security film substrates. Single-source vulnerability in Taiwan foundry capacity threatens wafer allocation priority for payment-grade silicon. Distribution runs through personalization bureaus in North America, Europe, and Asia-Pacific that laminate, encode, and fulfill credentials to issuer specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
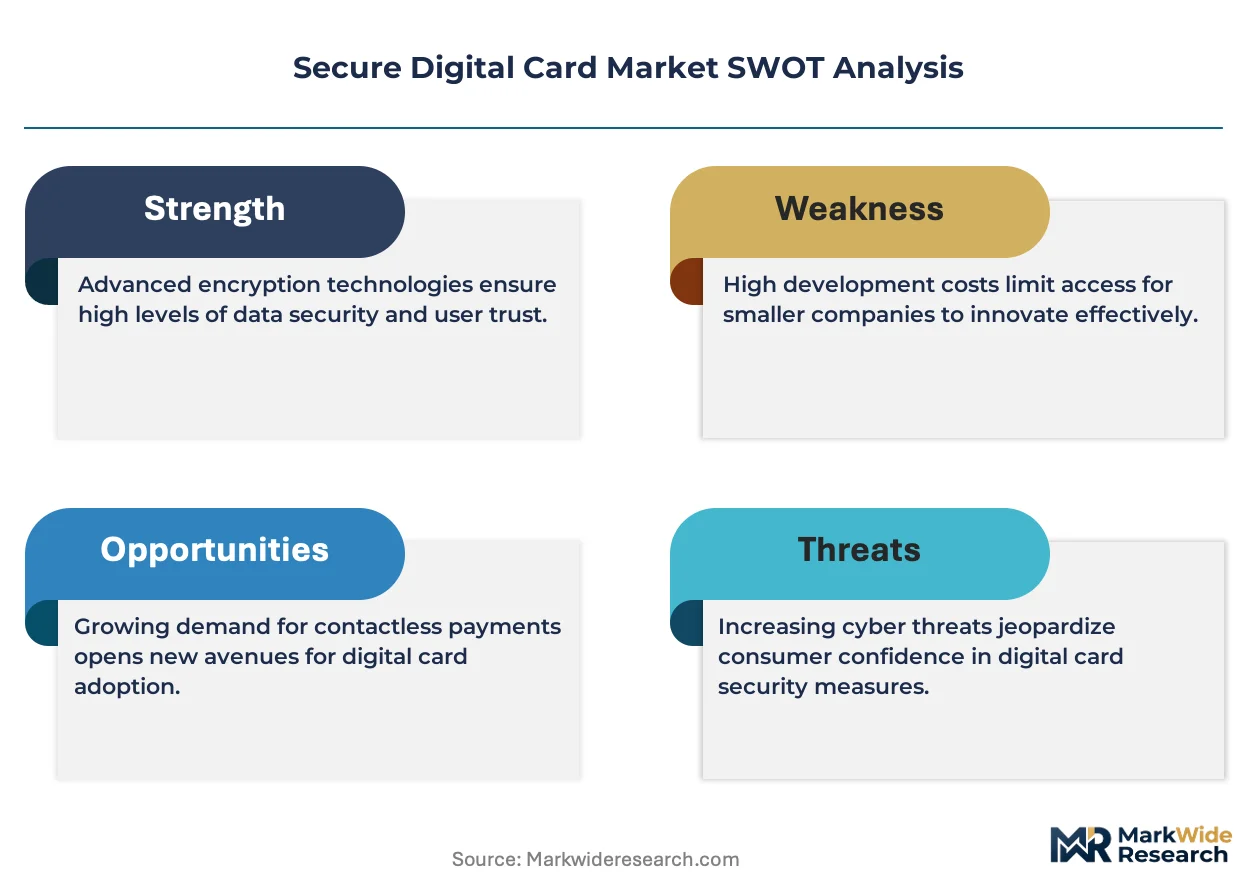
Secure digital card manufacturing capability concentrates among semiconductor conglomerates with captive wafer fabrication, leaving fabless specialists and regional assemblers exposed to foundry allocation bottlenecks and certification backlog delays.
For Market Incumbents: Pre-empt central bank digital currency displacement by embedding tokenized credential APIs directly into transit authority procurement platforms. Capture biometric-payment convergence through strategic component partnerships with Swedish and Norwegian fingerprint sensor suppliers. Defend margin position against NAND flash cost deflation by anchoring long-term supply agreements with South Korean foundries. For New Entrants and Emerging Players: Mid-market commercial issuers in India Stack-integrated tier-2 and tier-3 urban centers represent the most penetrable entry point for domestic personalization bureau capacity expansion. Cloud-based virtual card management APIs for enterprise expense management platforms offer lowest barrier to issuance without EMV certification backlog exposure. Target acquisition of middleware specialists bridging legacy core banking systems to tokenized credential architectures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors controller-specialist firms sustaining R&D intensity in high-reliability enterprise segments over memory-integrated conglomerates facing NAND flash commoditization. Long-term viability hinges on biometric-authentication adoption curves and transit-integrated payment credential proliferation. Monitor central bank digital currency pilot program expansion in high-frequency consumer corridors as inflection indicator for traditional card rail displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Sensor Integration | Fingerprint-on-card modules from Nordic suppliers achieve mass-issuance cost thresholds for premium credential tiers. |
| Transit Authority Partnership | Open-loop contactless tenders in São Paulo and Sydney replace closed-loop systems with dual-interface card volumes. |
| API Platform Development | Real-time virtual card provisioning embeds into enterprise expense management software displacing physical fulfillment. |
| Foundry Capacity Securement | Long-term wafer allocation agreements with Taiwan semiconductor manufacturers mitigate geopolitical supply concentration risk. |
| India Stack Localization | RuPay contactless expansion into tier-2 urban centers scales domestic personalization bureau capacity for unbanked segments. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with secure element architects, transit authority procurement officers, fintech issuer compliance leads, and personalization bureau operations directors; and secondary validation against PCI Security Standards Council certification databases, RBI tokenization guidelines, EMVCo terminal approval registries, and semiconductor foundry capex disclosures. Bottom-up triangulation across component cost curves and top-down reconciliation against issuer procurement volumes anchored market sizing.
Forecast inputs encompassed product type segmentation across contactless, EMV, digital wallet, and virtual card architectures; technology modality splits between NFC, chip, and magnetic stripe authentication; and application contexts spanning retail payments, corporate expenses, and transit-integrated corridors. CAGRs derived from regression analysis of historical issuance volumes against infrastructure deployment timelines and regulatory mandate effective dates, incorporating NAND flash cost curve projections and EMV certification throughput constraints.
Practitioners should monitor central bank digital currency pilot expansion, Taiwan foundry utilization rates, and transit authority open-loop migration timelines for early signals of credential architecture displacement. Forecasts reflect assumptions regarding PCI DSS audit frequency escalation and contactless terminal penetration curves. Macroeconomic deviation in petrochemical feedstock costs, regulatory acceleration of account-based payment rails, or technological breakthrough in device-based authentication would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Data Privacy Software Market
Security Software
Europe Encryption Software Market
Security Software
Quantum Key Distribution System Market
Security Software
Data Loss Prevention Market
Security Software
Employee Computer Monitoring Software Market
Security Software
North America Secure Access Service Edge Market
Security Software
Consumer Endpoint Security Market
Security Software
Privileged Identity Management Market
Security Software
Global Wireless Intrusion Prevention System Market
Security Software
Passport Reader Market
Security Software
Global Software-Defined Security Market
Security Software
Remote Access Management Market
Security Software
Internet Filter Software Market
Security Software
Secure Email Gateway Market
Security Software
VPN Software Market
Security Software
Single Sign-On Market