
 Asia Pacific Anti Money Laundering Solutions Market | 2026-2036
Asia Pacific Anti Money Laundering Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Anti Money Laundering Solutions Market Insights
Modular compliance bundling is repositioning how Asia Pacific banks evaluate AML procurement, shifting from standalone transaction monitoring toward integrated KYC-risk-reporting suites. Oracle Corporation leverages its cloud infrastructure to anchor multi-tenant deployments across ASEAN financial hubs. IBM Corporation differentiates through AI-enhanced anomaly detection architectures that sustain premium positioning in transaction monitoring. ACI Worldwide competes on real-time payment screening specialization, dominating corridors with high cross-border velocity.
Anti money laundering solutions encompass software platforms, services, and cloud architectures engineered to detect, analyze, and report suspicious financial activities through algorithmic pattern recognition and rule-based monitoring engines. These systems process structured and unstructured data streams to flag anomalies against regulatory thresholds, serving primary commercial purpose of shielding institutions from illicit fund flows and enforcement penalties. Software deployments currently lead revenue composition as banks prioritize in-house control over sensitive transaction data, while cloud-based solutions represent the fastest-expanding segment as hybrid architectures gain traction among mid-tier institutions seeking elastic compute without full infrastructure commitment. Services margins concentrate in managed compliance offerings where vendor expertise substitutes for scarce internal AML talent pools.
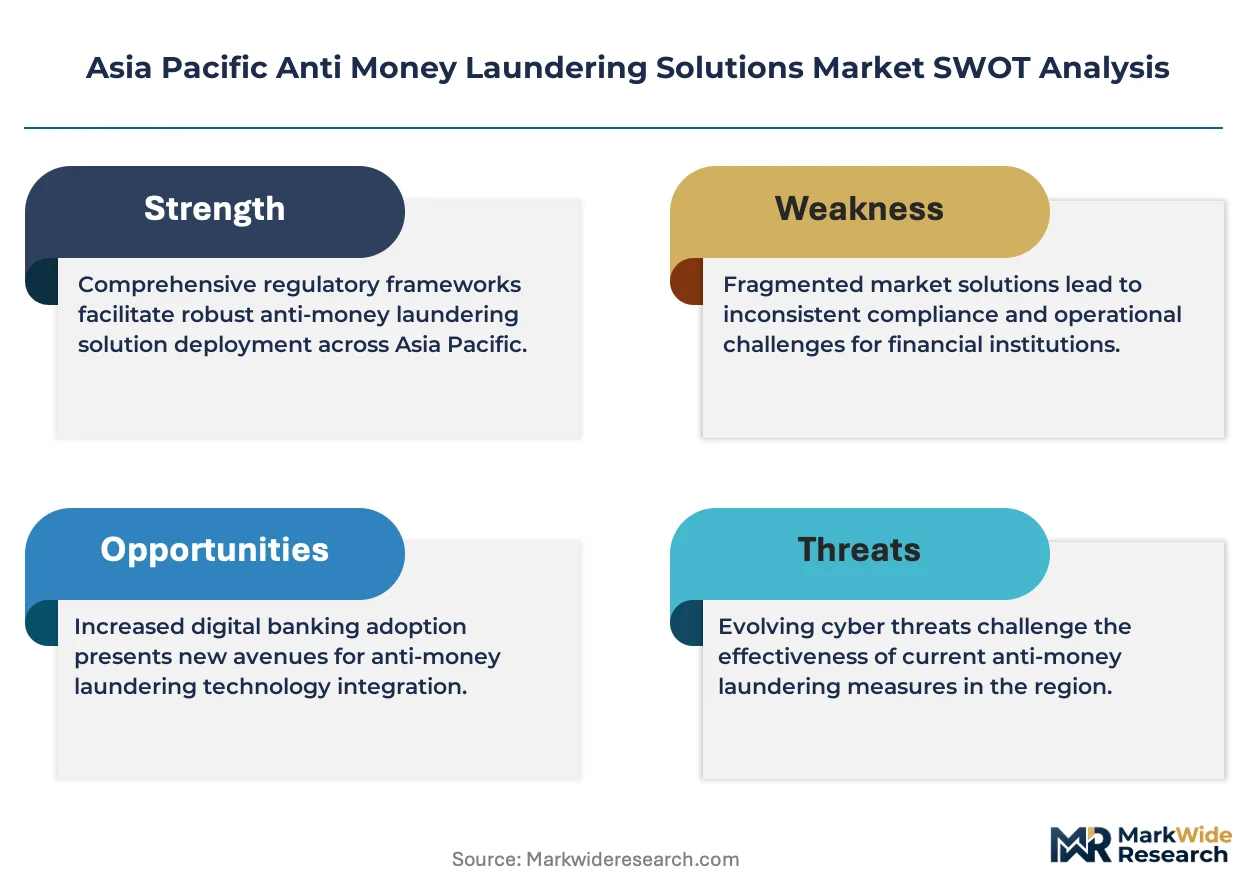
India's RBI mandates periodic KYC updates through its master direction framework, compelling banks to refresh technology stacks or face operational restrictions. Australia's AUSTRAC enforcement actions against major banks have elevated transaction monitoring to board-level priority, directly expanding procurement budgets. Singapore's MAS technology risk management guidelines shape product certification requirements that filter vendor eligibility. Stakeholders must weigh sovereign data residency rules against cloud scalability when architecting multi-jurisdiction deployments across the region.
Market Dynamics
Regulatory fragmentation across Asia Pacific is compressing deployment timelines as banks face simultaneous mandates from India's RBI, Singapore's MAS, and Australia's AUSTRAC, forcing procurement toward modular compliance architectures that can adapt to divergent national requirements without full system replacement.
Growth Catalysts
- RBI Master Direction KYC:India's central bank mandates periodic customer data refreshes, compelling financial institutions to automate identity verification workflows or face operational restrictions.
- Real-time payment rails:ASEAN cross-border corridors with high transaction velocity require instant screening capabilities that legacy batch-processing systems cannot support.
- AUSTRAC enforcement precedent:Australia's financial intelligence unit has imposed substantial penalties on major banks, elevating transaction monitoring to board-level capital allocation priority.
Market Restraints
- Sovereign data residency:India's data localization requirements and China's cybersecurity law fragment cloud architectures, forcing redundant infrastructure deployment across jurisdictions.
- Scarce AML talent pools:Singapore and Hong Kong face acute shortages of certified compliance officers, inflating managed service costs and extending implementation timelines.
- Legacy system entrenchment:Southeast Asian tier-two banks operate on decades-old core banking platforms that resist API-based integration with modern screening engines.
Strategic Opportunities
- Philippines digital banking licenses:The central bank's new charter categories for neobanks create greenfield procurement opportunities unencumbered by legacy infrastructure.
- AI-enhanced anomaly detection:Machine learning convergence with graph analytics enables identification of complex layering schemes that rule-based systems miss.
- MAS technology risk certification:Singapore's vendor eligibility framework creates competitive moat for solutions providers achieving pre-approved status.
Industry Challenges
- False positive fatigue:Transaction monitoring systems generate alert volumes that overwhelm investigation teams, degrading operational efficiency and regulatory credibility.
- Cross-border data friction:Divergent privacy regimes between Australia, Singapore, and India complicate unified risk scoring for multinational banking groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Anti Money Laundering Solutions Market |
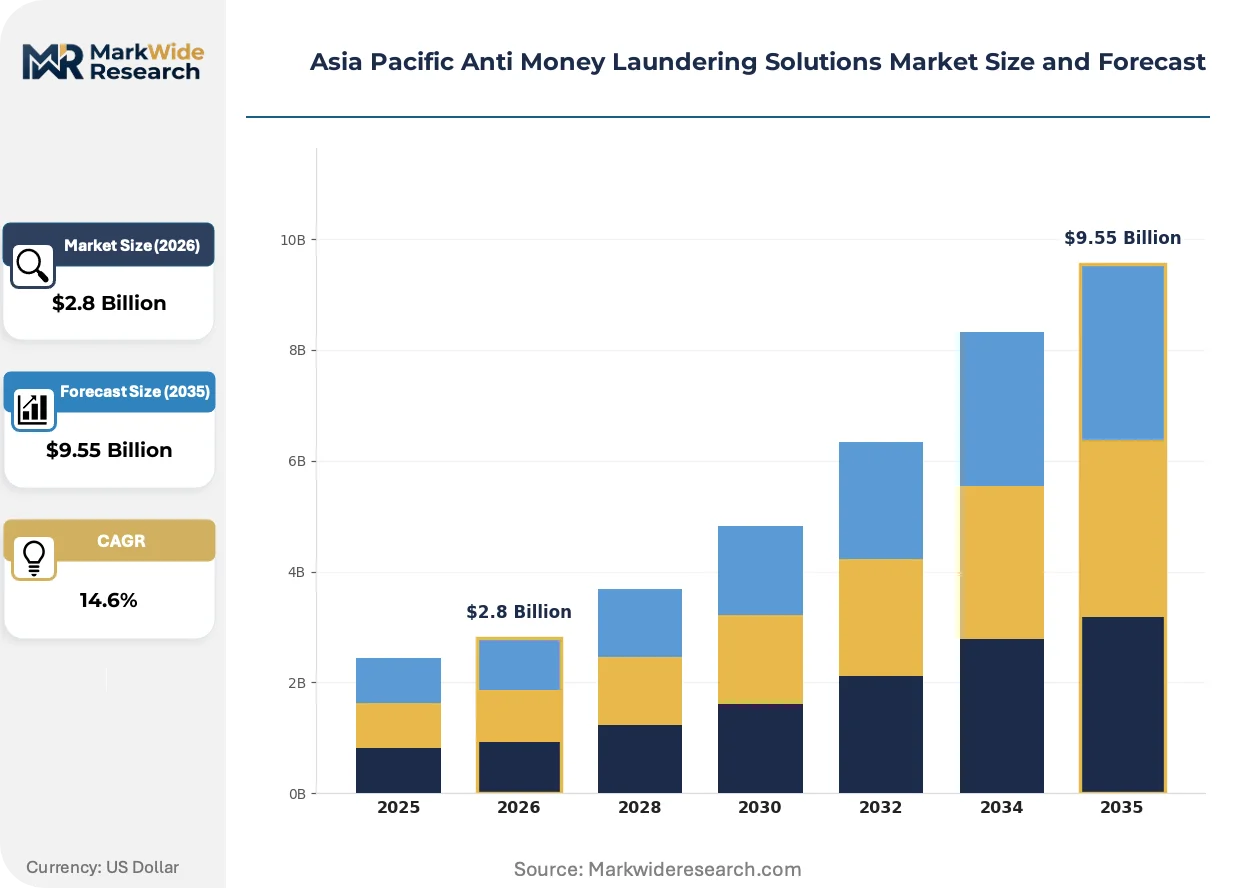
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Services, Cloud-Based Solutions, On-Premise Solutions End User: Banks, Insurance Companies, Investment Firms, Regulatory Authorities Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Compliance Area: KYC, Transaction Monitoring, Risk Assessment, Reporting |
| Companies Covered | Accenture, ACI Worldwide, BAE Systems, NICE Systems, Oracle Corporation, SAS Institute, Fiserv, IBM Corporation, Open Text Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Anti Money Laundering Solutions Market Trends and Innovations
Cloud-native compliance architectures are displacing on-premise deployments as Asia Pacific banks prioritize elastic compute for transaction volume spikes and regulatory audit cycles. Three developments define the current innovation trajectory.
Federated learning for AML is decentralizing model training across banking consortia without exposing sensitive transaction data. Singapore's DBS and OCBC are piloting shared anomaly detection networks that preserve data sovereignty while pooling pattern recognition capabilities. This architecture is decentralizing competitive advantage from proprietary datasets toward algorithmic sophistication.
AUSTRAC's 2023 design and distribution obligations for anti-money laundering extend liability to product manufacturers, not just distributors. Australian banks now embed compliance checkpoints into product development workflows rather than retrofitting controls post-launch. Wealth management and remittance products face the steepest compliance redesign requirements.
Mid-tier institutions across Indonesia and Vietnam are unbundling compliance suites, purchasing standalone KYC modules from specialist vendors rather than integrated platforms from incumbent providers. This fragmentation favors agile software vendors with API-first architectures over legacy suite vendors. Procurement committees in Jakarta and Ho Chi Minh City are driving this disaggregation most aggressively.
Asia Pacific Anti Money Laundering Solutions Market Segmentation
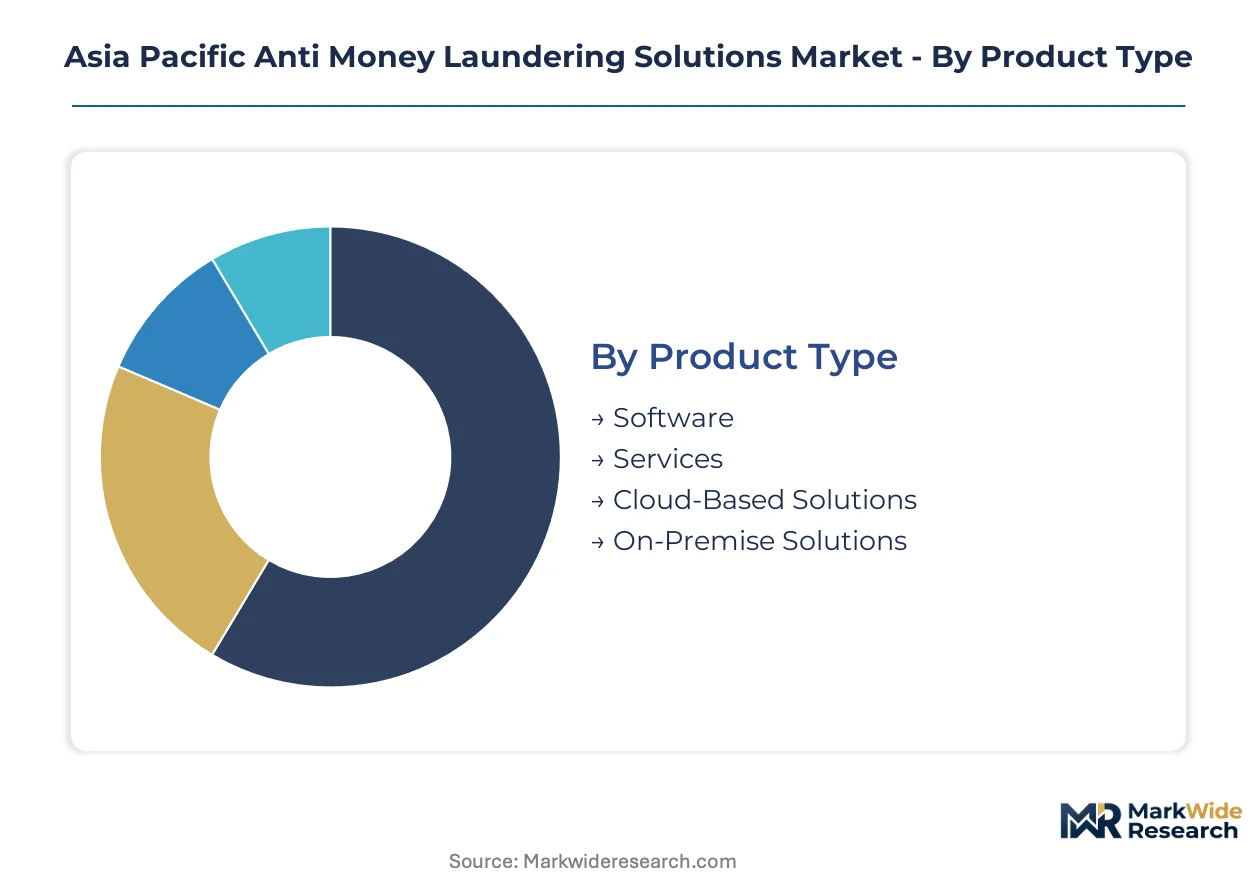
AML procurement patterns across Asia Pacific diverge sharply by institution size, regulatory exposure, and infrastructure maturity. Banks in India and Singapore prioritize integrated suites, while mid-tier players in Indonesia and Vietnam unbundle components to manage capital outlay. Understanding these segment dynamics clarifies where vendor specialization commands premium pricing versus where standardization dominates.
Product Type:
Standardization prevails in software licensing, while customization intensity escalates through services and cloud architectures.
- Software:Core transaction monitoring engines and rule-based screening platforms deploy on bank-controlled infrastructure. India's RBI mandates drive concentrated procurement among private sector banks in Mumbai and digital payment corridors.
- Services:Managed compliance offerings substitute for scarce AML talent pools in Singapore and Hong Kong. Implementation timelines extend 40-60% when banks rely on external investigators and model validation teams.
- Cloud-Based Solutions:Elastic compute for transaction spikes without full infrastructure commitment.
- On-Premise Solutions:Sovereign data residency requirements in India and China fragment deployment architectures.
Leading the category by volume: Software. Growing fastest: Cloud-Based Solutions.
End User:
Regulatory pressure intensity varies dramatically across user categories, with enforcement precedent directly shaping procurement urgency.
- Banks:Universal and retail banks absorb the majority of AML technology spend, driven by AUSTRAC penalties in Australia and RBI master direction compliance in India. Transaction monitoring budgets have reached board-level capital allocation priority.
- Insurance Companies:Life insurers and general underwriters face emerging scrutiny on premium financing and claims layering schemes. Australia's design and distribution obligations extend liability to product manufacturers, accelerating embedded compliance investments.
- Investment Firms:Wealth managers and broker-dealers concentrate in Singapore's private banking hub.
- Regulatory Authorities:Government agencies procure surveillance and data analytics capabilities.
Dominant spend concentration: Banks. Steepest expansion trajectory: Investment Firms.
Deployment:
Cost tier stratification separates enterprise banks with dedicated infrastructure from mid-tier institutions seeking operational flexibility.
- On-Premise:Major banks in Australia and Singapore maintain captive data centers for sensitive transaction processing. AUSTRAC audit requirements and MAS technology risk guidelines reinforce this preference among systemically important institutions.
- Cloud-Based:Neobanks in the Philippines and Vietnam deploy natively on cloud infrastructure, unencumbered by legacy platform debt. The Philippines central bank's digital banking licenses create greenfield procurement channels.
- Hybrid:Tier-two banks across ASEAN split sensitive screening on-premise while bursting compute to cloud during regulatory audit cycles.
- Managed Services:Mid-market institutions outsource entire compliance operations to address talent scarcity.
Highest absolute spend: On-Premise. Gaining share fastest: Cloud-Based.
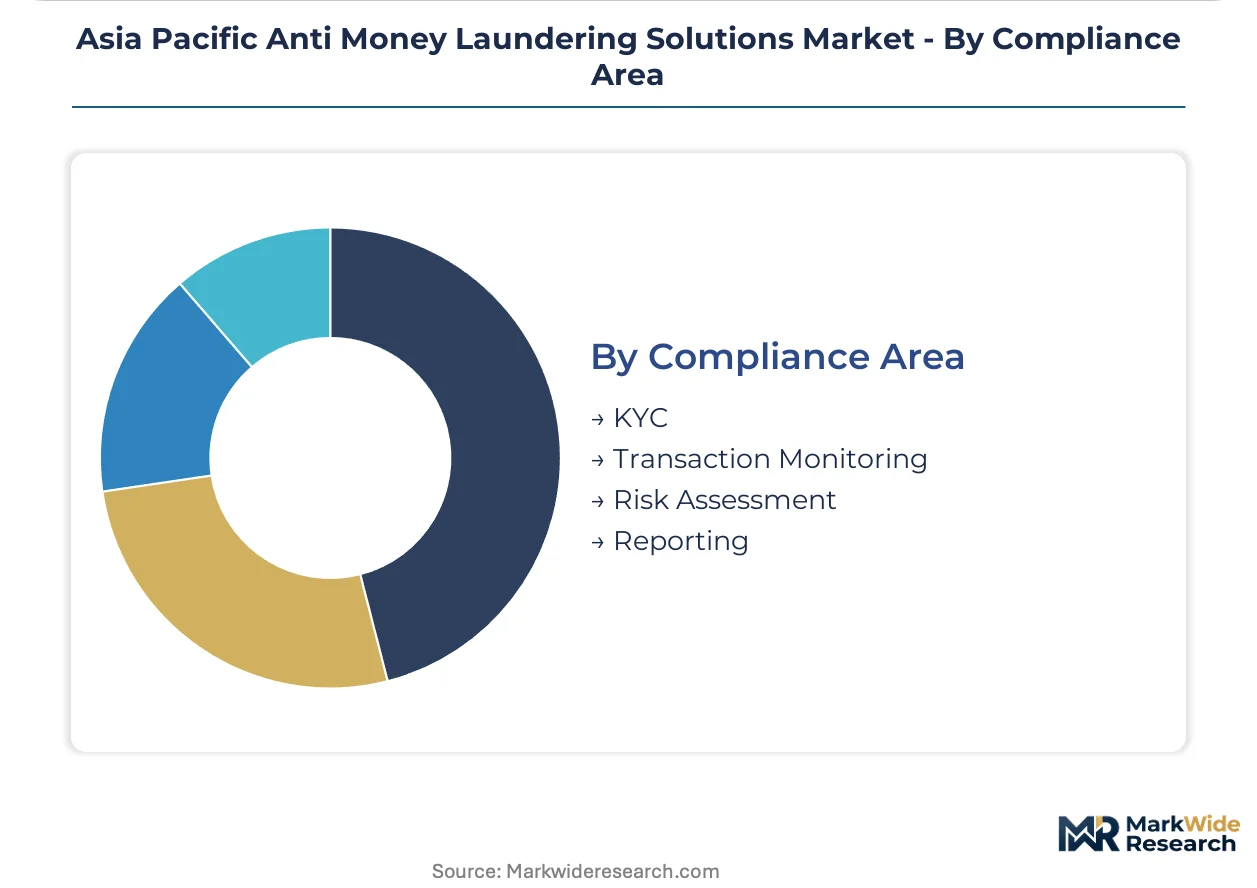
Compliance Area:
Application maturity progresses from established KYC workflows toward AI-enhanced transaction monitoring and predictive risk assessment.
- KYC:Identity verification and periodic customer data refresh workflows anchor compliance foundations. India's RBI mandates periodic updates through its master direction framework, compelling technology stack refreshes.
- Transaction Monitoring:Real-time screening capabilities dominate procurement priorities where cross-border payment velocity is highest. ASEAN corridors with instant payment rails require capabilities legacy batch systems cannot support.
- Risk Assessment:Customer risk scoring and enhanced due diligence automation.
- Reporting:Regulatory filing and suspicious activity report generation.
Widest installed base: KYC. Climbing the fastest: Transaction Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's GIFT City and Singapore's Marina Bay financial district concentrate AML procurement budgets through tax-advantaged zones and regulatory sandbox programs. These special-economic-zones anchor regional deployment timelines and vendor certification priorities.
India
Digital payment corridors in Mumbai and Bengaluru drive concentrated software procurement as UPI transaction volumes strain legacy monitoring systems. RBI's master direction framework mandates periodic KYC refreshes, compelling private sector banks to automate identity verification workflows. The GIFT City special economic zone in Gujarat hosts fintech clusters where neobanks deploy cloud-native compliance architectures without legacy platform debt.
Singapore
Wealth management hubs and private banking corridors generate premium-tier demand for AI-enhanced anomaly detection. MAS technology risk management guidelines filter vendor eligibility through pre-approved certification frameworks. The Marina Bay financial district anchors procurement concentration, with DBS and OCBC piloting federated learning networks for shared AML capabilities.
Australia
AUSTRAC enforcement actions against major banks have elevated transaction monitoring to board-level capital allocation priority. Sydney and Melbourne financial centers absorb the majority of compliance technology spend as design and distribution obligations extend liability to product manufacturers. The country's data residency requirements reinforce on-premise deployment preferences among systemically important institutions.
Philippines
Digital banking licenses issued by the central bank create greenfield procurement channels unencumbered by legacy infrastructure. Manila-based neobanks and payment processors dominate initial cloud-based solution adoption. The central bank's regulatory sandbox program accelerates vendor certification timelines for ASEAN-focused compliance specialists.
Vietnam
Ho Chi Minh City and Hanoi financial districts exhibit aggressive unbundling of compliance suites, with mid-tier banks purchasing standalone KYC modules from specialist vendors. The State Bank of Vietnam's tightening anti-money laundering directives compress implementation timelines. Local procurement committees favor API-first architectures over integrated platforms from incumbent providers.
Asia Pacific Anti Money Laundering Solutions Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor structure. The market fragments between cloud infrastructure providers anchoring multi-tenant deployments, AI-enhanced anomaly detection specialists commanding premium positioning, and real-time payment screening vendors dominating high-velocity corridors. Three archetypes define competitive positioning: integrated suite providers, modular component specialists, and managed compliance service operators. Dominant competitive moves include strategic partnerships with regional cloud providers and API-based portfolio diversification into adjacent fraud prevention domains.
Within the integrated suite tier, Oracle Corporation and IBM Corporation exemplify divergent strategic positioning. Oracle leverages cloud infrastructure scale to anchor multi-tenant deployments across ASEAN financial hubs. IBM occupies a position emphasizing AI-enhanced detection architectures that sustain premium pricing in transaction monitoring segments. ACI Worldwide represents the specialization archetype, with its corporate name indicating payment-processing heritage that translates into real-time screening dominance for cross-border corridors.
| Leading Market Players |
|---|
| Accenture |
| ACI Worldwide |
| BAE Systems |
| NICE Systems |
| Oracle Corporation |
| SAS Institute |
| Fiserv |
| IBM Corporation |
| Open Text Corporation |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up compliance specialists anchor supply concentration in Singapore and Sydney, compressing margins for mid-tier vendors while reinforcing pricing discipline among integrated suite providers serving Australia's major banks and India's RBI-mandated institutions.
Pricing Analysis
Margin tightening in cloud-native deployments reflects hyperscaler infrastructure costs and MAS certification requirements. Subscription-tiered SaaS pricing dominates, with differentiation hinging on AUSTRAC audit-grade reporting and RBI KYC automation depth. Pricing pressure accelerates as Philippine neobanks and Vietnamese mid-tier banks unbundle suites into standalone API modules. Tier-two ASEAN institutions exhibit highest price sensitivity, while Singapore private banks absorb premium AI-enhanced detection tariffs.
Supply Chain Analysis
Dual-sourcing mandates from Australian systemically important banks and Singapore's DBS consortium fragment vendor qualification across Oracle cloud infrastructure, IBM AI architectures, and ACI payment screening engines. Software development concentrates in India, cloud infrastructure in Singapore and Australia, with managed compliance talent drawn from Hong Kong. Supply chain risk centers on single-source dependency for federated learning model training. Distribution runs through direct enterprise sales teams and regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as MAS pre-approval frameworks and AUSTRAC enforcement precedents raise compliance barriers, forcing sub-scale vendors toward acquisition or exit.
For Market Incumbents: Anchor defensive positioning through MAS technology risk certification investment and captive AI model development in Singapore. Acquire API-first specialists in Ho Chi Minh City and Manila before regional neobanks cement vendor relationships. Cloud infrastructure scale and regulatory pre-approval status constitute the critical leverage points against modular disruptors. For New Entrants and Emerging Players: Enter via standalone KYC modules for Vietnam's mid-tier banks and Philippine digital payment processors, where legacy suite entrenchment remains weakest. Target cloud-native deployments in Jakarta and Bangkok where hybrid architecture demand outpaces incumbent delivery capacity. Position through federated learning consortium participation as an alternative to proprietary dataset competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor API-first compliance specialists with MAS certification progress and established Philippine central bank sandbox relationships. Long-term viability hinges on regulatory pre-approval moats rather than feature differentiation alone. Watch AUSTRAC enforcement velocity as the inflection signal for Australian bank procurement budget expansion.| Strategic Initiative | Industry Significance |
|---|---|
| MAS Technology Risk Certification | Pre-approval status filters vendor eligibility for Singapore's Marina Bay financial district procurement. |
| Federated Learning Consortium Participation | Shared anomaly detection networks preserve data sovereignty while pooling DBS and OCBC pattern recognition. |
| API-First Architecture Development | Modular unbundling captures Vietnamese and Indonesian mid-tier bank procurement committee preferences. |
| Cloud Infrastructure Multi-Tenancy | Elastic compute deployment serves ASEAN cross-border payment corridors with instant screening requirements. |
| Managed Compliance Service Expansion | External investigator substitution addresses acute AML talent scarcity in Singapore and Hong Kong. |
Research Methodology
Regulatory filings from AUSTRAC, MAS, and RBI, alongside vendor certification databases and ASEAN payment system operator disclosures, formed the secondary backbone. Primary interviews with compliance technology officers at Indian private sector banks, Singapore wealth management heads, and Australian transaction monitoring directors triangulated deployment timeline and budget allocation data. Bottom-up segment sizing and top-down regulatory mandate impact assessment cross-validated revenue projections.
Bottom-up modeling anchored forecasts across software licensing, services, and cloud deployment segments, with organization size tiers and compliance area maturity as orthogonal dimensions. CAGRs derived from regulatory mandate velocity, enforcement precedent severity, and infrastructure refresh cycle analysis. Federated learning adoption curves and neobank license issuance rates served as industry-specific forecast inputs over the projection horizon.
Revisions become necessary when AUSTRAC enforcement intensity shifts, MAS certification frameworks expand, or RBI KYC mandate timelines compress. Forecasts reflect documented assumptions on regulatory implementation schedules and cloud infrastructure cost trajectories. A model refresh is warranted upon material change in ASEAN real-time payment rail deployment velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Digital Vehicle Forensics Market
Security Software
Global Insider Threat Management ITM Software Market
Security Software
Network Camera and Video Analytics Market
Security Software
Security Testing Market
Security Software
Personal Data Recovery Software Market
Security Software
Global Wireless Intrusion Prevention System Market
Security Software
Global Network Security Software Market
Security Software
Japan Mobile Biometrics Market
Security Software
Employee Computer Monitoring Software Market
Security Software
Next-Generation Intrusion Prevention System (NGIPS) Market
Security Software
Managed Security Services Market
Security Software
Devsecops Market
Security Software
United States Lawful Interception Market
Security Software
Global Advanced Authentication Market
Security Software
Digital Risk Protection Platform Market
Security Software
Global Data Protection As a Service (Dpaas) Market