
 Global Automotive Lithium Ion Battery Controller Market | 2026-2036
Global Automotive Lithium Ion Battery Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Lithium Ion Battery Controller Market Intelligence
South Korea's significant investment in domestic battery component production is narrowing the historical technology gap with semiconductor giants. Texas Instruments Incorporated leverages its extensive analog and embedded processing portfolio to offer integrated solutions. Infineon Technologies AG dominates the market for power semiconductors essential for battery management. Meanwhile, NXP Semiconductors specializes in secure communication interfaces for advanced battery systems.
An automotive lithium-ion battery controller is a sophisticated electronic circuit that manages and protects the battery pack in a vehicle. It monitors key parameters like voltage, current, and temperature to calculate the State of Charge (SOC) and ensure safe operation. The shift toward smart controllers is accelerating, as they provide superior diagnostics and predictive maintenance capabilities compared to older analog designs. Among applications, the Electric Vehicles segment drives volume, with controllers being a critical component for performance and range.
Regulatory frameworks such as the US EPA's emissions standards and China's GB standards for battery safety create stringent design constraints. The EU's forthcoming battery passport requirements under the Green Deal further compel manufacturers to integrate advanced data tracking into controllers. Success for controller suppliers depends on their ability to develop platforms that are adaptable to this fragmented and evolving global regulatory landscape.
Market Dynamics
The evolution of battery controllers is now dictated by regulatory demands for lifecycle data transparency. This global push, exemplified by the EU Green Deal, shifts design priorities from pure operational safety to include comprehensive data logging and reporting capabilities for the entire battery lifespan.
Growth Catalysts
- EV Production Volume:The sheer scale of electric vehicle manufacturing, particularly centered in China, provides a massive and sustained volume demand for advanced battery controller units.
- Smart Controller Adoption:A technical shift towards smart controllers that offer predictive maintenance and enhanced diagnostics improves EV range and reliability, creating strong pull from automotive OEMs.
- Regulatory Mandates:Forthcoming rules like the EU's battery passport requirement make advanced data-logging controllers a non-negotiable component for market access, compelling investment in the technology.
Market Restraints
- Semiconductor Supply Concentration:The reliance on specialized power semiconductors, a market dominated by a few firms like Infineon, exposes controller manufacturers to supply chain volatility and pricing power from chipmakers.
- High Development Costs:Designing and validating automotive-grade controllers that meet stringent safety standards like ISO 26262 requires significant R&D investment and long development cycles, creating high barriers to entry.
- Software Integration Complexity:Integrating sophisticated State of Charge algorithms and predictive analytics software with robust hardware is a major technical hurdle, risking project delays and cost overruns for suppliers.
Strategic Opportunities
- Second-Life Battery Systems:The growing market for used EV batteries in stationary energy storage applications creates a new segment for specialized controllers designed for grid-balancing and commercial power management.
- Wireless BMS Integration:Combining secure communication interfaces with core controller functions to enable wireless battery management systems offers a path to reduce vehicle weight, cost, and assembly complexity.
- Adaptable Regulatory Platforms:Developing a modular controller architecture that can be easily adapted to meet the fragmented and evolving safety and data regulations in the US, EU, and China presents a key opportunity.
Industry Challenges
- Talent Scarcity:A persistent shortage of engineers who possess a combination of expertise in power electronics, embedded software development, and battery electrochemistry constrains product development capacity across the industry.
- Standardization Gaps:The absence of a universal communication protocol for battery data exchange between different vehicle systems and charging infrastructure complicates interoperability and increases design costs for suppliers.
- Compliance Burden:Navigating the complex certification processes required by disparate global standards, including China's GB standards and US EPA rules, adds significant time and expense to product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Lithium Ion Battery Controller Market |
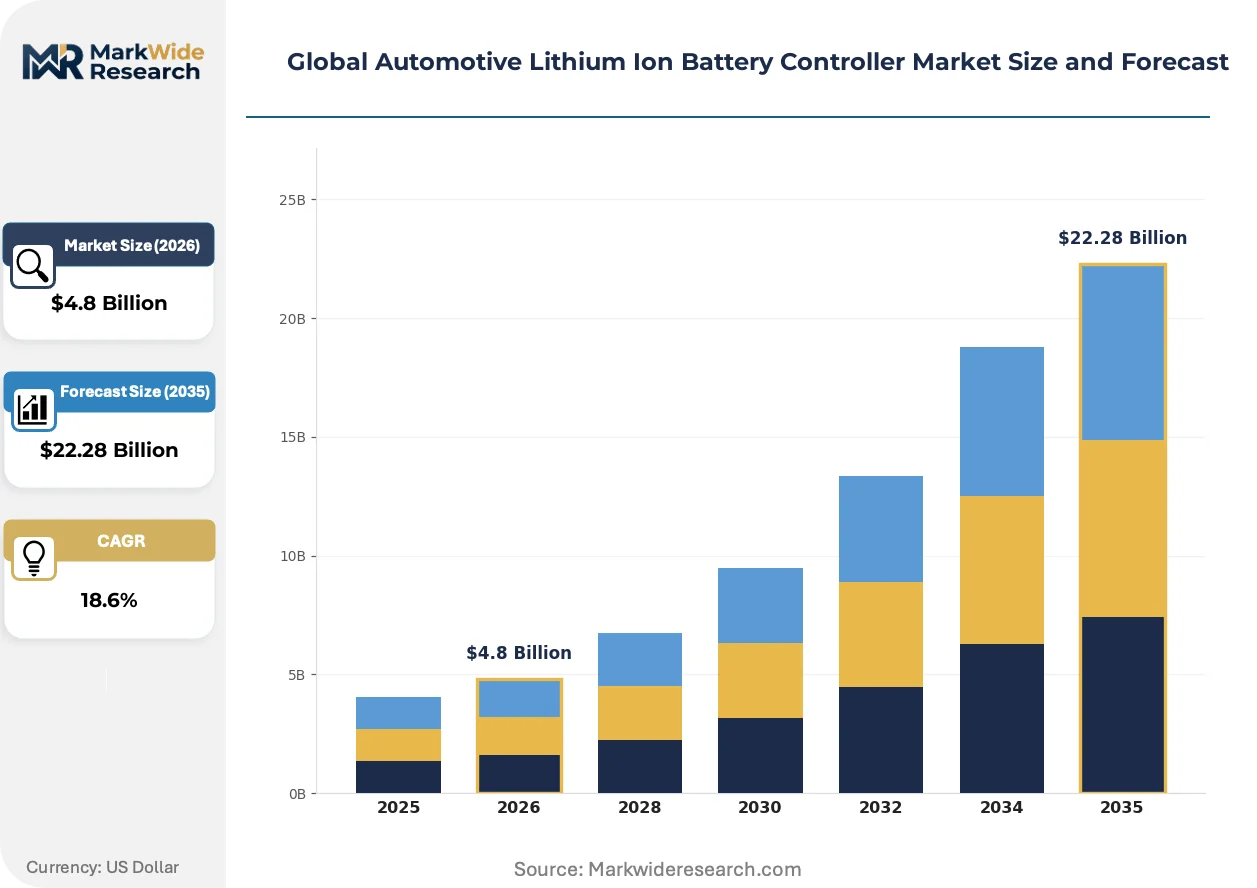
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Management Systems, Thermal Management Systems, Power Distribution Units, Energy Management Systems Application: Electric Vehicles, Hybrid Vehicles, Plug-in Hybrid Vehicles, Energy Storage Systems End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Technology: Analog Controllers, Digital Controllers, Smart Controllers, Custom Controllers |
| Companies Covered | Texas Instruments Incorporated, NXP Semiconductors, Infineon Technologies AG, Microchip Technology Inc, Maxim Integrated, Schneider Electric, Honeywell International Inc, Eternity Power Solutions Pvt. Ltd, A123 Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Lithium Ion Battery Controller Market Strategic Shifts & Innovations
Software-defined capabilities and advanced connectivity are transforming the battery controller from a passive component into an active, intelligent hub. This evolution focuses on vehicle energy management, data analytics, and future grid interaction, moving far beyond simple monitoring and protection functions.
Wireless Battery Management System (wBMS) technology uses radio frequency to transmit data between cell monitoring units and the central controller. Automakers are increasingly exploring wBMS to simplify battery pack assembly, reduce the weight and cost of extensive wiring harnesses, and improve manufacturing scalability. This technology is collapsing the distinction between the battery pack's physical and digital architecture, enabling more flexible and modular vehicle platform designs.
The EU Green Deal's battery passport mandate is a significant regulatory driver. This rule will require a digital record tracking a battery's origin, materials, carbon footprint, and health status throughout its lifecycle, with the controller serving as the primary data gateway. The electric vehicle segment is most affected, forcing controller manufacturers to integrate secure, tamper-proof data logging and transmission capabilities directly into their core hardware designs.
Automotive OEMs are shifting their procurement strategy from buying discrete components to sourcing integrated system-level solutions. This change disrupts the traditional model of selling individual microcontrollers or power ICs, creating an advantage for suppliers that can provide a pre-validated platform combining hardware and software. This trend is most prominent within high-volume EV programs in China and Europe, where speed to market and system reliability are paramount.
Global Automotive Lithium Ion Battery Controller Market Segmentation
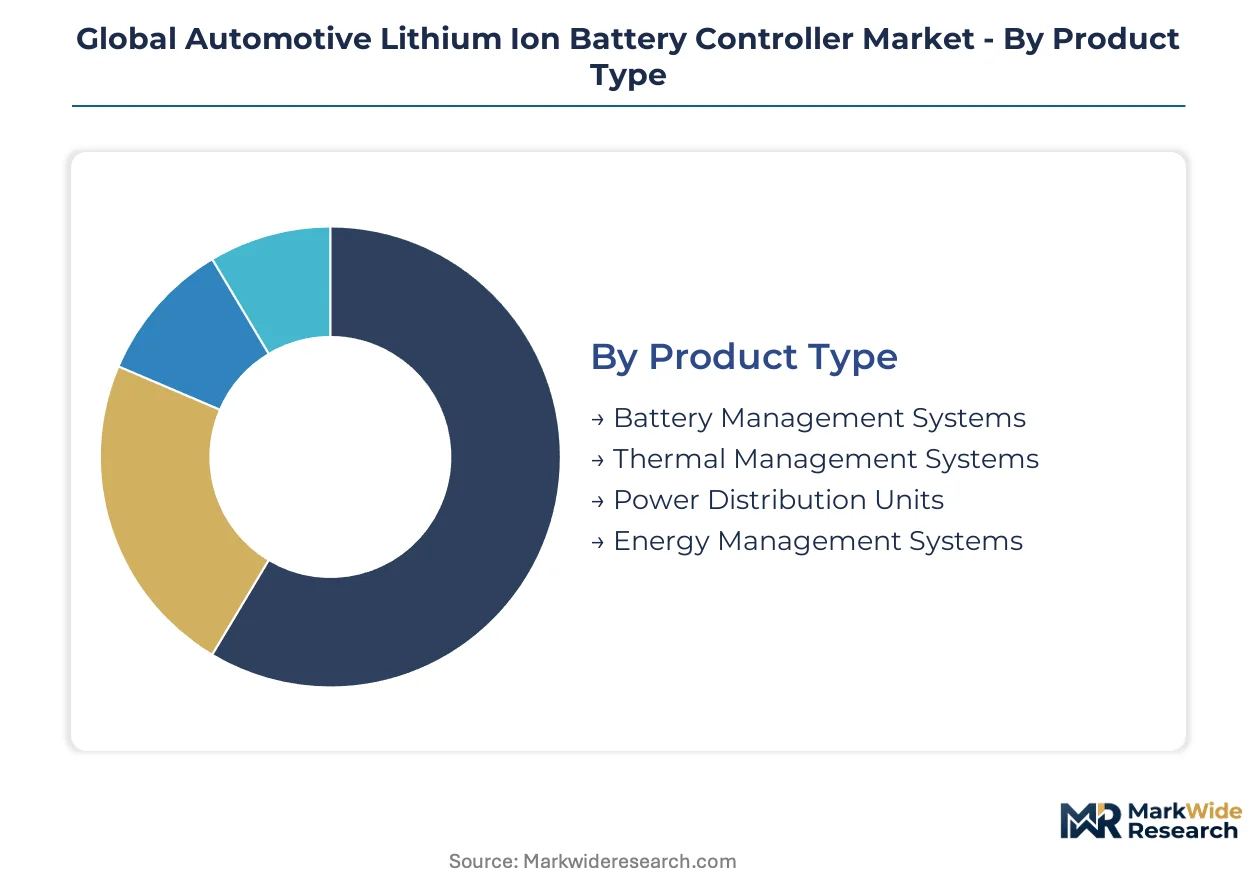
Market segmentation provides a detailed framework for understanding the diverse requirements and opportunities within the global automotive lithium-ion battery controller industry. Each segment reflects unique functional demands, integration complexities, and market dynamics shaping product development and adoption cycles.
Product Type:
Different product types within battery controllers exhibit varying development and integration cycle times for automotive applications.
- Battery Management Systems:This core electronic circuit continuously monitors and manages the battery pack's state of charge, state of health, and temperature, ensuring safe and efficient operation. Demand concentrates in high-volume electric vehicle production, particularly within China, driven by stringent safety regulations.
- Thermal Management Systems:These controllers regulate the battery's temperature to optimize performance, extend lifespan, and prevent thermal runaway events. High-performance electric vehicles and rapid charging infrastructure in Europe create significant demand for advanced thermal control.
- Power Distribution Units:Integrates high-voltage power routing with essential safety features for the entire vehicle electrical system.
- Energy Management Systems:Optimizes power flow between the battery, electric motor, and auxiliary vehicle systems for maximum efficiency and range.
Battery Management Systems dominate the installed base for current vehicle platforms. Thermal Management Systems are where expansion concentrates for next-generation EV designs.
Application:
Application segments demonstrate diverse volume requirements and performance specifications across the automotive landscape.
- Electric Vehicles:Dedicated controllers for full battery-electric powertrains manage high voltage, complex charging profiles, and energy regeneration. Global EV manufacturing, especially strong in China and Europe, drives substantial demand due to emissions standards.
- Hybrid Vehicles:Controllers manage smaller battery packs for regenerative braking and supplemental power, requiring seamless integration with internal combustion engines. Transitional markets like Japan and parts of North America show sustained demand for fuel-efficient hybrid solutions.
- Plug-in Hybrid Vehicles:Controllers for larger battery packs than conventional hybrids enable extended electric-only range and external charging capabilities.
- Energy Storage Systems:Specialized controllers for stationary battery packs manage grid interaction, long-duration cycling, and second-life battery applications.
Electric Vehicles represent the largest current consumption segment. Energy Storage Systems are expanding most quickly as second-life battery applications grow.
End User:
End-user segments exhibit distinct procurement patterns and integration requirements for battery controller units.
- OEMs:Automotive manufacturers require highly customized, automotive-grade controllers integrated directly into their vehicle platforms during initial production. High-volume EV programs from established automakers in Germany and the US prioritize system reliability and safety.
- Aftermarket Providers:Suppliers provide replacement or upgrade controllers, often focusing on compatibility with existing vehicle architectures and diverse models. Demand stems from older EV models and specialized fleet conversions, with growth in regions seeking cost-effective maintenance solutions.
- Fleet Operators:Organizations managing large vehicle fleets require robust, telematics-enabled controllers for operational efficiency and predictive maintenance across their assets.
- Research Institutions:Academic and private research entities utilize controllers for developing new battery chemistries, advanced energy management algorithms, and future vehicle concepts.
OEMs dictate the majority of controller design specifications. Fleet Operators are increasingly influencing controller features for data logging and remote diagnostics.
Technology:
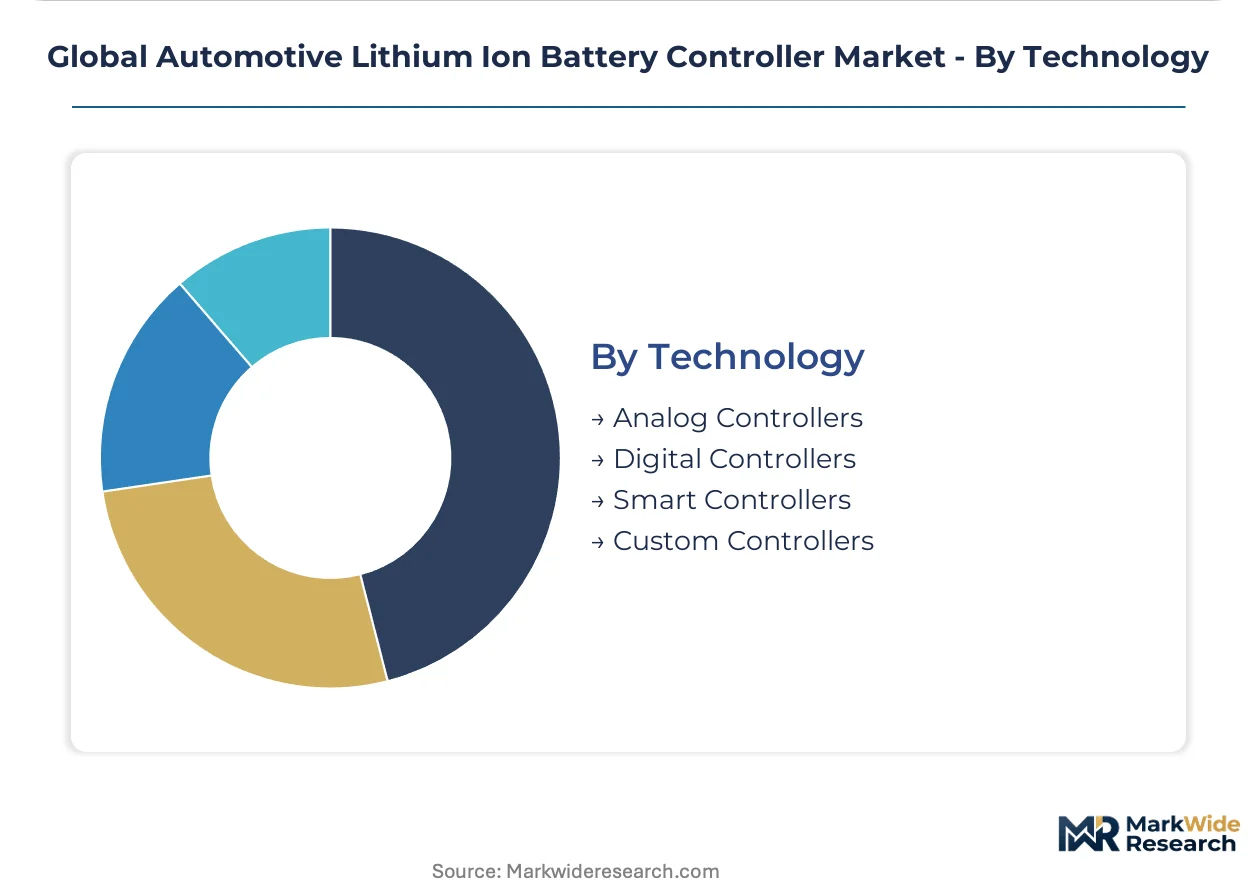
Technology segments reflect varying levels of maturity and complexity in controller design and embedded functionality.
- Smart Controllers:Advanced controllers incorporate AI/ML for predictive analytics, enhanced diagnostics, and adaptive energy management capabilities. Premium EV segments and next-generation autonomous vehicles demand these units for superior performance and range.
- Digital Controllers:Microprocessor-based controllers offer programmable logic, precise control algorithms, and digital communication interfaces for robust operation. Mainstream EV and PHEV platforms favor these controllers for their flexibility and integration with vehicle electronic control units.
- Analog Controllers:Basic electronic circuits provide fundamental voltage and current protection, primarily found in older or lower-cost battery systems.
- Custom Controllers:Application-specific controllers developed for niche vehicles, specialized battery chemistries, or unique performance requirements.
Digital Controllers currently hold the largest market share. Smart Controllers are gaining share fastest due to increasing demand for advanced features.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive lithium-ion battery controller market exhibits significant regional concentration, particularly in areas with established electric vehicle manufacturing and advanced semiconductor ecosystems. Key demand drivers for these controllers include stringent regulatory mandates and the accelerating shift towards smart controller technologies. This regional focus shapes both production capabilities and market access requirements for suppliers.
China
China's robust electric vehicle manufacturing sector drives substantial demand for advanced battery controllers. The nation's GB standards for battery safety impose stringent design constraints on components. Shanghai and the Yangtze River Delta region continue to anchor significant EV production and supply chain development.
Germany
German automotive OEMs require highly customized controllers for their high-volume EV programs, prioritizing system reliability. The EU Green Deal's battery passport mandate compels advanced data tracking integration into controllers. Major automotive centers in Bavaria and Baden-Württemberg lead the development of next-generation EV designs.
United States
United States automotive manufacturers prioritize sophisticated controllers for their growing electric vehicle production. US EPA emissions standards and the Inflation Reduction Act (IRA) influence battery component sourcing and design. Michigan's automotive industry and California's tech hubs contribute to controller innovation and integration efforts.
South Korea
South Korea's significant investment in domestic battery component production fuels demand for advanced controllers. The country's initiatives aim to narrow the technology gap with established semiconductor leaders. The Seoul Capital Area hosts key research institutions and manufacturing facilities driving battery management system advancements.
Japan
Japan's automotive sector maintains sustained demand for controllers, particularly within its strong hybrid vehicle segment. METI initiatives support advanced battery research and development, alongside JIS standards for component quality. The Kanto region, including Tokyo, remains a central hub for automotive R&D and manufacturing integration.
Global Automotive Lithium Ion Battery Controller Market Key Industry Players
Specialized semiconductor manufacturers and integrated solutions providers split the market for automotive lithium-ion battery controllers. This market exhibits a tiered structure, with a few dominant power semiconductor firms supplying critical components to a broader ecosystem. Strategic archetypes include large-scale integrated circuit suppliers, often with extensive analog portfolios, and niche battery management system specialists focusing on software integration. Companies engage in strategic partnerships and continuous portfolio diversification to address evolving regulatory demands and technological shifts in the automotive sector.
Within the integrated solutions segment, Texas Instruments Incorporated exemplifies a supplier leveraging an extensive analog and embedded processing portfolio to offer comprehensive solutions for battery control. NXP Semiconductors occupies a position as a specialist in secure communication interfaces, crucial for advanced battery systems and wireless BMS integration. Infineon Technologies AG represents a dominant force in the power semiconductor market, providing essential components for power management functions across the automotive industry. These companies anchor the supply of foundational technologies that enable sophisticated battery controller designs.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Infineon Technologies AG |
| Microchip Technology Inc |
| Maxim Integrated |
| Schneider Electric |
| Honeywell International Inc |
| Eternity Power Solutions Pvt. Ltd |
| A123 Systems |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta region's extensive battery controller production capacity directly influences downstream pricing power for automotive OEMs. This concentration impacts negotiation leverage across the supply chain.
Pricing Analysis
The EU Green Deal's battery passport dictates the pricing tier structure for advanced automotive battery controllers. Contract-based long-term offtake agreements dominate, driven by extensive R&D and validation cycles. Price differentiation stems from ISO 26262 certification levels and customization for specific OEM platforms. Aftermarket providers exhibit the highest price sensitivity, while OEMs prioritize performance and reliability.
Supply Chain Analysis
US export controls on advanced semiconductor technology limit the flow of critical components for battery controllers. Supply concentrates heavily in China, South Korea, and Germany. The industry relies on specialized power semiconductors and embedded microcontrollers as key inputs. Single-source vulnerability from dominant chipmakers like Infineon Technologies AG presents a significant supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive lithium-ion battery controller market reflects a significant shift in buyer power, driven by OEM consolidation into integrated system-level solutions. This trend forces suppliers to adapt their offerings beyond discrete components.
For Market Incumbents: Build an intellectual property moat around advanced software and secure communication protocols. Invest heavily in Wireless BMS integration and AI/ML algorithms for predictive maintenance to counter emerging niche specialists. Secure long-term supply agreements with key semiconductor partners to mitigate supply chain volatility. Focus R&D on adaptable regulatory platforms to meet evolving global standards like the EU battery passport.
For New Entrants and Emerging Players: Build out specialized controller solutions for the rapidly expanding second-life battery systems market. Target the energy storage systems segment, which offers lower barriers to entry compared to automotive OEMs. Develop modular architectures adaptable to specific regional standards, such as China's GB standards, for faster market access. Emphasize cost-effective, high-reliability designs for fleet operators seeking predictive maintenance capabilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-centric specialists with strong embedded processing expertise. The long-term viability for advanced controller firms remains robust, driven by sustained EV growth and stringent regulatory mandates. Seek acquisition targets possessing proprietary AI/ML algorithms for predictive diagnostics or established secure communication interfaces. Widespread adoption of Wireless BMS technology across multiple OEM platforms serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Standardizing controller architectures reduces R&D costs and accelerates deployment for diverse vehicle models. |
| Software-Defined Battery Management | Investing in software-defined capabilities enables over-the-air updates and advanced diagnostic features for OEMs. |
| Strategic Semiconductor Partnerships | Securing long-term alliances with chipmakers like Infineon Technologies AG mitigates supply chain risks. |
| Wireless BMS Integration | Developing wBMS solutions reduces vehicle weight and assembly complexity for automotive manufacturers. |
| EU Green Deal Compliance Solutions | Integrating battery passport data tracking ensures market access and meets evolving European regulatory requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted for primary insights into the automotive lithium-ion battery controller market. Interviews included OEM platform engineers, Tier 1 procurement leads, battery cell specialists, and fleet operators. Secondary validation drew from vehicle production databases, US EPA and China GB standards regulatory filings. This approach facilitated bottom-up and top-down triangulation of market data.
Forecast calibration integrated historical market data with expert consensus across the analysis window. Segmentation dimensions modeled included product type, application, end-user, technology, and content per vehicle. Compound annual growth rates were derived from linear regression and market penetration models. Key forecast inputs included global electric vehicle production forecasts and anticipated battery chemistry evolution.
Stress conditions across semiconductor supply and electric vehicle adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions, though significant geopolitical events or rapid battery chemistry evolution could alter projections. Material shifts in global trade policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Scooter Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
Solar Car Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Electric Vehicle Communication Controller Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market