
 Central and Eastern Europe E-Bike Market | 2026-2036
Central and Eastern Europe E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Central and Eastern Europe E-Bike Market Outlook
CE marking under the EU Machinery Directive is collapsing the supplier base to technically qualified assemblers. Robert Bosch GmbH leverages its Stuttgart-developed drive systems to anchor premium OEM partnerships across the region. Riese & Müller differentiates through in-house frame production and Made-in-Germany positioning. Cube Bikes competes on volume scale, sustaining one of Europe's largest bicycle manufacturing footprints from Waldershof.
Central and Eastern Europe e-bikes are pedal-assisted bicycles integrating electric motors of 250W continuous rated power, speed limitation at 25 km/h, and rechargeable battery packs primarily lithium-ion chemistry for propulsion assistance in urban mobility and light logistics. City E-Bikes dominate unit sales where flat terrain and short commute distances favor cost-optimized hub motor configurations. Mountain E-Bikes capture margin concentration through mid-drive systems and suspension integration demanded by Outdoor Enthusiasts in Carpathian and Alpine-adjacent terrain. Cargo E-Bikes represent the fastest structural expansion as Delivery Services in Budapest and Warsaw replace van-based last-mile operations.
EU F-Gas Regulation and REACH compliance on battery supply chains shape component sourcing decisions, while national regulators in Poland and the Czech Republic enforce type-approval alignment with EU vehicle framework directives. ECHA substance restrictions on nickel and cobalt processing are forcing cell suppliers to document due diligence across raw material procurement. Stakeholders must monitor whether proposed EU Battery Regulation repairability mandates will retrofit obligations onto existing fleet operators or apply only to new registrations.
Market Dynamics
EU Green Deal cycling infrastructure mandates are compressing procurement timelines across municipal bike-sharing programs, forcing fleet operators to accelerate replacement cycles and consolidate supplier relationships around CE-marked assemblers.
Growth Catalysts
- EU Machinery Directive CE marking:Technical compliance requirements are filtering out uncertified component suppliers and elevating qualified regional assemblers into preferred vendor status for municipal procurement.
- Poland's Silesian Voivodeship fleet expansion:Municipal bike-sharing operators in Katowice and surrounding industrial cities are placing multi-year orders for hub-motor city e-bikes to replace aging mechanical fleets.
- Lithium-ion cell chemistry advances:Energy density improvements in NMC and LFP cell formulations are extending range capabilities without weight penalties, broadening addressable commute distances for urban riders.
Market Restraints
- Cobalt and nickel price volatility:ECHA substance restrictions on raw material processing are increasing cell documentation costs and compressing margin structures for battery pack integrators serving the region.
- Mid-drive motor supply concentration:Stuttgart-developed drive system production remains captive to a limited supplier base, creating allocation bottlenecks for premium mountain e-bike OEMs.
- EU F-Gas Regulation compliance costs:Thermal management system requirements for battery packs are adding certification overhead that disproportionately burdens smaller frame assemblers without in-house engineering.
Strategic Opportunities
- Czech Republic Moravian corridor underpenetration:Brno and Ostrava municipal transit authorities lack deployed bike-sharing infrastructure relative to Warsaw and Budapest, creating first-mover whitespace for fleet operators.
- Cargo e-bike last-mile logistics:Budapest delivery services are piloting van-replacement programs for parcel distribution in historic districts with vehicle access restrictions.
- EU Battery Regulation repairability mandates:Proposed standardization of swappable battery architectures could retrofit obligations onto existing fleet operators, creating aftermarket service revenue pools.
Industry Challenges
- REACH documentation skill scarcity:Battery supply chain due diligence requirements for cobalt and nickel sourcing are outpacing available compliance personnel at regional distributors.
- Type-approval timeline compression:Polish and Czech national regulators enforcing EU vehicle framework alignment are extending certification cycles for new frame-motor combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central and Eastern Europe E-Bike Market |
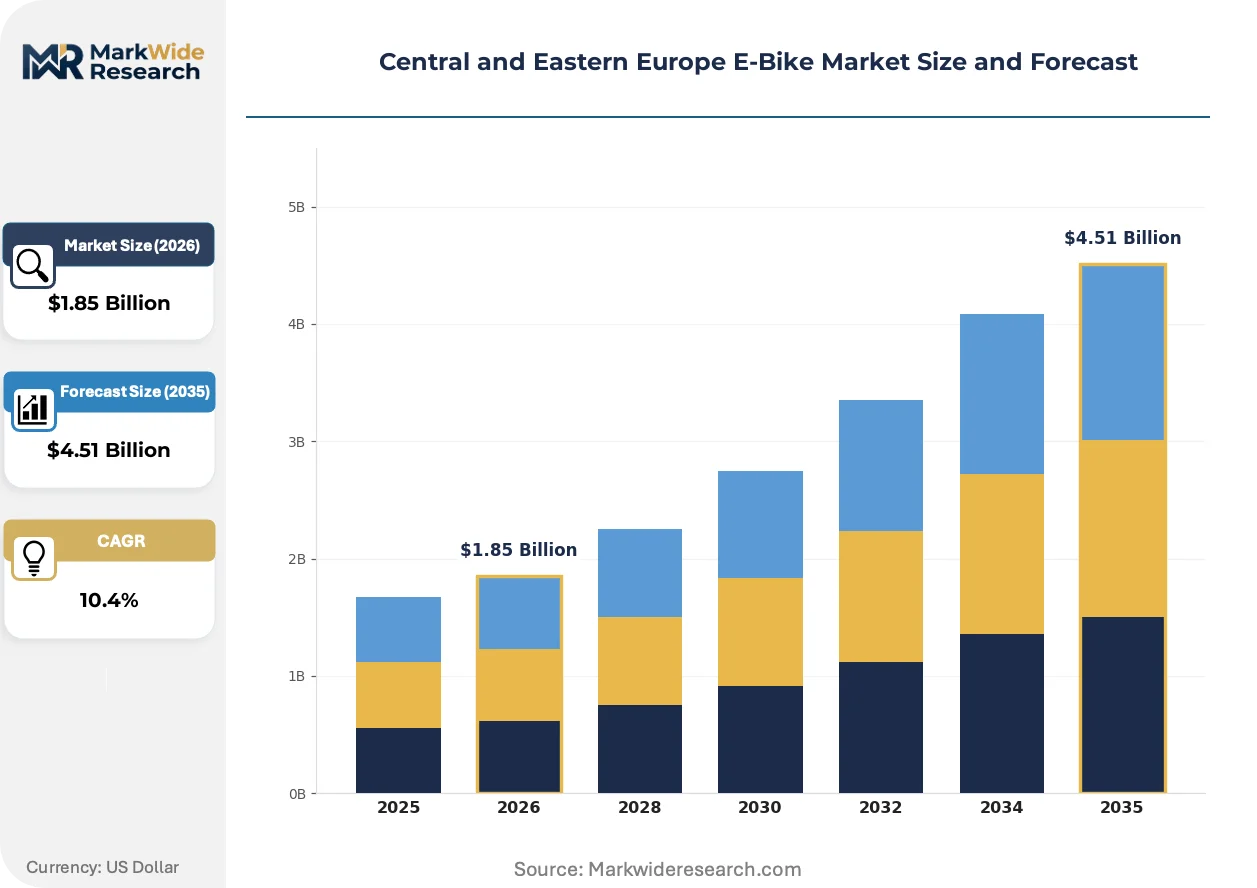
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Cargo E-Bikes, Folding E-Bikes End User: Commuters, Outdoor Enthusiasts, Delivery Services, Tourists Battery Type: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Lithium Polymer Sales Channel: Online Retailers, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Yamaha Motor Co, Riese & Müller, Giant Manufacturing Co. Ltd, Canyon Bicycles, Cube Bikes, Merida Industry Co. Ltd, Robert Bosch GmbH, BH Bikes, Accell Group N.V, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central and Eastern Europe E-Bike Market Strategic Shifts
Active torque sensor integration is replacing cadence-based pedal assist across mid-tier city e-bike offerings, altering rider experience expectations and component sourcing patterns for frame assemblers.
Mid-drive torque sensor systems with strain-gauge crank integration are delivering proportional power modulation that mirrors rider effort. Polish and Czech urban commuters upgrading from mechanical bicycles or hub-motor e-bikes are specifying these configurations in direct-to-consumer channel purchases. The technology is displacing basic cadence-sensor hub motors in the 1,500-2,500 euro price band, compressing volumes for legacy motor suppliers without torque-sensing IP.
EU Battery Regulation draft provisions on repairability and second-life certification are mandating modular pack architectures with standardized cell interfaces. Frame manufacturers must redesign downtube enclosures and locking mechanisms to accommodate swappable formats. Cargo e-bike fleet operators in Warsaw and Budapest are most exposed, as their high-utilization vehicles face accelerated compliance deadlines relative to consumer retail channels.
Direct-to-consumer channel penetration is fragmenting traditional bicycle retail in Poland's Masovian Voivodeship. Independent dealers in Warsaw are unbundling after-sales service from hardware margin, charging flat-rate assembly and maintenance fees for online-purchased units. This behavior is most visible among Outdoor Enthusiasts in Carpathian-adjacent terrain, where mountain e-bike buyers research specifications digitally but require local suspension tuning expertise.
Central and Eastern Europe E-Bike Market Segmentation
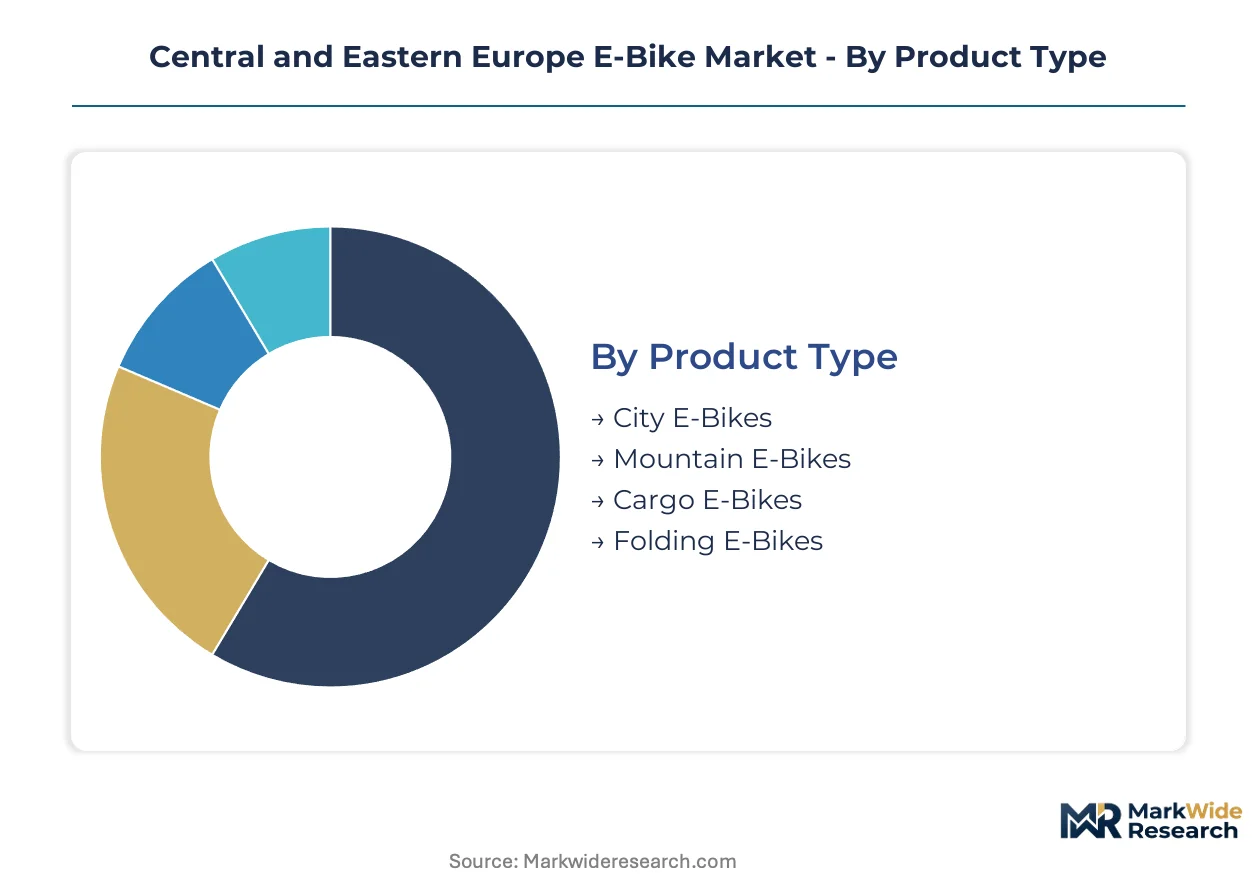
E-bike demand across Central and Eastern Europe fragments across distinct use cases, battery chemistries, and procurement channels. Each segment carries unique technical requirements and regulatory exposure that reshape competitive positioning for frame assemblers and component suppliers.
Product Type:
Domestic consumption concentrates on urban-optimized configurations, while export-oriented production from Waldershof and Czech assembly plants supplies premium mountain variants to Western European markets.
- City E-Bikes:Hub-motor configurations with 250W continuous rated power dominate unit volumes. Flat terrain across Poland's Masovian Voivodeship and Hungary's Great Plain favors cost-optimized builds for municipal bike-sharing procurement.
- Mountain E-Bikes:Mid-drive torque-sensor systems with 85Nm peak output command premium positioning. Carpathian-adjacent terrain in southern Poland and northern Slovakia drives specification for suspension integration and battery thermal management.
- Cargo E-Bikes:Extended wheelbase frames with dual-battery architectures support last-mile logistics in Warsaw and Budapest historic districts with vehicle access restrictions.
- Folding E-Bikes:Compact lithium-polymer packs and hinge-reinforced aluminum frames address multi-modal commuters in Prague and Bratislava transit corridors.
City E-Bikes commands the established base. The steepest expansion runs through Cargo E-Bikes.
End User:
Procurement authority concentrates with fleet operators and municipal transit authorities, while individual purchasing decisions fragment across price-performance thresholds.
- Commuters:Daily ride distances under 15 kilometers favor hub-motor city configurations. CE marking under the EU Machinery Directive filters supplier eligibility for corporate subsidy programs in Poland and the Czech Republic.
- Outdoor Enthusiasts:Technical specification research via direct-to-consumer channels precedes local dealer service relationships. Carpathian trail networks and Alpine-adjacent terrain in Slovakia drive mid-drive motor demand.
- Delivery Services:High-utilization fleet economics prioritize swappable battery architectures and modular component replacement. Budapest parcel operators pilot van-replacement programs under EU Green Deal logistics mandates.
- Tourists:Seasonal rental demand concentrates in Krakow and Prague historic centers, with hub-motor city configurations specified for flat urban terrain and low maintenance requirements.
Commuters anchor volume concentration. Delivery Services are climbing the fastest as fleet electrification timelines compress.
Battery Type:
Cell chemistry selection determines thermal management requirements, REACH documentation burden, and weight-range tradeoffs across terrain types.
- Lithium-Ion:NMC and LFP cylindrical cell formats deliver 500Wh+ capacities within 3kg pack weights. ECHA substance restrictions on nickel and cobalt processing force supply chain due diligence documentation.
- Lead Acid:Flooded and AGM variants persist in price-sensitive municipal procurement where total cost of ownership calculations exclude energy density premiums. Weight penalties restrict deployment to flat terrain applications.
- Nickel-Metal Hydride:Intermediate energy density suits cold-climate performance in Polish Silesian Voivodeship industrial cities where lithium-ion thermal management adds cost.
- Lithium Polymer:Pouch cell formats enable frame-integrated downtube enclosures with custom form factors. Folding e-bike manufacturers in the Czech Republic specify these for space-constrained packaging.
Lithium-Ion holds the technology leadership position. Lithium Polymer is gaining share fastest in premium compact segments.
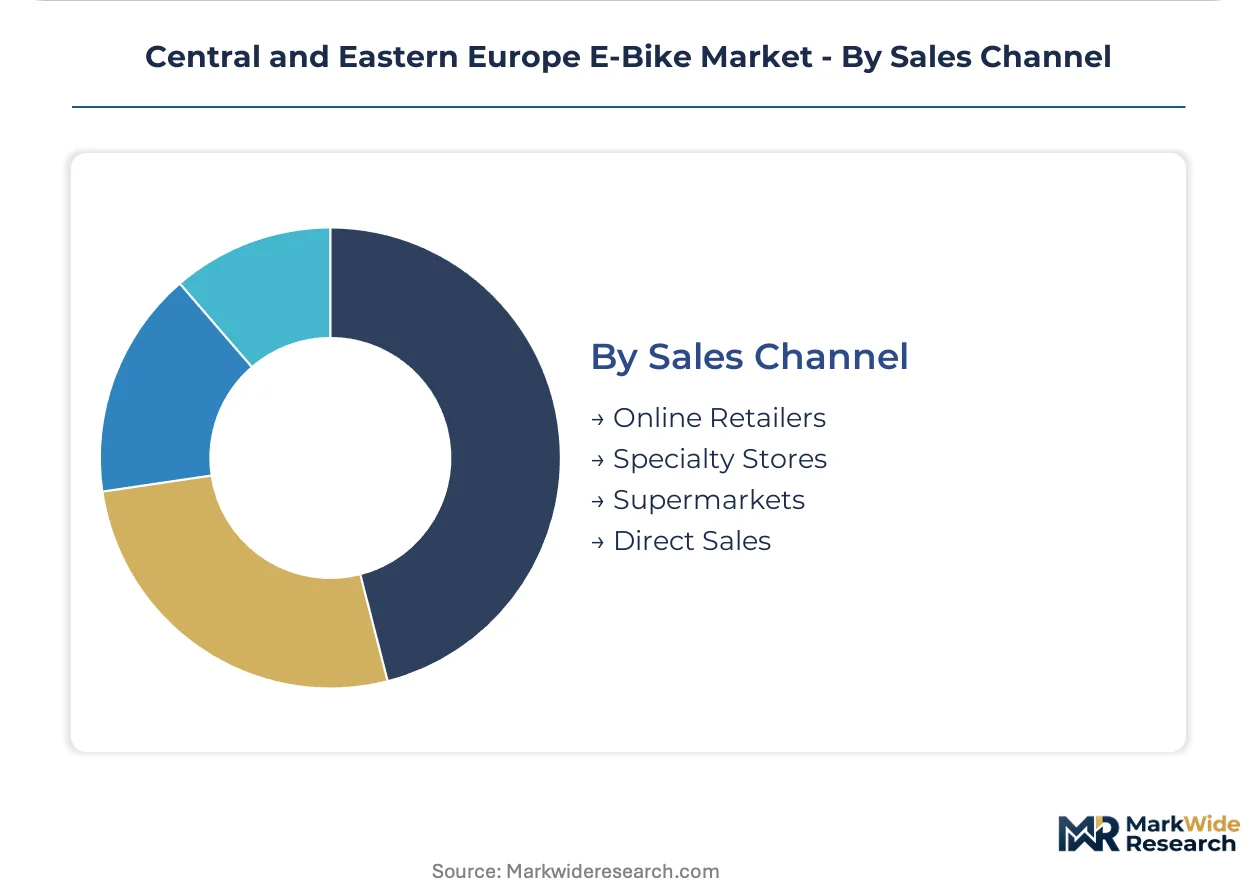
Sales Channel:
Channel strategy determines margin capture, after-sales service obligation, and exposure to direct-to-consumer price compression.
- Online Retailers:Platform-aggregated demand fragments across price tiers. Polish consumers in Masovian Voivodeship research specifications digitally but require independent dealer assembly for warranty validation.
- Specialty Stores:Technical consultation and suspension tuning services defend margin against pure-play digital competitors. Mountain e-bike buyers in Carpathian-adjacent regions prioritize local expertise.
- Supermarkets:Mass-market hub-motor city configurations with limited service support capture impulse purchases. Price positioning aligns with mechanical bicycle replacement cycles.
- Direct Sales:Manufacturer-owned channels bypass distributor margins for premium mid-drive configurations. Stuttgart-developed drive system suppliers anchor these relationships with technical training obligations.
Specialty Stores retain the premium positioning. Online Retailers are expanding most quickly as digital research behavior hardens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal cycling infrastructure mandates are accelerating municipal procurement timelines across Central and Eastern Europe, compressing replacement cycles for aging mechanical fleets and elevating CE-marked assemblers into preferred vendor status.
Poland
Silesian Voivodeship industrial cities and Masovian Voivodeship municipal operators are placing multi-year hub-motor city e-bike orders. The country's national transport regulator enforces EU vehicle framework type-approval alignment for all new registrations. Katowice and Warsaw bike-sharing programs are consolidating supplier relationships around technically qualified regional assemblers.
Czech Republic
Brno and Ostrava municipal transit authorities remain underpenetrated relative to Warsaw and Budapest, creating first-mover whitespace for fleet operators. ECHA REACH compliance requirements on battery supply chains are forcing cell suppliers to document due diligence across cobalt and nickel procurement. Prague folding e-bike manufacturers specify lithium-polymer pouch formats for space-constrained multi-modal commuter packaging.
Hungary
Budapest delivery services are piloting van-replacement cargo e-bike programs for parcel distribution in historic districts with vehicle access restrictions. EU F-Gas Regulation thermal management requirements are adding certification overhead for battery pack integrators serving high-utilization fleet operators. The capital's municipal procurement office is evaluating swappable battery architectures for compliance with proposed EU Battery Regulation repairability mandates.
Slovakia
Carpathian-adjacent terrain in northern regions drives mid-drive torque-sensor system demand among Outdoor Enthusiasts. The country's alignment with EU Machinery Directive CE marking filters supplier eligibility for corporate subsidy programs. Bratislava transit corridors are deploying compact folding e-bike configurations to address last-kilometer connectivity gaps.
Romania
Bucharest urban congestion charges are redirecting commuter preference toward pedal-assisted alternatives for sub-15 kilometer daily rides. National regulators enforce EU Green Deal cycling infrastructure compliance deadlines for municipal fleet electrification. Cluj-Napoca and Timișoara are emerging as logistics hubs where cargo e-bike operators test last-mile delivery economics against van-based alternatives.
Central and Eastern Europe E-Bike Market Competitive Environment
Listed leaders compete with private specialists across technical certification and municipal procurement access. The supplier base compresses around CE-marked assemblers as EU Machinery Directive compliance filters out uncertified component sources. Three archetypes dominate: Stuttgart-developed drive system suppliers anchoring premium OEM partnerships, volume-scale frame manufacturers with captive production footprints, and in-house engineering specialists differentiating through Made-in-Germany positioning. Consolidation pressures favor backward integration into motor production and strategic partnerships around battery cell supply.
Within the premium-tier vector, Riese & Müller and Canyon Bicycles exemplify engineering-intensive positioning. Robert Bosch GmbH anchors the component supply layer through drive system development. Cube Bikes occupies a scale-driven position among European frame assemblers. Yamaha Motor Co represents diversified motor manufacturing origin. Giant Manufacturing Co. Ltd and Merida Industry Co. Ltd sit within the Asia-origin volume production archetype. BH Bikes and Accell Group N.V exemplify regional European brand consolidation patterns.
| Leading Market Players |
|---|
| Yamaha Motor Co |
| Riese & Müller |
| Giant Manufacturing Co. Ltd |
| Canyon Bicycles |
| Cube Bikes |
| Merida Industry Co. Ltd |
| Robert Bosch GmbH |
| BH Bikes |
| Accell Group N.V |
| Others |
Value Chain & Pricing Dynamics
Multi-year fleet procurement contracts with take-or-pay clauses lock in hub-motor city e-bike volumes for Polish and Czech municipal operators while freezing component costs against lithium-ion cell price swings. These arrangements bind CE-marked assemblers to fixed-margin service tiers across the replacement cycle.
Pricing Analysis
Certification level creates the primary spread between premium mid-drive configurations and economy hub-motor builds. Three-tier pricing structure separates CE-marked municipal fleet units from direct-to-consumer retail models and unbundled assembly-service offerings. Pricing pressure stems from ECHA documentation costs for cobalt and nickel supply chains compressing battery pack integrator margins. Corporate subsidy program participants show lowest price sensitivity, while supermarket channel buyers exhibit acute cost consciousness.
Supply Chain Analysis
Strategic stockpiling of NMC and LFP cells dominates procurement behavior as assemblers buffer against nickel and cobalt price volatility. Manufacturing concentrates in Germany, Poland, and the Czech Republic for frame production, with cell supply anchored in South Korea and China. Stuttgart-developed drive systems create single-source vulnerability for premium mid-drive configurations. Distribution runs through independent dealers unbundling service from hardware margin, plus direct-to-consumer platforms requiring local assembly partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical compliance personnel scarcity across Poland and the Czech Republic is constraining battery supply chain documentation capacity, elevating qualified assemblers with in-house REACH expertise into preferred vendor status for municipal procurement.
For Market Incumbents: Compound backward integration into motor production to reduce allocation bottlenecks from Stuttgart-developed drive system suppliers. Secure captive lithium-ion cell supply through long-term offtake agreements with South Korean and Chinese producers to defend margin position against ECHA substance restriction compliance costs. For New Entrants and Emerging Players: Lead with swappable battery architecture specialization targeting Budapest and Warsaw cargo e-bike fleet operators facing accelerated EU Battery Regulation repairability mandates. Capture first-mover position in Brno and Ostrava municipal transit corridors where bike-sharing infrastructure remains underpenetrated relative to Warsaw. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet operators with multi-year municipal service contracts. Prioritize acquisition targets with established CE marking under the EU Machinery Directive and documented REACH compliance infrastructure. Monitor EU Battery Regulation final text for retrofit obligation scope as the inflection signal determining aftermarket service revenue pool depth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Reduces allocation risk from Stuttgart-developed drive system concentration. |
| CE Marking Pathway Investment | Unlocks municipal procurement eligibility under EU Machinery Directive compliance. |
| Swappable Battery Architecture Development | Positions fleet operators for EU Battery Regulation repairability mandate compliance. |
| Long-term Cell Supply Agreement | Hedges ECHA cobalt and nickel documentation cost escalation. |
| Direct-to-Consumer Service Unbundling | Captures assembly and maintenance margin from online retail channel growth. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with e-bike OEM procurement directors, municipal fleet operators, independent dealer service managers, and battery pack integrators; and secondary validation through EU vehicle framework directive filings, ECHA REACH registration databases, Polish and Czech national transport regulator type-approval records, and customs trade data on lithium-ion cell imports. Bottom-up unit shipment estimates from frame assemblers were triangulated against top-down municipal procurement budget disclosures.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, battery chemistry, end-user segment, and sales channel, with CAGRs derived from polynomial trend fitting to historical procurement cycles and elasticity-adjusted adoption curves. Key inputs included EU Green Deal cycling infrastructure mandate implementation timelines and lithium-ion cell energy density improvement curves.
Underlying assumptions cover EU Machinery Directive enforcement continuity and REACH documentation requirement stability, with deviation risk concentrated in EU Battery Regulation repairability mandate scope decisions and cobalt-nickel commodity price volatility. Practitioners should keep alternative scenarios live as regulatory finalization timelines and raw material supply chain restructuring evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Bike Kit Market
Electric Vehicles
Special Purpose Electric Vehicle Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
North America Wireless Electric Vehicle Charging Market
Electric Vehicles
China Solar E-Bike Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Japan Electric Vehicle Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market