
 Anode Material for Sodium-Ion Battery Market | 2026-2036
Anode Material for Sodium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Anode Material for Sodium-Ion Battery Market Insights
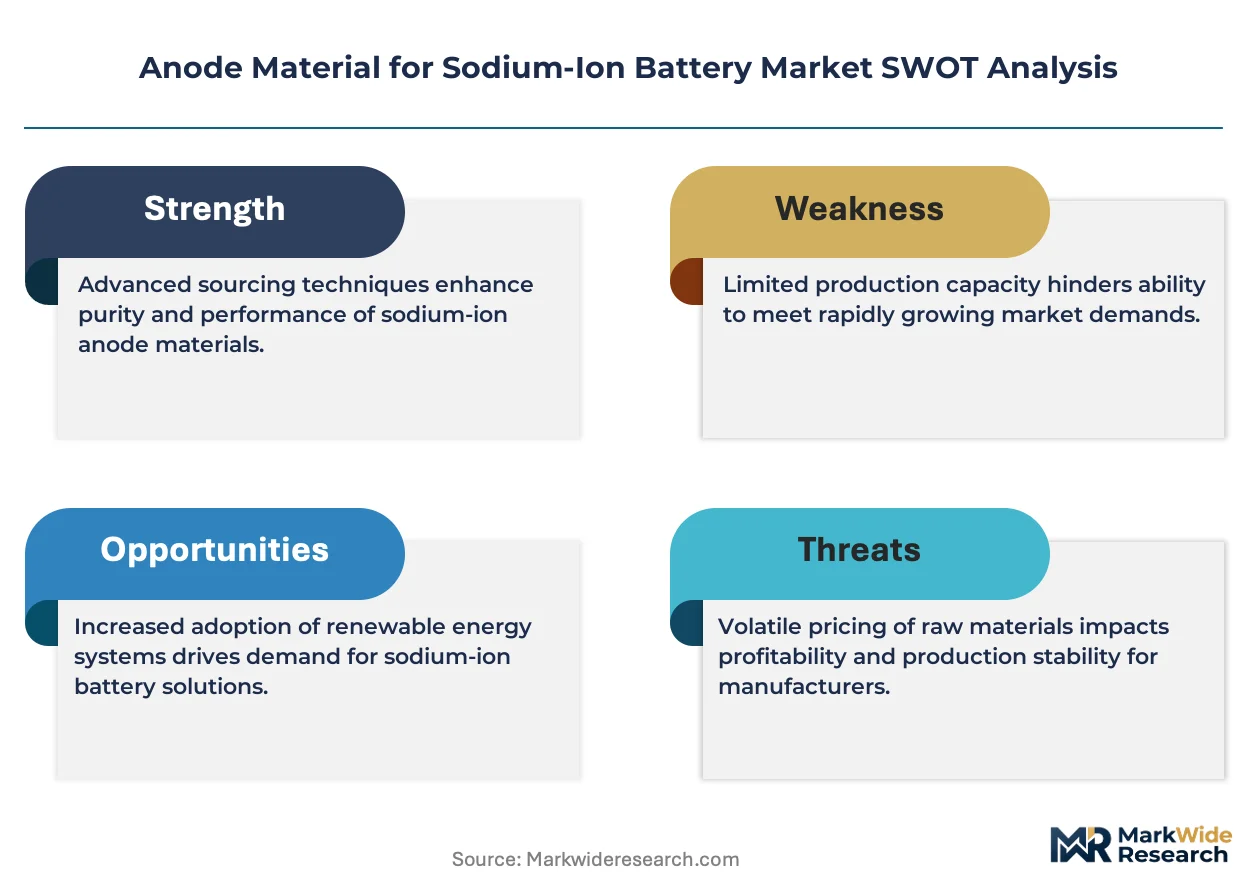
Subscription-based performance guarantees for anode material supply is broadening how producers contract with cell manufacturers. BTR leverages its integrated precursor-to-anode pipeline to lock in multi-year supply agreements. Kuraray sustains leadership in pitch-derived hard carbon through proprietary mesophase control technology. Hunan Shinzoom Technology anchors regional capacity expansion with dedicated lines for sodium-ion specific formulations.
Anode material for sodium-ion batteries encompasses carbonaceous and alloy-based compounds engineered to intercalate sodium ions at potentials near metallic sodium, with hard carbon achieving reversible capacities of 300 mAh/g through controlled pyrolysis of biomass or petroleum precursors. These materials enable electrochemical energy storage in systems that bypass lithium supply constraints for grid and mobility applications. Hard carbon dominates material type segments due to its amorphous structure accommodating the larger sodium ion radius, while tin-based alloys represent the fastest-expanding category despite volume expansion challenges. Among production methods, chemical vapor deposition commands premium positioning for coating uniformity, whereas mechanical milling occupies the volume tier serving cost-sensitive energy storage deployments.
The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape anode material qualification pathways for European cell producers. China's GB standards for sodium-ion batteries, administered by SAMR, establish electrochemical performance benchmarks that filter market access for domestic and imported materials. India's BIS certification requirements for battery safety create additional compliance layers for suppliers targeting emerging South Asian demand. Stakeholders must monitor how evolving solid-electrolyte interphase stabilization protocols and biogenic precursor sourcing claims reshape technical specifications and procurement criteria.
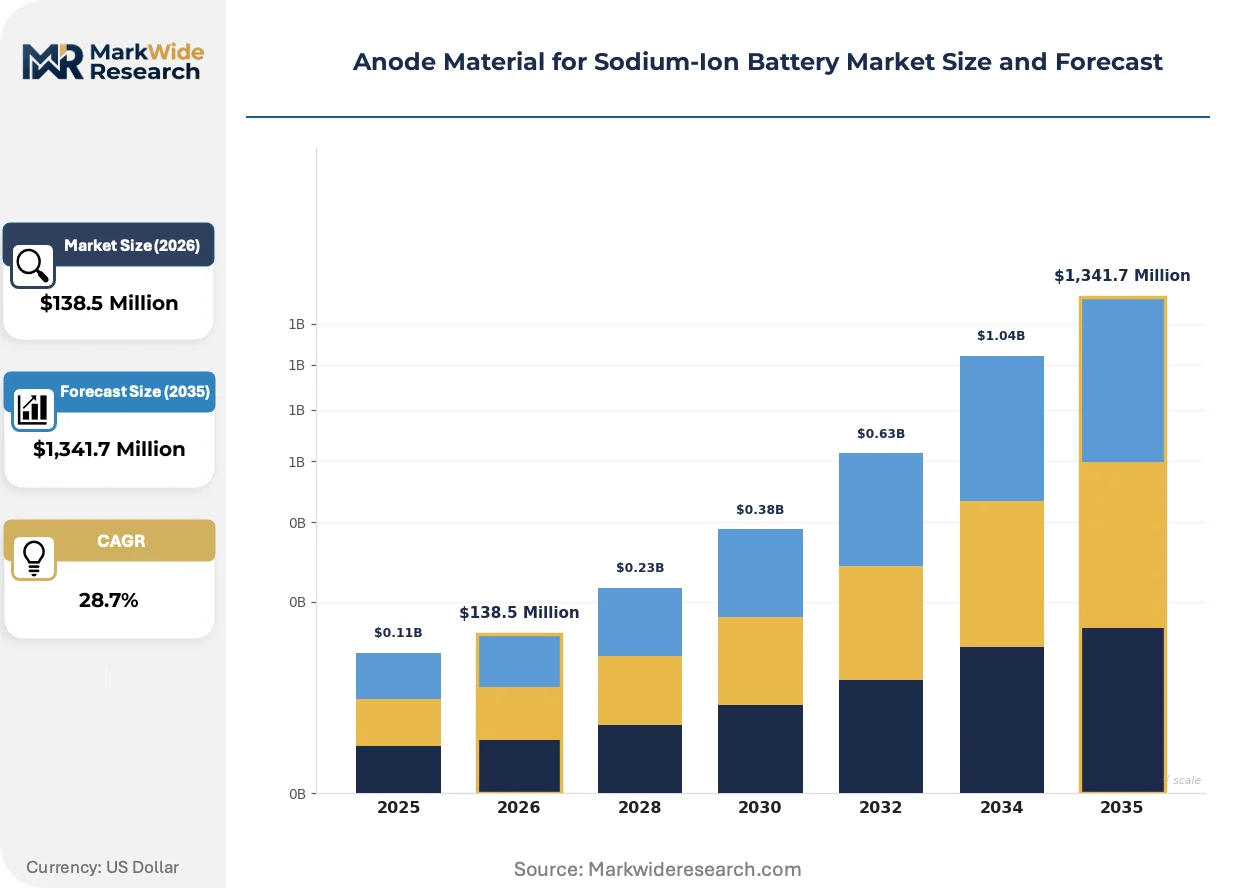
Market Dynamics
Hard carbon precursor supply chains are consolidating around petroleum pitch and biomass pyrolysis clusters, creating captive feedstock advantages for integrated producers while forcing merchant suppliers into tolling arrangements.
Growth Catalysts
- Stationary energy storage procurement:Utilities in Germany and India are tendering sodium-ion battery contracts to diversify beyond lithium supply constraints.
- EU Battery Regulation carbon footprint mandates:Hard carbon derived from biogenic precursors qualifies for preferential recycled content thresholds.
- Dual carbon goals in China:SAMR-administered GB standards accelerate domestic qualification timelines for grid-scale sodium-ion deployments.
Market Restraints
- Petroleum pitch price volatility:Kuraray and Kureha control mesophase pitch supply, exposing anode producers to feedstock cost swings.
- Jiangsu-Hunan supply concentration:Precursor processing and cell manufacturing cluster in two Chinese provinces, creating geographic risk.
- Initial coulombic efficiency ceiling:Hard carbon's irreversible capacity loss in first cycles limits energy density in mobility applications.
Strategic Opportunities
- India BIS certification pathway:Early movers securing safety certifications gain priority access to emerging grid storage tenders.
- Lignin-derived hard carbon:Paper industry waste streams enable biogenic precursor claims under EU Battery Regulation.
- Chemical vapor deposition coating services:Cell manufacturers outsource SEI stabilization layers to specialized equipment operators.
Industry Challenges
- Solid-electrolyte interphase engineering talent:Sodium-ion specific electrolyte additive formulation requires electrochemists with limited industry experience.
- Pilot-to-production scale-up capital:Continuous pyrolysis reactors for hard carbon demand furnace investments with long depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anode Material for Sodium-Ion Battery Market |
| Market Size in 2026 | $138.5 Million |
| Market Size in 2035 | $1,341.7 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Graphite, Hard Carbon, Soft Carbon, Tin Production Method: Mechanical Milling, Chemical Vapor Deposition, Sol-Gel, Hydrothermal Application: Electric Vehicles, Energy Storage, Consumer Electronics, Grid Storage End User: Aerospace, Automotive, Electronics, Industrial |
| Companies Covered | BTR, Shengquan Group, Kuraray, Best Graphite, Shenzhen Xfh Technology, Jereh Group, Hunan Shinzoom Technology, Shanshan, Wuhan Bixidi Battery Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anode Material for Sodium-Ion Battery Market Trends and Innovations
Pre-cursor-to-anode integration is compressing qualification timelines as producers internalize pyrolysis steps previously outsourced to carbon specialists.
Hard carbon production is modularizing around containerized pyrolysis units that enable distributed precursor processing near biomass sources. European utilities adopting sodium-ion for frequency regulation are specifying these modular systems to secure local supply chains. The technology is modularizing capital deployment, allowing cell manufacturers to stage capacity expansion without committing to centralized carbon black-scale facilities.
REACH substance registration requirements for imported hard carbon are forcing non-EU producers to establish EU-based tolling partnerships or register intermediates directly. The industrial consequence is a bifurcation between REACH-compliant suppliers serving automotive cell producers and unregistered material flowing to stationary storage applications. German cell manufacturers are responding by qualifying domestic pyrolysis partners to insulate against import documentation delays.
Long-term offtake contracting is displacing spot purchasing as utilities seek price predictability for twenty-year grid assets. Sodium-ion battery integrators are locking in five-to-seven-year hard carbon supply agreements with fixed escalators tied to pitch indices. This pattern is most visible in India's renewable energy storage auctions, where project finance requires demonstrated feedstock cost stability.
Anode Material for Sodium-Ion Battery Market Segmentation
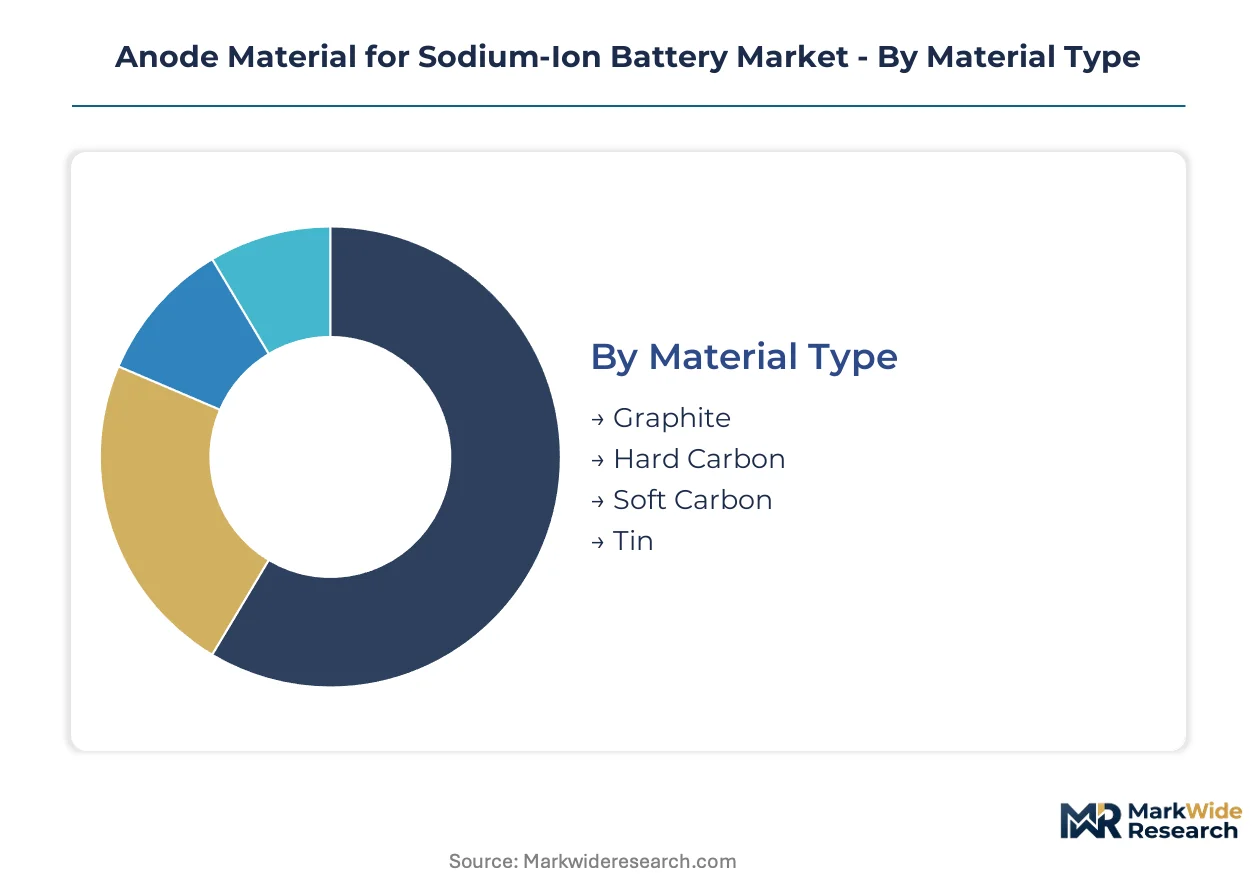
Segmentation in anode materials for sodium-ion batteries reveals how capital deployment and technical specifications diverge across the value chain. Each dimension—material chemistry, production infrastructure, application requirements, and end-user procurement patterns—creates distinct margin structures and barriers to entry.
Material Type:
Capital intensity varies sharply across material chemistries, with pyrolysis-based production demanding continuous furnace investments while alloy routes require precision metallurgy equipment.
- Hard Carbon:Amorphous carbon structures accommodate sodium ions through interlayer spacing engineered via controlled pyrolysis of biomass or petroleum precursors. Demand concentrates in China's Jiangsu and Hunan provinces where precursor supply chains and cell manufacturing clusters have achieved critical mass, though initial coulombic efficiency losses limit deployment in mobility applications.
- Tin:Intermetallic alloys deliver higher theoretical capacity through alloying reactions with sodium, suffering from severe volume expansion during cycling that demands advanced binder and electrolyte formulations. Grid storage integrators in Germany and India are piloting tin-blend anodes for frequency regulation where cycle life requirements are less stringent than automotive.
- Graphite:Layered crystalline structure intercalates sodium ions at higher potentials than hard carbon, offering limited commercial traction due to inferior capacity retention.
- Soft Carbon:Graphitizable carbon precursors yield ordered structures with lower sodium storage capacity, finding niche use in hybrid anode formulations.
Most installed capacity flows through Hard Carbon. Expansion is steepest in Tin.
Production Method:
Cost tiers separate batch processing from continuous systems, with coating technologies commanding premium positioning for uniformity-critical applications.
- Chemical Vapor Deposition:Gas-phase deposition achieves conformal carbon coatings with precise thickness control for solid-electrolyte interphase stabilization. Automotive cell producers in Europe specify CVD-treated hard carbon to meet EU Battery Regulation carbon footprint declarations, outsourcing coating services to specialized equipment operators rather than internalizing capital expenditure.
- Mechanical Milling:High-energy ball milling reduces particle size and enhances surface area for improved electrolyte wetting. Stationary energy storage deployments in India favor mechanically milled material where cost sensitivity outweighs performance premiums.
- Sol-Gel:Solution-based synthesis enables precise stoichiometry control for alloy-based anodes, requiring substantial solvent recovery infrastructure.
- Hydrothermal:High-pressure aqueous processing converts biomass precursors without pyrolysis, attracting pilot investments near lignin waste streams.
Volume manufacturing runs through Mechanical Milling. Technology licensing concentrates in Chemical Vapor Deposition.
Application:
Customer type determines specification stringency, with mobility applications demanding decade-long cycle life validation that stationary assets can relax.
- Grid Storage:Utility-scale frequency regulation and renewable firming tolerate lower energy density in exchange for capital cost advantages and supply chain diversification. German utilities tendering sodium-ion contracts specify twenty-year asset lifetimes, locking in five-to-seven-year hard carbon supply agreements with fixed escalators tied to pitch indices.
- Energy Storage:Commercial and industrial behind-the-meter systems prioritize fire safety and temperature tolerance over gravimetric performance. India's renewable energy storage auctions require demonstrated feedstock cost stability for project finance, favoring biogenic precursor claims under BIS certification pathways.
- Electric Vehicles:Two-wheeler and entry-level passenger car segments represent the mobility frontier, constrained by hard carbon's irreversible capacity loss in first cycles.
- Consumer Electronics:Low-power devices with modest cycle requirements enable early market penetration for novel material formulations.
Procurement volume clusters in Grid Storage. Specification evolution is fastest in Electric Vehicles.
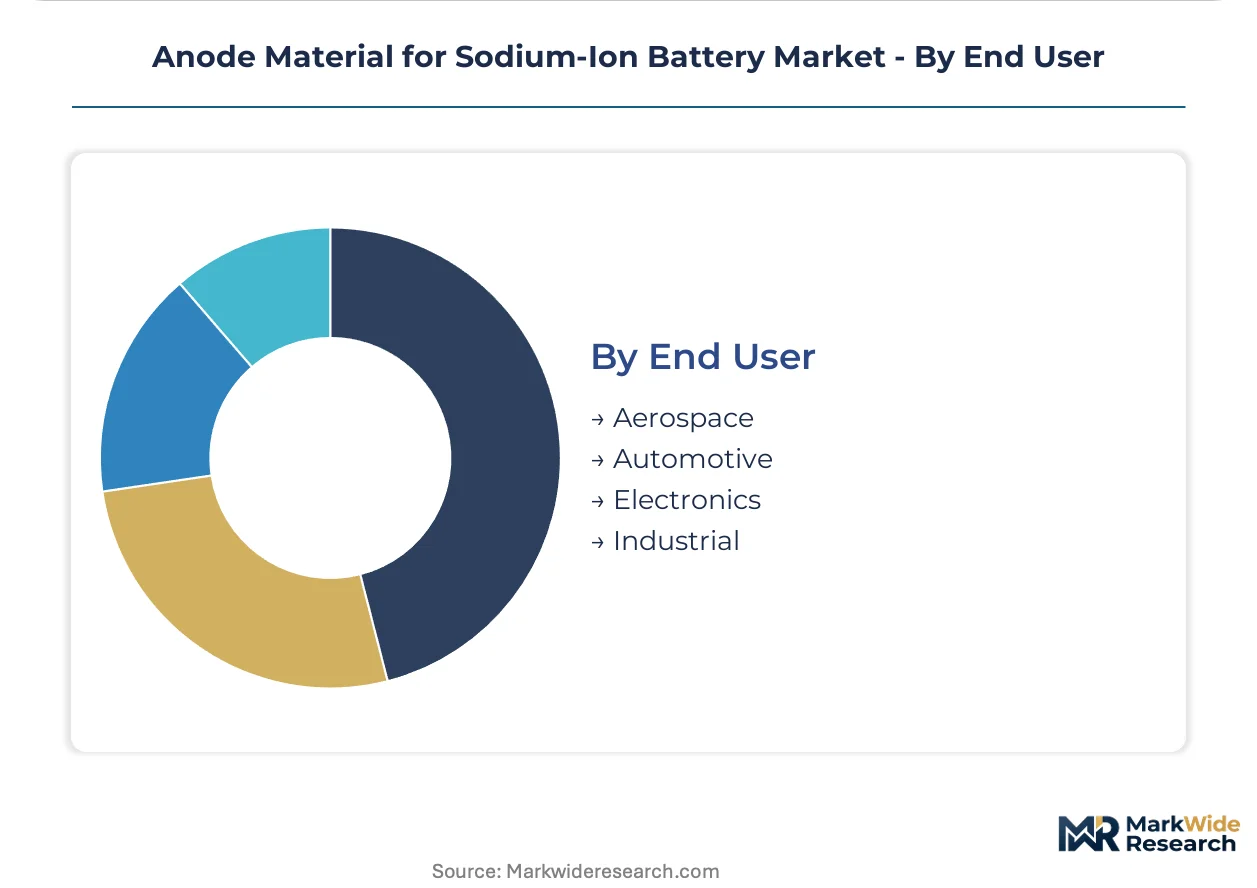
End User:
Geographic procurement patterns concentrate demand in jurisdictions with active industrial policy support for sodium-ion commercialization.
- Automotive:Cell manufacturers serving two-wheeler OEMs in India and China qualify hard carbon anodes under GB standards and BIS certification requirements. SAMR-administered benchmarks filter market access for domestic and imported materials, compressing qualification timelines for grid-scale deployments.
- Industrial:Forklift and material handling equipment operators seek drop-in replacements for lead-acid systems without lithium supply exposure.
- Electronics:Portable power and backup systems specify sodium-ion where transportation safety regulations restrict lithium chemistry.
- Aerospace:Satellite and drone applications test alloy-based anodes for specific energy advantages despite cycling limitations.
Contracting activity concentrates in Automotive. Certification backlog is deepest in Aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands precursor processing scale while Germany drives carbon footprint certification standards, creating divergent qualification pathways for anode material suppliers.
China
Jiangsu and Hunan provinces anchor hard carbon production through integrated precursor-to-anode pipelines serving domestic cell manufacturers. SAMR-administered GB standards compress qualification timelines for grid-scale sodium-ion deployments under national dual carbon goals. Changsha and Changzhou industrial clusters host dedicated pyrolysis lines for sodium-ion specific formulations.
Germany
Utility tenders for frequency regulation batteries specify twenty-year asset lifetimes requiring demonstrated feedstock cost stability. EU Battery Regulation carbon footprint declarations and REACH substance registration reshape anode material qualification pathways for European cell producers. Bavarian pyrolysis partnerships insulate automotive cell manufacturers against import documentation delays.
India
Renewable energy storage auctions in Gujarat and Maharashtra require BIS certification for project finance, favoring early movers securing safety approvals. Central Electricity Authority procurement guidelines prioritize supply chain diversification beyond lithium dependency. Tamil Nadu cell manufacturing clusters pilot tin-blend anodes for grid applications with relaxed cycle life requirements.
Japan
METI-funded consortia advance mesophase pitch refining technology for premium hard carbon applications. JIS standards for battery materials create technical barriers for imported anode products. Osaka-based carbon specialists sustain proprietary pyrolysis control methods for automotive qualification programs.
United States
IRA production tax credits incentivize domestic hard carbon manufacturing from lignin waste streams in the Pacific Northwest. EPA environmental compliance requirements for pyrolysis emissions shape facility siting decisions. Texas and Ohio industrial zones attract tolling partnerships for REACH-compliant material re-export to European customers.
Anode Material for Sodium-Ion Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated precursor producers commanding premium positioning in utility-scale contracts while tolling operators serve cost-sensitive stationary storage. The vendor base concentrates around petroleum pitch refiners and biomass pyrolysis specialists, creating tiered supply access based on feedstock control. Three archetypes dominate: captive precursor-to-anode integrators, merchant carbon processors, and specialized coating service providers. Capacity expansion and strategic tolling partnerships represent the dominant competitive moves as firms seek to secure feedstock without committing to full vertical integration.
Among integrated specialists, BTR leverages its precursor pipeline to anchor multi-year supply agreements with cell manufacturers. Kuraray occupies a position exemplifying mesophase pitch technology leadership through proprietary refining methods. Hunan Shinzoom Technology represents the regional capacity expansion archetype with dedicated sodium-ion formulation lines. These three firms illustrate how feedstock access, technology control, and geographic proximity to manufacturing clusters determine competitive positioning.
| Leading Market Players |
|---|
| BTR |
| Shengquan Group |
| Kuraray |
| Best Graphite |
| Shenzhen Xfh Technology |
| Jereh Group |
| Hunan Shinzoom Technology |
| Shanshan |
| Wuhan Bixidi Battery Material |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between REACH-registered and unregistered hard carbon suppliers creates divergent pricing ladders and forces distinct supply chain architectures across European and Asian procurement channels. Cell manufacturers sourcing for automotive applications under EU Battery Regulation mandates absorb premium tolling costs through Bavarian pyrolysis partnerships, while stationary storage integrators in India and China access merchant material through spot-indexed petroleum pitch contracts.
Pricing Analysis
Capacity additions in Jiangsu and Hunan provinces are reshaping price floors for mechanically milled hard carbon, compressing margins for merchant carbon processors without captive precursor supply. Contract-based long-term offtake agreements with fixed escalators tied to mesophase pitch indices dominate utility-scale procurement, while tolling fees for CVD coating services command premiums reflecting equipment scarcity. Cost compression in standard-grade material intensifies as integrated producers internalize pyrolysis steps, leaving spot purchasers most price-sensitive and automotive cell producers least sensitive due to certification lock-in.
Supply Chain Analysis
Dual-sourcing requirements from German and Indian utilities mandate qualification of at least two hard carbon suppliers per contract, fragmenting procurement across petroleum pitch refiners and biomass pyrolysis specialists. Supply concentrates in China, Japan, and Germany, with raw material dependencies on petroleum mesophase pitch, lignin waste streams, and sodium-ion specific electrolyte additives. Single-source vulnerability around Kuraray and Kureha mesophase pitch control exposes anode producers to feedstock cost swings. Distribution runs through direct long-term agreements with cell manufacturers rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between China's compressed qualification timelines under SAMR-administered GB standards and Europe's carbon footprint declaration requirements, rewarding producers with dual-certification capabilities that can shift output across regulatory zones.
For Market Incumbents: Acquire biomass pyrolysis assets near European lignin waste streams to secure biogenic precursor claims under EU Battery Regulation recycled content thresholds. Consolidate tolling partnerships in Bavaria and Texas to insulate automotive customers from REACH documentation delays while expanding captive petroleum pitch refining capacity to defend against Kuraray supply concentration risk. For New Entrants and Emerging Players: Lignin-derived hard carbon technology offers the most penetrable wedge for European market entry, targeting German utility frequency regulation tenders where cycle life requirements are less stringent than automotive. Pursue BIS certification in India to access Gujarat and Maharashtra renewable energy storage auctions, positioning containerized pyrolysis units as localized supply chain solutions that bypass Jiangsu-Hunan concentration risk. For Investors and Strategic Acquirers: Consolidation pressure builds where precursor-to-anode integration gaps leave merchant carbon processors exposed to petroleum pitch price volatility. Five-to-ten-year viability hinges on feedstock control and certification breadth rather than scale alone. Target acquisition archetype: regional pyrolysis specialists with SAMR qualification and lignin precursor partnerships. Watch for inflection in sodium-ion electric vehicle qualification timelines under GB standards as signal for mobility segment premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Mesophase pitch control insulates margins from Kuraray and Kureha supply concentration. |
| REACH-Compliant Tolling Partnership | Bavarian pyrolysis capacity secures European automotive qualification pathways against import delays. |
| Long-term Supply Agreement | Twenty-year utility asset lifetimes demand fixed-escalator contracts tied to pitch indices for project finance. |
| Biogenic Precursor Certification | Lignin-derived hard carbon qualifies for EU Battery Regulation preferential recycled content thresholds. |
| Containerized Pyrolysis Deployment | Modular units enable distributed processing near biomass sources, reducing Jiangsu-Hunan geographic risk. |
Research Methodology
Multiple input streams — cell manufacturer procurement director interviews, carbon processor technical assessments, and utility tender document analysis — were reconciled against customs trade data, SAMR GB standard filings, and EU Battery Regulation implementation guidance. Primary engagement with plant managers at Jiangsu and Hunan pyrolysis facilities, EPC contractors for containerized unit deployment, and CEA procurement officers in Gujarat and Maharashtra informed capacity and demand calibration. Secondary sources included SEC filings from listed material suppliers, IEA stationary storage deployment databases, and BIS certification registries. Bottom-up production capacity tallies and top-down utility procurement forecasts were cross-validated to anchor segmentation outputs.
Data-stream reconciliation across material type, production method, application, and end-user dimensions generated volume and value estimates across the projection horizon. Hard carbon, tin, graphite, and soft carbon chemistries were modeled separately with distinct precursor cost structures. Production methods differentiated continuous pyrolysis furnace economics from batch CVD coating service pricing. Grid storage, energy storage, electric vehicle, and consumer electronics applications carried distinct specification stringency and cycle life validation timelines. CAGRs were derived from weighted capacity expansion announcements and tendered deployment schedules, with sodium-ion specific electrolyte additive availability and solid-electrolyte interphase engineering talent scarcity incorporated as constraint variables.
The model holds under sustained dual carbon policy enforcement in China and EU Battery Regulation carbon footprint phase-in; deviation in petroleum pitch supply disruption or BIS certification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
United Kingdom Electric Vehicle Battery Anode Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Lithium Ion Battery Cathodes Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Ion Capacitor Market