
 Lithium Ion Battery Cathodes Market | 2026-2036
Lithium Ion Battery Cathodes Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Ion Battery Cathodes Market Outlook
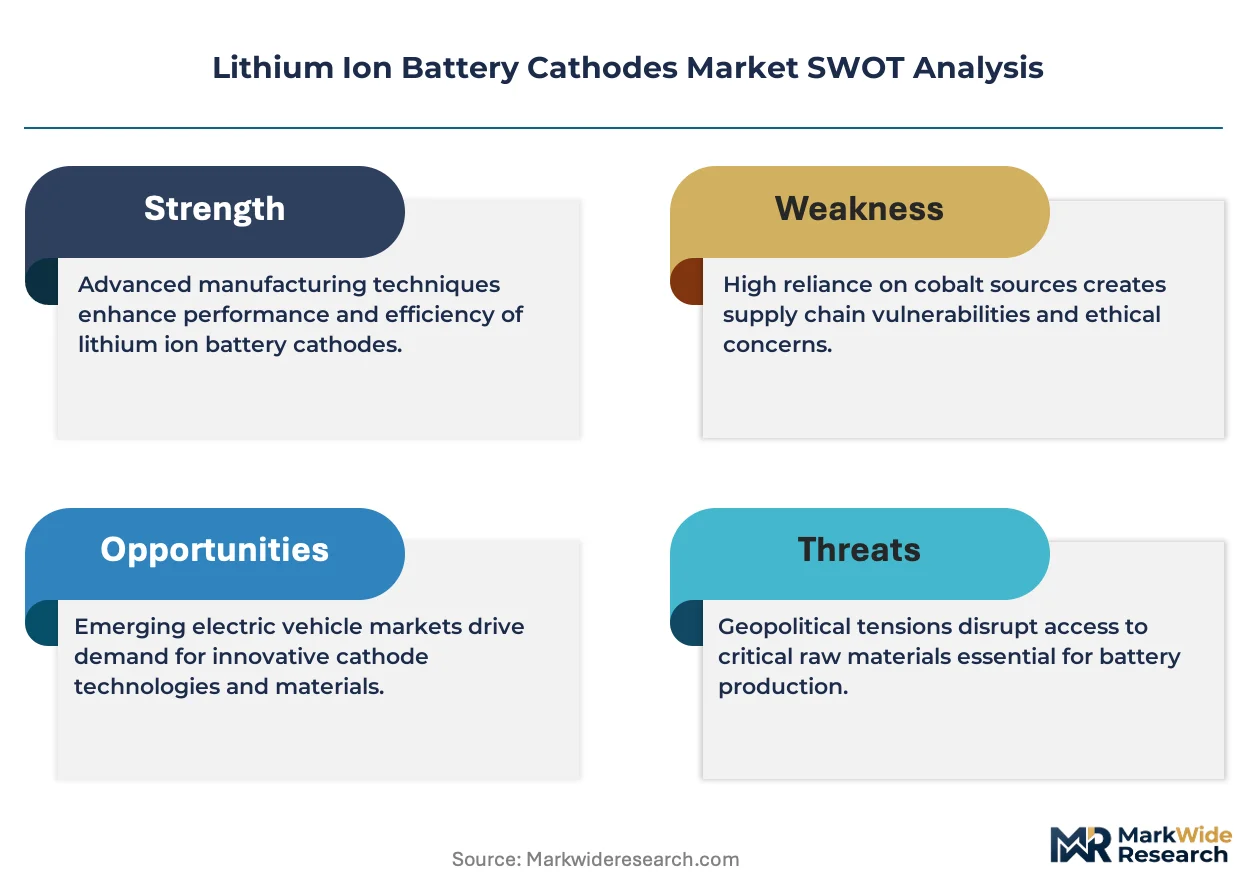
The EU Battery Regulation is repositioning cathode procurement toward verifiable low-carbon supply chains. CATL leverages integrated mining-to-cell operations across multiple continents. Umicore anchors its competitiveness through closed-loop recycling capabilities in Europe. BASF SE specializes in high-nickel NMC precursors serving premium automotive contracts.
Lithium ion battery cathodes are crystalline metal oxide structures, typically layered spinels or olivine frameworks, that intercalate lithium ions during charge and discharge cycles. Their primary industrial purpose is to determine cell voltage, energy density, and cycle stability in rechargeable electrochemical storage systems. LFP formulations now lead in energy storage installations due to superior thermal stability and extended calendar life. NMC chemistries command the electric vehicle segment as automakers prioritize gravimetric energy density for extended range. Cobalt-based LCO retains dominance in consumer electronics where volumetric energy density constraints govern device miniaturization.
China's MIIT enforces GB standards for cathode active material purity and cell safety testing that shape export eligibility for domestic producers. The EPA in the United States and ECHA in Europe impose parallel restrictions on heavy metal content and supply chain due diligence that filter material sourcing decisions. REACH compliance and emerging battery passport requirements are tightening documentation burdens across the value chain. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps.
Market Dynamics
EU Battery Regulation carbon footprint declarations are forcing cathode producers to restructure upstream sourcing and install emissions tracking systems across mining-to-precursor operations.
Growth Catalysts
- EU recycled content mandates:Battery Regulation thresholds for recovered lithium, nickel, and cobalt are pulling investment into hydrometallurgical recycling infrastructure across Poland, Germany, and Finland.
- Electric vehicle range wars:Automakers specify NMC 811 and 9½½ formulations to push pack-level energy density past 300 Wh/kg, locking in nickel-rich cathode demand for premium B-segment and above.
- Energy storage procurement:Utility-scale developers specify LFP for 4-hour and 8-hour grid batteries, exploiting the chemistry's thermal stability to reduce fire suppression system costs in containerized installations.
Market Restraints
- Nickel price volatility:London Metal Exchange nickel contract swings following Indonesian export policy shifts transmit directly into NMC precursor cost structures, compressing cathode maker margins.
- Cobalt supply concentration:DRC artisanal and industrial mine output dominates feedstock for high-voltage LCO and NMC formulations, concentrating geopolitical and ESG audit risk in a single jurisdiction.
- Water-intensive refining:Nickel laterite processing via high-pressure acid leaching demands 30-50 cubic meters per ton of contained metal, exposing Indonesian and Philippine operations to drought-driven output curtailments.
Strategic Opportunities
- US IRA domestic content bonuses:Clean Vehicle Tax Credit critical mineral and battery component sourcing thresholds are incentivizing cathode precursor plants in Texas, Tennessee, and North Carolina.
- Sodium-ion hybrid cathodes:Layered oxide formulations incorporating sodium and lithium are opening cost-sensitive two-wheeler and stationary storage segments where energy density requirements relax.
- Battery passport data services:Digital product passports verifying carbon intensity and recycled content are creating subscription revenue streams for analytics platforms serving OEM compliance departments.
Industry Challenges
- PhD-level materials science talent scarcity:Formulation optimization for single-crystal NMC and high-voltage spinel structures requires rare expertise in solid-state chemistry and interfacial engineering, constraining R&D throughput.
- Cell-to-pack integration complexity:BYD Blade and CATL cell-to-pack architectures eliminate module housings but demand tighter cathode thickness tolerances and electrode coating uniformity, raising defect rates during scale-up.
- REACH-SVHC documentation lag:European Chemicals Agency substance of very high concern candidate list updates outpace supplier certificate refresh cycles, triggering production holds and customs delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Ion Battery Cathodes Market |
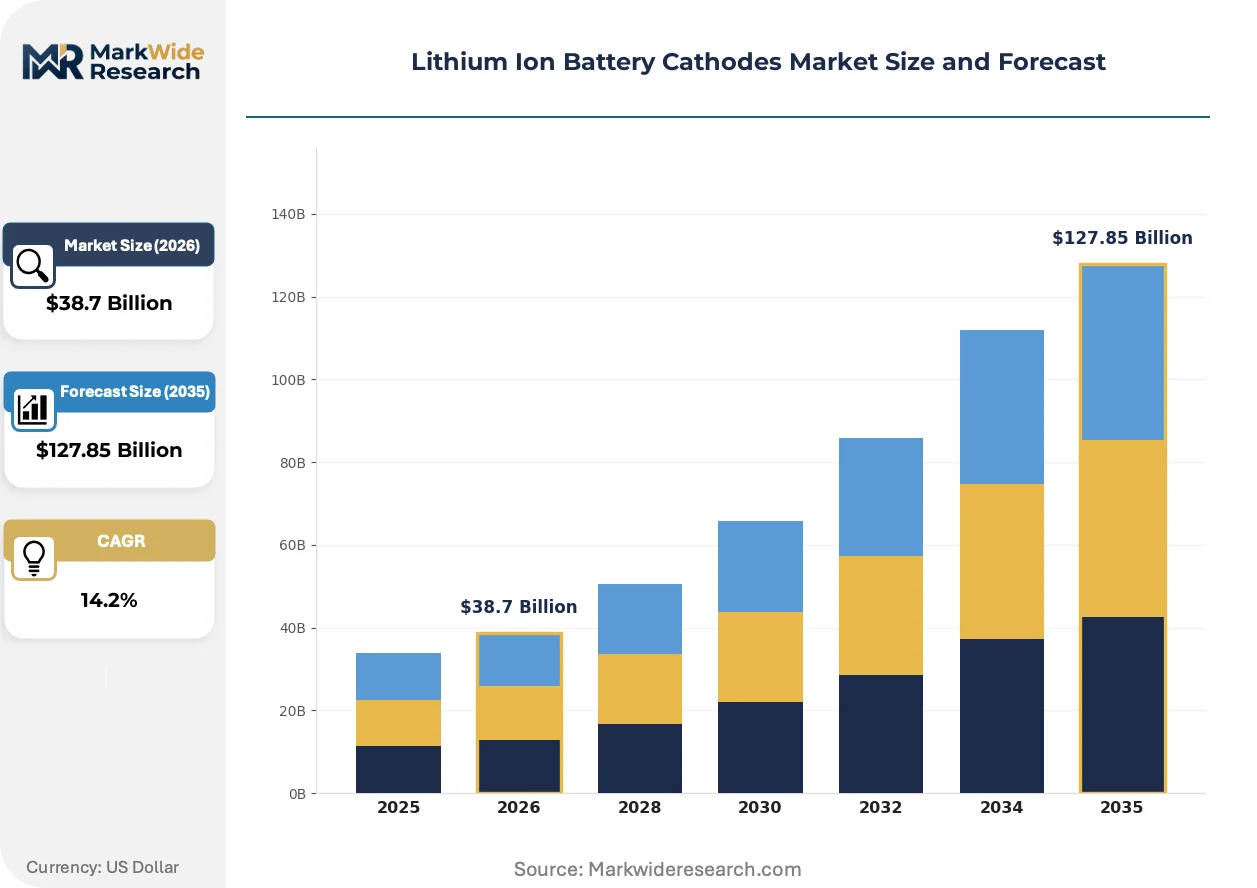
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NMC, LFP, LCO, NCA Material: Cobalt, Nickel, Lithium, Manganese End User: Consumer Electronics, Electric Vehicles, Energy Storage, Industrial Applications Application: Smartphones, Laptops, Electric Bicycles, Electric Tools |
| Companies Covered | CATL, LG Energy Solution, Panasonic, BASF SE, Umicore, Sumitomo Metal Mining, POSCO Future M, BYD, Nichia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Ion Battery Cathodes Market Strategic Shifts
High-nickel cathode stabilization chemistries and dry electrode coating processes are compressing manufacturing energy intensity while extending cycle life for next-generation electric vehicle platforms.
Single-crystal NMC is absorbing the reliability demands of 800-volt electrical architectures. Cell makers specify these morphologies for reduced microcracking under high-C-rate fast charging. The structural shift is absorbing margin from polycrystalline alternatives as automakers lock in 10-year/300,000-kilometer warranty terms.
REACH battery passport pre-registration requirements are forcing cathode active material producers to deploy blockchain-traceable supply chain documentation. The regulation compresses opacity in African cobalt and Indonesian nickel logistics. European OEM procurement departments are now rejecting batches lacking verified carbon intensity declarations.
Fleet operators and leasing companies are consolidating cathode chemistry specifications into multi-year framework agreements. This behavior displaces spot-market purchasing for volume EV and stationary storage deployments. The shift is most visible in Germany and the Netherlands where municipal bus electrification programs aggregate demand across hundreds of vehicles.
Lithium Ion Battery Cathodes Market Segmentation
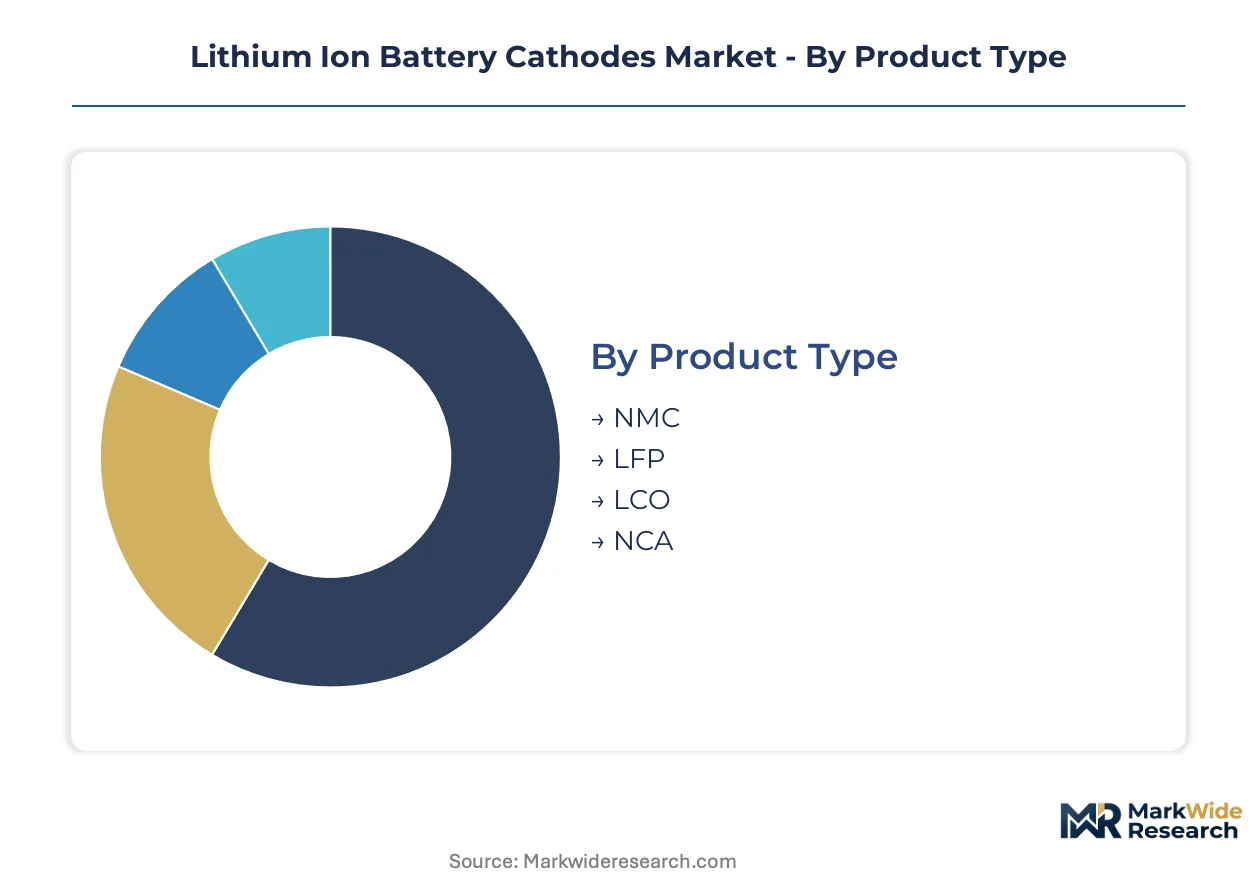
Cathode chemistry selection locks in downstream performance ceilings for battery systems. Procurement teams trade energy density against thermal stability and supply chain risk across distinct formulation categories. Segmentation clarity enables targeted capacity planning and regulatory compliance mapping.
Product Type:
Standardization dominates high-volume automotive contracts while specialty formulations command premium positioning in performance-sensitive applications.
- NMC:Layered oxide structures blending nickel, manganese, and cobalt deliver the highest gravimetric energy density among commercial cathodes. Automakers specify NMC 811 and 9½½ variants for 800-volt architectures and 300+ kilometer range targets. Nickel-rich formulations absorb the steepest investment in single-crystal morphology R&D.
- LFP:Olivine-structured lithium iron phosphate eliminates cobalt dependency entirely. Utility-scale developers in China and Germany specify LFP for containerized grid storage exploiting superior thermal runaway resistance. The chemistry sacrifices volumetric density for calendar life extension beyond 6000 cycles.
- LCO:Layered cobalt oxide maintains dominance in smartphone and laptop applications where space constraints override cost sensitivity. High-voltage LCO variants support premium consumer electronics miniaturization.
- NCA:Nickel-cobalt-aluminum oxide balances energy density with structural stability for cylindrical cell formats. Tesla's 2170 and 4680 cell programs anchor NCA demand in high-performance EV segments.
Most installed capacity flows through NMC. Expansion is steepest in LFP.
Material:
Upstream metal procurement concentration determines margin volatility and ESG audit burden across cathode supply chains.
- Cobalt:DRC artisanal and industrial mining dominates feedstock supply for LCO and NMC precursors. ECHA REACH due diligence requirements and EU Battery Regulation recycled content mandates are forcing cathode producers to document chain-of-custody from mine to precursor.
- Nickel:Indonesian laterite processing via high-pressure acid leaching supplies the bulk of battery-grade nickel sulfate. EPA and ECHA parallel restrictions on processing emissions are filtering investment toward hydrometallurgical refining with lower carbon intensity.
- Lithium:Spodumene concentrate from Australia and brine evaporation from Chile and Argentina feed lithium carbonate and hydroxide production. China's MIIT GB standards for cathode-grade lithium salt purity shape export eligibility for domestic refiners.
- Manganese:Electrolytic manganese dioxide and high-purity manganese sulfate support NMC stoichiometry optimization. South African and Gabonese mine output supplies the bulk of battery-grade material.
Procurement risk concentrates in cobalt. Price volatility transmits most sharply through nickel.
End User:
Volume scale and specification stringency diverge sharply between mass-market automotive and fragmented industrial applications.
- Electric Vehicles:OEMs specify cathode chemistry through multi-year framework agreements locking in 10-year warranty compliance. Cell-to-pack architectures from BYD and CATL demand tighter thickness tolerances and coating uniformity from cathode suppliers.
- Energy Storage:Utility developers prioritize LFP for 4-hour and 8-hour grid batteries, exploiting thermal stability to reduce fire suppression system costs. Procurement aggregates across municipal and regional programs in Germany and the Netherlands.
- Consumer Electronics:Smartphone and laptop manufacturers specify LCO for maximum volumetric energy density. Device miniaturization trends sustain cobalt dependency despite ESG pressure.
- Industrial Applications:Forklift, mining equipment, and stationary backup power systems specify cathodes based on duty cycle and temperature extremes. Fragmented demand limits supplier concentration.
Electric vehicles absorb the largest absolute volume. Energy storage is gaining share fastest.
Application:
Form factor and cycle life requirements fragment cathode selection across portable and motive power segments.
- Smartphones:LCO pouch cells dominate premium handset designs. Volumetric energy density constraints govern cathode selection as device thickness targets compress below 8 millimeters.
- Laptops:Prismatic LCO and NMC cylindrical formats compete based on thermal management architecture. Enterprise fleet procurement is consolidating specifications into multi-year supply agreements.
- Electric Bicycles:Cost-sensitive two-wheeler markets specify LFP and sodium-ion hybrid cathodes where energy density requirements relax. China's domestic market anchors volume.
- Electric Tools:High-discharge cylindrical cells for power tools specify NMC for burst current capability. Professional-grade tool warranties demand consistent cathode quality across production batches.
Smartphone cathode specifications are most standardized. Electric bicycle applications show the steepest chemistry diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial lithium ion battery cathode production originated in Japan during the 1990s consumer electronics boom, then migrated to China as electric vehicle demand reshaped volume requirements. Today's capacity geography reflects this lineage: Japanese firms retain specialty formulations, Chinese producers dominate mass-market output, and Western jurisdictions are reconstructing domestic supply chains through industrial policy.
China
CATL and BYD anchor cathode demand through integrated cell-to-material operations spanning Fujian and Guangdong provinces. MIIT enforces GB standards for active material purity that filter export eligibility for domestic refiners. The Yangtze River Delta concentrates precursor plants in Changzhou and Ningbo, where nickel sulfate refining capacity expanded following Indonesian offtake agreements.
United States
IRA Clean Vehicle Tax Credit thresholds are pulling cathode precursor investment toward Texas and Tennessee. The EPA imposes parallel restrictions on heavy metal content and supply chain due diligence that shape material sourcing decisions. Greater Austin hosts emerging cathode active material facilities serving Tesla's 4680 cell program and adjacent OEM battery plants.
Germany
Umicore's closed-loop recycling operations in Antwerp supply German cathode plants facing EU Battery Regulation recycled content mandates. ECHA REACH documentation requirements compress supplier refresh cycles, triggering production holds for non-compliant batches. The Rhine-Ruhr industrial corridor hosts BASF SE's high-nickel NMC precursor operations serving premium automotive contracts.
Japan
Panasonic and Nichia sustain LCO dominance for consumer electronics where volumetric density constraints govern device miniaturization. METI battery technology roadmaps prioritize solid-state cathode interfaces for next-generation platforms. The Kansai region around Osaka retains specialty cathode formulation expertise dating to the original lithium ion commercialization.
South Korea
LG Energy Solution and POSCO Future M anchor cathode demand through cylindrical and prismatic cell programs for export markets. The country's national industrial regulator imposes cell safety testing standards that shape cathode active material specifications. The Busan-Ulsan industrial complex concentrates precursor refining capacity with offtake ties to Indonesian nickel processing.
Lithium Ion Battery Cathodes Market Competitive Environment
Capital-heavy producers compete with asset-light designers across cathode supply tiers. Integrated mining-to-cell operators absorb margin through captive precursor supply, while specialized active material houses compete on formulation agility and customer co-development. Three archetypes dominate: diversified chemical conglomerates with battery material divisions, pure-play cathode specialists, and captive cell-maker supply operations. Competitive moves center on backward integration into nickel refining and strategic partnerships for recycling feedstock security.
Among Asian-integrated producers, CATL and BYD exemplify the captive supply archetype where cathode operations serve internal cell demand. BASF SE occupies a position representing European chemical conglomerate diversification into battery materials. Umicore anchors the closed-loop recycling specialist tier. These three patterns—captive integration, chemical diversification, and circular feedstock focus—absorb the strategic variation visible across the competitive set.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic |
| BASF SE |
| Umicore |
| Sumitomo Metal Mining |
| POSCO Future M |
| BYD |
| Nichia |
| Others |
Value Chain & Pricing Dynamics
Single-crystal NMC premiumization against commodity polycrystalline grades splits cathode procurement into parallel supply chain configurations, with automakers paying formulation premiums for warranty-compliant 800-volt architectures while energy storage developers optimize for LFP spot-market sourcing from integrated Chinese refiners.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments cathode active material contracts by certification grade and volume scale. Premium tiers command spreads for single-crystal morphology and EU Battery Regulation carbon passport documentation, while standard NMC 622 and LFP grades trade on nickel sulfate and lithium carbonate spot indices. Cost compression in nickel-rich formulations is intensifying because Indonesian HPAL output expansion outpaces precursor capacity buildout. Fleet procurement teams show highest price sensitivity, locking multi-year offtake agreements to hedge London Metal Exchange volatility.
Supply Chain Analysis
Nickel sulfate supply rests on Indonesian high-pressure acid leaching complexes and Finnish hydrometallurgical refiners serving European automaker specifications. Cathode precursor production draws from DRC cobalt hydroxide, Australian spodumene concentrate, and Chilean-Argentine brine evaporation for lithium carbonate. Single-source vulnerability concentrates in Indonesian nickel processing, where export policy shifts transmit directly into NMC cost structures. Distribution runs through long-term framework agreements binding cell makers to active material houses, displacing spot-market purchasing for volume electric vehicle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EU Battery Regulation compliance premiums and IRA domestic content bonuses, with cathode producers capturing margin spreads by siting precursor plants in jurisdictions where carbon intensity thresholds and critical mineral sourcing rules diverge.
For Market Incumbents: Lock in closed-loop recycling feedstock agreements before EU recycled content mandates tighten. Secure Indonesian nickel offtake through equity stakes in HPAL operations to hedge London Metal Exchange volatility. Defend formulation leadership by accelerating single-crystal NMC R&D for 800-volt platform warranties.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in sodium-ion hybrid cathodes opens white-space entry for two-wheeler and stationary storage segments where energy density requirements relax below electric vehicle thresholds. Target municipal bus electrification programs in Germany and the Netherlands aggregating demand across fleet-scale procurements. Lead with LFP cost positioning against nickel-rich alternatives in grid battery tenders.
For Investors and Strategic Acquirers: Consolidation pressure builds where hydrometallurgical recycling capabilities face EU Battery Regulation recycled content thresholds without secured black mass feedstock. Long-term viability favors targets with backward integration into nickel refining and carbon passport data infrastructure. Watch Indonesian export licensing shifts as inflection indicators for NMC precursor margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Refining | Captive HPAL output secures NMC precursor cost stability against LME contract swings. |
| Hydrometallurgical Recycling Capacity Buildout | EU Battery Regulation thresholds pull investment into Poland and Finland for black mass processing. |
| Single-Crystal NMC Formulation Scale-Up | Automaker 800-volt warranties demand reduced microcracking under fast-charge cycling. |
| Carbon Passport Data Platform Deployment | Blockchain-traceable documentation satisfies ECHA REACH and EU OEM procurement rejections. |
| IRA Domestic Content Precursor Siting | Texas and Tennessee plants qualify Clean Vehicle Tax Credit critical mineral thresholds. |
Study Parameters
Multiple input streams — cathode plant manager interviews, OEM procurement lead discussions, battery cell engineering director consultations, and utility-scale developer surveys — were reconciled against customs data, MIIT GB standard filings, SEC 10-K supply chain disclosures, and ECHA REACH registration databases. Primary fieldwork captured formulation specifications, capacity expansion timelines, and contract structuring practices across integrated and merchant active material producers. Bottom-up cathode chemistry demand modeling triangulated against top-down electric vehicle production and grid storage deployment forecasts.
Data-stream reconciliation anchored volume projections across chemistry type, end-use segment, and regional production cluster dimensions over the projection horizon. CAGRs derived from installed capacity buildout curves, automaker platform electrification roadmaps, and utility procurement pipeline aggregation. Forecast inputs incorporated nickel sulfate and lithium carbonate price elasticity assumptions, EU Battery Regulation compliance cost pass-through estimates, and IRA domestic content bonus capture rates by precursor plant geography.
Caveats apply where Indonesian export policy shifts, DRC artisanal mining ESG audit disruptions, or cell-to-pack architecture defect rate escalations could materially shift the outlook. Forecasts reflect assumptions on nickel-rich cathode stabilization chemistry maturation and hydrometallurgical recycling yield improvements. A small set of named triggers — LME nickel contract volatility spikes, EU Battery Regulation delegated act timing, and sodium-ion hybrid cathode cost crossover points — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Anode Material for Sodium-Ion Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
Cylindrical Lithium-Ion Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market