
 US Electric Commercial Vehicle Battery Pack Market | 2026-2036
US Electric Commercial Vehicle Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
US Electric Commercial Vehicle Battery Pack Market Insights
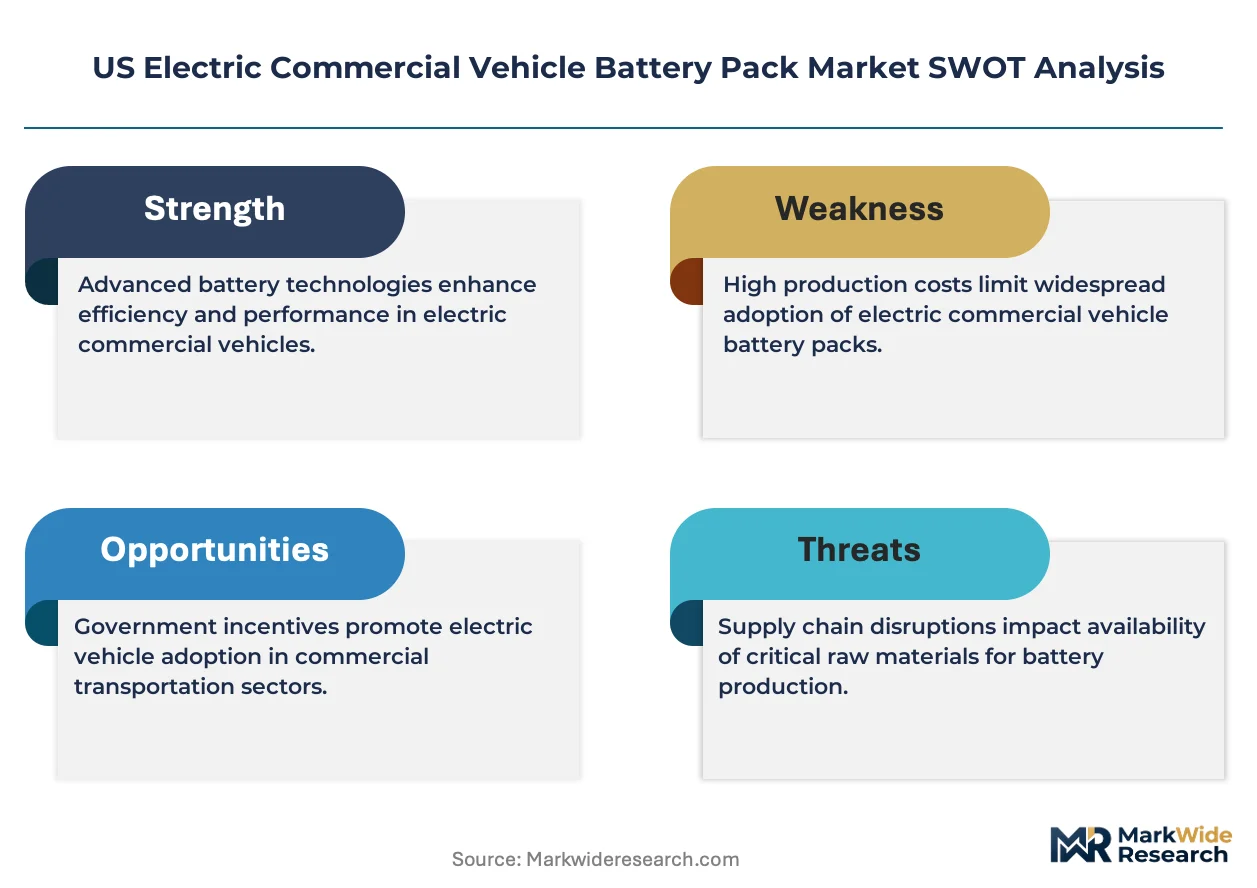
Project finance and battery leasing arrangements are reshaping competitive entry in the US electric commercial vehicle battery pack sector. CATL leverages its cell-to-pack architecture to sustain cost leadership for heavy-duty truck applications. Tesla anchors its position through in-house production of structural battery packs integrated with its commercial vehicle platforms. Ford Motor Company competes by extending its BlueOval SK joint venture manufacturing footprint across the Midwest.
US electric commercial vehicle battery packs are electrochemical energy storage systems engineered with lithium-ion cells, thermal management circuits, and battery management units that deliver sustained power output for commercial duty cycles. These systems typically operate at 400-800 volts and incorporate liquid cooling loops to maintain optimal cell temperatures during high-rate discharge scenarios common in freight and transit operations. Lithium-ion chemistry dominates current deployments due to its energy density and declining cell costs, while solid-state architectures represent the fastest-growing technology segment as manufacturers target extended range and reduced thermal runaway risk. Delivery vans command the largest vehicle-type volume as e-commerce fulfillment networks electrify, whereas refrigerated vehicles concentrate margin pools because cold-chain duty cycles demand specialized thermal packaging and higher-capacity configurations.
The EPA tailpipe emission standards and NHTSA fuel economy regulations for heavy-duty vehicles are tightening compliance thresholds that compel fleet operators toward electrification. California Air Resources Board mandates through the Advanced Clean Trucks rule are creating a de facto national product standard as manufacturers optimize for the most restrictive jurisdiction. OSHA workplace safety standards for high-voltage systems also shape service infrastructure requirements and technician certification protocols. Stakeholders must monitor how IRA domestic content provisions evolve to determine qualifying assembly locations and critical mineral sourcing strategies.
Market Dynamics
Fleet electrification mandates are compressing procurement timelines as California's Advanced Clean Trucks rule forces OEMs to accelerate zero-emission vehicle development cycles ahead of federal compliance thresholds.
Growth Catalysts
- Advanced Clean Trucks Regulation:California Air Resources Board mandates compel manufacturers to achieve escalating zero-emission sales percentages, creating guaranteed demand pull for battery pack producers serving the US market.
- Last-Mile Logistics Electrification:E-commerce fulfillment networks are electrifying delivery van fleets as total cost of ownership parity with diesel powertrains approaches in urban duty cycles.
- Co-Location Manufacturing Clusters:Battery assembly plants and commercial vehicle OEM facilities are concentrating in Texas and the Great Lakes corridor, reducing logistics costs and tightening supply chain integration.
Market Restraints
- Lithium Price Volatility:Cell-grade lithium carbonate and hydroxide price swings compress pack manufacturer margins and complicate long-term contract pricing with fleet customers.
- Domestic Cell Capacity Concentration:Limited US-based cell production forces reliance on imported cylindrical and prismatic cells, exposing pack assemblers to tariff risk and supply disruption.
- Charging Infrastructure Gap:Insufficient high-power depot charging and corridor fast-charging networks constrain fleet electrification velocity in rural and interstate trucking routes.
Strategic Opportunities
- IRA Domestic Content Credits:Inflation Reduction Act assembly and critical mineral sourcing incentives reward pack producers qualifying battery components for commercial vehicle tax credits.
- Refrigerated Vehicle Electrification:Cold-chain duty cycles demand specialized thermal packaging and higher-capacity configurations, creating margin pools above standard delivery van applications.
- Battery Leasing Models:Project finance and lease arrangements separate pack asset ownership from vehicle procurement, lowering fleet capital barriers and opening recurring revenue streams for pack providers.
Industry Challenges
- High-Voltage Technician Certification:OSHA workplace safety standards for battery servicing require specialized training protocols that outpace current vocational program output, constraining service network expansion.
- Thermal Runaway Containment Design:Pack engineers must integrate cell-level failure isolation and suppression systems that satisfy NHTSA safety investigations while maintaining energy density targets.
- Legacy Fleet Integration Complexity:Retrofit battery systems for existing diesel chassis demand custom mechanical and electrical engineering that fragments production scale and extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electric Commercial Vehicle Battery Pack Market |
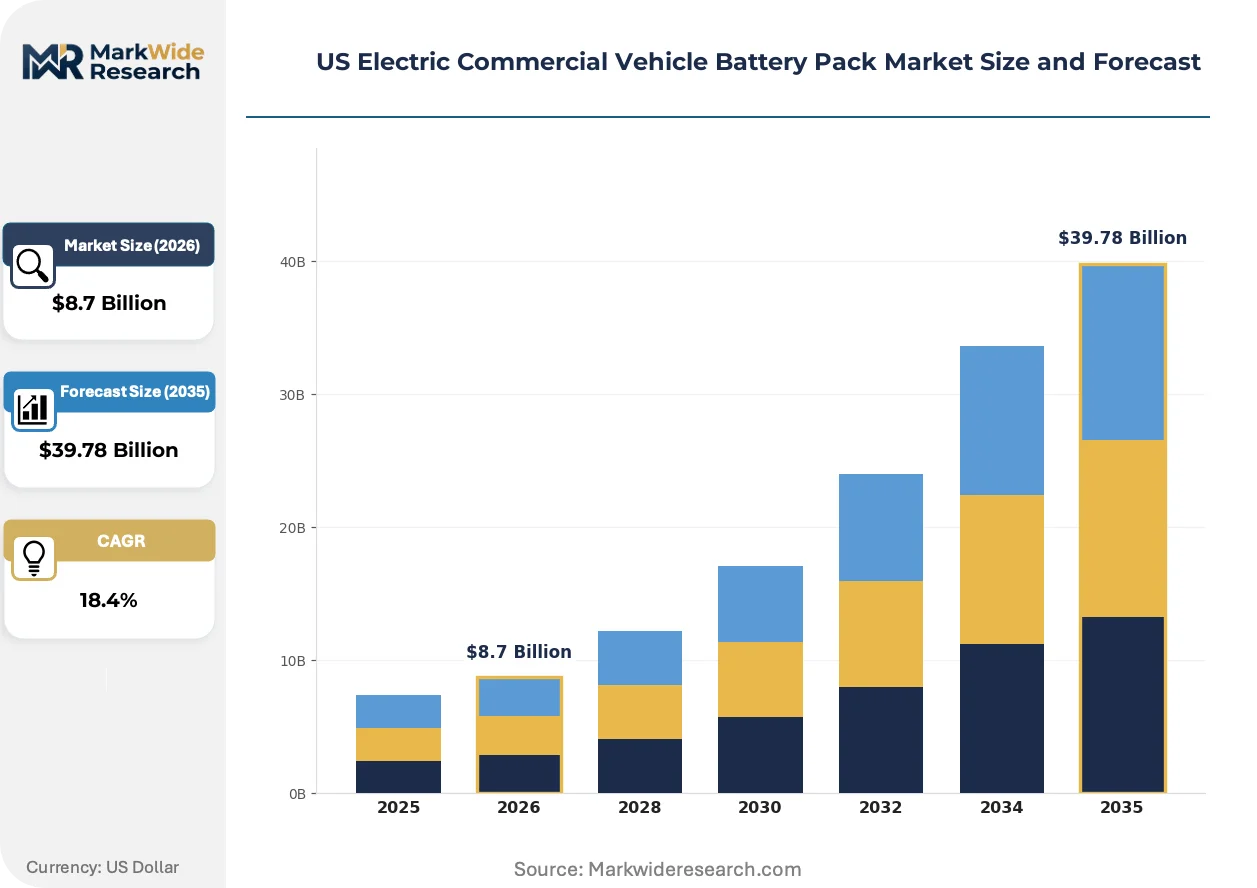
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead Acid, Solid State Vehicle Type: Delivery Vans, Buses, Trucks, Refrigerated Vehicles Charging Method: Fast Charging, Standard Charging, Wireless Charging, Battery Swapping End User: Logistics, Public Transport, Construction, Food Delivery |
| Companies Covered | BYD Company Ltd., Contemporary Amperex Technology Co. Ltd. (CATL), LG Energy Solution Ltd., Samsung SDI Co. Ltd., Tesla Inc., Panasonic Holdings Corporation, SK On, General Motors, Ford Motor Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electric Commercial Vehicle Battery Pack Market Trends and Innovations
Cell-to-pack architectures are eliminating module housings and interconnection hardware, fundamentally restructuring how energy density and manufacturing cost trade-offs resolve in heavy-duty applications.
Solid-state electrolyte technology is collapsing the thermal management burden and fire suppression system mass that conventional liquid-cooled lithium-ion packs require for safe operation. Freight operators running high-utilization routes are piloting solid-state prototypes to extend range without payload penalty. This compression of auxiliary system overhead is enabling pack designers to reclaim 15-20% of pack volume for additional cell capacity.
EPA tailpipe emission standards and NHTSA fuel economy regulations for heavy-duty vehicles are tightening compliance thresholds that compel fleet operators toward electrification. Manufacturers optimizing for the most restrictive jurisdiction are standardizing California Air Resources Board-compliant designs across national product lines. Heavy-duty regional haul and urban delivery segments face the steepest compliance cost escalation and are responding with accelerated zero-emission vehicle pilot programs.
Fleet procurement departments are unbundling battery pack acquisition from vehicle chassis purchase, treating energy storage as a separate capital decision with distinct financing and residual value recovery strategies. Third-party battery lessors and energy service companies are inserting themselves between OEMs and fleet operators, capturing margin that previously flowed through vehicle dealerships. This channel restructuring is most visible in California and New York where state-level incentives favor asset-light operating models for municipal and private delivery fleets.
US Electric Commercial Vehicle Battery Pack Market Segmentation
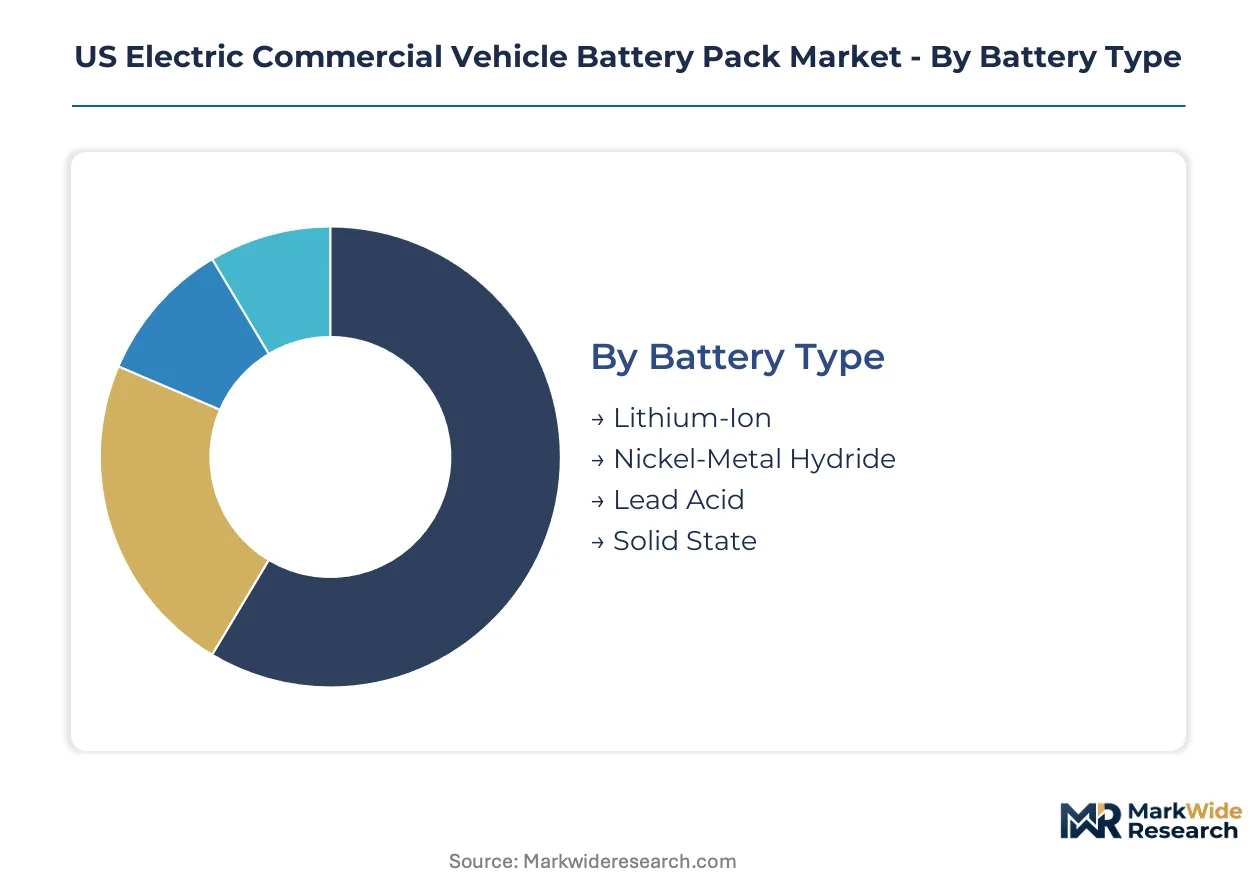
Segmentation in the US electric commercial vehicle battery pack market reveals how duty cycle intensity, thermal requirements, and fleet operating models dictate pack specifications. Procurement patterns diverge sharply between high-utilization logistics networks and intermittent municipal service applications.
Battery Type:
Lithium-ion chemistries dominate mature deployments while solid-state architectures represent the emerging frontier for extended-range heavy-duty applications.
- Lithium-Ion:NMC and LFP cell formulations deliver 150-300 Wh/kg energy density with established thermal management protocols. Fleet operators in Texas and the Great Lakes corridor specify these packs for delivery van routes where charging infrastructure density supports mid-shift opportunity charging.
- Solid State:Sulfide and oxide electrolyte architectures eliminate liquid electrolyte fire risk while enabling 400+ Wh/kg cell-level density. California-based freight operators pilot these systems for refrigerated long-haul corridors where payload preservation and range extension justify premium pack costs.
- Nickel-Metal Hydride:Legacy chemistry retains niche presence in transit bus retrofits where capital constraints limit lithium-ion conversion scope.
- Lead Acid:Auxiliary power unit applications in construction equipment persist where deep-cycle durability outweighs energy density requirements.
Lithium-ion handles the majority of throughput; solid-state is expanding most quickly on share as IRA domestic content incentives accelerate pilot programs.
Vehicle Type:
Application-specific thermal loads and duty cycle profiles create distinct pack specification tiers across commercial vehicle categories.
- Delivery Vans:Compact form factor packs at 400-600V operating voltage serve last-mile logistics networks. E-commerce fulfillment centers in California and New York specify these configurations where depot charging and urban route density enable full electrification.
- Refrigerated Vehicles:Dual-circuit thermal management packs integrate traction battery cooling with refrigeration unit power draw. Cold-chain operators demand 20-30% higher capacity configurations than standard vans, creating specialized margin pools for pack assemblers.
- Buses:High-floor and low-floor transit configurations require distinct pack mounting architectures with NHTSA rollover protection compliance.
- Trucks:Class 4-8 vocational applications impose sustained high-rate discharge demands that accelerate cell degradation without active liquid cooling.
Delivery vans command the largest unit volumes; refrigerated vehicles are gaining share fastest as cold-chain electrification mandates tighten.
Charging Method:
Infrastructure availability and fleet utilization rates determine charging technology selection across operator segments.
- Fast Charging:150-350 kW DC systems enable 80% state-of-charge recovery in 30-45 minutes for high-rotation logistics fleets. Interstate corridor operators along Texas-to-California freight routes prioritize these configurations to minimize asset downtime.
- Battery Swapping:Standardized pack form factors allow 3-5 minute exchange cycles matching diesel refueling duration. Regional haul operators in the Great Lakes manufacturing corridor pilot swap networks to eliminate charging dwell time from duty cycle planning.
- Standard Charging:50-100 kW AC and DC overnight depot systems serve municipal and school bus fleets with predictable return-to-base patterns.
- Wireless Charging:Inductive pad systems at distribution center loading docks enable opportunity charging without connector wear.
Fast charging handles the majority of installed infrastructure investment; battery swapping is climbing the fastest as OEMs standardize pack interfaces.
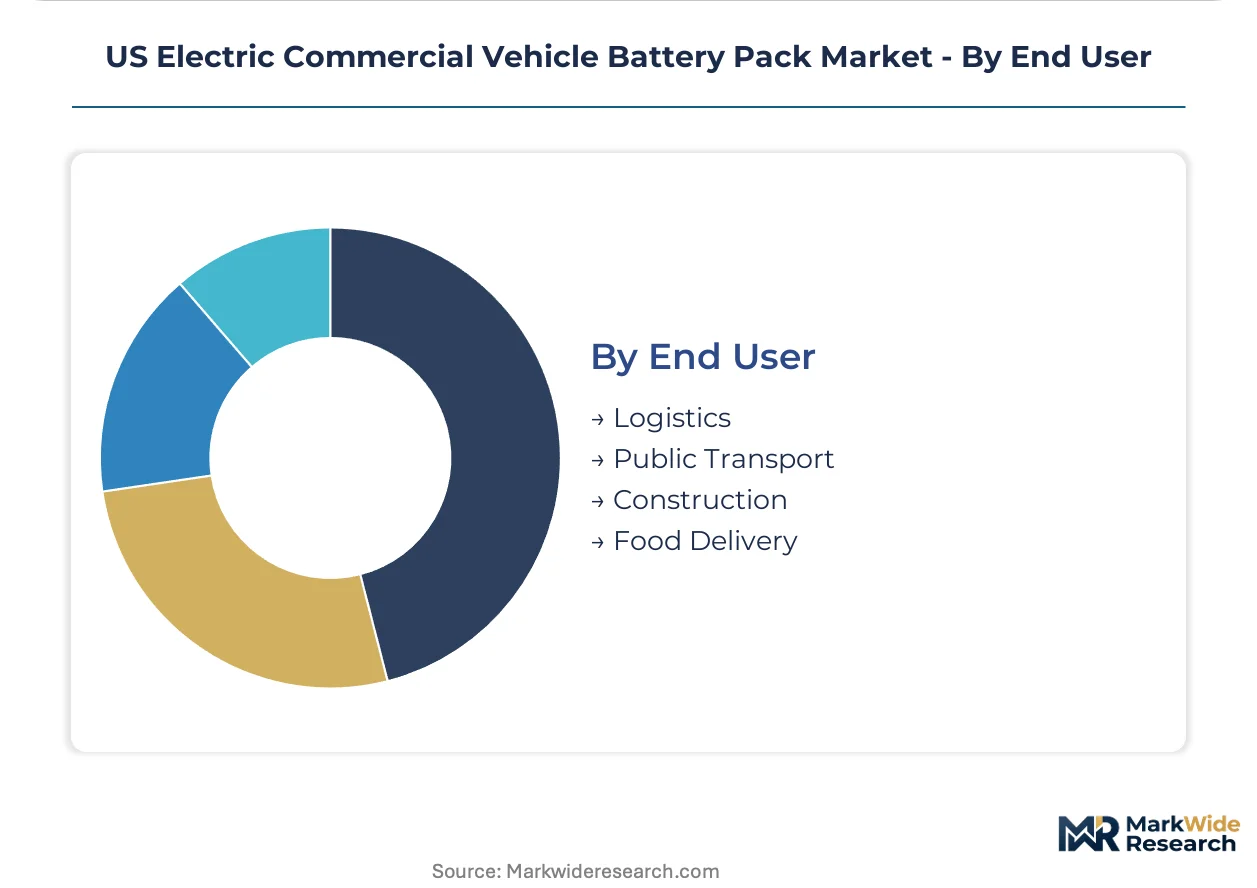
End User:
Fleet scale and operational predictability separate high-volume contract manufacturing from custom engineering engagements.
- Logistics:National parcel carriers and regional last-mile operators specify packs through multi-year procurement agreements with residual value guarantees. Amazon, UPS, and FedEx electrification commitments in California and Texas anchor demand concentration.
- Public Transport:Municipal transit authorities and school districts issue RFPs with Buy America compliance requirements that favor domestic pack assembly locations.
- Construction:Vocational equipment OEMs demand ruggedized pack enclosures with IP67 ingress protection for off-highway duty cycles.
- Food Delivery:Gig economy fleet operators prioritize lowest capital entry points, often selecting leased pack arrangements over direct ownership.
Logistics commands the dominant procurement volume; food delivery is the fastest-expanding user segment as app-based platforms electrify contractor vehicle pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US electric commercial vehicle battery pack market exhibits pronounced regional concentration, with domestic production capacity expanding fastest in states offering IRA-compliant assembly incentives and co-located OEM demand.
California
Last-mile logistics electrification and cold-chain fleet mandates drive procurement volume. CARB Advanced Clean Trucks regulation compels zero-emission sales percentages that OEMs cannot satisfy without dedicated battery supply agreements. The Central Valley and Inland Empire host distribution center clusters where depot charging infrastructure enables full delivery van electrification.
Texas
Interstate freight corridors and energy sector capital access attract battery assembly plant investments. ERCOT grid dynamics and industrial electricity rates below national averages reduce pack production energy costs. The Dallas-Fort Worth Metroplex anchors logistics fleet procurement alongside Houston's port-related drayage electrification pilots.
Michigan
Legacy automotive engineering talent and OEM headquarters proximity sustain pack development engineering. The state's manufacturing extension partnerships facilitate workforce transition from internal combustion to high-voltage battery assembly. Detroit and Lansing metropolitan areas concentrate prototype testing facilities for heavy-duty truck applications.
Ohio
Appalachian lithium processing investments and Great Lakes shipping access reduce critical mineral logistics costs. The state's automotive supplier density enables just-in-time cell delivery to pack assembly operations. Columbus and Toledo host joint venture manufacturing footprints serving Midwest delivery van and school bus electrification demand.
New York
Municipal fleet electrification mandates and congestion pricing policies accelerate urban commercial vehicle turnover. NYSERDA incentive programs favor battery leasing models that lower capital barriers for small fleet operators. The New York Metro area concentrates food delivery platform electrification alongside MTA bus depot charging infrastructure deployment.
US Electric Commercial Vehicle Battery Pack Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cell supply and thermal management subsystems. The market structure consolidates around vertically integrated OEMs and independent pack assemblers serving multi-brand fleets. Three archetypes dominate: captive producers supplying affiliated vehicle platforms, independent contract manufacturers serving diversified OEM portfolios, and energy service companies offering battery-as-a-service arrangements. Capacity expansion and strategic joint ventures constitute the primary competitive moves as players secure IRA-compliant domestic assembly locations.
Within the captive producer tier, Tesla Inc. and Ford Motor Company exemplify platform-integrated strategies where pack design aligns with proprietary vehicle architectures. Contemporary Amperex Technology Co. Ltd. occupies a position as an independent contract manufacturer supplying multiple OEM platforms. These three entities represent divergent approaches to securing supply chain position: in-house production control, joint venture manufacturing scale, and cell-to-pack cost leadership.
| Leading Market Players |
|---|
| BYD Company Ltd. |
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| LG Energy Solution Ltd. |
| Samsung SDI Co. Ltd. |
| Tesla Inc. |
| Panasonic Holdings Corporation |
| SK On |
| General Motors |
| Ford Motor Company |
| Others |
Pricing and Supply Chain Analysis
The Great Lakes manufacturing corridor concentrates cell-to-pack assembly capacity that OEMs leverage for IRA-compliant production, translating supply scarcity into pricing leverage for domestic producers serving fleet operators with multi-year procurement agreements. California's Advanced Clean Trucks mandates compress buyer timelines, forcing acceptance of premium pricing for qualifying battery configurations that satisfy zero-emission sales thresholds.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing that stratifies across premium, standard, and economy tiers based on thermal management sophistication and domestic content certification. Volume scale and vertical integration status differentiate price bands, with in-house cell production commanding 15-20 point margin advantages over import-dependent assemblers. Cost compression in standard-tier packs is intensifying because lithium carbonate price volatility feeds through to cell-grade material contracts. Municipal transit authorities exhibit highest price sensitivity due to fixed budget cycles, while national logistics carriers absorb premiums for residual value guarantees and service bundling.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Korean and Japanese cathode material suppliers stabilize working capital for pack assemblers facing 90-120 day production cycles. Cell-grade lithium hydroxide draws from Australian hard-rock spodumene and Chilean brine operations, with nickel sulfate and cobalt sulfate resting on Indonesian and DRC processing capacity. Tariff exposure on Chinese-origin cylindrical cells creates single-source vulnerability for prismatic cell-dependent heavy-duty configurations. Distribution runs through regional OEM integration centers in Texas and Michigan that coordinate just-in-time pack delivery to vehicle assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification mandates function as a cyclical recovery mechanism, with California Air Resources Board compliance thresholds forcing replacement demand that absorbs excess pack capacity accumulated during development-phase overbuild.
For Market Incumbents: Insulate margin structures through captive cathode precursor production in Appalachian processing corridors, securing IRA critical mineral credits that emerging Asian competitors cannot replicate. Accelerate NHTSA thermal runaway certification investments to create regulatory moats against solid-state entrants threatening conventional lithium-ion architectures. Joint venture manufacturing scale in Ohio and Michigan tightens supply chain integration against price volatility from imported cell inputs.
For New Entrants and Emerging Players: Battery-as-a-service arrangements for food delivery platforms in New York and California represent the most penetrable entry point, separating pack asset ownership from vehicle procurement to bypass capital-intensive OEM supply relationships. Refrigerated vehicle electrification in Texas interstate corridors offers specialized thermal packaging margin pools above commoditized delivery van applications. Direct channel partnerships with third-party fleet lessors bypass entrenched dealership networks that incumbents control.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among energy service companies offering battery leasing with residual value recovery mechanisms, positioning these archetypes for sustained cash flow quality through mid-decade fleet turnover cycles. Acquisition targets should emphasize domestic assembly qualification under IRA provisions and established thermal management IP for cold-chain duty cycles. Watch NHTSA rulemaking on heavy-duty battery safety standards as the inflection signal determining which cell architectures achieve platform design wins.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Manufacturing Scale-Up | CATL's architecture eliminates module housings, compressing pack cost structures for heavy-duty truck OEMs. |
| Domestic Cathode Precursor Integration | Appalachian lithium processing investments reduce critical mineral logistics costs for IRA-compliant assembly. |
| Battery Leasing Platform Launch | Third-party lessors capture margin between OEMs and fleet operators in California and New York incentive markets. |
| Thermal Runaway Certification Investment | NHTSA-compliant suppression systems create regulatory barriers against unproven solid-state entrants. |
| Refrigerated Pack Specialization | Dual-circuit thermal management commands 20-30% capacity premiums from cold-chain operators. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement directors, battery pack engineering leads, OEM platform planners, and IRA policy specialists and refined through secondary validation against EPA regulatory filings, NHTSA safety investigation databases, CARB compliance reports, and DOE manufacturing incentive disclosures. Bottom-up cell production capacity estimates were triangulated with top-down fleet electrification commitment aggregations across the analysis window.
Demand-supply-balance framing structured the analytical framework across vehicle type, battery chemistry, charging method, and end-user segmentation dimensions. CAGRs were derived from installed base turnover rates and replacement cycle compression under regulatory mandates. Model inputs incorporated lithium carbonate futures curves, regional electricity rate differentials affecting production costs, and OEM platform launch timelines.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity rates, lithium spot prices, or federal incentive continuity would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and cell chemistry cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Control Unit Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
New Energy Vehicle (NEV) Taxi Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
Electric Vehicle E-Axle Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
EV Lightweight Materials Market