
 Global Electric Vehicles Engineering Plastics Market | 2026-2036
Global Electric Vehicles Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Vehicles Engineering Plastics Market Analysis
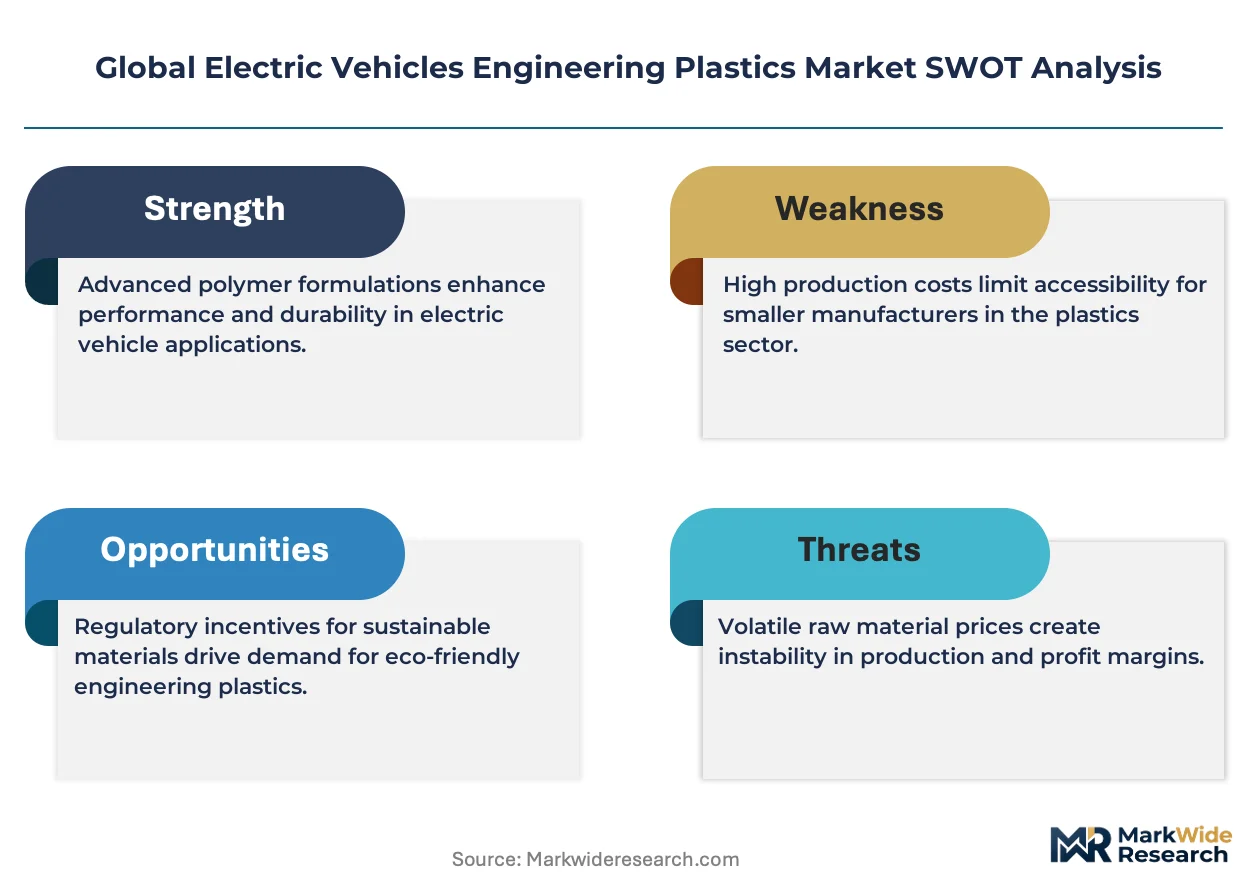
The capital-intensity divergence between integrated resin producers and compounders is reorganizing competitive tiers in electric vehicle plastics. BASF SE leverages its Ludwigshafen Verbund site to sustain backward integration into caprolactam for nylon battery housings. SABIC anchors its position through differentiated high-heat polycarbonate grades for EV power electronics. Covestro AG competes on optical-quality polycarbonate for interior display housings, while DuPont specializes in Zytel nylon variants for thermal management modules.
Electric vehicles engineering plastics encompass thermoplastic polymers formulated to withstand elevated temperatures, electrical loads, and mechanical stress in electrified powertrains, typically requiring Vicat softening temperatures above 130°C and UL94 V-0 flame ratings for battery-adjacent components. These materials replace metal to reduce curb weight and extend driving range per charge. Nylon and polycarbonate dominate current volume owing to their established supply chains and processing familiarity, while high-performance grades capture disproportionate margin pools in battery enclosures and inverter housings. Polypropylene maintains cost leadership in non-structural interior panels where thermal demands remain modest.
The US EPA tailpipe standards and the EU Green Deal's embedded carbon rules are forcing OEMs to document full lifecycle polymer emissions, reshaping supplier qualification criteria. China's MIIT enforces GB standards for battery compartment flame resistance, creating divergent testing protocols across export destinations. REACH and RoHS compliance in Europe adds substance-restriction layers that compound formulation complexity. Stakeholders must monitor regulatory fragmentation between California's Advanced Clean Cars program and emerging ASEAN technical regulations as they decide regional compound localization strategies.
Market Dynamics
Flame-retardant certification requirements for battery-adjacent components are compressing qualification timelines and concentrating procurement among resin compounders with in-house testing capabilities. China's GB standards for battery compartment flame resistance and the EU Green Deal's embedded carbon documentation rules are forcing parallel compliance investments across multiple export destinations.
Growth Catalysts
- MIIT battery safety mandates:China's GB standards for thermal runaway containment are mandating UL94 V-0 rated materials in battery enclosures, pulling engineering-grade nylon and polycarbonate into new vehicle programs.
- Power electronics thermal loads:Silicon carbide inverter adoption is pushing operating temperatures above 150°C, expanding addressable volume for high-heat polymer grades in traction modules.
- Stuttgart-Wolfsburg corridor concentration:Germany's automotive engineering cluster is localizing resin compounding capacity to serve BMW, Mercedes-Benz, and Volkswagen platform rollouts.
Market Restraints
- Caprolactam supply concentration:Nylon 6 feedstock production clusters in Northeast Asia and the US Gulf Coast expose compounders to benzene derivative volatility and force majeure risks.
- REACH substance restrictions:ECHA's evolving SVHC candidate list is forcing reformulation of halogenated flame retardants, extending R&D cycles by 18-24 months for recertification.
- Metal substitution ceiling:Structural battery pack components above 40 kWh capacity retain aluminum or steel due to modulus limitations in thermoplastic composites.
Strategic Opportunities
- India PLI scheme localization:The country's production-linked incentive program for advanced chemistry cell manufacturing is creating virgin demand for battery housing materials without established supply relationships.
- Optical-grade polycarbonate convergence:Interior display housings and lidar lens applications are merging specifications, enabling volume aggregation across previously separate procurement channels.
- Recycled content mandates:The EU Green Deal's recycled plastics targets for automotive applications are rewarding compounders with mechanical recycling capabilities in closed-loop OEM agreements.
Industry Challenges
- Flame-retardant formulation expertise gap:UL94 certification testing and GB standard compliance require specialized polymer scientists that resin compounders struggle to recruit from adjacent industries.
- Multi-jurisdiction certification timelines:Simultaneous NMPA, EPA, and REACH compliance for a single battery housing grade extends qualification to 36 months, freezing design-in decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Vehicles Engineering Plastics Market |
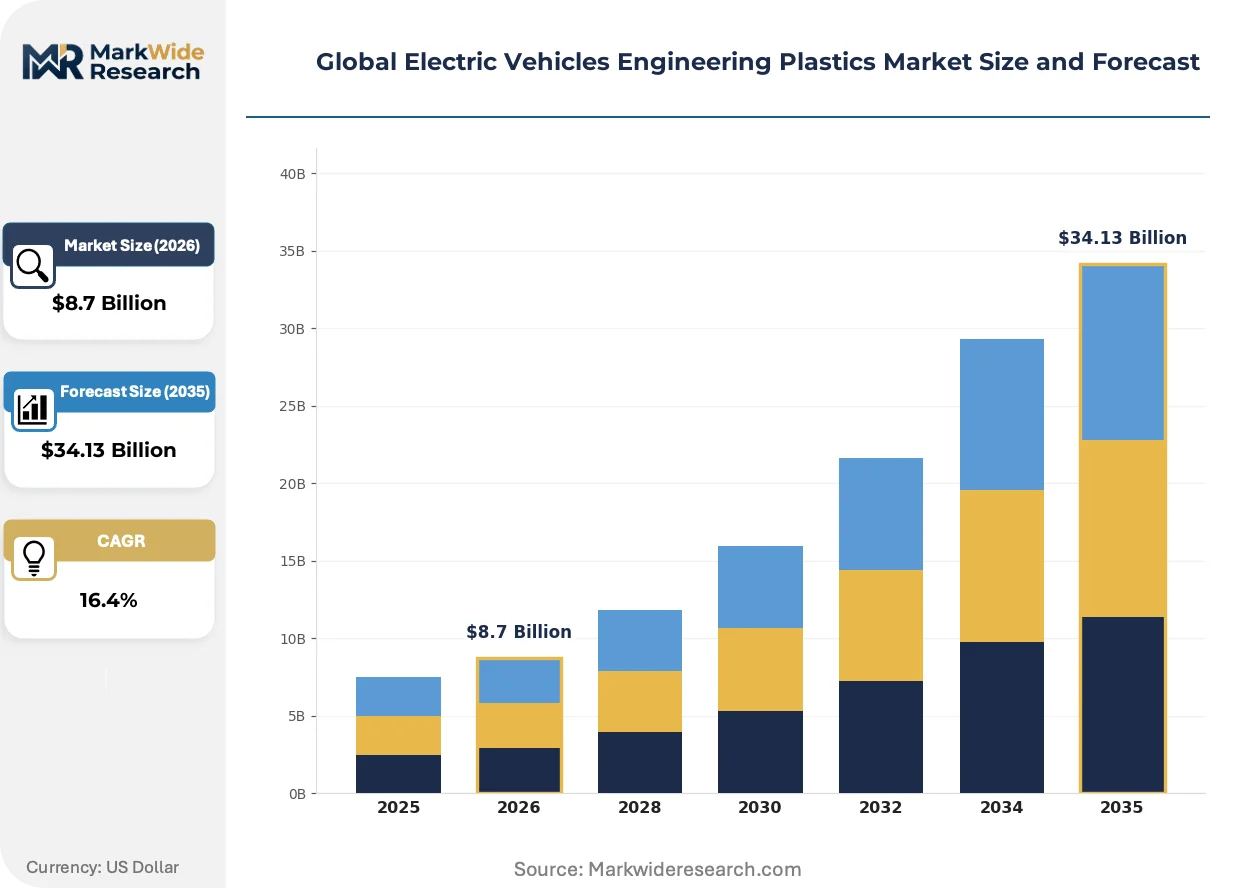
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ABS, PC, Nylon, PP Application: Interior, Exterior, Under-the-Hood, Chassis End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Grade: High Performance, Standard, Engineering, Specialty |
| Companies Covered | BASF SE, SABIC, LyondellBasell Industries Holdings B.V., Evonik Industries, Covestro AG, DuPont, LG Chem, Asahi Kasei, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Vehicles Engineering Plastics Market Emerging Trajectories
Material substitution patterns are fragmenting as OEMs balance thermal performance, weight reduction, and recyclability credentials in platform-specific decisions. The convergence of battery chemistry evolution and polymer processing advances is creating new specification categories.
Bio-based polyamide feedstocks derived from castor oil are decomposing the petroleum-dependent supply structure for high-temperature underhood applications. Tier 1 suppliers in Germany and Japan are qualifying these grades for charge port housings and thermal management modules. The structural consequence is a bifurcation in resin procurement, with sustainability-mandated vehicle programs diverging from cost-optimized volume platforms.
The EU Green Deal's embedded carbon reporting rules are forcing OEMs to document polymer lifecycle emissions from extraction through end-of-life. This industrial consequence is reshaping supplier scorecards, with compounders required to provide ISO 14040-compliant LCA data for qualification. Battery enclosure procurement in Europe is responding by prioritizing suppliers with renewable energy certificates and mass-balance certified feedstocks.
Consolidated platform sourcing is replacing discrete component procurement for battery system housings. Cell-to-pack architectures are compressing the supplier base, with OEMs awarding multi-year resin supply agreements to compounders capable of co-developing thermal runaway containment solutions. This pattern is most visible in China's NEV sector, where CATL and BYD are vertically integrating material specification into their platform designs.
Global Electric Vehicles Engineering Plastics Market Segmentation
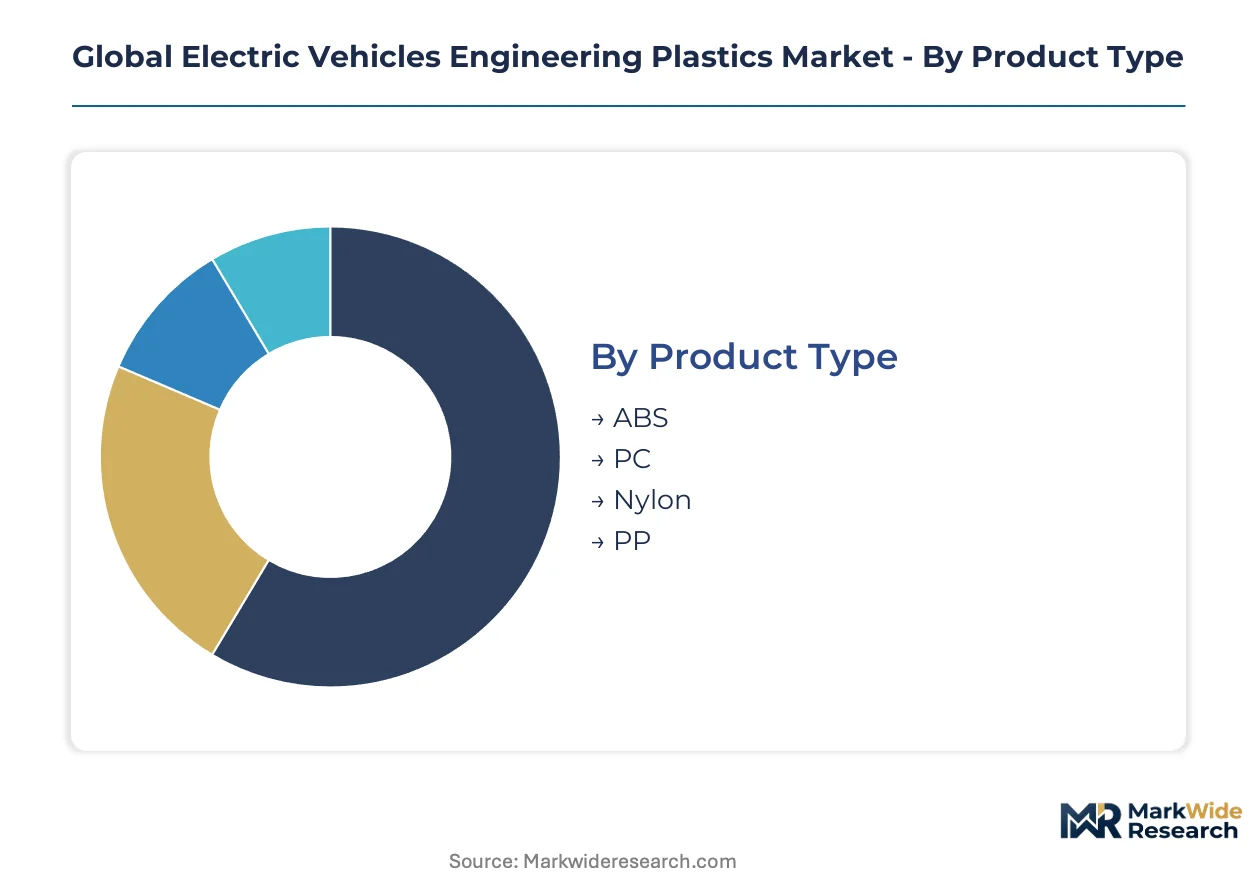
Engineering plastics procurement in electric vehicles fragments across multiple decision axes. OEM material engineers weigh thermal performance against processing economics, while regulatory compliance layers create non-negotiable specification floors that reshape viable supply options.
Product Type:
Margin pools concentrate in flame-retardant grades certified for battery-adjacent applications, where technical barriers protect pricing power.
- Nylon:Polyamide formulations dominate battery enclosure applications through inherent flame resistance and dimensional stability under thermal cycling. China's MIIT GB standards for thermal runaway containment are pulling UL94 V-0 rated nylon grades into new vehicle programs from BYD and CATL supply chains.
- Polycarbonate:High-heat PC grades capture premium positioning in power electronics housings where silicon carbide inverter adoption pushes operating temperatures above 150°C. SABIC and Covestro compounders anchor supply relationships through differentiated optical and thermal grades.
- ABS:Cost-optimized interior components leverage established injection molding infrastructure.
- PP:Polypropylene retains volume leadership in non-structural panels where thermal demands remain modest.
The dominant share belongs to Nylon, while Polycarbonate is closing the gap fastest.
Application:
Cost tier separation between structural and cosmetic applications drives distinct procurement channel formation.
- Under-the-Hood:Thermal management modules, inverter housings, and charge port assemblies demand Vicat softening temperatures above 150°C. Germany's Stuttgart-Wolfsburg corridor concentrates specification development for these high-stress applications.
- Interior:Display housings and lidar lens applications merge optical-grade polycarbonate specifications, enabling volume aggregation.
- Exterior:Body panels and trim components balance weathering resistance with weight reduction targets.
- Chassis:Structural battery pack components above 40 kWh capacity retain metal due to modulus limitations in thermoplastic composites.
Under-the-Hood commands the steepest premium pricing, though Interior applications are expanding most quickly through display convergence.
End User:
Customer type determines technical dialogue depth and contract structure variation across the value chain.
- OEMs:Volkswagen, BMW, and Mercedes-Benz platform teams co-develop material specifications directly with compounders, locking in multi-year supply agreements for cell-to-pack architectures.
- Tier-1 Suppliers:Bosch and Continental procurement organizations intermediate resin selection for modular subsystems.
- Vehicle Assemblers:Contract manufacturers execute material specifications handed down from platform owners.
- Aftermarket Providers:Repair and replacement channels source through distribution networks with limited technical specification involvement.
OEMs retain the deepest specification control, while Tier-1 Suppliers are gaining procurement influence through subsystem integration.
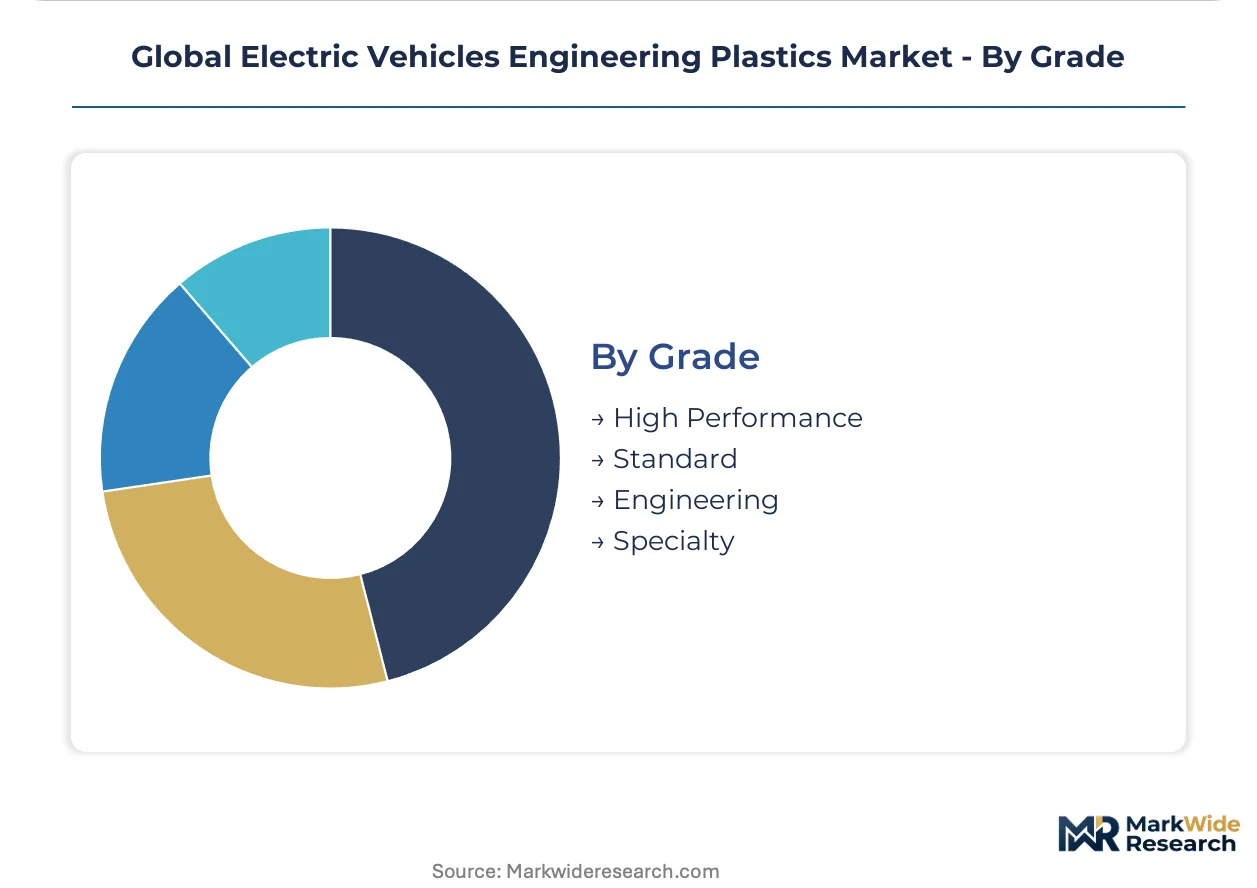
Grade:
Supply concentration in high-performance compounding capabilities creates tiered market access.
- High Performance:Formulations meeting combined thermal, electrical, and flame-resistance thresholds for battery enclosures command qualification timelines exceeding 24 months. REACH SVHC restrictions on halogenated flame retardants are forcing reformulation cycles that extend R&D investment recovery periods.
- Specialty:Bio-based polyamide feedstocks derived from castor oil are qualifying for charge port housings under EU Green Deal embedded carbon reporting requirements.
- Engineering:Mid-tier grades balance property profiles against processing economics for volume applications.
- Standard:Commodity specifications serve cost-optimized platforms with modest thermal or regulatory demands.
High Performance grades dominate margin capture, while Specialty grades are gaining share fastest through sustainability-mandated vehicle programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and China absorb premium pricing for flame-retardant battery grades with minimal elasticity, while procurement teams in India and Mexico remain acutely price-sensitive on standard engineering resins. This demand-elasticity contrast shapes regional compounding capacity investments and localization timelines.
China
CATL and BYD platform rollouts are consuming UL94 V-0 rated nylon grades at unprecedented scale. MIIT enforces GB standards for thermal runaway containment that exceed export-market thresholds. The Yangtze River Delta cluster around Shanghai anchors resin compounding capacity expansion to serve cell-to-pack architecture demand.
Germany
Mercedes-Benz, BMW, and Volkswagen procurement teams co-develop material specifications directly with compounders for high-voltage battery housings. EU Green Deal embedded carbon documentation rules force ISO 14040-compliant LCA data submission for supplier qualification. The Stuttgart-Wolfsburg corridor concentrates specification development for silicon carbide inverter applications above 150°C.
United States
EPA tailpipe standards and California's Advanced Clean Cars program are accelerating engineering plastics substitution in Detroit Three platform designs. IRA domestic content incentives are reshaping resin procurement toward North American compounding capacity. The US Gulf Coast caprolactam production cluster exposes compounders to benzene derivative volatility.
India
PLI scheme incentives for advanced chemistry cell manufacturing are creating virgin demand for battery housing materials without established supply relationships. BIS is developing automotive polymer standards that will diverge from European REACH frameworks. Tamil Nadu and Gujarat are attracting resin compounder greenfield investments to serve emerging OEM assembly operations.
Japan
Asahi Kasei and Toyota co-development programs are qualifying high-heat polycarbonate grades for next-generation traction inverters. METI carbon neutrality roadmaps are pressuring suppliers to document mass-balance certified feedstocks. The Nagoya-Toyota industrial corridor maintains tight technical dialogue between resin producers and Tier-1 subsystem integrators.
Global Electric Vehicles Engineering Plastics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated resin producers with backward integration into petrochemical feedstocks compete on scale and supply security, while specialized compounders capture premium positioning through formulation expertise and certification capabilities. Three archetypes dominate: integrated petrochemical majors, independent engineering plastics compounders, and regional specialists serving single-country certification requirements. Capacity expansion and strategic partnerships represent the dominant competitive moves, with compounders locking in multi-year supply agreements with OEM platform teams.
Within the integrated petrochemical tier, BASF SE anchors European supply relationships through its Ludwigshafen Verbund operations, while SABIC represents Middle Eastern feedstock-advantaged positioning. Among Asia-Pacific compounders, LG Chem exemplifies the battery chemistry-to-materials convergence archetype. Each occupies a distinct competitive position based on geographic origin and structural integration depth rather than interchangeable product offerings.
| Leading Market Players |
|---|
| BASF SE |
| SABIC |
| LyondellBasell Industries Holdings B.V. |
| Evonik Industries |
| Covestro AG |
| DuPont |
| LG Chem |
| Asahi Kasei |
| LANXESS |
| Others |
Supply Flow & Price Mechanics
Ninety-day qualification timelines for UL94 V-0 certified nylon grades compress procurement cycles and concentrate pricing power among German and Chinese compounders with in-house flame-retardant testing capabilities. Battery enclosure manufacturers absorb premium spreads for certified materials while standard engineering resins face cost compression from polypropylene substitution in non-structural applications.
Pricing Analysis
After-market service contracts and technical support agreements drive lifetime value capture beyond resin unit sales. Three-tier pricing structure across premium, standard, and economy levels separates UL94 V-0 certified battery grades from mid-tier engineering formulations and commodity polypropylene. Pricing pressure stems from REACH SVHC reformulation cycles extending R&D recovery periods for halogenated flame-retardant alternatives. Tier-1 suppliers exhibit acute price sensitivity on standard grades, while OEM platform teams absorb premiums for thermal runaway containment certification.
Supply Chain Analysis
Inventory buffers for caprolactam feedstock stretch 45-60 days as Northeast Asian and US Gulf Coast production clusters expose compounders to benzene derivative volatility. Nylon 6 supply anchors in China, Germany, and the United States, with polycarbonate compounding capacity concentrating in Saudi Arabia, Japan, and Belgium. Raw material flows draw from benzene, bisphenol-A, and adipic acid streams tethered to petrochemical complex economics. Single-source vulnerability runs through China's Yangtze River Delta for battery-grade flame-retardant additives. Distribution runs through direct OEM platform agreements and Tier-1 subsystem integrators with technical specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack battery architectures are disrupting established procurement channels, creating first-mover advantages for compounders capable of co-developing thermal management solutions with CATL and BYD platform teams.
For Market Incumbents: Fortify backward integration into caprolactam and bisphenol-A feedstocks to defend margin position against benzene price volatility. Expand flame-retardant testing laboratory capacity in Stuttgart-Wolfsburg corridor to compress 36-month multi-jurisdiction certification timelines. Prioritize mass-balance certified feedstock documentation for EU Green Deal supplier scorecard compliance. For New Entrants and Emerging Players: Differentiate on bio-based polyamide formulations derived from castor oil for EU sustainability-mandated vehicle programs. Target India's PLI scheme localization gap for advanced chemistry cell battery housings where supply relationships remain unformed. Pursue co-development partnerships with Tamil Nadu and Gujarat OEM assembly operations seeking technical specification support. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-performance flame-retardant compounding as REACH reformulation cycles extend R&D investment recovery. Compounders with integrated testing capabilities and renewable energy certificates command premium positioning through the projection horizon. Monitor GB standard harmonization progress between China's MIIT and export-market regulators as inflection indicator for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | BASF's Ludwigshafen Verbund operations demonstrate captive feedstock security against benzene volatility. |
| Flame-Retardant Testing Laboratory Expansion | In-house UL94 and GB standard certification capabilities compress 36-month qualification timelines for battery enclosures. |
| Mass-Balance Certified Feedstock Sourcing | ISO 14040-compliant LCA data submission satisfies EU Green Deal embedded carbon documentation for Mercedes-Benz and BMW procurement. |
| India PLI Scheme Localization Partnership | Tamil Nadu and Gujarat greenfield investments capture virgin battery housing demand from Tata Motors and Mahindra Electric. |
| Bio-Based Polyamide Co-Development | Castor oil-derived grades qualify for charge port housings under EU sustainability-mandated vehicle programs diverging from cost-optimized platforms. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, resin compounding plant managers, and flame-retardant formulation scientists and refined through secondary validation. Primary fieldwork encompassed technical specification interviews across Stuttgart-Wolfsburg, Yangtze River Delta, and Detroit Three engineering corridors. Secondary sources included MIIT GB standard filings, ECHA SVHC candidate list updates, SEC 10-K resin segment disclosures, and IHS Markit vehicle production databases. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Variance decomposition separated volume growth drivers from price-mix effects across grade tier, propulsion architecture, and regional production cluster dimensions. Segmentation modeling captured nylon, polycarbonate, polypropylene, and ABS formulation splits by under-hood, interior, exterior, and chassis application. CAGRs derived from fitted growth curves incorporating silicon carbide inverter adoption curves, cell-to-pack architecture penetration, and regulatory compliance timeline assumptions. Forecast inputs included battery chemistry evolution patterns and polymer processing advance trajectories.
The analysis sits within stated boundaries; outcomes outside sustained NEV platform rollout velocity or REACH substance restriction stability would require recalibration. Forecasts reflect documented assumptions regarding MIIT enforcement intensity and EU Green Deal implementation pace. Battery thermal runaway containment standard divergence between China's GB protocols and export-market thresholds represents specific revision risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
Mexico Solar E-Bike Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Solar Vehicle Market