
 Asia-Pacific Alfalfa Market | 2026-2036
Asia-Pacific Alfalfa Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Alfalfa Market Outlook
China's GB/T 20806 feed-grade alfalfa standard is unwinding market access for uncertified suppliers across the Asia-Pacific region. Al Dahra ACX Global Inc leverages integrated desert farming and port logistics to dominate Middle East-to-Asia hay corridors. Anderson Hay & Grain Co anchors its position through controlled-atmosphere storage and Pacific Rim shipping scale. Grupo Oses competes via specialized dehydration infrastructure in Spain with re-export focus on Japanese dairy cooperatives.
Alfalfa, Medicago sativa, is a perennial leguminous forage crop containing 15-22% crude protein and 30-35% fiber on a dry-matter basis, produced through sun-curing, dehydration, or pelleting for protein-dense animal nutrition. Dehydrated alfalfa commands premium positioning among Japanese dairy processors due to consistent nutrient retention and lower mycotoxin risk versus sun-cured alternatives. Pelleted alfalfa extends shelf stability for Southeast Asian importers facing tropical humidity challenges, while fresh alfalfa remains concentrated in domestic Chinese supply chains serving nearby livestock operations.
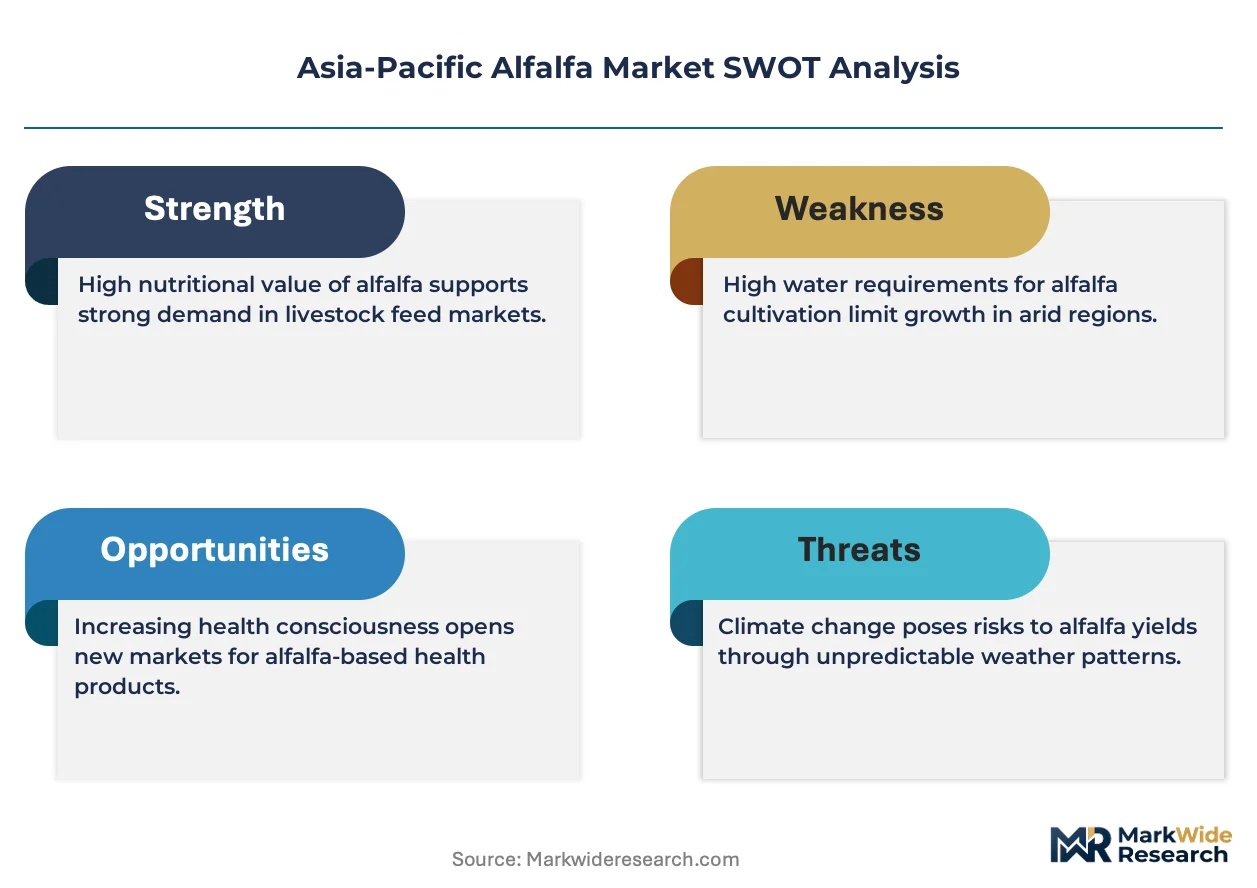
China's SAMR enforces feed safety labeling under GB standards, while Australia's Department of Agriculture mandates phytosanitary certification for hay exports to prevent weed seed contamination across trading partners. Japan's MAFF inspects imported forage for radioactive cesium residue, creating compliance friction for non-certified suppliers. Stakeholders must monitor evolving MEE environmental audits of Chinese dehydration facilities and assess backward integration into irrigated farming assets before certification requirements tighten further.
Market Dynamics
China's dual carbon goals are compressing feed-grade alfalfa supply chains toward certified low-emission producers, while Australian dehydration infrastructure attracts capital seeking phytosanitary-compliant export capacity. Dairy processor procurement teams now weight carbon intensity in supplier scorecards alongside crude protein specifications.
Growth Catalysts
- Japan's MAFF cesium residue protocols:Radioactive contamination screening creates procurement preference for Australian and Spanish supply corridors with verified chain-of-custody documentation, elevating premium-grade hay volumes.
- Dehydration technology diffusion:Controlled-atmosphere dehydration infrastructure is expanding across China's northern plains, enabling year-round production independent of sun-curing weather windows.
- Riverina irrigation concentration:Australian dairy feed demand clusters around the Murrumbidgee Irrigation Area, drawing capital toward vertically integrated farming-to-port logistics networks.
Market Restraints
- Phytosanitary certification friction:Australia's Department of Agriculture weed seed protocols impose inspection delays and rejection risk on sun-cured hay exports, compressing margins for small-scale operators.
- Substitute forage competition:Corn silage and soybean meal pricing volatility in Chinese domestic markets creates intermittent substitution pressure for protein supplementation in dairy rations.
- Input cost concentration:Diesel-powered irrigation and natural gas dehydration expose Australian and Chinese producers to fossil fuel price swings without renewable transition hedges in place.
Strategic Opportunities
- Southeast Asian humidity adaptation:Pelletized alfalfa formats address tropical storage degradation in Indonesian and Vietnamese import channels, opening new dairy and equine feed segments.
- MEE environmental audit acceleration:China's Ministry of Ecology and Environment facility inspections will consolidate dehydration capacity toward compliant operators with captive renewable energy supply.
- Carbon credit stacking:Irrigation efficiency and renewable-powered dehydration create verified emission reduction credentials tradable in China's national ETS for feed procurement premiums.
Industry Challenges
- Certification timeline compression:GB/T 20806 feed-grade standard implementation windows are shortening, forcing uncertified Chinese suppliers into costly facility retrofits or exit.
- Dehydration engineering scarcity:Specialized technicians for continuous-belt dehydration system maintenance are concentrated in Spain and France, constraining Chinese facility commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Alfalfa Market |
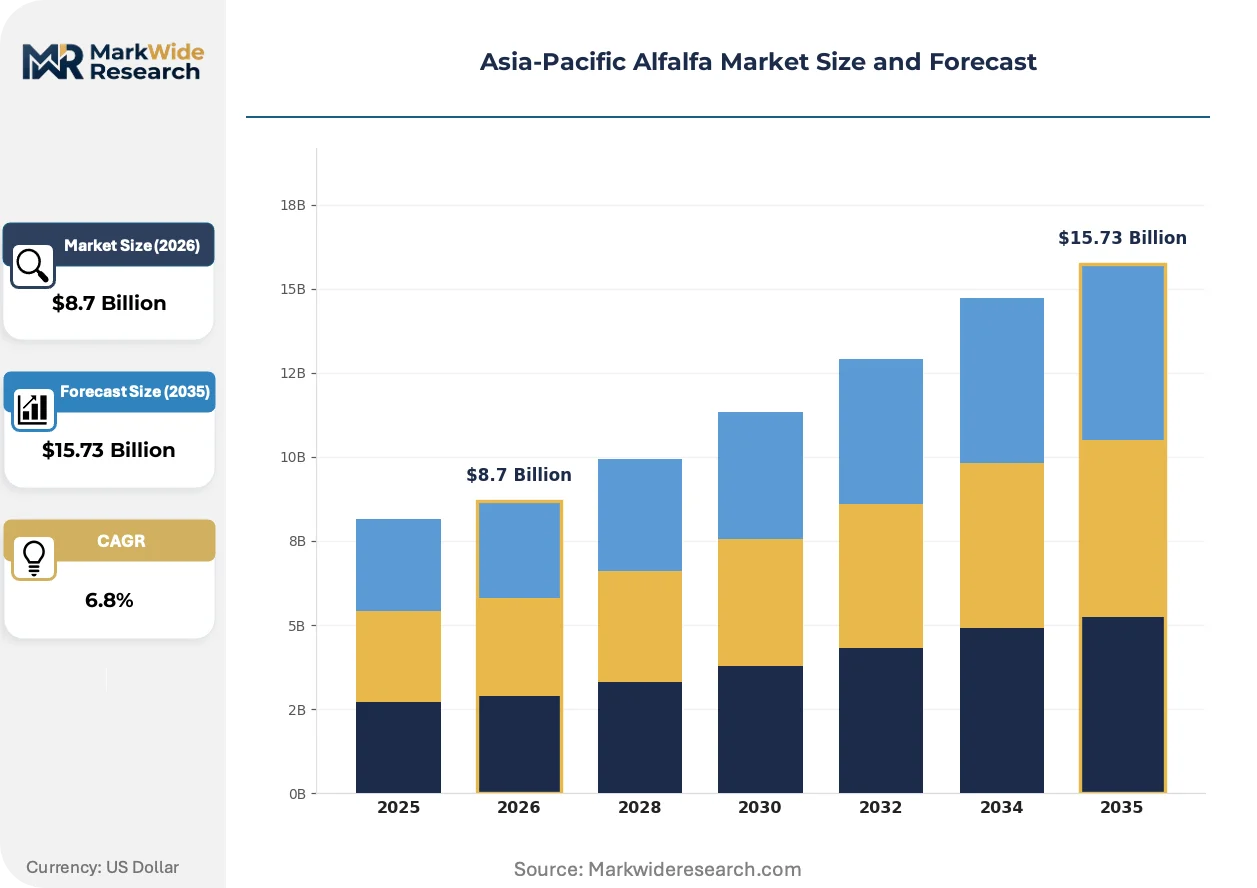
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Alfalfa, Cubed Alfalfa, Pelleted Alfalfa, Fresh Alfalfa End User: Dairy Farmers, Livestock Feed, Poultry Farms, Horse Owners Packaging Type: Bales, Sacks, Bags, Totes Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale Suppliers |
| Companies Covered | Alfalfa Monegros SL, Bailey Farms Inc, Al Dahra ACX Global Inc, Cubeit Hay Company, Border Valley Trading, Anderson Hay & Grain Co, The Accomazzo Company, Grupo Oses, S&S Agrisource Holding LLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Alfalfa Market Strategic Shifts
Processing technology and regulatory compliance frameworks are restructuring competitive advantage away from raw commodity supply toward certified, traceable, and carbon-accounted forage products. Procurement teams now embed sustainability metrics into supplier selection algorithms.
Controlled-atmosphere dehydration is displacing traditional sun-curing across premium supply tiers. Japanese dairy cooperatives now specify dehydrated alfalfa in procurement tenders for consistent protein retention and mycotoxin control. This technology compression is eliminating seasonal supply volatility premiums that previously rewarded sun-cured spot market arbitrage.
China's SAMR feed safety labeling enforcement under GB standards is tightening ingredient traceability requirements. Dehydration facilities must now document input sourcing and processing parameters for batch-level recall capability. Australian exporters to China are responding by integrating farm management software with export documentation systems.
Consolidated procurement by Chinese dairy conglomerates is compressing supplier counts and extending contract durations. Long-term offtake agreements with dehydration operators are replacing spot market purchases for core protein requirements. This concentration is most visible in Hebei and Inner Mongolia dairy clusters serving Beijing-Tianjin liquid milk demand.
Asia-Pacific Alfalfa Market Segmentation
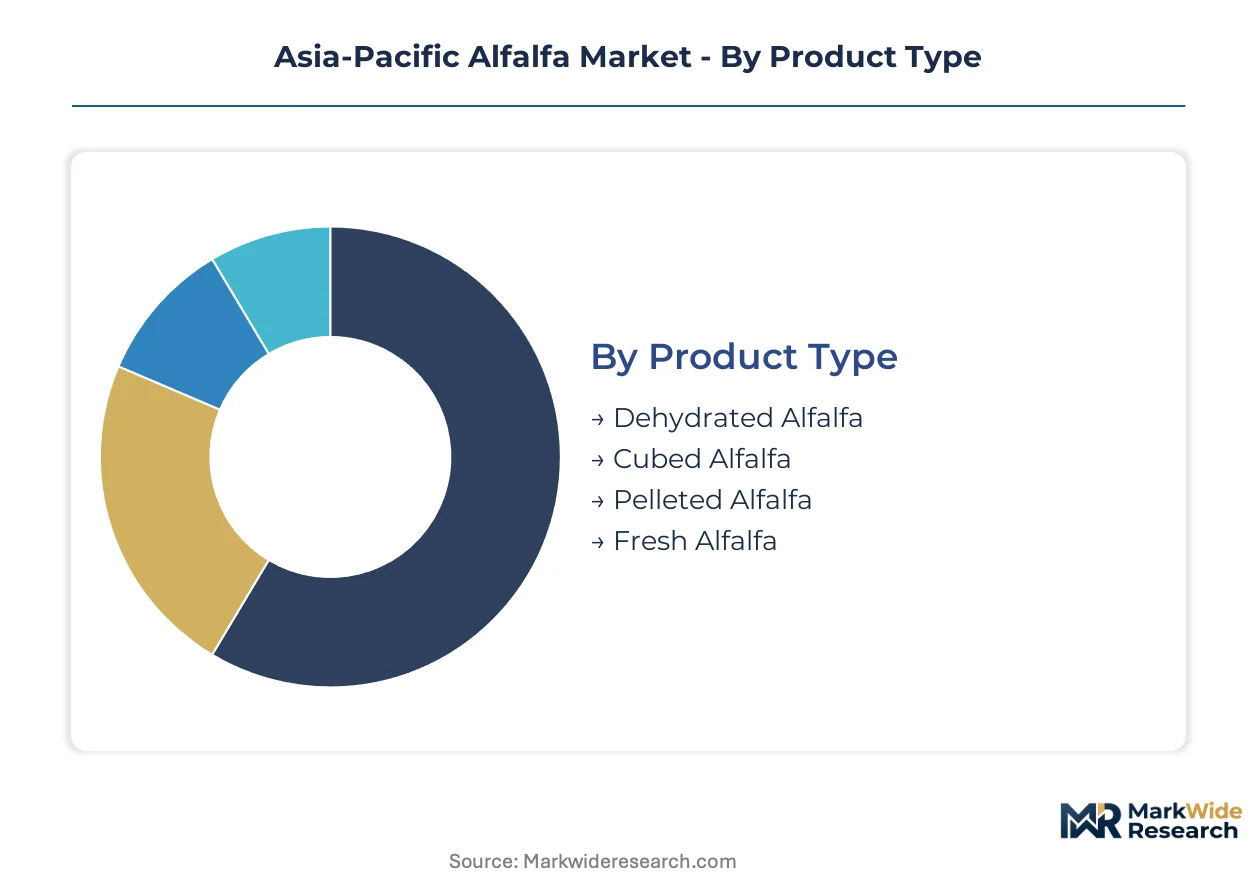
Segmentation in the Asia-Pacific alfalfa market reveals how regulatory compliance, climate adaptation, and supply chain configuration reshape procurement patterns across distinct product formats and customer profiles. Understanding these divisions exposes where margin concentrates and where certification barriers create competitive moats.
Product Type:
China's SAMR enforces divergent labeling and safety protocols across processing methods, elevating certified dehydration facilities while compressing uncertified sun-curing operations.
- Dehydrated Alfalfa:Continuous-belt dehydration at 800-900°C preserves 18-22% crude protein with minimal mycotoxin formation. Japanese dairy cooperatives in Hokkaido and Tohoku specify this grade for year-round ration consistency, paying premiums for verified chain-of-custody documentation meeting MAFF cesium screening protocols.
- Pelleted Alfalfa:Densified 6-8mm pellets reduce moisture absorption and extend shelf stability in tropical storage conditions. Indonesian and Vietnamese importers facing monsoon humidity challenges are shifting procurement toward pelleted formats for dairy and equine feed segments, displacing loose bale imports in coastal distribution hubs.
- Cubed Alfalfa:Compressed 25-50mm cubes suit automated feeding systems in Australian Riverina dairy operations with mechanized barn infrastructure.
- Fresh Alfalfa:Domestic Chinese supply chains serving Hebei and Inner Mongolia livestock operations within 48-hour harvest windows dominate this perishable category.
Established volume favors dehydrated formats; emerging adoption favors pelleted configurations for Southeast Asian climate adaptation.
End User:
Procurement sophistication varies sharply across livestock sectors, with dairy processors deploying carbon-intensity scorecards while poultry operators prioritize cost-per-protein-unit metrics.
- Dairy Farmers:Large-scale cooperatives in China's northern plains and Australia's Murrumbidgee Irrigation Area specify certified low-emission forage inputs to meet processor sustainability requirements and dual carbon compliance pressures. Long-term offtake agreements with dehydration operators are replacing spot purchases for core protein needs.
- Horse Owners:Japanese equine facilities and Australian thoroughbred stables demand premium-grade dehydrated products with guaranteed nutrient retention and contaminant-free certification, accepting price premiums for verified supply chains.
- Livestock Feed:Commercial feed mills blend alfalfa with corn silage and soybean meal, creating intermittent substitution pressure when grain protein prices fluctuate.
- Poultry Farms:Layer and broiler operations in Vietnam and Indonesia utilize alfalfa for carotenoid enrichment in egg yolks and skin pigmentation, prioritizing volume sourcing over certification tiers.
Margin concentration sits with dairy procurement; volume expansion is climbing fastest in equine feed channels.
Packaging Type:
Logistics configuration and climate exposure determine packaging selection, with export corridors favoring containerized formats and domestic Chinese distribution tolerating bulk handling.
- Bales:Large rectangular bales dominate Australian export shipments to Japan and China, optimized for containerized ocean freight and automated handling at destination ports.
- Sacks:25-50kg woven polypropylene sacks serve Southeast Asian distributors with fragmented last-mile delivery networks and smallholder dairy penetration.
- Bags:Retail-scale packaging targets Japanese horse owners and specialty feed retailers with direct-to-farm delivery requirements.
- Totes:One-tonne flexible intermediate bulk containers support industrial feed mill intake in China's coastal provinces with mechanized unloading infrastructure.
Export infrastructure favors bale formats; domestic fragmentation favors sack distribution.
Distribution Channel:
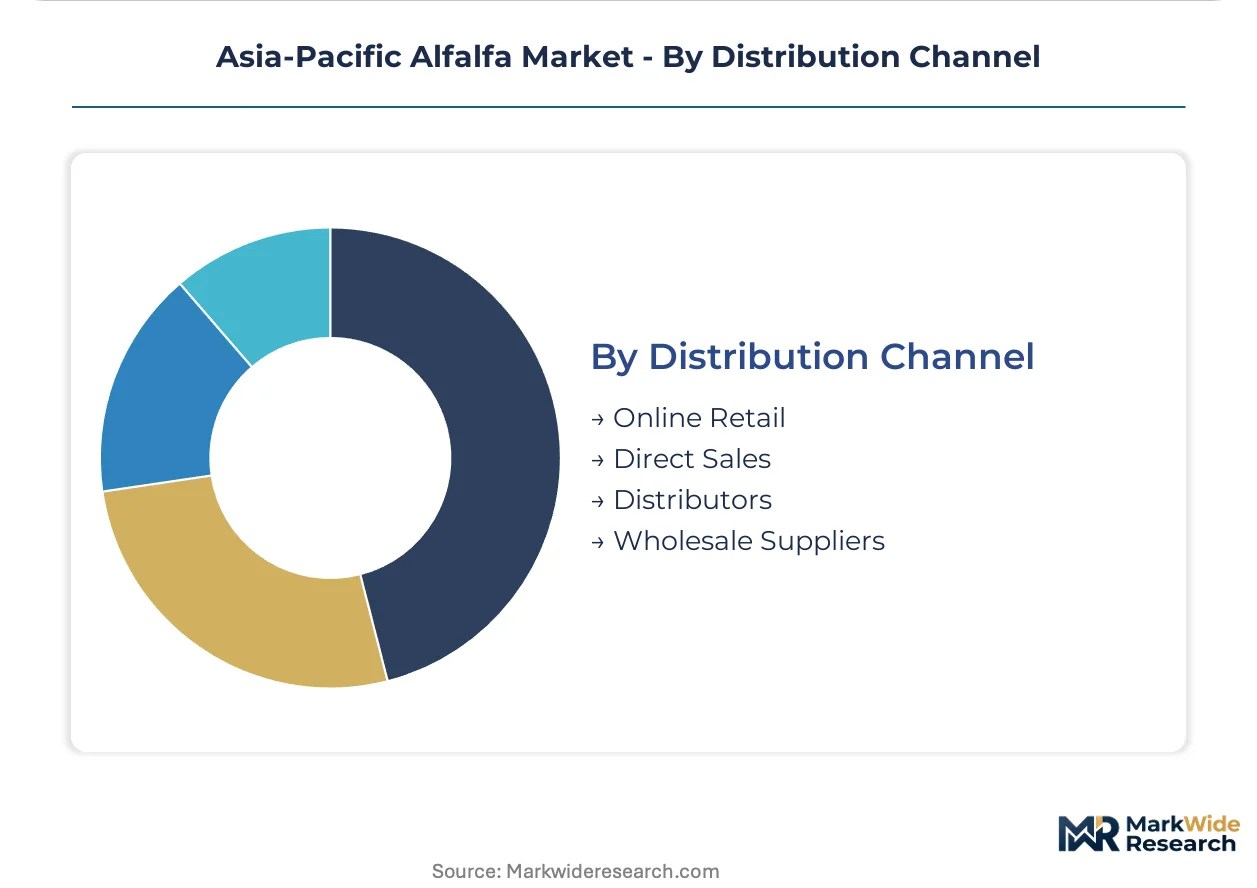
Channel selection reflects customer scale and certification complexity, with large dairy conglomerates bypassing intermediaries while smaller operators rely on distributor technical support.
- Direct Sales:Chinese dairy conglomerates in Hebei and Inner Mongolia negotiate long-term contracts directly with dehydration facilities, integrating farm management software with export documentation systems for SAMR traceability compliance.
- Distributors:Regional specialists in Vietnam and Indonesia provide technical advisory on ration formulation and handle phytosanitary clearance complexity for importers lacking in-house regulatory expertise.
- Wholesale Suppliers:Volume aggregators in Australian port cities consolidate Riverina production for Pacific Rim shipment, offering standardized grades with phytosanitary certification.
- Online Retail:Equestrian specialty platforms in Japan and urban China serve horse owners and small-scale livestock keepers with premium packaged products and documented origin verification.
Scale concentration favors direct channels; regulatory complexity favors distributor intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and Japan's MAFF cesium residue protocols are redirecting procurement flows across the Asia-Pacific region. Dairy processors now weight carbon intensity alongside crude protein specifications in supplier scorecards. This regulatory compression favors certified dehydration corridors with verified chain-of-custody documentation.
China
SAMR's GB/T 20806 feed-grade standard is unwinding market access for uncertified suppliers while MEE environmental audits consolidate dehydration capacity toward compliant operators. The Hebei and Inner Mongolia dairy clusters serving Beijing-Tianjin liquid milk demand are extending long-term offtake agreements with certified facilities. Continuous-belt dehydration infrastructure is expanding across China's northern plains for year-round production independent of weather windows.
Japan
Hokkaido and Tohoku dairy cooperatives specify dehydrated alfalfa for consistent protein retention and mycotoxin control, paying premiums for verified documentation meeting MAFF radioactive cesium screening protocols. METI procurement guidelines now embed sustainability metrics into supplier selection algorithms. Japanese equine facilities and thoroughbred stables demand contaminant-free certification with guaranteed nutrient retention.
Australia
The Department of Agriculture's phytosanitary certification mandates for weed seed prevention are compressing margins for small-scale sun-cured operators while attracting capital toward dehydration infrastructure. The Murrumbidgee Irrigation Area in the Riverina region anchors dairy feed demand concentration, drawing investment into vertically integrated farming-to-port logistics networks. Large rectangular bale exports dominate containerized ocean freight to Japan and China.
Vietnam
Monsoon humidity challenges are shifting importer procurement toward pelleted alfalfa formats that reduce moisture absorption and extend shelf stability in tropical storage conditions. Regional distributors provide technical advisory on ration formulation and handle phytosanitary clearance complexity for dairy and poultry feed segments. Layer and broiler operations utilize alfalfa for carotenoid enrichment in egg yolks and skin pigmentation.
Indonesia
Fragmented last-mile delivery networks and smallholder dairy penetration favor 25-50kg woven polypropylene sack distribution over bulk handling. Poultry farms prioritize volume sourcing for carotenoid enrichment applications over certification tiers. Equestrian specialty platforms are emerging to serve premium packaged product demand with documented origin verification for equine feed segments.
Asia-Pacific Alfalfa Market Competitive Environment
Player mix skews toward integrated desert farming operators and controlled-atmosphere dehydration specialists with Pacific Rim shipping scale. Market structure concentrates around three strategic archetypes: integrated farming-to-port operators leveraging captive irrigation assets, dehydration technology specialists with continuous-belt processing infrastructure, and regional wholesale aggregators consolidating production for standardized export grades. Dominant competitive moves include backward integration into irrigated farming assets and strategic partnerships with dairy conglomerates for long-term offtake agreements.
Among Middle East-to-Asia corridor operators, Al Dahra ACX Global Inc represents the integrated desert farming archetype with port logistics capabilities. Anderson Hay & Grain Co anchors the controlled-atmosphere storage and Pacific Rim shipping tier. Grupo Oses occupies a position within the European dehydration specialist segment with re-export focus on Japanese dairy cooperatives. These three exemplify how certification compliance and supply chain scale separate premium-tier positioning from commodity-grade competition.
| Leading Market Players |
|---|
| Alfalfa Monegros SL |
| Bailey Farms Inc |
| Al Dahra ACX Global Inc |
| Cubeit Hay Company |
| Border Valley Trading |
| Anderson Hay & Grain Co |
| The Accomazzo Company |
| Grupo Oses |
| S&S Agrisource Holding LLC |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Chinese dairy conglomerates and certified dehydration facilities lock in supply access while anchoring price visibility across volatile input cost cycles. These contracts insulate procurement teams from spot market swings in natural gas and diesel-powered irrigation, compressing margin risk for compliant operators.
Pricing Analysis
Certification level under GB/T 20806 standards creates the primary spread between premium dehydrated grades and uncertified sun-cured alternatives. Three-tier pricing structure across certified premium, transitional standard, and uncertified economy levels reflects divergent compliance investment and mycotoxin risk profiles. Cost compression in the economy tier is intensifying because MEE environmental audits are forcing facility retrofits or exit. Large-scale dairy cooperatives in Hebei and Inner Mongolia exhibit the lowest price sensitivity, while smallholder poultry operations in Vietnam prioritize volume sourcing over certification tiers.
Supply Chain Analysis
Phytosanitary certification chokepoints at Australian port terminals constrain export velocity for sun-cured hay while privileging dehydration infrastructure with pre-cleared documentation. Geographic supply concentrates in Australia's Riverina region, China's northern plains, and Spain's Ebro Valley dehydration corridor. Raw material flows draw from irrigated alfalfa acreage, natural gas or renewable-powered thermal processing, and containerized ocean freight capacity. Single-source vulnerability runs through specialized continuous-belt dehydration engineering concentrated in Spain and France. Distribution runs through vertically integrated farming-to-port networks for bulk dairy procurement, with regional distributors handling fragmented last-mile delivery in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific alfalfa demand sits in early-cycle expansion as Japanese dairy processors embed carbon intensity metrics into procurement scorecards, accelerating certified supply chain buildout ahead of regulatory maturation.
For Market Incumbents: Secure long-term offtake contract renewals with Hebei and Inner Mongolia dairy clusters before GB/T 20806 certification windows tighten further. Backward integration into captive irrigated farming assets in the Riverina or northern plains reduces input cost exposure to fossil fuel volatility. Defensive priority rests on dehydrator technician training programs to overcome engineering scarcity constraining Chinese facility commissioning. For New Entrants and Emerging Players: GB/T 20806 fast-track certification for existing dehydration facilities in China's northern plains opens immediate market access as uncertified competitors face forced exit. Southeast Asian pelleted alfalfa distribution through Vietnamese and Indonesian regional specialists represents the most penetrable white-space target, with technical advisory services on ration formulation as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Mid-scale dehydration operators with renewable energy supply agreements and SAMR-traceable farm management software integration represent the priority acquisition archetype. Long-term viability across the analysis window hinges on carbon credit stacking credentials tradable in China's national ETS. The signal to watch is MEE audit enforcement velocity accelerating facility consolidation toward compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Irrigated Farming Assets | Captive alfalfa supply in Riverina or northern plains reduces fossil fuel input cost exposure for dehydration operators. |
| GB/T 20806 Certification Investment | SAMR compliance unlocks access to Hebei-Inner Mongolia dairy conglomerate procurement channels. |
| Renewable-Powered Dehydration Transition | Carbon credit stacking in China's national ETS creates feed procurement premiums for verified emission reductions. |
| Pelletized Format Capacity Expansion | Tropical humidity adaptation opens Vietnamese and Indonesian dairy and equine feed segments. |
| Continuous-Belt Dehydration Technology Licensing | Spanish and French engineering partnerships accelerate Chinese facility commissioning timelines. |
Study Parameters
The analysis maps dehydrated, pelleted, cubed, and fresh alfalfa formats, each validated through dehydration facility operators, dairy procurement managers, export logistics coordinators, and phytosanitary certification officers. Primary fieldwork combined structured interviews with secondary triangulation against Australian Department of Agriculture export records, Chinese SAMR feed safety filings, Japanese MAFF import inspection data, and trade flow databases. Bottom-up volume modeling from facility capacity and offtake contracts cross-checked against top-down demand estimates from dairy herd projections and ration formulation standards.
Consistency checks validated volume and value outputs against independent benchmarks across the projection horizon. Segmentation dimensions modeled include product processing method, end-use livestock category, packaging configuration, and distribution channel structure. CAGRs derived from fitted growth curves incorporating dairy herd expansion rates, irrigation infrastructure investment pipelines, and regulatory compliance timeline assumptions. Industry-specific inputs encompassed natural gas price volatility scenarios and MEE environmental audit enforcement schedules.
Underlying assumptions cover sustained dual carbon policy enforcement in China, continued MAFF cesium screening protocols in Japan, and stable Riverina irrigation water allocations, with deviation risk concentrated in fossil fuel price spikes and certification timeline compression. Practitioners should keep alternative scenarios live as MEE audit acceleration and renewable energy transition subsidies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
Singapore Floriculture Market
Agriculture and Agri Products
Agrimony Market
Agriculture and Agri Products
Russia Compound Feed Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Coir Market