
 Organic Starter-Grower Chicken Feed Market | 2026-2036
Organic Starter-Grower Chicken Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Starter-Grower Chicken Feed Market Analytics
Midwestern U.S. grain cooperatives is restructuring organic soybean and corn procurement for starter-grower formulations. Cargill leverages its elevator network to secure non-GMO organic grain streams across Iowa and Illinois. Purina Animal Nutrition LLC anchors retail shelf presence through farm-store partnerships in the Corn Belt. Alltech Inc. competes on yeast-based additive integration that supports gut development in young birds without synthetic growth promoters.
Organic starter-grower chicken feed denotes nutritionally complete rations formulated for chicks from hatch through approximately sixteen weeks, typically containing 18-22% crude protein from certified organic soybean meal, corn, and supplemental amino acids to support skeletal and feather development ahead of layer or broiler transition. Pellet formulations dominate commercial channels because reduced feed waste and uniform nutrient intake align with certified organic audit requirements. Crumbles occupy the fastest-expanding position among backyard poultry owners seeking intermediate texture between mash and pellets. Protein-rich formulations command margin concentration as organic soybean meal premiums over conventional exceed baseline grain spreads.
The USDA National Organic Program governs ingredient sourcing and processing facility certification, while the EU Green Deal's Farm to Fork Strategy accelerates antibiotic-free production targets that redirect conventional growers toward organic starter protocols. FDA oversight of veterinary feed directives limits medicated options in organic channels, tightening the product boundary. Stakeholders must monitor organic grain supply elasticity and certification backlogs as conversion timelines lag flock expansion commitments.
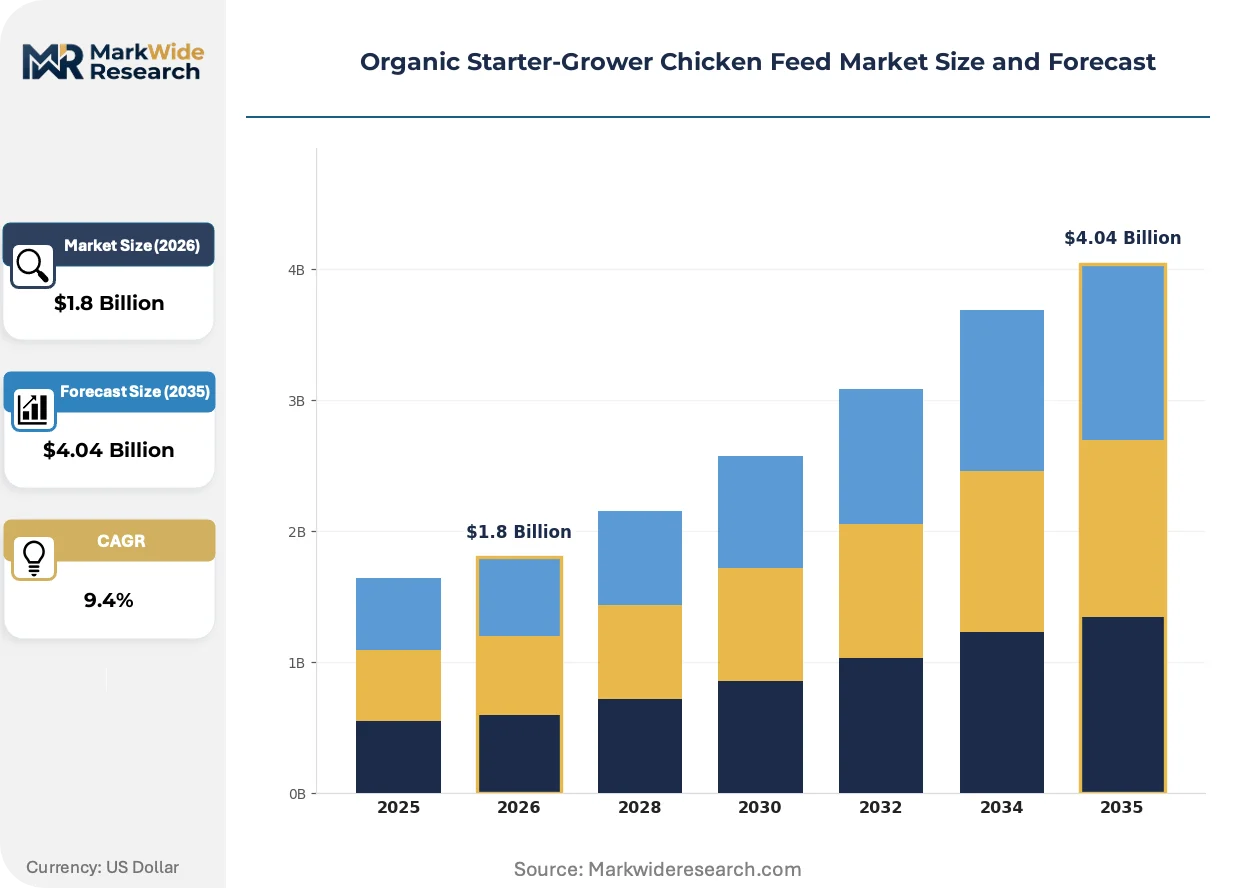
Market Dynamics
Antibiotic-free mandates from the EU Green Deal and USDA National Organic Program are compressing conventional feed pathways and redirecting flock expansion capital toward certified organic starter-grower formulations, tightening grain procurement competition across major poultry regions.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Binding antibiotic reduction targets force conventional growers in Germany and France to convert starter protocols to organic certification, expanding addressable demand.
- Pellet formulation technology:Reduced feed waste and uniform nutrient intake align with certified organic audit requirements, accelerating commercial channel preference for structured rations.
- Backyard poultry clusters:Owner-operators in Oregon and Washington state concentrate demand where direct-to-farm distribution networks and organic certification density overlap.
Market Restraints
- Organic soybean meal premiums:Price spreads over conventional inputs exceed baseline grain differentials, compressing margin structures for formulators without captive supply.
- Certification backlogs:USDA National Organic Program processing delays lag flock expansion timelines, stranding capital in pending conversions.
- Grain supply elasticity constraints:Iowa and Illinois organic corn procurement faces conversion lag from conventional acreage, tightening input security.
Strategic Opportunities
- Crumbles texture segment:Intermediate formulations between mash and pellets capture backyard poultry owners seeking customizable feeding experiences without full pellet infrastructure.
- Yeast-based additive integration:Gut development support without synthetic growth promoters opens differentiation for specialty nutrition providers targeting young bird protocols.
- Farm-store channel expansion:Direct retail partnerships in the Corn Belt bypass distributor markups and build brand loyalty among volume purchasers.
Industry Challenges
- Organic facility certification timelines:Processing plant audits and ingredient traceability documentation create operational bottlenecks that delay product launch schedules.
- Veterinary feed directive compliance:FDA restrictions on medicated options in organic channels eliminate fallback formulations during disease pressure events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Starter-Grower Chicken Feed Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Crumbles, Mash, Medicated Formulation: Grain-Based, Protein-Rich, Vitamin-Enriched, Herbal Distribution Channel: Retail Stores, Online Stores, Farms, Wholesalers Customer Segment: Commercial Farmers, Backyard Poultry Owners, Organic Farms, Cooperative Groups |
| Companies Covered | Purina Animal Nutrition LLC, Cargill, Alltech Inc., Associated British Foods plc, Koninklijke DSM N.V., Nature's Best Organic Feeds, Kalmbach Feeds, Archer Daniels Midland, ForFarmers Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Starter-Grower Chicken Feed Market Evolving Landscape
Formulation science and certification protocols are reshaping how starter-grower rations deliver early-stage bird development, with texture engineering and additive biology displacing conventional growth promotion methods.
Precision pellet density engineering is consolidating control over feed conversion ratios in commercial operations. Large-scale layer and broiler transition facilities adopt uniform nutrient geometry to minimize selective feeding and audit documentation burden. This consolidation is compressing demand for loose mash formats in certified organic channels.
REACH and EU Green Deal chemical safety expansions are tightening residue screening for imported organic soybean meal. Formulators sourcing from South American suppliers face additional testing protocols that extend procurement cycles. German and Dutch poultry operations are responding by regionalizing grain streams through Baltic organic certification networks.
Direct-to-farm subscription models are fragmenting traditional distributor control over backyard poultry supply. Owner-operators in the Pacific Northwest and New England bypass retail markup through cooperative purchasing platforms that aggregate demand for scheduled delivery. This channel shift is most visible among certified organic hobby flocks seeking traceability documentation for local egg marketing.
Organic Starter-Grower Chicken Feed Market Segmentation
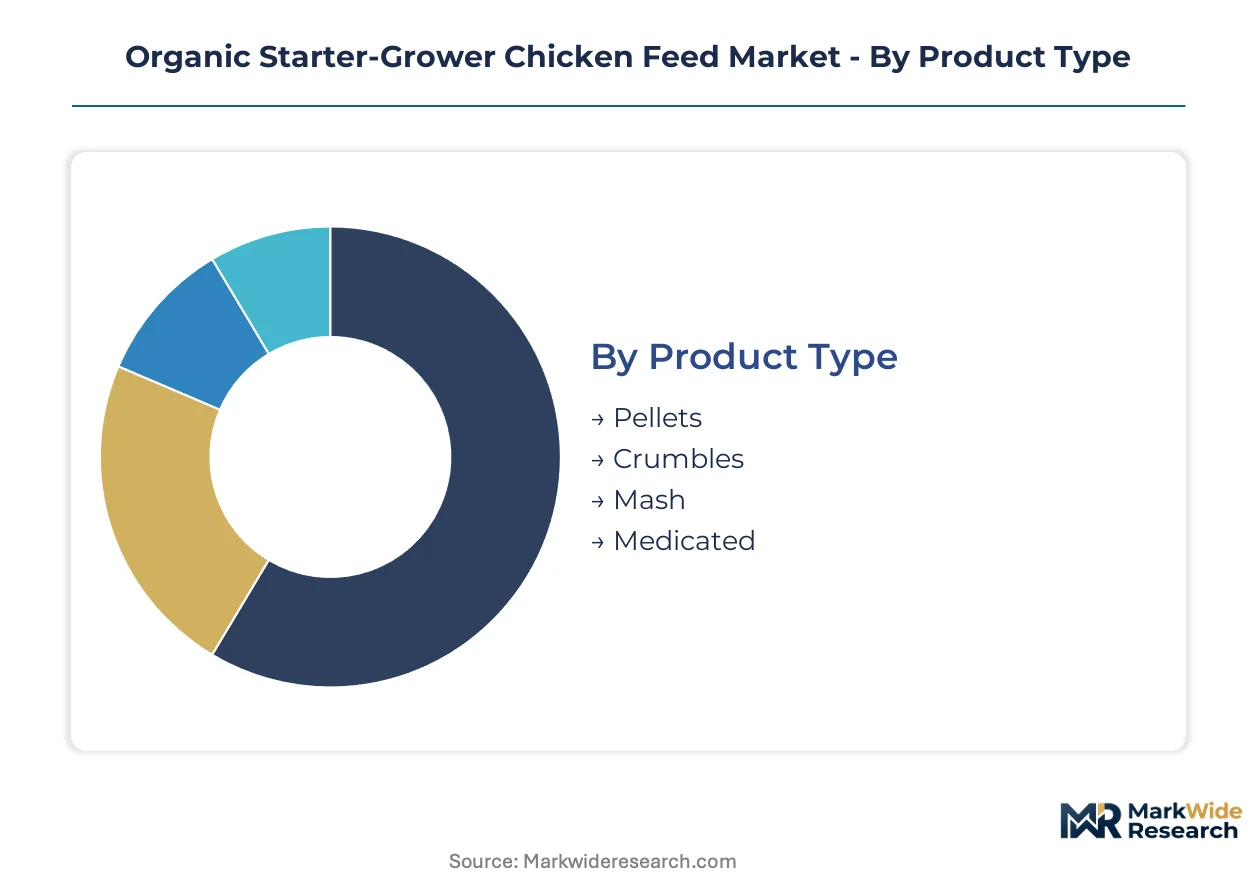
Texture engineering and certification compliance create distinct performance tiers in organic starter-grower formulations. Channel fragmentation between commercial-scale procurement and backyard hobbyist purchasing drives divergent packaging and distribution requirements across the market.
Product Type:
Pellet formulations dominate commercial volume while crumbles capture premium positioning among specialty buyers.
- Pellets:Compressed cylindrical rations with uniform nutrient density reduce selective feeding and satisfy USDA National Organic Program audit documentation requirements. Layer and broiler transition facilities in Iowa and Illinois standardize on pellet infrastructure to minimize feed conversion ratio variance.
- Crumbles:Intermediate particle size between mash and pellets delivers customizable feeding experiences without full pellet system investment. Backyard poultry clusters in Oregon and Washington state drive demand where direct-to-farm networks and organic certification density overlap.
- Mash:Loose-ground formulation retains lowest processing overhead and suits small-batch organic operations with on-farm mixing capacity.
- Medicated:FDA veterinary feed directive restrictions severely constrain this segment in certified organic channels, limiting deployment to transitional flocks not yet achieving full organic status.
Mature deployment sits with Pellets. Newer deployment is concentrated in Crumbles.
Formulation:
Protein sourcing economics separate margin performance from baseline grain-based commodity positioning.
- Protein-Rich:Formulations with 20-22% crude protein from certified organic soybean meal command the widest premiums over conventional inputs. German and Dutch poultry operations regionalize procurement through Baltic organic certification networks to bypass REACH screening delays on South American imports.
- Grain-Based:Corn and organic wheat foundations with 18% protein targets serve cost-sensitive commercial operations. Cargill leverages Iowa and Illinois elevator networks to secure non-GMO organic grain streams for these formulations.
- Vitamin-Enriched:Synthetic vitamin restrictions under EU Green Deal protocols limit premix options, requiring natural-source alternatives that extend formulation cycles.
- Herbal:Botanical additives targeting gut health occupy niche positioning among premium backyard poultry owners seeking traceability documentation for local egg marketing.
Volume concentrates in Grain-Based formulations. Steepest expansion trajectory belongs to Protein-Rich as antibiotic-free mandates tighten conventional pathways.
Distribution Channel:
Direct access models are fragmenting traditional distributor control over backyard supply while commercial channels consolidate.
- Farms:Direct-to-farm distribution networks in the Pacific Northwest and Corn Belt bypass retail markup and build volume loyalty among certified organic operations. Purina Animal Nutrition LLC anchors presence through farm-store partnerships in Iowa and Illinois.
- Retail Stores:Farm-store and agricultural supply chains maintain shelf presence for emergency replenishment and novice poultry owners without cooperative purchasing access.
- Online Stores:Subscription platforms aggregate backyard poultry demand for scheduled delivery, fragmenting traditional distributor control most visibly among certified organic hobby flocks.
- Wholesalers:Bulk procurement intermediaries serve commercial layer and broiler transition facilities with pallet-scale logistics and extended payment terms.
Established procurement runs through Farms. Channel shift momentum concentrates in Online Stores.
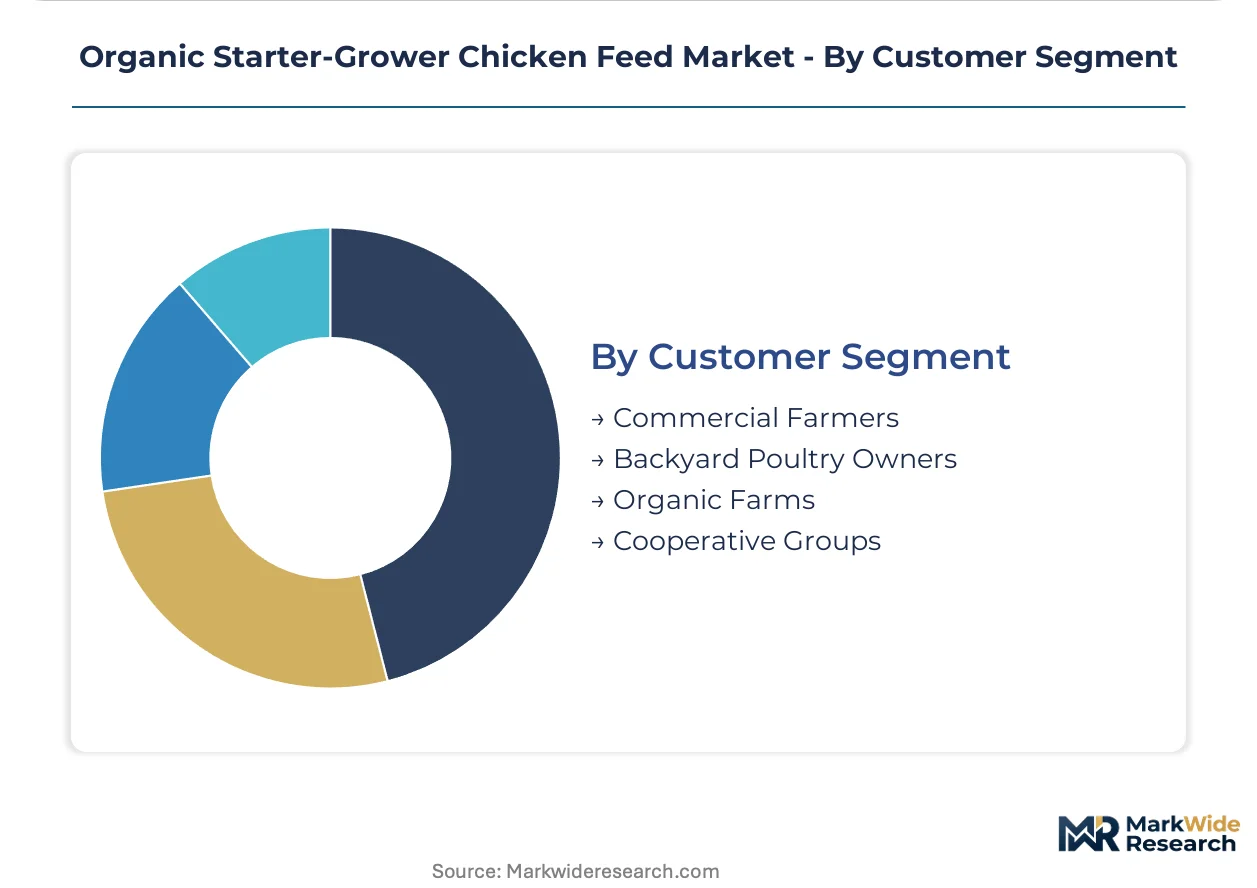
Customer Segment:
Scale economics and certification sophistication create divergent service requirements across buyer types.
- Commercial Farmers:Large-scale layer and broiler transition facilities demand pellet uniformity, audit documentation, and feed conversion ratio optimization. Precision pellet density engineering consolidates their procurement around structured rations.
- Backyard Poultry Owners:Owner-operators in Oregon, Washington, and New England prioritize traceability documentation for local egg marketing and seek intermediate textures without infrastructure investment. Cooperative purchasing platforms aggregate their demand for scheduled delivery.
- Organic Farms:Fully certified operations face USDA National Organic Program processing delays that lag flock expansion timelines, stranding capital in pending conversions.
- Cooperative Groups:Purchasing collectives concentrate demand for volume discounts and shared logistics, particularly visible among German organic certification networks.
Revenue concentration rests with Commercial Farmers. Fastest share gains are emerging among Backyard Poultry Owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iowa and Illinois organic corn procurement anchors North American feedstock security for starter-grower formulations, while Baltic grain networks and Pacific Northwest distribution clusters reshape procurement geography across major poultry regions.
United States
Midwestern grain cooperatives restructure organic soybean and corn procurement for starter-grower formulations. The USDA National Organic Program governs ingredient sourcing and processing facility certification. Iowa and Illinois elevator networks concentrate non-GMO organic grain streams for layer and broiler transition facilities.
Germany
Binding antibiotic reduction targets under the EU Green Deal Farm to Fork Strategy force conventional growers to convert starter protocols to organic certification. ECHA and EFSA chemical safety expansions tighten residue screening for imported organic soybean meal. Dutch and German poultry operations regionalize grain streams through Baltic organic certification networks.
France
Conventional flock expansion capital redirects toward certified organic starter-grower formulations under EU antibiotic-free mandates. REACH regulations extend procurement cycles for South American organic soybean meal imports. Regional poultry clusters in Brittany and Pays de la Loire concentrate demand where organic certification density overlaps with distribution infrastructure.
United Kingdom
Backyard poultry owner demand concentrates in England where direct-to-farm distribution networks and organic certification density overlap. EU Green Deal protocols continue influencing domestic organic standards post-Brexit transition. Farm-store partnerships in East Anglia and the Midlands build volume loyalty among certified organic operations.
Canada
Health Canada and PMRA oversight aligns veterinary feed directive restrictions with organic channel limitations on medicated options. Prairie organic grain production in Saskatchewan and Alberta supplies regional formulators. British Columbia backyard poultry clusters drive demand for intermediate crumble textures through cooperative purchasing platforms.
Organic Starter-Grower Chicken Feed Market Competitive Landscape
Global majors compete with regional champions across feedstock procurement and distribution channel control. The vendor base stratifies between integrated grain handlers with captive organic supply, specialty nutrition providers with additive differentiation, and regional formulators with farm-store proximity. Three archetypes dominate: elevator-network integrators securing non-GMO organic grain streams, yeast-based additive specialists targeting gut development protocols, and direct-to-farm distributors bypassing retail markup. Competitive moves concentrate on backward integration into organic grain procurement and farm-store channel expansion to build volume loyalty.
Within the integrated grain-handler archetype, Cargill and Archer Daniels Midland occupy positions anchored by Midwestern elevator infrastructure. Among specialty nutrition providers, Alltech Inc. exemplifies the yeast-based additive differentiation vector. Purina Animal Nutrition LLC represents the farm-store channel expansion model through Corn Belt retail partnerships. These three companies illustrate how procurement control, biological differentiation, and distribution proximity define competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Purina Animal Nutrition LLC |
| Cargill |
| Alltech Inc. |
| Associated British Foods plc |
| Koninklijke DSM N.V. |
| Nature's Best Organic Feeds |
| Kalmbach Feeds |
| Archer Daniels Midland |
| ForFarmers Group |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap formulators across the Corn Belt and Pacific Northwest maintain pricing discipline through captive organic grain contracting, insulating their starter-grower rations from the spot-market volatility that squeezes margin structures for distributor-dependent competitors.
Pricing Analysis
Certification documentation bundling separates premium organic starter-grower formulations from unbundled commodity alternatives, with USDA National Organic Program audit trails and veterinary feed directive compliance packages commanding wider spreads. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein concentration and additive sophistication, with protein-rich formulations bearing organic soybean meal premiums that exceed baseline grain differentials. Cost compression in grain-based tiers is intensifying because Iowa and Illinois organic corn procurement faces conversion lag from conventional acreage. Backyard poultry owners in Oregon and Washington exhibit highest price sensitivity, while commercial layer facilities prioritize feed conversion ratio optimization over unit cost.
Supply Chain Analysis
Regional distribution centers in Des Moines and Portland anchor hub-and-spoke patterns that consolidate organic grain flows from Iowa, Illinois, and Saskatchewan into formulator networks. The supply chain draws from certified organic soybean meal originating in Baltic certification networks, South American imports facing REACH screening delays, and Prairie organic wheat production in Alberta. Single-source vulnerability concentrates in organic facility certification timelines, where USDA National Organic Program processing delays lag flock expansion commitments. Distribution runs through farm-store partnerships in the Corn Belt and direct-to-farm subscription platforms fragmenting traditional wholesaler control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic-free mandates are displacing conventional growth promotion methods with yeast-based additive protocols and precision pellet engineering, forcing capital reallocation toward biological differentiation and texture innovation.
For Market Incumbents: Acquire captive organic grain elevator capacity in Iowa and Illinois to secure non-GMO corn and soybean streams against procurement competition from Cargill and Archer Daniels Midland. Invest in crumble formulation infrastructure to capture backyard poultry demand in the Pacific Northwest before regional specialists consolidate channel control. For New Entrants and Emerging Players: Begin with direct-to-farm subscription platforms targeting New England hobby flocks seeking traceability documentation for local egg marketing, bypassing Purina Animal Nutrition LLC's farm-store shelf dominance. Partner with Baltic organic certification networks to circumvent REACH screening delays on South American soybean meal imports. For Investors and Strategic Acquirers: Distressed-cycle entries favor yeast-based additive specialists with FDA-compliant gut development protocols in Germany and the Netherlands, where EU Green Deal antibiotic reduction targets redirect conventional grower capital toward organic conversion. Monitor organic facility certification backlog resolution as the inflection signal for stranded capital release.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Grain Procurement | Cargill's elevator network secures non-GMO corn streams across Iowa and Illinois against supply tightening. |
| Crumbles Texture Segment Development | Intermediate formulations capture Oregon and Washington backyard poultry owners without pellet infrastructure investment. |
| Yeast-Based Additive Integration | Alltech Inc. differentiates on gut development protocols that satisfy FDA veterinary feed directive restrictions. |
| Farm-Store Channel Expansion | Purina Animal Nutrition LLC builds volume loyalty among Corn Belt commercial farmers through retail partnerships. |
| Baltic Certification Network Regionalization | German and Dutch operations bypass REACH screening delays on South American organic soybean meal imports. |
Research Methodology
Independent corroboration across feed formulator procurement directors, USDA National Organic Program certification officers, and agricultural cooperative grain managers underwrites the qualitative findings in this study. Primary interviews with veterinary feed directive compliance specialists, farm-store category buyers, and backyard poultry cooperative organizers combined with secondary validation from FDA veterinary guidance documents, USDA organic integrity database records, and EU Green Deal Farm to Fork Strategy implementation reports. Bottom-up demand aggregation across texture segments and formulation tiers triangulated against top-down grain supply elasticity assessments.
Comparable historical reference periods spanning pre- and post-antibiotic-free mandate implementation anchored the forecast window across the projection horizon. Segmentation modeling incorporated product type, protein concentration tier, distribution channel, and customer scale economics, with CAGRs derived from organic grain supply conversion trajectories and flock expansion commitment pipelines. Industry-specific inputs included organic soybean meal premium spreads over conventional and certification backlog resolution timelines.
Underlying measurement precision varies by segment; pellet formulations carry tighter precision than medicated segments given FDA veterinary feed directive restrictions. Forecasts reflect documented assumptions on organic acreage conversion rates and EU Green Deal enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market
Agriculture and Agri Products
Sugar Beet Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
South Africa Agriculture Market