
 Herring Market | 2026-2036
Herring Market Size, Share, and Industry Trends Forecast 2026-2036
Herring Market Analysis
Branded value-added herring products is reshaping competitive positioning across the supply chain. Cornelis Vrolijk leverages its integrated North Sea fleet and processing assets to control raw material flows from catch to retail. Domstein AS anchors its position through specialized cold-chain distribution across Scandinavian retail channels. Iceland Seafood International differentiates via certified sustainable sourcing programs that command premium placement in European supermarkets.
Herring (Clupea harengus) denotes a silvery, schooling pelagic fish with oil content ranging from 10% to 20% by weight, typically processed through brining, smoking, canning, or flash-freezing for human consumption and industrial reduction. Frozen herring occupies the largest volume share as food manufacturers and Eastern European processors prioritize bulk procurement of whole fish for filleting and smoking operations. Canned herring represents the fastest-expanding value segment, driven by shelf-stable convenience demand in German and Polish retail channels where tin formats dominate pantry stocking patterns. Fresh herring retains niche premium positioning in Dutch and Belgian fish markets where same-day catch commands price premiums from restaurant buyers.
The Common Fisheries Policy quota system administered by the European Commission constrains total allowable catches in North Sea and Baltic stocks, directly limiting raw material availability for processors. Norway's Directorate of Fisheries and the Marine Stewardship Council certification framework shape market access rules for export-oriented producers seeking retail placement in EU and UK channels. Stakeholders must monitor quota negotiations between coastal states and traceability mandates from the EU Illegal, Unreported and Unregulated Fishing Regulation to secure long-term supply contracts and retail listings.
Market Dynamics
The Common Fisheries Policy quota system compresses raw material availability for processors, forcing supply chain reconfiguration around certified sustainable sourcing and alternative catch zones outside EU-controlled waters.
Growth Catalysts
- MSC Certification Mandates:Retailers in Germany and Poland now require Marine Stewardship Council labeling for shelf placement, pulling processors toward audited supply chains.
- Convenience Demand in Eastern Europe:Canned herring formats gain traction in Polish and Czech retail channels as pantry-stocking patterns shift toward shelf-stable proteins.
- Smoked Product Premiumization:Traditional smokehouse techniques command price premiums in Dutch and Belgian foodservice markets where heritage preparation methods differentiate offerings.
Market Restraints
- Quota-Driven Supply Compression:The European Commission's total allowable catch limits for North Sea herring stocks directly constrain processor throughput during peak seasons.
- Fuel Cost Volatility:Pelagic trawler operations face margin pressure from diesel price swings that constitute 25-35% of vessel operating expenditures.
- Single-Species Dependency:Baltic Sea stock fluctuations create raw material concentration risk for processors lacking diversified North Atlantic sourcing.
Strategic Opportunities
- UK Channel Expansion:Post-Brexit regulatory divergence creates white space for Norwegian and Icelandic processors to secure direct retail listings independent of EU quota pooling.
- Functional Food Ingredients:Herring oil extraction for omega-3 supplements opens pharmaceutical and nutraceutical offtake channels beyond traditional food applications.
- Blockchain Traceability Integration:EU Illegal, Unreported and Unregulated Fishing Regulation mandates create first-mover advantage for processors deploying end-to-end catch documentation systems.
Industry Challenges
- Cold-Chain Infrastructure Capex:Flash-freezing and controlled-atmosphere storage requirements demand capital deployment that mid-scale processors struggle to finance.
- Auditor Capacity Bottlenecks:MSC and ASC certification backlogs delay market access timelines for processors seeking premium retail placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herring Market |
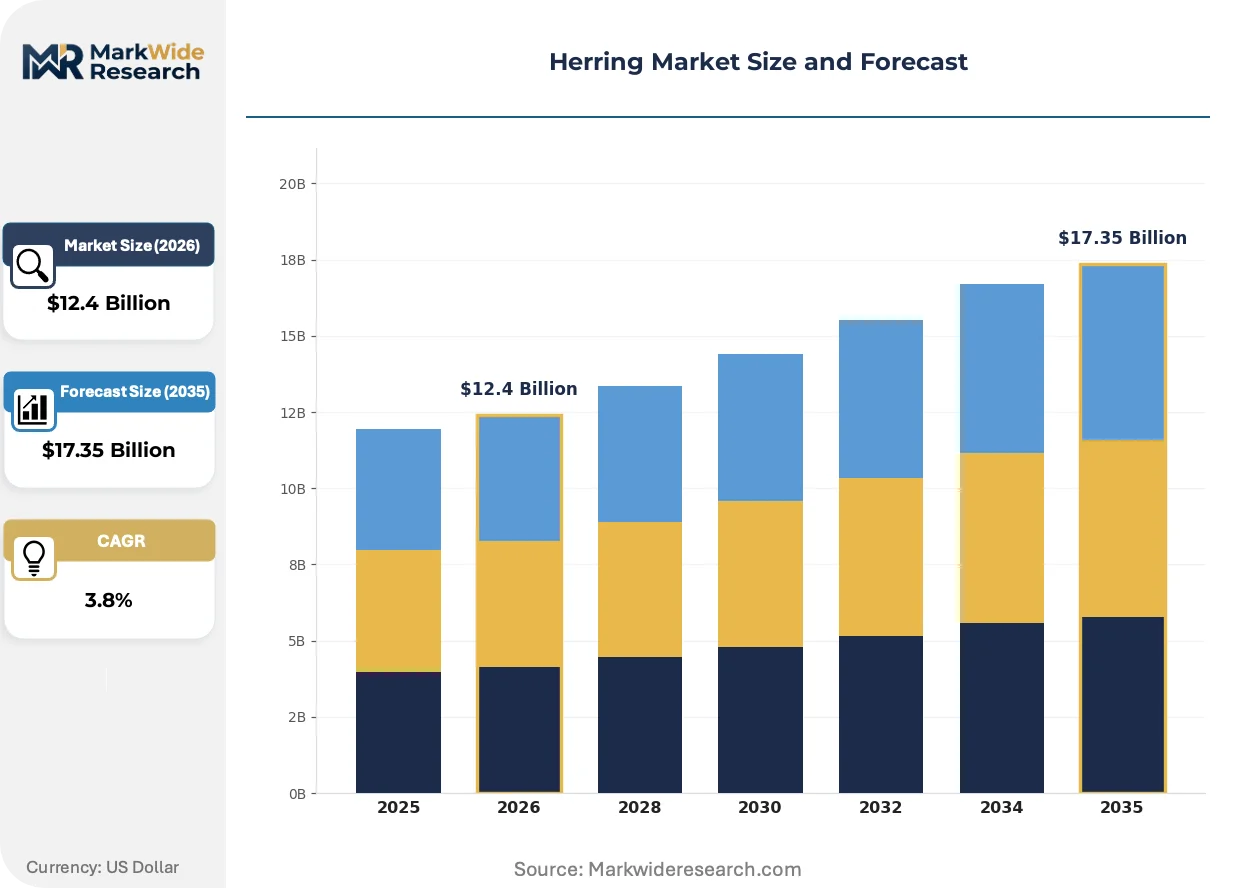
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $17.35 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Herring, Frozen Herring, Canned Herring, Smoked Herring End User: Supermarkets, Restaurants, Fish Markets, Food Processing Packaging Type: Bags, Boxes, Trays, Tins Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Cornelis Vrolijk, Domstein AS, AS KURSA, Haringhandel A. Hoek BV, Esser Haringgroothandel en Rokerij BV, Barry Group Inc., Denholm Seafoods Ltd., Iceland Seafood International, Channel Fish Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herring Market Emerging Trajectories
Processing technology and traceability systems are compressing traditional supply chain tiers, while regulatory mandates and shifting retail procurement models reconfigure competitive requirements across the value chain.
Automated filleting and pin-boning systems are collapsing labor intensity in processing facilities. Norwegian and Dutch mid-scale processors deploy vision-guided robotics that reduce manual handling requirements by 60-70% for standard cuts. This technology compression enables round-the-clock production cycles that were previously constrained by shift labor availability.
EU Green Deal sustainability reporting obligations under the Corporate Sustainability Reporting Directive extend to seafood supply chains. Large retail buyers now demand Scope 3 emissions documentation from herring suppliers, forcing processors to invest in fuel monitoring and vessel efficiency upgrades. German supermarket chains are the most aggressive in enforcing these disclosure timelines.
Consolidated retail procurement is displacing traditional auction-based fish buying. Dutch and Belgian supermarket groups now contract directly with vessel operators for specified catch volumes, bypassing wholesale markets. This channel compression concentrates volume with vertically integrated suppliers capable of delivering consistent quality grades across extended contract periods.
Herring Market Segmentation
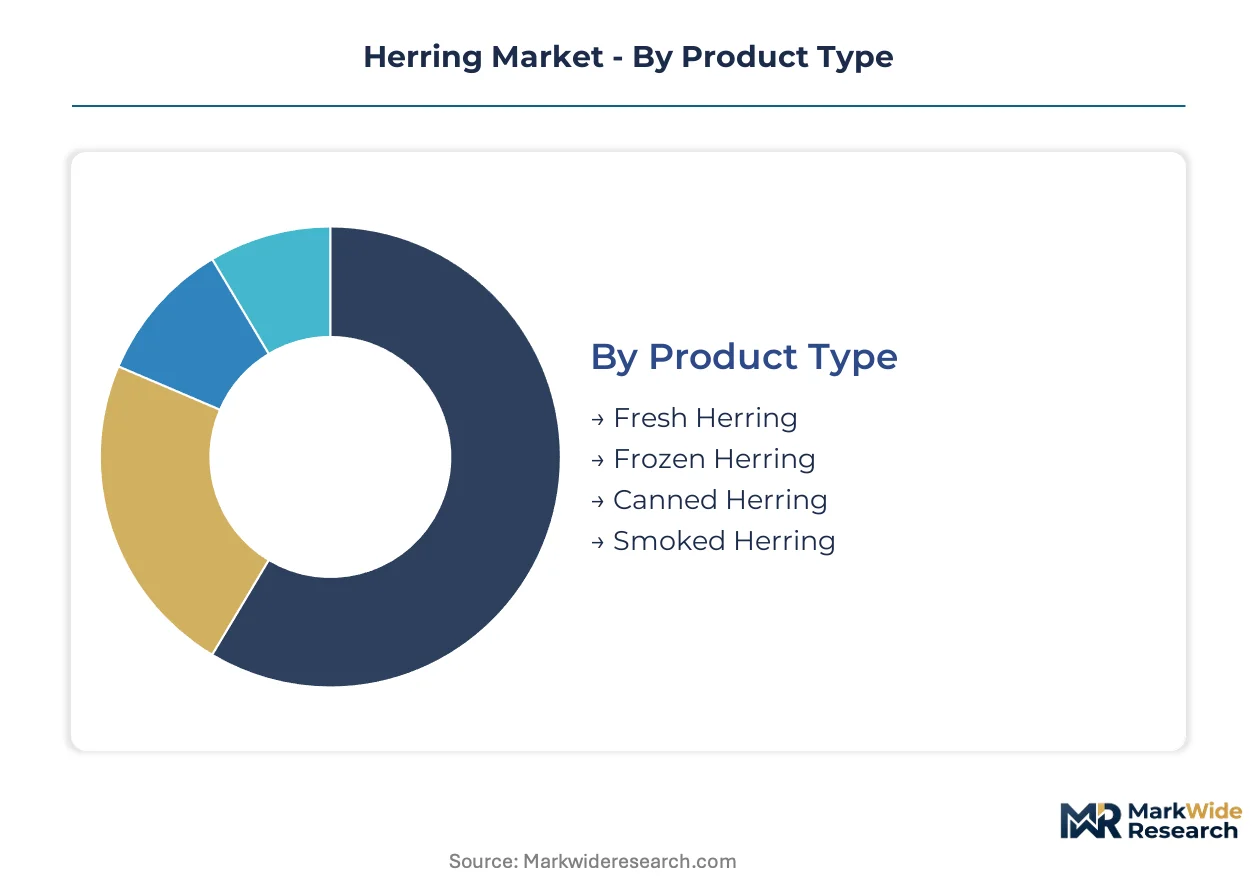
Segmentation in the herring trade maps directly to shelf-life economics and procurement cadence. Product format determines inventory velocity, while channel structure dictates margin capture and working capital intensity across the value chain.
Product Type:
Frozen herring turns inventory slowest at 4-6 months, while fresh formats clear in 48-72 hours, creating the widest cycle-time spread across the category.
- Fresh Herring:Whole fish sold on ice with 24-48 hour shelf life demands same-day logistics from North Sea ports to Dutch and Belgian auction floors. Rotterdam fish merchants command price premiums for catch landed within 12 hours, though spoilage risk limits geographic reach to coastal markets.
- Canned Herring:Shelf-stable tin formats with 36-month durability anchor pantry-stocking patterns in German and Polish retail channels. Brine and tomato sauce variants dominate mass-market placement, while smoked oil infusions secure premium positioning.
- Frozen Herring:Flash-frozen whole fish and fillets at -18°C enable 12-18 month storage for Eastern European processors running filleting and smoking operations.
- Smoked Herring:Traditional kiln-cured products with 14-21 day refrigerated shelf life serve Dutch and Belgian foodservice accounts seeking heritage preparation methods.
Frozen herring anchors the volume base while canned herring gains share at the steepest rate.
End User:
Cost tier separation runs deepest here, with food processing commanding bulk discounts and fish markets absorbing the highest per-unit procurement costs.
- Food Processing:Baltic and Polish smokehouses purchase frozen whole herring in 20-tonne lots for filleting, brining, and value-added product manufacturing.
- Supermarkets:German and Dutch retail chains source MSC-certified frozen fillets and canned formats under private label programs with annual contract volumes.
- Restaurants:Belgian and Dutch foodservice buyers procure fresh and smoked herring through specialized seafood wholesalers serving heritage cuisine segments.
- Fish Markets:Traditional auction-based buyers in Scheveningen and Ostend handle small-lot fresh catch for local consumer and independent retail accounts.
Food processing absorbs the highest tonnage while supermarkets drive the steepest specification tightening on sustainability documentation.
Packaging Type:
Volume scale concentrates in industrial formats, while retail-ready packaging commands margin premiums through shelf differentiation.
- Tins:Steel cans with hermetic sealing dominate canned herring formats, enabling ambient distribution through Polish and Czech retail networks without cold-chain dependency.
- Boxes:Corrugated cases containing 10-20 kg frozen blocks serve Eastern European processor intake specifications for filleting line efficiency.
- Bags:Polyethylene pouches for frozen fillet retail packs balance visibility with frost protection in Scandinavian supermarket freezer cabinets.
- Trays:Expanded polystyrene and recyclable pulp formats present fresh herring in Dutch and Belgian retail fish counters with ice-bed display compatibility.
Tins anchor the volume base while trays gain share at the steepest rate as fresh format retailing expands.
Distribution Channel:
Customer type determines route complexity, with direct sales bypassing margin extraction by intermediaries while distributors absorb credit and inventory risk.
- Direct Sales:Norwegian and Icelandic vessel operators contract frozen herring volumes directly to German supermarket chains, bypassing auction markets and capturing 8-12% margin improvement.
- Wholesalers:Dutch seafood merchants in Urk and Vlissingen consolidate fresh and frozen lots for redistribution to Belgian and French retail accounts.
- Distributors:Temperature-controlled logistics specialists handle frozen and smoked product flows from processing facilities to Eastern European retail warehouses.
- Online Retail:E-commerce platforms serve niche demand for specialty smoked and marinated herring formats in urban German and UK markets.
Direct sales anchors the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish retail buyers exhibit the sharpest price elasticity in canned formats, while Dutch foodservice accounts absorb premiums for same-day fresh catch without volume contraction.
Norway
Direct-to-retail contracting from Norwegian vessel operators captures margin premiums in German and UK supermarket channels. The Directorate of Fisheries administers quota allocations that constrain total allowable catches for North Sea and Norwegian Sea stocks. Bergen and Ålesund anchor processing clusters where flash-freezing facilities supply Eastern European smokehouse operations.
Germany
MSC-certified canned herring dominates pantry-stocking patterns across discounter and supermarket tiers. The country's national food safety regulator enforces strict labeling requirements for marine products under EU hygiene regulations. Hamburg and Bremen serve as import gateways where Polish and Dutch distributors consolidate frozen volumes for redistribution.
Netherlands
Heritage smokehouse techniques command sustained premiums in Belgian and domestic foodservice accounts. The Dutch Food and Consumer Product Safety Authority implements traceability mandates aligned with EU Illegal, Unreported and Unregulated Fishing Regulation. Scheveningen and Urk maintain auction-based fresh fish markets where same-day catch supplies restaurant buyers.
Poland
Baltic processing smokehouses purchase frozen herring in bulk lots for filleting and value-added manufacturing. The country's veterinary inspectorate enforces EU hygiene standards for fishery products entering retail distribution. Gdynia and Szczecin concentrate cold-storage infrastructure serving domestic supermarkets and Czech export channels.
United Kingdom
Post-Brexit regulatory divergence creates procurement white space for Norwegian and Icelandic processors seeking direct retail listings. The Food Standards Agency adminishes import controls and sustainability documentation requirements distinct from EU quota pooling. Grimsby and Peterborough host processing facilities where smoked and marinated formats supply supermarket private label programs.
Herring Market Vendor Landscape
Vertically integrated fishing enterprises and specialized cold-chain distributors split the market between raw material control and channel access. Consolidation concentrates volume with fleet-owning processors capable of delivering consistent quality grades across extended contract periods. Three archetypes dominate: North Sea trawler-integrators, Scandinavian cold-chain specialists, and Baltic smokehouse operators. Competitive moves center on direct retail contracting and MSC certification acquisition to secure shelf placement.
Among North Sea trawler-integrators, Cornelis Vrolijk occupies a position exemplifying fleet-to-retail control over raw material flows. Domstein AS represents the Scandinavian cold-chain specialist archetype, while Iceland Seafood International anchors the certified-sustainability tier. These three entities collectively illustrate how sourcing credentials and distribution reach determine competitive position in quota-constrained supply conditions.
| Leading Market Players |
|---|
| Cornelis Vrolijk |
| Domstein AS |
| AS KURSA |
| Haringhandel A. Hoek BV |
| Esser Haringgroothandel en Rokerij BV |
| Barry Group Inc. |
| Denholm Seafoods Ltd. |
| Iceland Seafood International |
| Channel Fish Co. Inc. |
| Others |
Supply Flow & Price Mechanics
Norwegian and Icelandic vessel operators concentrate upstream catch capacity, directing margin capture toward processors with direct retail contracting relationships and MSC-certified inventory pools. Quota constraints under the Common Fisheries Policy amplify pricing power for non-EU suppliers serving German and UK supermarket channels.
Pricing Analysis
After-sales service contracts for cold-chain logistics and extended quality guarantees drive lifetime value for frozen and smoked herring formats. Three-tier pricing structure across premium MSC-certified, standard commercial-grade, and economy bulk-frozen levels segments buyer tiers. Pricing pressure stems from fuel cost volatility in pelagic trawler operations, compressing margins for mid-scale processors lacking long-term retail contracts. Polish retail buyers exhibit the sharpest price sensitivity in canned formats, while Dutch foodservice accounts absorb premiums for same-day fresh catch without volume contraction.
Supply Chain Analysis
Contract-manufacturing concentration sits with Dutch smokehouses in Urk and Vlissingen, Polish filleting operations in Gdynia and Szczecin, and Norwegian flash-freezing facilities in Bergen and Ålesund. Raw material flows draw from North Sea, Norwegian Sea, and Baltic Sea stocks, with packaging inputs resting on steel tinplate and temperature-controlled logistics equipment. Single-source vulnerability concentrates in Baltic Sea stock fluctuations, where recruitment failures cascade through dependent smokehouse operations. Distribution runs through direct vessel-to-retail contracting for frozen volumes, bypassing traditional auction markets and consolidating volume with vertically integrated suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across product format and certification tiers creates niche entry points, as MSC mandates and convenience demand pull new buyer segments toward audited, shelf-stable formats.
For Market Incumbents: Insulate market position by deepening backward integration into North Sea and Norwegian Sea quota holdings, securing raw material priority access ahead of EU allocation negotiations. Invest in automated filleting and pin-boning systems to collapse labor intensity and extend production cycles beyond shift-limited operations. Counter fuel cost volatility through vessel efficiency upgrades that satisfy German supermarket Scope 3 emissions documentation requirements. For New Entrants and Emerging Players: Build out blockchain traceability infrastructure to capture first-mover advantage under EU Illegal, Unreported and Unregulated Fishing Regulation mandates, securing premium retail placement ahead of certification backlogs. Target UK supermarket channels where post-Brexit regulatory divergence creates procurement white space independent of EU quota pooling. Enter through omega-3 supplement extraction, opening pharmaceutical and nutraceutical offtake beyond traditional food applications. For Investors and Strategic Acquirers: Capital is best deployed toward fleet-owning processors with direct retail contracting capabilities and MSC-certified supply chains, as quota constraints concentrate volume with vertically integrated suppliers. Long-term viability hinges on sustained access to non-EU catch zones and cold-chain infrastructure ownership. Watch for inflection in coastal state quota negotiations between Norway, Iceland, and EU member states as signal of raw material availability shifts.| Strategic Initiative | Industry Significance |
|---|---|
| MSC Certification Acquisition | Secures shelf placement in German and Polish retail channels requiring audited supply chains. |
| Direct Retail Contracting | Bypasses auction markets and captures 8-12% margin improvement for Norwegian vessel operators. |
| Automated Processing Deployment | Vision-guided robotics reduce manual handling by 60-70% for standard cuts in Dutch facilities. |
| Cold-Chain Infrastructure Expansion | Flash-freezing and controlled-atmosphere storage enable 12-18 month inventory cycles. |
| Blockchain Traceability Integration | EU IUU Regulation mandates create first-mover advantage for end-to-end catch documentation. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with vessel operators, processing facility managers, supermarket category buyers, and cold-chain logistics specialists; and secondary validation through customs trade records, EU Commission quota allocation documents, MSC certification registries, and seafood industry association reports. Bottom-up volume modeling from processor throughput data triangulated against top-down market sizing from retail audit channels.
Forecast inputs considered quota trajectory negotiations, fuel cost modeling for pelagic trawler operations, and retail procurement consolidation patterns across the projection horizon. Segmentation dimensions spanned product format, end-use channel, packaging type, and geographic sourcing origin. CAGRs derived from historical volume-price relationships projected forward under constrained supply assumptions.
Sensitivities concentrate around coastal state quota renegotiations, Baltic Sea recruitment variability, and MSC auditor capacity bottlenecks delaying market access timelines. Quarterly review of EU Commission TAC announcements and Marine Stewardship Council certification queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Processing Market
Seafood
Organic Salmon Market
Seafood
Seafood Processing Market
Seafood
Middle East Seafood Market
Seafood
Fish Hydrolysate Market
Seafood
Crustacean Market
Seafood
Canned Sardines Market
Seafood
Seafood Extracts Market
Seafood
Canned Fishery Product Market
Seafood
Caviar Market
Seafood
Food Clamshells Market
Seafood
Mussels Market
Seafood
Latin America Salmon Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
Global Commercial Fishing Market