
 Striped Bass Market | 2026-2036
Striped Bass Market Size, Share, and Industry Trends Forecast 2026-2036
Striped Bass Market Analytics
Portion-size bundling is shifting buyer choice in the Striped Bass Market as foodservice distributors move from whole-fish procurement to pre-cut fillet packs with yield guarantees. Euclid Fish Company leverages its Great Lakes processing infrastructure to supply consistent portion-controlled product to midwestern restaurant chains. Stavis Seafoods anchors its position through direct dock-to-kitchen relationships with independent seafood houses along the eastern seaboard. Pacifico Aquaculture differentiates via land-based recirculating aquaculture systems that deliver year-round supply independent of wild catch variability.
Striped bass (Morone saxatilis) is an anadromous perciform fish with firm, pink-tinged flesh averaging 15-25% fat content depending on origin and season, valued commercially for its mild flavor profile and grill-stable texture. Fresh product commands the dominant share of value as restaurants pay premiums for same-day landed fish with verifiable tags from specific harvesting areas. Frozen and smoked categories capture residual volume from seasonal oversupply, with smoked stripers finding niche placement in specialty retail. The aquaculture application segment shows structural momentum as land-based tank systems reduce mortality rates and accelerate grow-out cycles compared to net-pen alternatives.
NOAA Fisheries and the Atlantic States Marine Fisheries Commission jointly administer interstate fishery management plans that set annual catch limits and minimum size thresholds for wild striped bass stocks. FDA Hazard Analysis Critical Control Point rules govern processing facility sanitation and temperature documentation from harvest through distribution. State environmental agencies in Maryland and Virginia enforce nutrient discharge permits for land-based aquaculture operations. Stakeholders must monitor pending revisions to Magnuson-Stevens Act reauthorization language that could reshape federal oversight of recreational versus commercial allocation.
Market Dynamics
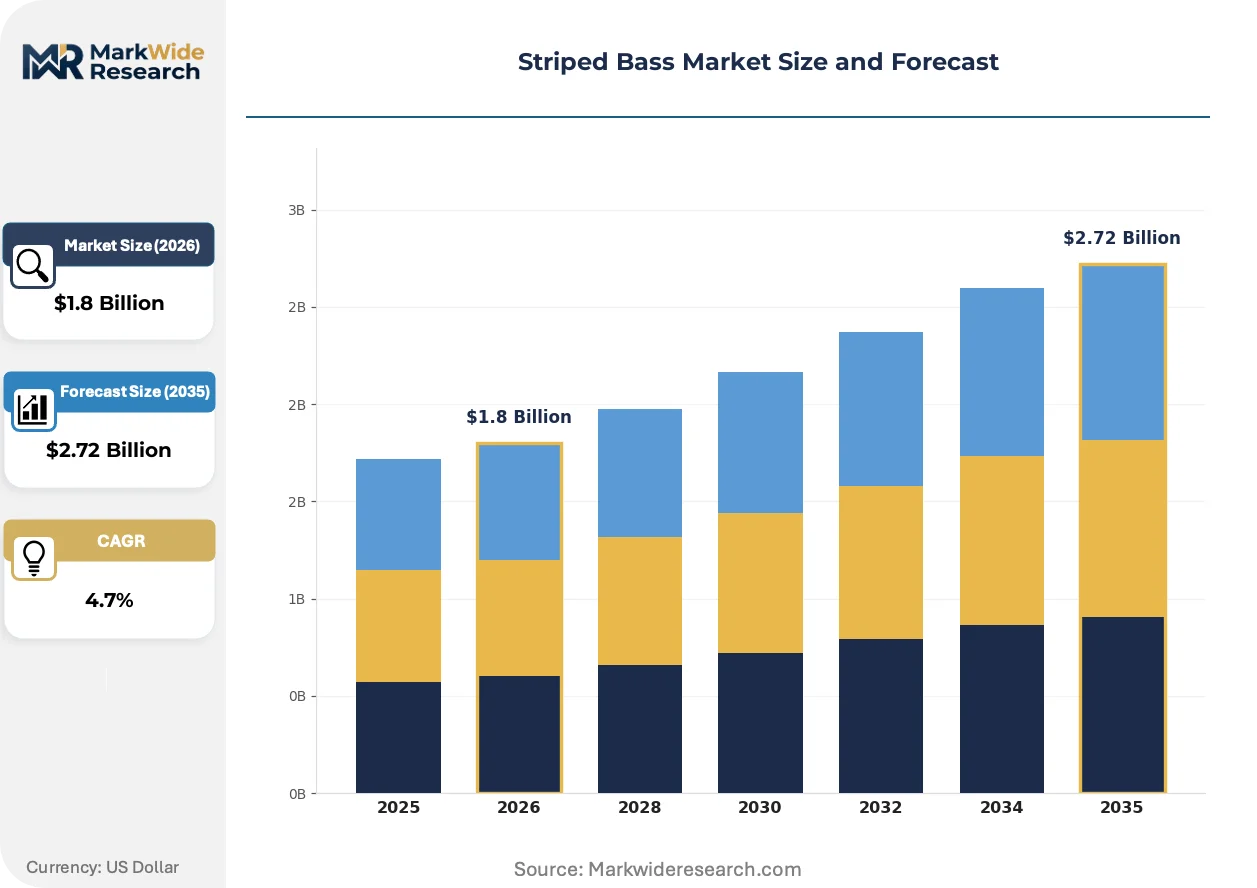
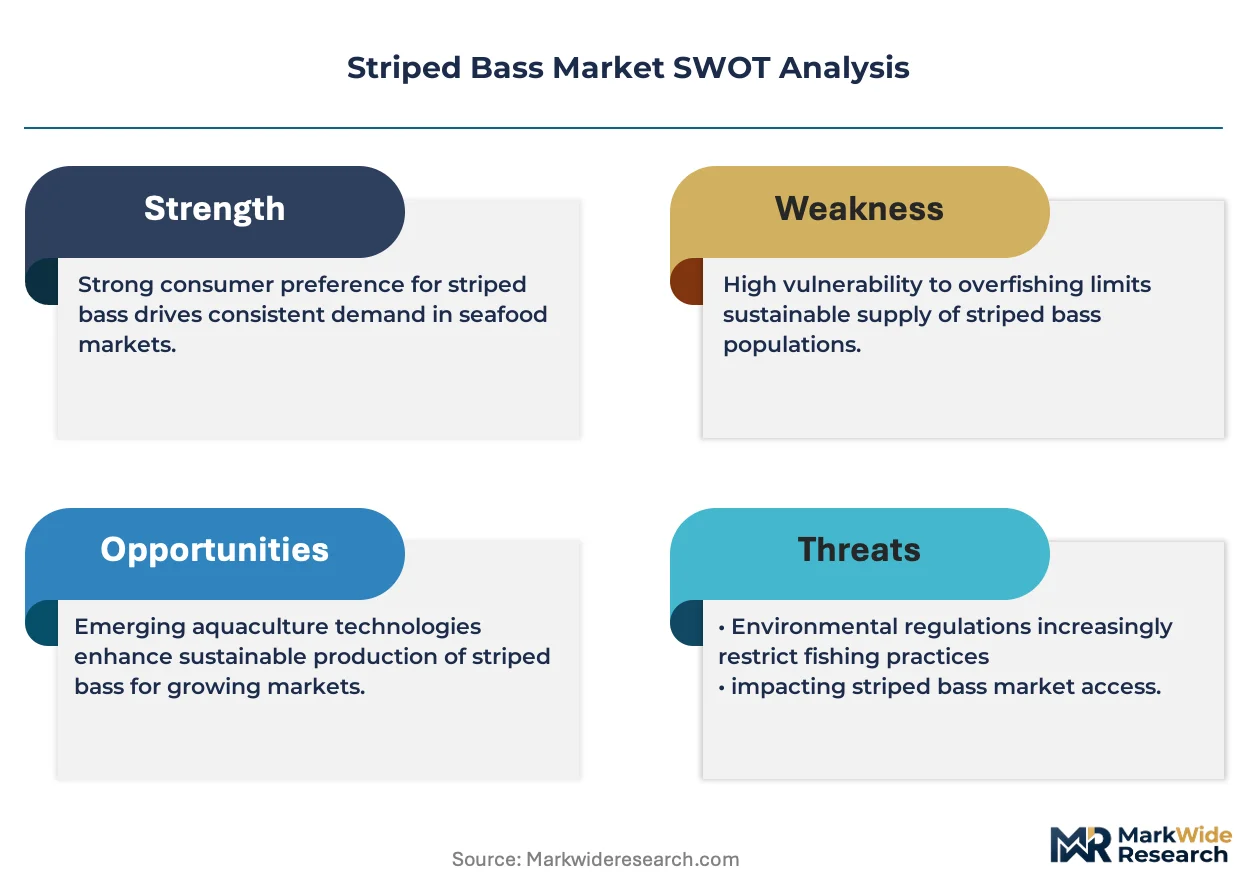
The Striped Bass Market pivots on a fundamental tension between NOAA-imposed catch limits and foodservice buyers' insatiable demand for traceable domestic supply. Interstate fishery management plans cap wild harvest volumes while aquaculture systems race to close the gap with land-based production.
Growth Catalysts
- Atlantic States Marine Fisheries Commission quota frameworks:These interstate agreements stabilize wild stock recovery trajectories, creating predictable supply baselines that attract long-term distributor investment.
- Recirculating aquaculture system (RAS) technology:Land-based tank infrastructure eliminates seasonal mortality spikes and accelerates grow-out cycles independent of Chesapeake Bay water temperature fluctuations.
- Mid-Atlantic restaurant chains:These buyers now mandate dock-to-kitchen traceability tags, paying premiums for same-day landed product with verified harvesting area documentation.
Market Restraints
- FDA HACCP compliance costs:Processing facilities must maintain continuous temperature documentation from harvest through distribution, elevating capital requirements for small-scale operators.
- Chesapeake Bay wild stock concentration:Over half of commercial landings originate from this single estuary system, exposing supply chains to localized hypoxic events and disease outbreaks.
- Frozen tilapia substitution:Budget-conscious foodservice accounts increasingly substitute lower-cost farmed whitefish in casual dining applications, compressing mid-tier striped bass pricing.
Strategic Opportunities
- Great Lakes RAS expansion:Michigan and Ohio processing infrastructure remains underutilized for striped bass, offering geographic diversification from Atlantic supply concentration.
- Direct-to-institutional channels:University and corporate dining systems seek contracted volume commitments with yield-guaranteed fillet packs, bypassing traditional distributor markups.
- Magnuson-Stevens Act reauthorization:Pending federal legislation may reallocate recreational versus commercial catch shares, potentially expanding quota access for documented sustainable harvesters.
Industry Challenges
- Multi-jurisdictional permitting complexity:Land-based aquaculture operators navigate overlapping state environmental agency nutrient discharge rules, federal water quality standards, and local zoning ordinances simultaneously.
- Harvest-to-processing cold chain integrity:Summer peak landings in Maryland and Virginia stress ice-capacity and transportation logistics, elevating spoilage risk during temperature excursions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Striped Bass Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Smoked, Processed End User: Restaurants, Supermarkets, Fish Markets, Food Services Distribution Channel: Direct Sales, Wholesale, E-Commerce, Retail Application: Culinary, Aquaculture, Recreational Fishing, Research |
| Companies Covered | A&H Seafood Market Partners, Euclid Fish Company, Stavis Seafoods, The Town Dock, Robert Wholey & Company Inc., Aqua Best Seafood Market, Allseas Fisheries Corp., Chester River Seafood, Pacifico Aquaculture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Striped Bass Market Evolving Landscape
Processing automation and traceability systems are compressing traditional supply chain layers while regulatory pressure intensifies documentation requirements. These forces reshape competitive positioning around speed-to-market and verifiable provenance rather than scale alone.
Computer vision grading systems are automating fillet quality assessment at processing lines, replacing manual inspection with real-time defect detection. Mid-Atlantic distributors deploy these systems to guarantee yield percentages in contracted restaurant deliveries. The technology is automating labor-intensive sorting tasks that previously bottlenecked peak-season throughput.
Magnuson-Stevens Act reauthorization debates are forcing quota allocation transparency, with congressional committees scrutinizing recreational angler versus commercial harvester equity. This legislative pressure is accelerating stakeholder coalition formation around transferable catch share mechanisms. Mid-Atlantic states are responding with pilot programs for electronic harvest reporting that satisfy federal audit requirements.
Dock-to-kitchen procurement is consolidating buyer relationships around direct harvester contracts, displacing traditional auction-house and distributor intermediaries. Independent seafood houses along the eastern seaboard now source through verified tagging systems that bypass secondary wholesalers. Massachusetts and North Carolina restaurants lead this behavioral shift, with chefs demanding specific harvesting area documentation for menu storytelling.
Striped Bass Market Segmentation
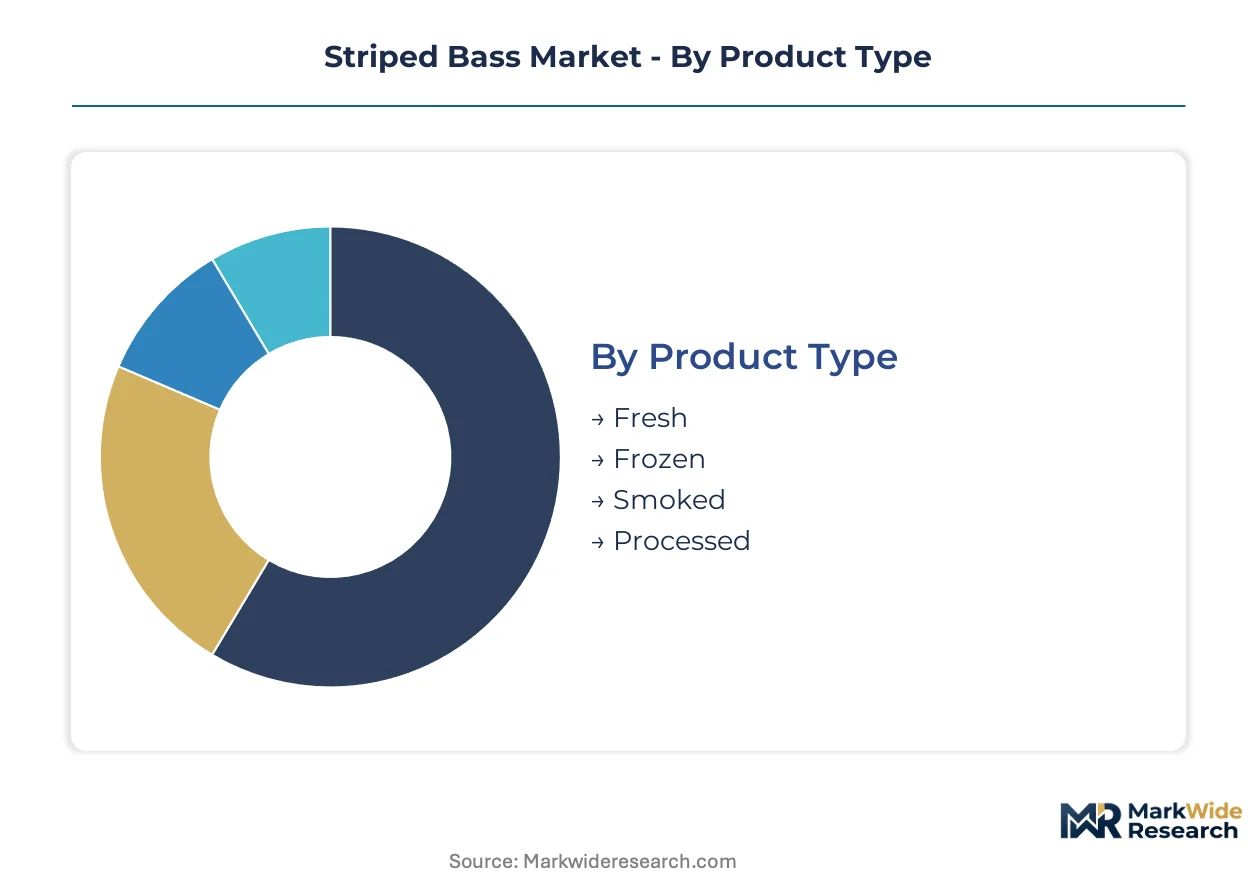
Striped bass market segmentation reveals divergent value capture strategies across preservation states and buyer channels. Fresh product commands price premiums through traceability documentation while frozen and processed categories absorb seasonal oversupply. Understanding these segment dynamics exposes where distributor investment and regulatory compliance costs concentrate.
Product Type:
Fresh product dominates value concentration while frozen categories anchor volume throughput in distributor portfolios.
- Fresh:Same-day landed fish with verifiable harvesting area tags command premium pricing from mid-Atlantic restaurant chains prioritizing menu provenance stories. FDA HACCP temperature documentation requirements from harvest through distribution elevate processing facility capital requirements. Chesapeake Bay and Massachusetts landing sites concentrate supply.
- Frozen:Blast-frozen fillet packs with yield guarantees serve institutional buyers seeking contracted volume commitments independent of seasonal wild catch variability. Great Lakes processing infrastructure from Euclid Fish Company supplies consistent portion-controlled product to midwestern restaurant chains. This category absorbs summer peak landings when fresh channel capacity saturates.
- Smoked:Specialty retail placement targets premium consumers with cured product from seasonal oversupply.
- Processed:Value-added preparations including pre-marinated portions reduce kitchen labor for foodservice accounts.
Today's leader: Fresh. Tomorrow's challenger: Frozen.
End User:
Buyer sophistication tiers separate traceability-demanding independent operators from price-sensitive institutional accounts.
- Restaurants:Independent seafood houses along the eastern seaboard from Massachusetts through North Carolina mandate dock-to-kitchen traceability tags and pay premiums for specific harvesting area documentation. Chefs leverage verifiable provenance for menu storytelling. Computer vision grading systems guarantee yield percentages in contracted deliveries.
- Supermarkets:Retail chains source through verified tagging systems that satisfy consumer transparency demands while managing shrink through controlled atmosphere packaging.
- Fish Markets:Traditional auction-house intermediaries face displacement from direct harvester contracts.
- Food Services:University and corporate dining systems seek yield-guaranteed fillet packs with bypassed distributor markups.
Restaurants currently absorb premium supply; food services represent the steepest expansion trajectory for contracted volume.
Distribution Channel:
Channel structure determines speed-to-market and documentation integrity for temperature-sensitive product.
- Direct Sales:Dock-to-kitchen procurement consolidates buyer relationships around verified harvester contracts, displacing traditional auction-house intermediaries. Stavis Seafoods anchors position through direct relationships with independent seafood houses. Electronic harvest reporting pilot programs satisfy federal audit requirements.
- Wholesale:Traditional distributor markups face compression from institutional buyers seeking contracted volume commitments.
- E-Commerce:Direct-to-consumer platforms serve specialty retail with smoked and value-added categories.
- Retail:Supermarket chains integrate traceability documentation into consumer-facing packaging.
Direct sales channels gain share fastest; wholesale intermediaries face margin compression.
Application:
Commercial culinary demand separates high-value foodservice from structural growth in controlled production systems.
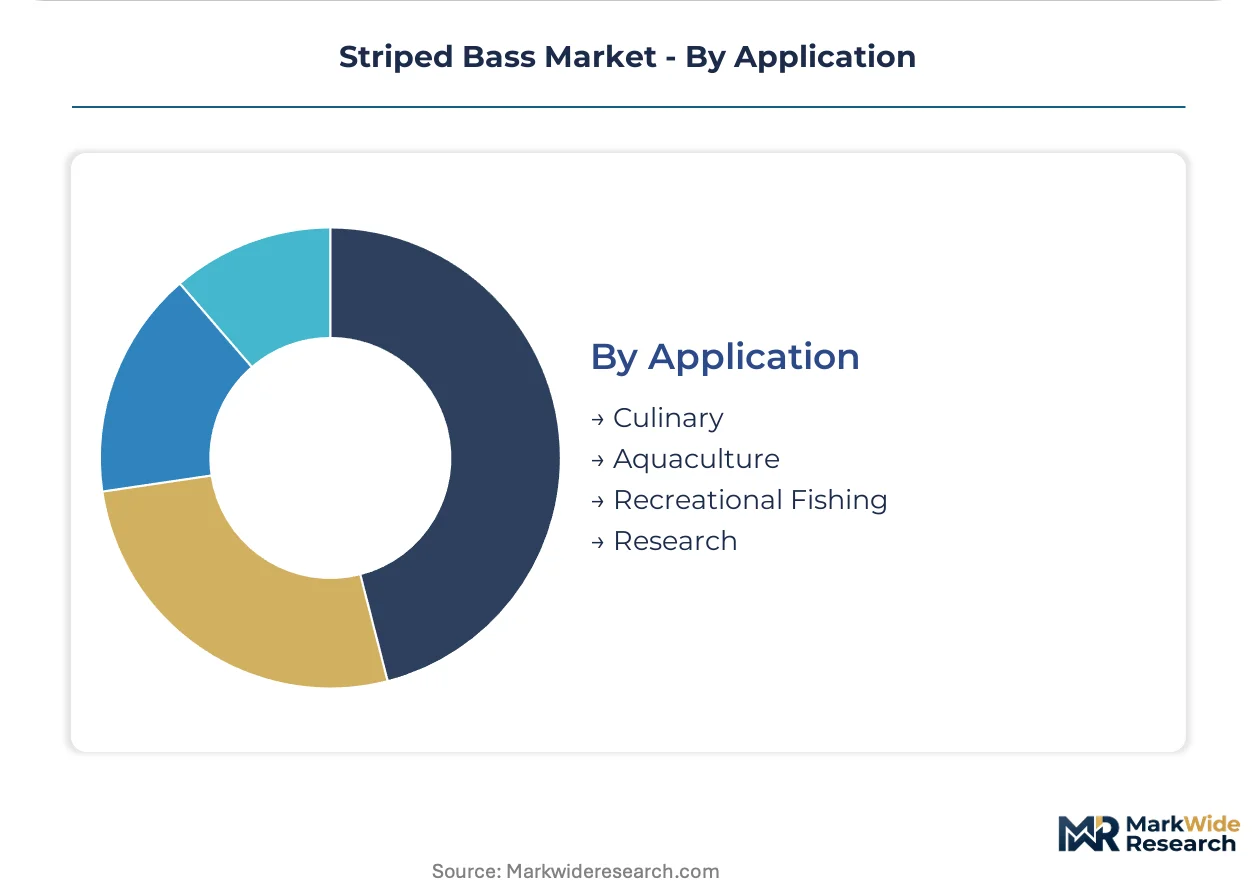
- Culinary:Grill-stable texture and mild flavor profile drive foodservice procurement across mid-Atlantic restaurant chains. Firm, pink-tinged flesh averaging 15-25% fat content commands premium positioning. NOAA fisheries quotas and state-level catch limits constrain wild harvest volumes available to this segment.
- Aquaculture:Land-based recirculating aquaculture systems from Pacifico Aquaculture deliver year-round supply independent of wild catch variability and Chesapeake Bay water temperature fluctuations. Tank infrastructure reduces mortality rates and accelerates grow-out cycles compared to net-pen alternatives.
- Recreational Fishing:Atlantic States Marine Fisheries Commission quota frameworks allocate separate harvest shares monitored through electronic reporting systems.
- Research:Stock assessment programs support interstate fishery management plan development.
Culinary applications currently dominate value capture; aquaculture represents the fastest-climbing trajectory as RAS technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Striped bass aquaculture and wild harvest operations trace their commercial lineage to the Chesapeake Bay watershed, where state hatchery programs scaled production through the mid-20th century. Domestic processing infrastructure now spans the Atlantic seaboard, with land-based recirculating systems expanding into interior watersheds.
United States
Mid-Atlantic restaurant chains from Massachusetts through North Carolina drive dock-to-kitchen procurement, mandating verifiable harvesting area tags for menu provenance. NOAA Fisheries and the Atlantic States Marine Fisheries Commission jointly administer interstate quota frameworks that stabilize wild stock recovery trajectories. Chesapeake Bay processing clusters in Maryland and Virginia handle summer peak landings, while Great Lakes infrastructure in Michigan and Ohio supplies portion-controlled product to midwestern buyers.
Canada
Atlantic provincial seafood distributors source striped bass through seasonal wild harvest and limited aquaculture trials in New Brunswick and Nova Scotia. Health Canada enforces Safe Food for Canadians Regulations governing temperature documentation from harvest through distribution. Quebec and Ontario foodservice buyers increasingly contract Great Lakes-processed fillet packs with yield guarantees.
Mexico
Baja California aquaculture operations experiment with land-based tank systems for export-grade production targeting U.S. southwestern markets. Mexico's national aquaculture regulator oversees discharge permits and biosecurity protocols for coastal production facilities. Ensenada processing clusters handle preliminary fillet preparation for cross-border distribution.
United Kingdom
Specialty seafood importers in London and Southeast England distribute smoked and frozen striped bass to premium retail channels. Food Standards Agency hygiene regulations govern cold chain integrity for temperature-sensitive imports. British restaurant procurement remains minimal compared to domestic European sea bass preferences.
Japan
Tokyo and Osaka-based seafood trading houses import limited frozen striped bass volumes for high-end sushi applications. Japan's Ministry of Health, Labour and Welfare enforces food sanitation laws on imported seafood temperature documentation. Kanto region distributors serve niche demand among expatriate dining establishments.
Striped Bass Market Competitive Landscape
Premium-margin players sit above commodity-margin players across traceability documentation and portion-control capabilities. The vendor base clusters around three strategic archetypes: land-based aquaculture specialists with year-round RAS supply, dock-to-kitchen distributors with direct harvester relationships, and Great Lakes processors leveraging geographic diversification from Atlantic supply concentration. Competitive moves concentrate on processing automation investments and electronic harvest reporting systems that satisfy federal audit requirements.
Among U.S.-based distributors, Stavis Seafoods and Euclid Fish Company exemplify divergent geographic strategies—Stavis anchors direct relationships with independent seafood houses along the eastern seaboard, while Euclid occupies a position supplying consistent portion-controlled product through underutilized Great Lakes infrastructure. Pacifico Aquaculture represents the land-based RAS archetype, delivering supply independent of wild catch variability.
| Leading Market Players |
|---|
| A&H Seafood Market Partners |
| Euclid Fish Company |
| Stavis Seafoods |
| The Town Dock |
| Robert Wholey & Company Inc. |
| Aqua Best Seafood Market |
| Allseas Fisheries Corp. |
| Chester River Seafood |
| Pacifico Aquaculture |
| Others |
Value Network & Pricing Analysis
Land-based recirculating aquaculture system (RAS) technology simultaneously compresses grow-out cycle economics and redistributes production capacity away from Chesapeake Bay concentration. This production-method transition enables year-round supply independent of wild catch quotas while elevating capital requirements that reshape competitive entry barriers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates dock-to-kitchen fresh product from blast-frozen fillet packs and commodity-smoked categories. Price differentiation rests on traceability documentation grade and volume scale commitments, with independent seafood houses paying premiums for same-day landed fish with verified harvesting area tags. Cost compression in mid-tier frozen categories is intensifying because budget-conscious foodservice accounts substitute lower-cost farmed whitefish in casual dining applications. University and corporate dining systems exhibit highest price sensitivity; independent restaurants along the eastern seaboard demonstrate lowest sensitivity when provenance documentation supports menu storytelling.
Supply Chain Analysis
Workforce availability constraints in Maryland and Virginia processing clusters elevate labor costs during summer peak landing periods. Geographic supply concentration centers on the United States Atlantic seaboard, with emerging Great Lakes infrastructure in Michigan and Ohio and limited Baja California aquaculture trials. Raw material dependencies draw from wild Chesapeake Bay stocks, land-based RAS fingerling supplies, and seasonal Massachusetts landings. Single-source vulnerability from Chesapeake Bay wild stock concentration exposes chains to localized hypoxic events. Distribution runs through direct dock-to-kitchen procurement channels consolidating buyer relationships around verified harvester contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Striped Bass Market reads as a late-cycle quality story. Mid-Atlantic restaurant chains now mandate traceability tags and pay premiums for specific harvesting area documentation, shifting procurement toward verifiable domestic sourcing.
For Market Incumbents: Anchor defensive positioning through backward integration into land-based RAS production capacity and electronic harvest reporting systems that satisfy federal audit requirements. Processors must secure nutrient discharge permits ahead of state environmental agency rule revisions. Stavis Seafoods and Euclid Fish Company demonstrate divergent geographic anchoring strategies worth emulating. For New Entrants and Emerging Players: Enter via underutilized Great Lakes processing infrastructure serving midwestern restaurant chains with portion-controlled fillet packs. The institutional foodservice segment—university and corporate dining systems—offers the most penetrable white-space target with contracted volume commitments and bypassed distributor markups. Target yield-guaranteed procurement contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for land-based RAS specialists because interstate quota frameworks cap wild harvest volumes and accelerate substitution demand for controlled production systems. Long-term viability hinges on technology maturation reducing mortality rates and accelerating grow-out cycles. Monitor Magnuson-Stevens Act reauthorization progress as the signal to watch for commercial quota reallocation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| RAS Capacity Expansion | Land-based tank infrastructure eliminates seasonal mortality spikes and accelerates grow-out cycles independent of Chesapeake Bay conditions. |
| Electronic Harvest Reporting | Pilot programs satisfy Atlantic States Marine Fisheries Commission federal audit requirements and quota allocation transparency demands. |
| Direct Dock-to-Kitchen Contracts | Verified tagging systems displace traditional auction-house intermediaries and consolidate buyer relationships around traceability documentation. |
| Computer Vision Grading Investment | Real-time defect detection automates labor-intensive sorting tasks that previously bottlenecked peak-season processing throughput. |
| Great Lakes Geographic Diversification | Michigan and Ohio processing infrastructure reduces Atlantic supply concentration exposure and serves midwestern institutional buyers. |
Research Methodology
Direct dialogue with seafood distributors, land-based aquaculture operators, restaurant procurement executives, and state environmental agency officials grounded qualitative insights. Secondary validation drew from NOAA Fisheries stock assessment reports, Atlantic States Marine Fisheries Commission quota documentation, FDA HACCP guidance filings, and state-level nutrient discharge permit records. Bottom-up and top-down triangulation cross-checked volume estimates against processing facility capacity disclosures and restaurant chain procurement data.
Bottom-up modeling segmented volume and value across preservation states, buyer channels, and application types throughout the forecast period. Segmentation dimensions included product type, end user sophistication tier, distribution channel structure, and production method. CAGRs were derived from trend extrapolation adjusted for regulatory constraint scenarios and technology adoption curves. Wild stock recovery trajectories and RAS technology cost curves served as industry-specific forecast inputs.
Inputs from NOAA Fisheries, state environmental agencies, and distributor interviews were available through the study window; gaps in proprietary RAS facility operating metrics introduce uncertainty bands around aquaculture supply projections. Forecasts reflect documented assumptions regarding quota stability and technology maturation timelines. Material deviation in Magnuson-Stevens Act reauthorization outcomes or Chesapeake Bay hypoxic event frequency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Sea Biscuits Market
Seafood
Global Commercial Fishing Market
Seafood
Tuna and Algae Omega-3 Market
Seafood
Seafood Takeout Market
Seafood
Mussels Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Fish Protein Market
Seafood
Japan Lobster Market
Seafood
COD Market
Seafood
Processed Seafood Market
Seafood
Lobster Market
Seafood
United States Plant-Based Seafood Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Seafood Flavors Market
Seafood
Latin America Salmon Market
Seafood
Fresh Fish Market