
 Automotive Image Signal Processor Market | 2026-2036
Automotive Image Signal Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Image Signal Processor Market Insights
Silicon germanium is decoupling from legacy CMOS architectures in high-end automotive vision systems, lowering wafer costs while preserving quantum efficiency in near-infrared bands. NXP Semiconductors leverages its S32G vehicle network processors to bundle ISP acceleration with domain control, sustaining integrated design wins across German and Japanese OEM programs. Texas Instruments anchors its position through Jacinto 7 SoCs that embed programmable vision accelerators, competing on power-constrained edge compute for front-camera modules. ON Semiconductor specializes in Hayabusa-series CMOS image sensors with co-optimized ISP pipelines, dominating the 8-megapixel segment for Level 2+ perception stacks.
An automotive image signal processor is a dedicated semiconductor subsystem that converts raw analog or digital pixel data from image sensors into enhanced, encoded video streams suitable for machine vision and human display, typically handling operations at 60–120 frames per second with sub-50-millisecond latency to support real-time vehicle decisioning. Its primary commercial purpose is to enable advanced driver assistance and automated driving systems to perceive lane markings, pedestrians, and obstacles under varying illumination. Driver Assistance applications currently command the largest revenue share, though Autonomous Driving modules exhibit the steepest growth trajectory as robotaxi programs scale. OEM direct procurement is displacing Tier-1 mediated sourcing for ISP silicon, concentrating margin pools with semiconductor vendors that offer sensor-processor co-design services.
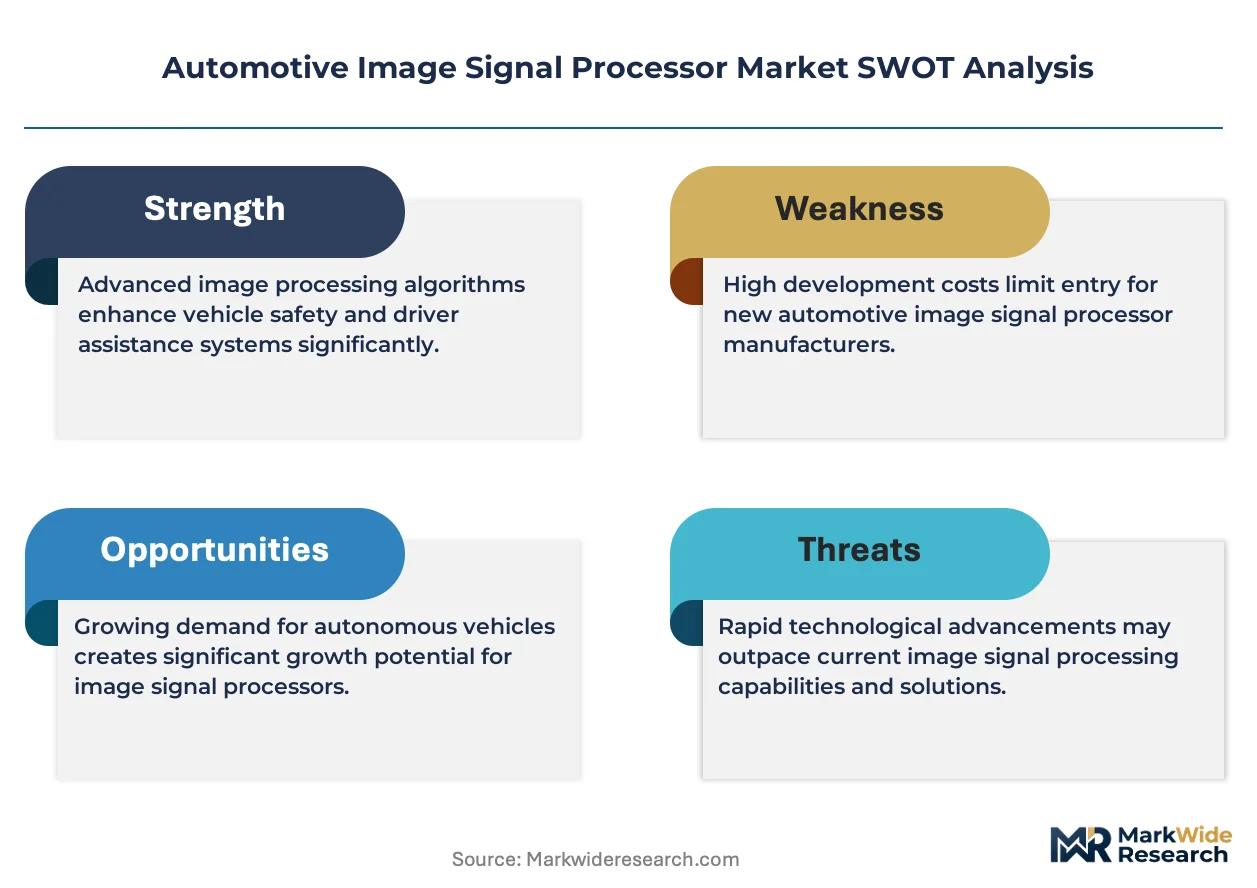
FCC Part 15 emissions rules in the United States, E-Mark type approval under UNECE WP.29 in Europe, and China's GB/T standards for advanced driver assistance constrain hardware architectures and validate cybersecurity overlays for camera-linked ISPs. These frameworks compel vendors to pre-certify electromagnetic compatibility and functional safety credentials before platform integration, raising barriers for unqualified entrants. Stakeholders must monitor how NHTSA's anticipated camera-based automatic emergency braking mandate and the EU AI Act's risk classification for autonomous systems reshape validation timelines and software liability exposure.
Market Dynamics
OEM direct procurement of ISP silicon is displacing Tier-1 mediated sourcing, compressing margin pools toward semiconductor vendors offering sensor-processor co-design services and concentrating supply relationships around integrated platform providers.
Growth Catalysts
- UNECE R79/R157 E-Mark mandates:European type approval requirements for automated lane-keeping and driver monitoring are forcing hardware refreshes across premium vehicle lines, accelerating ISP procurement for surround-view modules.
- Silicon germanium architectures:Advanced SiGe fabrication is decoupling from legacy CMOS at the wafer level, preserving quantum efficiency in near-infrared bands while lowering unit costs for night-vision perception stacks.
- Robotaxi perception scaling:Autonomous ride-hail programs in the United States and China are driving volume demand for 8-megapixel front-camera ISPs with sub-50-millisecond latency specifications.
Market Restraints
- Wafer supply concentration:Advanced SiGe and stacked-CMOS capacity remains captive to Taiwanese and South Korean foundry networks, creating input bottlenecks for European and North American fabless designers.
- FCC Part 15 electromagnetic compliance:United States emissions certification for camera-linked ISPs requires pre-validated shielding architectures that extend development cycles and limit vendor flexibility.
- Functional safety certification costs:ISO 26262 ASIL-B and ASIL-D qualification for automotive ISPs demands redundant pipeline designs that inflate silicon area and unit economics.
Strategic Opportunities
- India PLI scheme for automotive electronics:Production-linked incentives for advanced driver assistance component manufacturing are attracting ISP packaging and test investments to Tamil Nadu and Gujarat clusters.
- Sensor-processor convergence:Co-optimized CMOS image sensor and ISP pipeline design is enabling Level 2+ perception stacks with reduced bill-of-material complexity and lower thermal budgets.
- China GB/T ADAS standardization:Mandatory camera-based automatic emergency braking requirements under GB/T 39901 are creating compliance-driven replacement cycles for domestic and joint-venture vehicle platforms.
Industry Challenges
- Embedded vision software talent scarcity:Shortage of engineers proficient in real-time image pipeline optimization and ASIL-qualified firmware development is constraining vendor roadmap velocity.
- Multi-domain integration complexity:ISPs must simultaneously serve human display, machine vision, and data recording paths with divergent latency and quality requirements, complicating verification matrices.
- Cybersecurity overlay validation:UNECE WP.29 R155 and ISO/SAE 21434 mandates for camera-linked systems require cryptographic authentication blocks that consume die area and power budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Image Signal Processor Market |
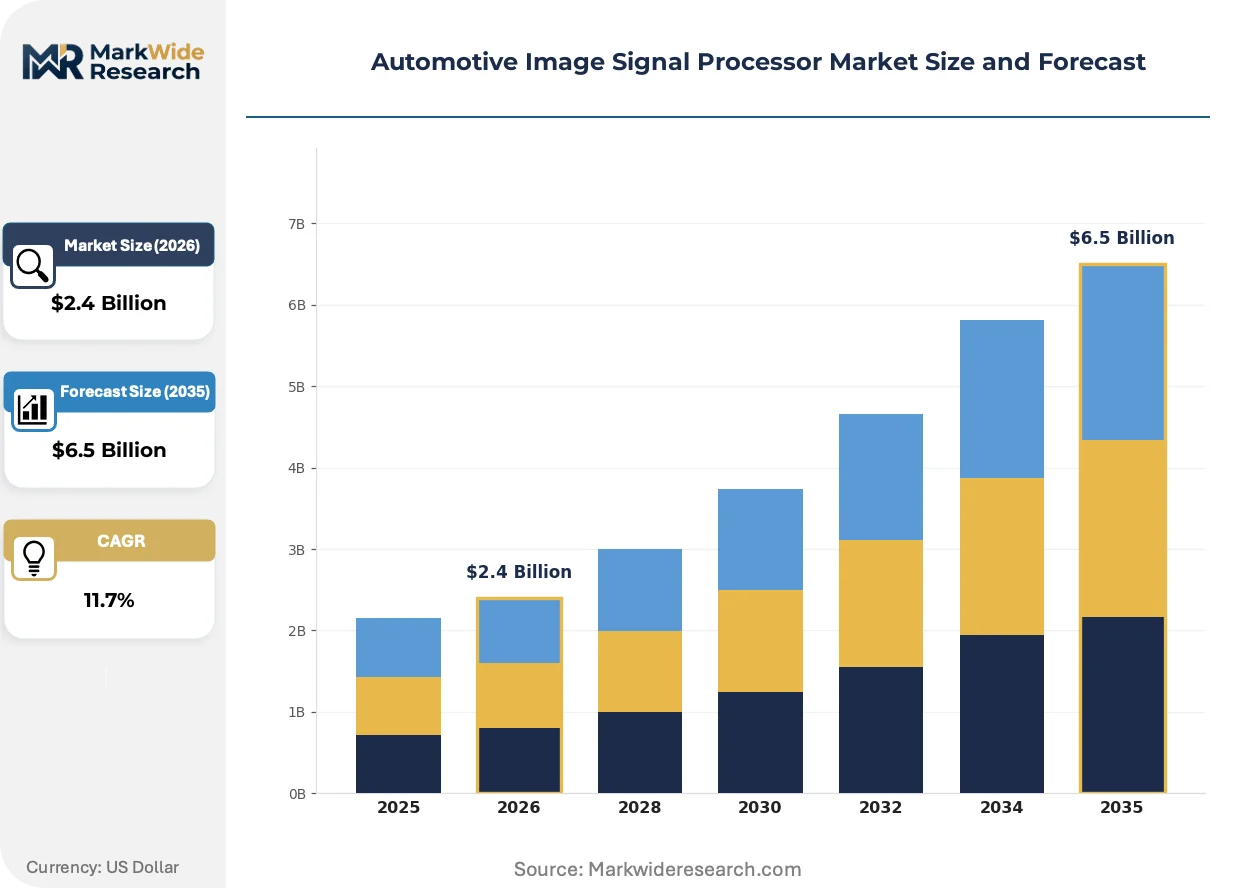
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Driver Assistance, Autonomous Driving, Safety Systems, Infotainment Technology: CMOS, CCD, Image Processing Algorithms, Sensor Fusion End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Feature: Real-Time Processing, High Dynamic Range, Low Light Performance, Noise Reduction |
| Companies Covered | NXP Semiconductors, Texas Instruments, ON Semiconductor, Intel (Mobileye), Renesas Electronics, OmniVision Technologies, STMicroelectronics, Ambarella, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Image Signal Processor Market Trends and Innovations
Edge computing architectures are redistributing image processing workloads away from centralized domain controllers, creating demand for ISPs with embedded neural acceleration and programmable vision pipelines.
Programmable vision accelerators embedded within automotive SoCs are decentralizing perception compute from standalone GPU clusters to camera-edge nodes. Tier-1 suppliers are adopting these integrated pipelines for front-camera modules in power-constrained vehicle platforms. This topology is compressing wiring harness weight and reducing centralized thermal management requirements across German and Japanese OEM programs.
The EU AI Act's risk classification framework for autonomous systems is imposing documentation and validation burdens on high-stakes perception components. Hardware vendors must now pre-certify functional safety credentials and algorithmic transparency before platform integration. Level 3 and Level 4 automated driving modules face the steepest compliance timeline extensions and software liability exposure adjustments.
Direct semiconductor procurement by vehicle manufacturers is fragmenting traditional Tier-1 supply relationships and unbundling sensor-processor integration services. BMW, Mercedes-Benz, and Volkswagen are negotiating co-design contracts that bypass established module suppliers. This pattern concentrates most visibly in Germany's premium ADAS program rollouts, where OEMs seek margin capture and roadmap control.
Automotive Image Signal Processor Market Segmentation
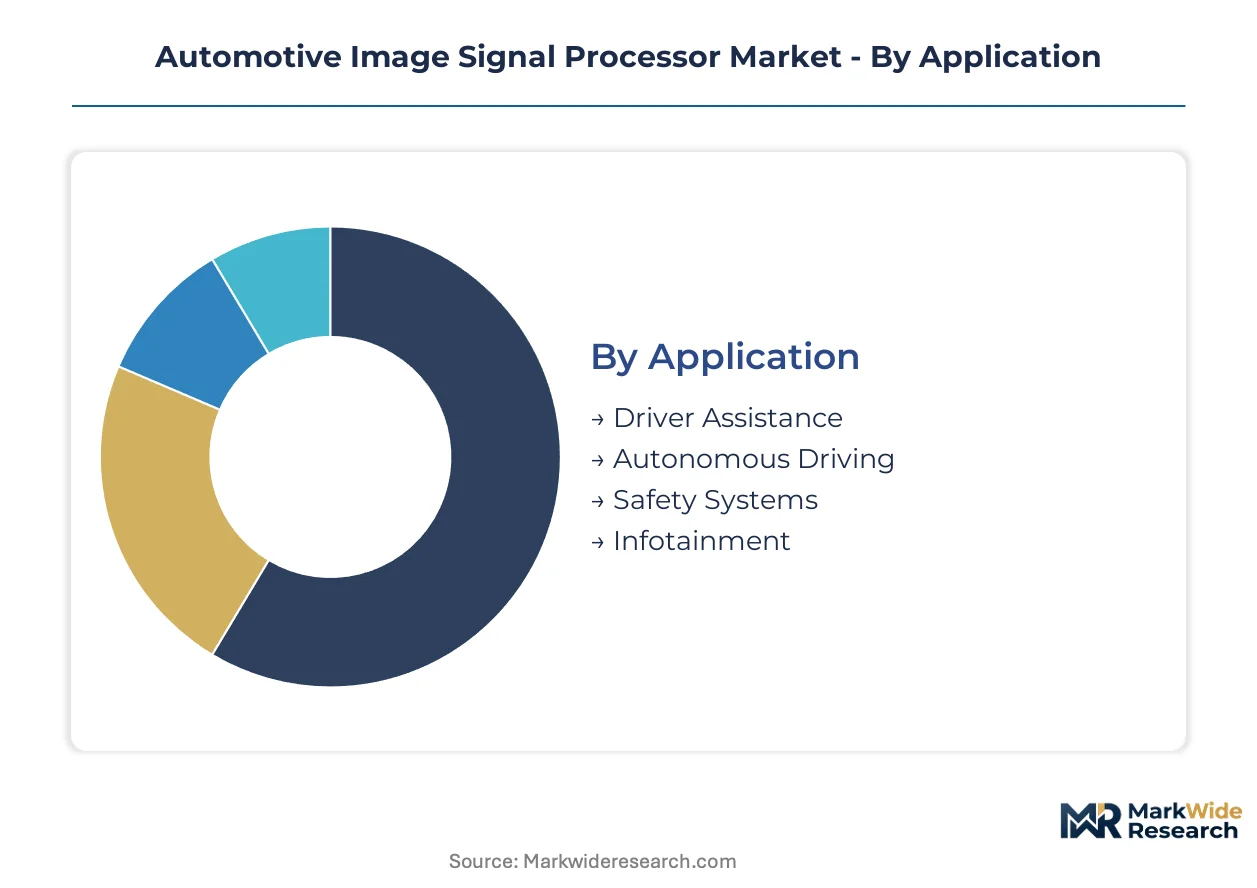
Automotive image signal processors serve divergent computational loads across vehicle systems. Application requirements vary from sub-50-millisecond latency for emergency braking to relaxed timing for cabin entertainment. Technology choices determine wafer economics and spectral sensitivity trade-offs.
Application:
Volume deployment concentrates in assisted driving functions, while premium silicon targets unsupervised automation.
- Driver Assistance:ISPs in this segment handle lane-keeping, adaptive cruise control, and parking assistance with 60–120 frames per second throughput. German OEMs anchor procurement for surround-view modules under UNECE R79 compliance timelines. Hardware refresh cycles accelerate as Level 2+ penetration deepens across European premium vehicle lines.
- Autonomous Driving:Robotaxi programs in the United States and China demand 8-megapixel front-camera ISPs with redundant pipeline architectures. Sub-50-millisecond latency specifications and ASIL-D functional safety qualifications inflate silicon area and unit costs. Tier-1 suppliers face margin compression as OEMs negotiate direct semiconductor procurement.
- Safety Systems:Automatic emergency braking and collision avoidance rely on hardened ISP pipelines with pre-certified electromagnetic compatibility.
- Infotainment:Cabin monitoring and occupant recognition operate with relaxed latency budgets and lower ASIL grades.
Mature deployment sits with Driver Assistance. Newer deployment is concentrated in Autonomous Driving.
Technology:
Cost tier separation runs from commodity CMOS to specialized silicon germanium architectures.
- CMOS:Stacked-CMOS fabrication dominates mid-range and high-volume automotive camera modules. Taiwanese and South Korean foundry networks control wafer supply, creating input bottlenecks for European fabless designers. Unit economics improve with each process node shrink, though near-infrared quantum efficiency lags SiGe alternatives.
- Image Processing Algorithms:Programmable vision accelerators embedded within automotive SoCs decentralize perception compute from standalone GPU clusters. Edge computing architectures redistribute workloads to camera-edge nodes, compressing wiring harness weight across Japanese OEM programs. Real-time pipeline optimization requires scarce embedded vision software talent.
- CCD:Legacy charge-coupled devices persist in specialized industrial inspection applications with limited automotive relevance.
- Sensor Fusion:Multi-modal integration combines camera, radar, and lidar data streams at the domain controller level.
Volume manufacturing clusters around CMOS. Capability differentiation is expanding most quickly in Image Processing Algorithms.
End User:
Customer type determines margin capture and design control allocation across the value chain.
- OEMs:BMW, Mercedes-Benz, and Volkswagen negotiate co-design contracts that bypass established module suppliers. Direct semiconductor procurement concentrates margin pools with vendors offering sensor-processor integration services. Roadmap control motivates German premium OEMs to unbundle traditional Tier-1 relationships.
- Tier-1 Suppliers:Continental, Bosch, and Denso mediate sourcing for mid-market vehicle platforms where OEMs lack internal vision system expertise. Procurement patterns favor integrated ISP-sensor platforms with pre-validated electromagnetic compatibility. Margin pressure intensifies as semiconductor vendors capture design-in value.
- Aftermarket Providers:Retrofit ADAS modules for commercial fleets operate outside OEM warranty and certification frameworks.
- Vehicle Assemblers:Contract manufacturers in emerging production clusters source ISPs through Tier-1 channels.
Established relationships persist with Tier-1 Suppliers. Structural shift is accelerating toward OEMs.
Feature:
Performance tiering separates premium perception stacks from cost-optimized cabin monitoring solutions.
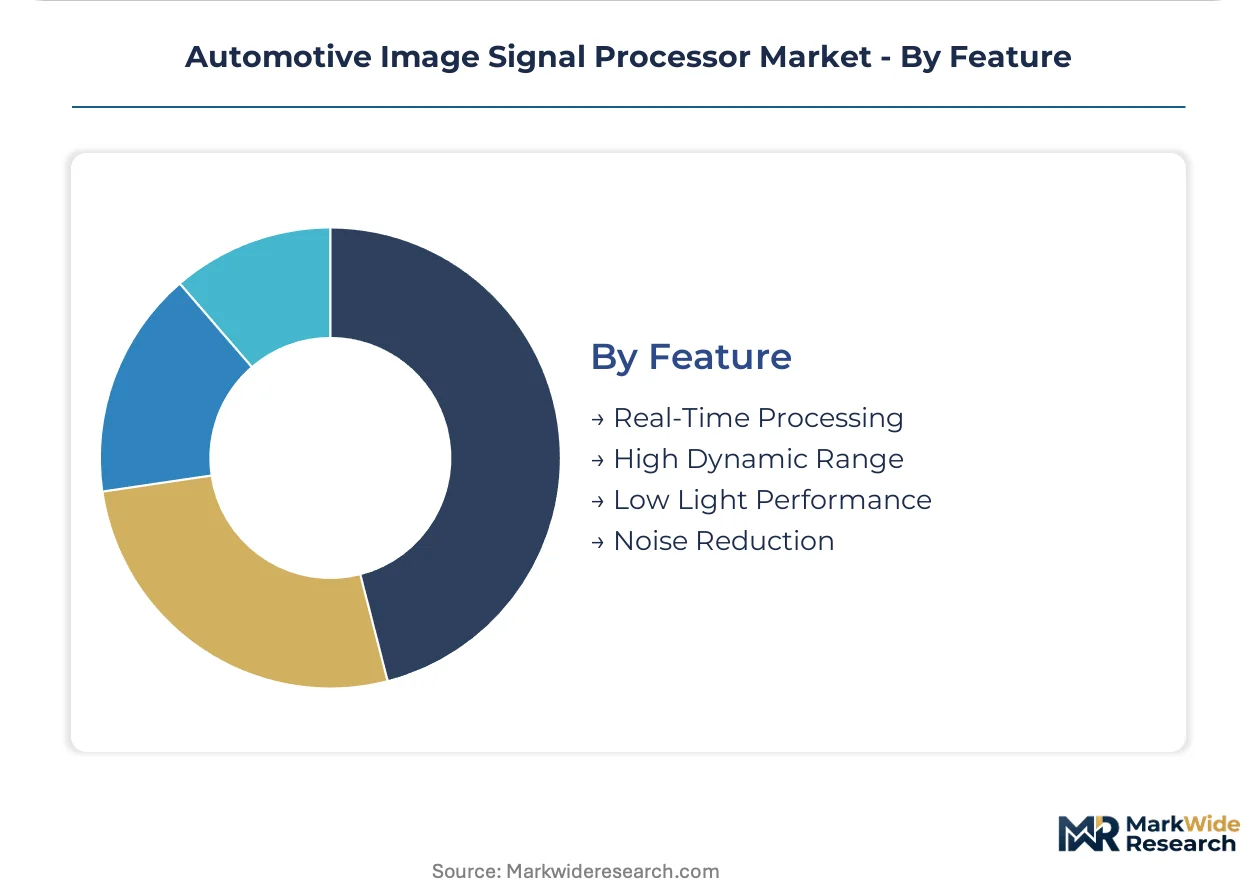
- Real-Time Processing:Sub-50-millisecond latency pipelines enable emergency braking and evasive steering decisions. ISO 26262 ASIL-B and ASIL-D qualifications demand redundant hardware blocks that consume die area and power budgets. Verification matrices expand as ISPs must simultaneously serve human display, machine vision, and data recording paths.
- High Dynamic Range:120-decibel and wider dynamic range capture handles tunnel exit and headlamp glare scenarios without saturation. Night-vision perception stacks in German premium ADAS programs require co-optimized sensor and ISP pipeline design. Thermal management constraints favor lower-power implementations in power-constrained vehicle platforms.
- Low Light Performance:Near-infrared sensitivity enables pedestrian detection under starlight conditions.
- Noise Reduction:Computational denoising preserves detail in high-ISO capture for machine vision training data collection.
Baseline capability is standardizing around Real-Time Processing. Premium differentiation is climbing fastest in High Dynamic Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM procurement of surround-view camera modules concentrates the largest demand share for automotive ISPs, while compliance timelines under UNECE R79 and R157 accelerate hardware refreshes across European premium vehicle lines.
United States
NHTSA's anticipated camera-based automatic emergency braking mandate and robotaxi scaling in California and Arizona drive procurement of 8-megapixel front-camera ISPs. FCC Part 15 emissions certification constrains shielding architectures and extends development cycles for camera-linked systems. Detroit's automotive engineering corridor anchors Tier-1 supplier integration activity for domestic OEM programs.
Germany
BMW, Mercedes-Benz, and Volkswagen negotiate direct semiconductor procurement contracts that bypass established module suppliers for Level 2+ perception stacks. UNECE R79 E-Mark type approval for automated lane-keeping forces hardware upgrades across premium vehicle lines. Stuttgart and Munich host concentrated ISP co-design activity with semiconductor vendors offering sensor-processor integration services.
China
GB/T 39901 mandatory camera-based automatic emergency braking requirements create compliance-driven replacement cycles for domestic and joint-venture vehicle platforms. MIIT oversight of automotive electronics certification shapes hardware architecture decisions. Yangtze River Delta manufacturing clusters in Shanghai and Suzhou concentrate ISP packaging and module assembly investments.
Japan
Toyota, Honda, and Nissan ADAS program rollouts sustain demand for power-constrained edge compute ISPs in front-camera modules. METI industrial policy supports domestic semiconductor supply chain resilience initiatives. Nagoya's automotive engineering corridor anchors Tier-1 supplier coordination for integrated vision system platforms.
South Korea
Hyundai Motor Group and Kia's premium ADAS expansion drives procurement of programmable vision accelerators with embedded neural processing. MFDS regulatory alignment with international functional safety standards shapes qualification timelines for automotive semiconductor vendors. Seoul Capital Area foundry networks control advanced stacked-CMOS wafer supply, creating input dependencies for European and North American fabless designers.
Automotive Image Signal Processor Market Competitive Landscape
Direct semiconductor procurement by vehicle manufacturers dominates the current competitive landscape, unbundling traditional Tier-1 supply relationships and compressing margin pools toward integrated platform providers. The vendor base stratifies across three archetypes: diversified semiconductor conglomerates with automotive verticals, specialized image sensor and processor vendors, and automotive SoC integrators bundling ISP acceleration with domain control. M&A activity and strategic co-design partnerships represent the dominant competitive moves as OEMs seek roadmap control and sensor-processor convergence.
Among diversified semiconductor conglomerates, NXP Semiconductors and Texas Instruments exemplify the integrated platform provider archetype, leveraging vehicle network processor portfolios to capture design-in value. ON Semiconductor occupies a specialist position within the image sensor-processor co-optimization tier, representing vendors that concentrate on CMOS sensor and ISP pipeline convergence for Level 2+ perception stacks.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Texas Instruments |
| ON Semiconductor |
| Intel (Mobileye) |
| Renesas Electronics |
| OmniVision Technologies |
| STMicroelectronics |
| Ambarella |
| Qualcomm Technologies |
| Others |
Pricing and Supply Chain Analysis
Polysilicon wafer spot indices from the Yangtze River Delta cascade through automotive ISP supply chains, compressing margins for fabless designers while concentrating pricing power with integrated foundry-device vendors serving German premium OEM programs.
Pricing Analysis
Volume procurement of mid-range CMOS-based ISPs for Driver Assistance applications generates thin margins, while 8-megapixel autonomous driving silicon with ASIL-D certification commands substantial premiums. Price differentiation rests on functional safety grade and sensor-processor co-design capability. Cost compression in standard-grade ISPs is intensifying because Taiwanese foundry capacity constraints limit supply elasticity. Tier-1 suppliers exhibit highest price sensitivity, while direct OEM procurement shows greater willingness to absorb certification premiums for roadmap control.
Supply Chain Analysis
Single-source vulnerability sits with advanced SiGe and stacked-CMOS wafer fabrication captive to Taiwanese and South Korean foundry networks. Raw material dependencies include 300mm silicon wafers, specialty gases for epitaxial deposition, and advanced packaging substrates. Tariff exposure on semiconductor equipment imports threatens European and North American fabless designers. Distribution runs through direct OEM contracts and Tier-1 module supplier channels, with the former displacing the latter in premium vehicle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive ISP market consolidation is accelerating as ISO 26262 ASIL-D qualification costs and foundry capacity constraints force undercapitalized players toward exit or acquisition.
For Market Incumbents: Acquire embedded vision software engineering teams to address talent scarcity constraining roadmap velocity. Secure captive wafer allocation agreements with South Korean foundries to mitigate single-source exposure. Defensive positioning requires sensor-processor co-design service capabilities as OEMs bypass Tier-1 mediation. For New Entrants and Emerging Players: Aftermarket fleet retrofit providers represent an underserved buyer archetype with relaxed certification requirements and faster procurement cycles. White-space targets include India PLI scheme beneficiaries seeking localized packaging partnerships and commercial vehicle platforms with lower ASIL grades. Go-to-market execution should emphasize rapid electromagnetic compatibility pre-certification to compress customer integration timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized image sensor-ISP co-optimization vendors in South Korea and Japan with proven OEM design wins. Long-term viability hinges on exposure to Level 2+ and autonomous driving program ramps rather than saturated Driver Assistance replacement cycles. Monitor NHTSA camera-based automatic emergency braking mandate progression as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Processor Co-Design Service Launch | Captures OEM direct procurement margin pools bypassing Tier-1 suppliers in German premium programs. |
| ASIL-D Certification Investment | Unlocks 8-megapixel autonomous driving ISP volumes for robotaxi deployments in California and Arizona. |
| India PLI Manufacturing Footprint | Accesses production-linked incentives for automotive electronics packaging in Tamil Nadu clusters. |
| SiGe Architecture R&D Partnership | Preserves near-infrared quantum efficiency while lowering wafer costs for night-vision perception stacks. |
| Cybersecurity Block Pre-Certification | Accelerates UNECE WP.29 R155 compliance timelines for camera-linked ISP integrations. |
Research Methodology
SEC 10-K filings, IHS Markit vehicle production databases, and UNECE WP.29 regulatory bulletins formed the secondary backbone, cross-referenced against primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, and semiconductor foundry planning officers. Bottom-up unit demand estimates triangulated against top-down market value reconstructions across the analysis window.
Historical trendline analysis of CMOS image sensor and automotive SoC pricing informed projection modeling across application, technology, end user, and feature segmentation dimensions. CAGRs derived from weighted average of technology diffusion curves and regulatory compliance timeline assumptions. Forecast inputs included UNECE R79/R157 mandate implementation schedules and robotaxi fleet deployment trajectories.
Revisions become necessary when foundry capacity expansion delays, NHTSA mandate timing shifts, or EU AI Act risk classification enforcement changes materialize. Forecasts reflect documented assumptions about OEM procurement pattern evolution and functional safety certification cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Audio Processor Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Automotive Smart Chip Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
NB-IoT Chipset Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
Processor for Smartphones Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
Europe MPU Market