
 Latin America ERP Software Market | 2026-2036
Latin America ERP Software Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America ERP Software Market Analytics
REACH is decoupling compliance costs from traditional on-premise ERP ownership across Latin American manufacturing exporters. SAP SE leverages deep localization for Brazilian Nota Fiscal eletrônica and Mexican CFDI requirements. Oracle Corporation anchors cloud infrastructure investments in São Paulo and Mexico City data regions. Epicor Software Corporation specializes in discrete manufacturing verticals where ISO traceability intersects with local tax granularity.
Enterprise resource planning software integrates financial, operational, and supply chain data through modular architectures deployed via on-premise servers, cloud instances, or hybrid configurations. Cloud-based deployment is displacing legacy installations as latency improves and data sovereignty frameworks mature. Financial Management applications dominate current revenue pools while Supply Chain Management modules represent the fastest expansion corridor as nearshoring reshapes regional logistics networks.
Brazil's Receita Federal, Mexico's SAT, and Colombia's DIAN each enforce electronic invoicing standards that mandate real-time ERP connectivity. These tax authority protocols shape product roadmaps by requiring certified digital signatures, automated ledger synchronization, and audit-ready transaction trails. Stakeholders must monitor regulatory divergence across Andean, Mercosur, and Pacific Alliance blocs when architecting multi-country rollouts.
Market Dynamics
Mandatory electronic invoicing regimes across Brazil, Mexico, and Colombia are forcing wholesale ERP replacements as legacy systems fail real-time tax authority connectivity requirements. Cloud-native architectures displace on-premise installations where latency and data sovereignty frameworks have matured sufficiently for enterprise workloads.
Growth Catalysts
- Nota Fiscal eletrônica mandates:Brazil's Receita Federal requires certified digital signatures and automated ledger synchronization, compelling manufacturers to upgrade financial management modules.
- Nearshoring logistics networks:Supply chain visibility investments accelerate as multinational firms relocate production to Mexican industrial corridors serving North American demand.
- ISO traceability requirements:Discrete manufacturers in automotive and aerospace verticals deploy ERP systems integrating quality management with granular tax compliance workflows.
Market Restraints
- Data sovereignty compliance:Brazil's LGPD and Mexico's data localization rules fragment cloud infrastructure architectures, raising operational complexity for regional rollouts.
- Skilled implementation labor scarcity:SAP and Oracle-certified consultants concentrate in São Paulo and Mexico City, creating bottlenecks for mid-market deployments in secondary cities.
- Legacy system technical debt:Decades-old AS/400 and mainframe installations in Argentine and Chilean enterprises resist modular API-based integration without costly middleware layers.
Strategic Opportunities
- Andean underpenetration:Peru, Ecuador, and Bolivia exhibit ERP adoption rates below regional averages, particularly among mining and agricultural exporters requiring supply chain modules.
- AI-driven predictive analytics:Machine learning modules for demand forecasting and inventory optimization represent whitespace as cloud data lakes accumulate sufficient transaction volumes.
- Pacific Alliance regulatory harmonization:Chile, Colombia, Mexico, and Peru's trade bloc creates cross-border ERP standardization opportunities for multinational implementations.
Industry Challenges
- Multi-authority certification timelines:Separate approvals from Brazil's Receita Federal, Mexico's SAT, and Colombia's DIAN delay product launches by 8-14 months for new entrants.
- Hybrid integration complexity:Manufacturers maintaining on-premise production systems alongside cloud financial modules face real-time synchronization failures during peak transaction periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America ERP Software Market |
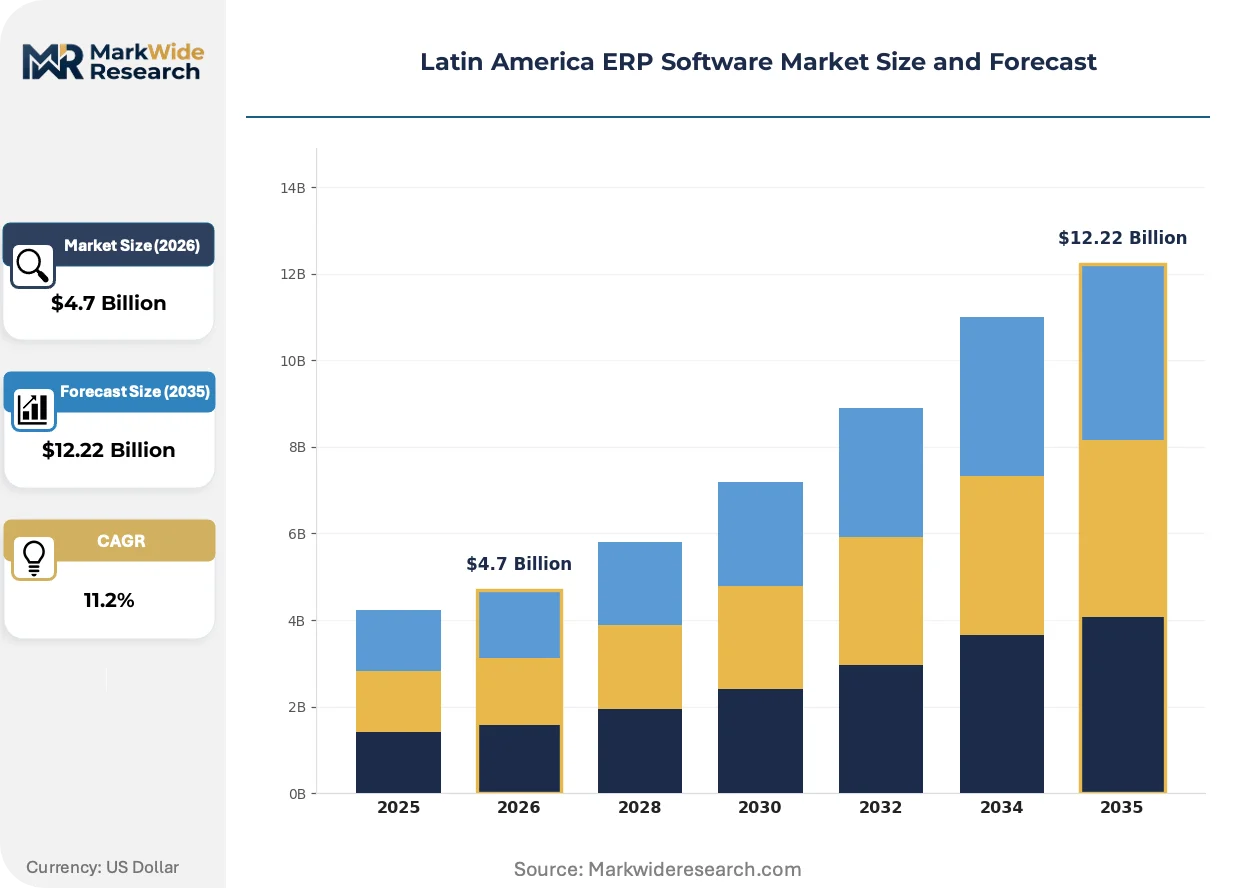
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.22 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services End User: SMEs, Large Enterprises, Government, Non-Profit Organizations Industry Vertical: Manufacturing, Retail, Healthcare, Construction Application: Financial Management, Supply Chain Management, Human Resource Management, Customer Relationship Management |
| Companies Covered | Infor Inc., Epicor Software Corporation, SAP SE, Unit4 N.V., IFS AB, Oracle Corporation, Sage Group plc, Rockwell Automation, Microsoft Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America ERP Software Market Evolving Landscape
Cloud-native ERP architectures are displacing legacy installations as latency improvements and sovereign data frameworks mature across the region. Three concurrent developments reshape competitive positioning and buyer expectations.
Artificial intelligence is converging with embedded ERP workflows to automate tax classification, fraud detection, and cash flow forecasting. Mid-market manufacturers in Brazilian automotive clusters adopt these capabilities fastest, compressing the traditional 18-month implementation cycle to under six months for standardized deployments.
Mexico's SAT electronic invoicing mandates now require real-time CFDI 4.0 connectivity with automated ledger synchronization. This regulatory tightening forces legacy system replacements among SME distributors and retailers, with compliance deadlines accelerating procurement decisions previously deferred due to budget constraints.
Subscription-based pricing models displace perpetual licenses as Brazilian and Mexican CFOs prioritize operational expenditure treatment over capital allocation. Channel partners in São Paulo and Mexico City now lead with consumption-based arrangements, unbundling implementation services from software access to reduce upfront commitment thresholds for mid-market prospects.
Latin America ERP Software Market Segmentation
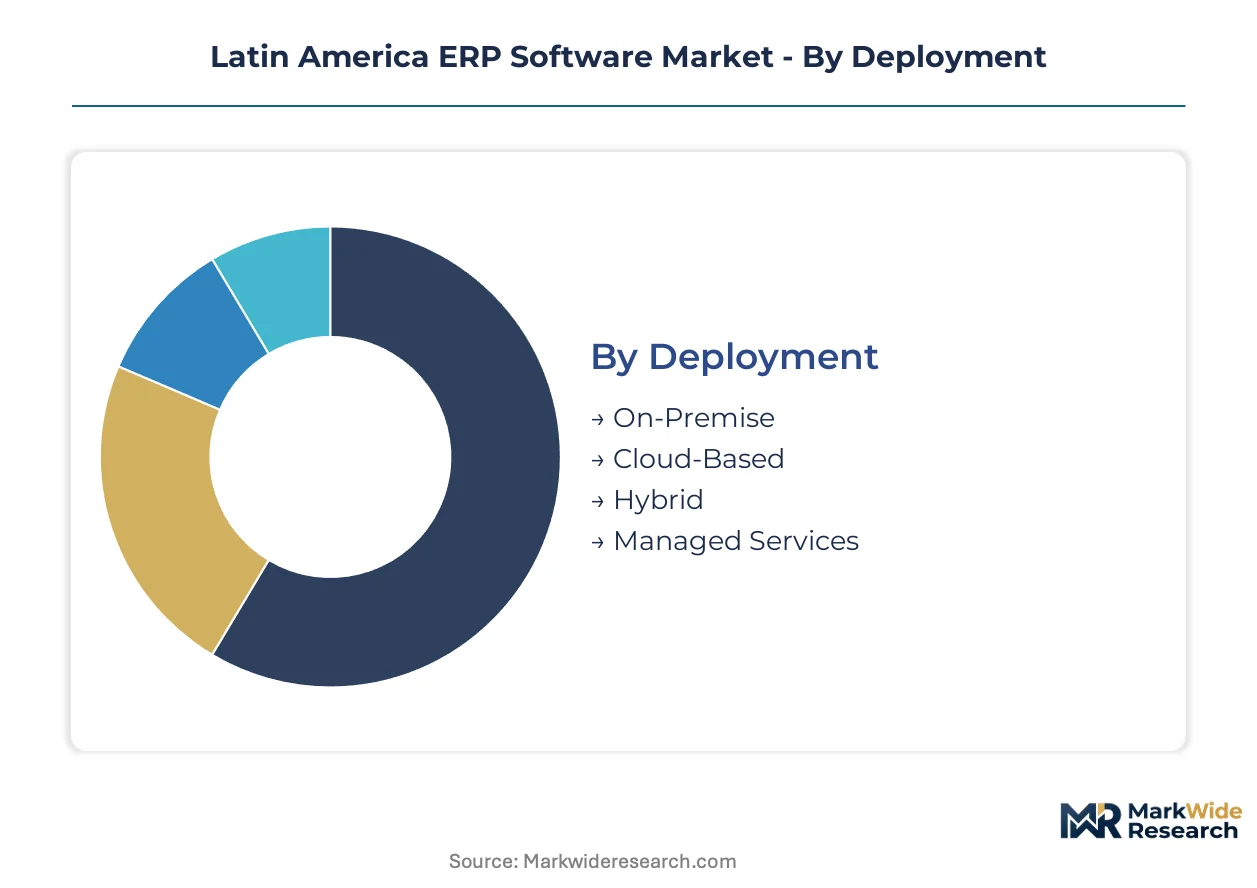
ERP segmentation in Latin America reflects divergent modernization pressures across deployment architectures, organizational scales, and compliance-intensive verticals. Tax authority mandates and cloud infrastructure maturity create asymmetric growth patterns that vendors must navigate through targeted module configurations.
Deployment:
The customization-vs-standardization spectrum spans from fully configurable on-premise installations to standardized multi-tenant cloud instances with limited localization flexibility.
- Cloud-Based:Multi-tenant architectures with automated updates and regional data residency options. Demand concentrates among Brazilian manufacturers modernizing Nota Fiscal eletrônica compliance while avoiding capital expenditure recognition. São Paulo industrial clusters adopt fastest where fiber latency supports real-time tax authority connectivity.
- On-Premise:Dedicated infrastructure with full customization control over tax rule engines and legacy system integration. Argentine and Chilean enterprises with AS/400 dependencies maintain this model due to middleware replacement costs and data sovereignty preferences.
- Hybrid:Split architectures retaining on-premise production systems alongside cloud financial modules. Mexican automotive suppliers deploy this configuration to balance SAT CFDI compliance with shop-floor system isolation.
- Managed Services:Third-party operated infrastructure with vendor-managed security patches and compliance updates. Mid-market Colombian distributors favor this model to overcome internal IT capacity constraints.
Leading the category by volume: Cloud-Based. Growing fastest: Managed Services.
End User:
Cost tier segmentation separates capital-rich multinational implementations from operational-expenditure-constrained domestic deployments.
- Large Enterprises:Complex multi-entity rollouts requiring granular tax localization across Mercosur and Pacific Alliance jurisdictions. Brazilian conglomerates with cross-border operations drive module standardization investments.
- SMEs:Rapid-deployment configurations with pre-configured industry templates and subscription pricing. Mexican distributors responding to SAT electronic invoicing deadlines represent the fastest expansion corridor.
- Government:Procurement-heavy implementations with transparency and audit trail mandates. Colombian and Peruvian public sector digitization programs create demand concentration.
- Non-Profit Organizations:Donor reporting and grant compliance modules with simplified financial management. Adoption lags commercial sectors due to budget fragmentation across multiple funding sources.
Dominant by implementation value: Large Enterprises. Expanding most quickly: SMEs.
Industry Vertical:
Application intensity varies by regulatory exposure and supply chain complexity across production and service sectors.
- Manufacturing:Deep integration of ISO traceability, quality management, and automated tax compliance workflows. Brazilian automotive and aerospace clusters deploy these systems to satisfy export certification and Receita Federal reporting simultaneously.
- Retail:Omnichannel inventory synchronization with real-time electronic invoicing at point of sale. Mexican retail chains upgrading for SAT CFDI 4.0 mandates drive replacement cycles.
- Healthcare:Patient billing integration with pharmaceutical supply tracking and ANVISA compliance in Brazil. Hospital networks in São Paulo and Mexico City lead adoption.
- Construction:Project-based cost accounting with subcontractor payment transparency and labor law compliance. Colombian infrastructure investment cycles create demand concentration.
Highest module penetration: Manufacturing. Steepest expansion trajectory: Retail.
Application:
Maturity gradients separate established financial modules from emerging predictive capabilities across functional domains.
- Financial Management:Core general ledger, accounts payable, and tax compliance engines with certified digital signature integration. Brazilian Nota Fiscal eletrônica and Mexican CFDI requirements make this the non-negotiable foundation for all deployments.
- Supply Chain Management:Inventory optimization, logistics visibility, and supplier collaboration portals. Nearshoring investments in Mexican industrial corridors accelerate adoption fastest as multinationals demand real-time shipment tracking.
- Human Resource Management:Payroll automation with local labor law compliance and benefits administration. Standardized across large enterprise deployments but underpenetrated in mid-market segments.
- Customer Relationship Management:Sales force automation and service ticketing with embedded analytics. Often deployed as standalone solutions rather than integrated ERP modules in Latin American markets.
Widest installed base: Financial Management. Gaining share fastest: Supply Chain Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives concentrate electronics manufacturing, generating ERP demand for inventory traceability and export compliance automation across northern Brazil.
Brazil
São Paulo automotive clusters drive cloud ERP adoption for Nota Fiscal eletrônica compliance. ANVISA pharmaceutical tracking mandates force serialization upgrades in Osasco industrial corridors. Receita Federal certification timelines delay product launches by 8-14 months for new market entrants.
Mexico
Nuevo León nearshoring investments accelerate supply chain module procurement. SAT CFDI 4.0 electronic invoicing deadlines compel SME distributors to replace legacy systems. Mexico City data regions anchor Oracle and Microsoft cloud infrastructure investments serving North American logistics networks.
Colombia
Bogotá infrastructure investment cycles create construction ERP demand for project cost transparency. DIAN electronic invoicing standards mandate real-time connectivity for mid-market distributors. Pacific Alliance regulatory harmonization enables cross-border template standardization with Chilean and Peruvian operations.
Argentina
Buenos Aires manufacturing retains AS/400 dependencies due to middleware replacement costs and currency volatility. AFIP tax authority protocols require certified digital signatures for export documentation. Córdoba automotive suppliers face skilled SAP consultant scarcity delaying implementation timelines.
Chile
Santiago mining exporters underpenetrate supply chain modules relative to regional averages. SII electronic tax document mandates push cloud migration among copper concentrate traders. Antofagasta port logistics operators invest in inventory optimization for Asia-Pacific shipment scheduling.
Latin America ERP Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architecture and vertical depth dimensions. SAP SE and Oracle Corporation anchor the consolidated tier through localization investments in São Paulo and Mexico City data regions. Mid-market specialists concentrate on discrete manufacturing workflows where ISO traceability intersects with granular tax compliance. Strategic moves emphasize cloud infrastructure regionalization and channel partner certification programs to overcome skilled implementation labor scarcity.
Among Germany-based enterprise software conglomerates, SAP SE exemplifies deep localization archetypes through Brazilian Nota Fiscal eletrônica and Mexican CFDI compliance engines. Epicor Software Corporation and Infor Inc. occupy positions within manufacturing-focused specialists, serving automotive and aerospace clusters where quality management modules integrate with tax authority protocols. Oracle Corporation anchors cloud-native infrastructure investments, representing the scale-driven platform play competing through latency-optimized data regions.
| Leading Market Players |
|---|
| Infor Inc. |
| Epicor Software Corporation |
| SAP SE |
| Unit4 N.V. |
| IFS AB |
| Oracle Corporation |
| Sage Group plc |
| Rockwell Automation |
| Microsoft Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up channel partners in São Paulo and Mexico City concentrate ERP distribution, creating pricing discipline through bundled implementation services and certified consultant scarcity. Subscription-based SaaS models displace perpetual licenses as Brazilian and Mexican CFOs prioritize operational expenditure treatment, compressing upfront commitment thresholds while elongating vendor revenue recognition timelines.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with accelerated SAT CFDI 4.0 compliance deployments commanding premiums for manufacturers facing regulatory deadlines. Price differentiation hinges on certification level for Brazilian Nota Fiscal eletrônica and Mexican CFDI protocols, plus geographic delivery cost for Andean implementations. Cost compression in mid-market segments is intensifying because SAP and Oracle-certified consultant scarcity inflates implementation labor rates. SME distributors in Mexican industrial corridors exhibit highest price sensitivity, while large Brazilian conglomerates with cross-border Mercosur operations demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with São Paulo and Mexico City as the dominant concentration points for SAP and Oracle-certified implementation consultants, creating bottlenecks for regional rollouts. Geographic supply concentration spans Brazil, Mexico, and Colombia as primary demand centers, with secondary expansion into Chilean mining and Peruvian agricultural exporters. Raw material dependencies include cloud infrastructure from hyperscaler data regions, localization code libraries for tax authority protocols, and ISO-certified quality management modules. Regulatory restriction risk manifests through multi-authority certification timelines from Brazil's Receita Federal, Mexico's SAT, and Colombia's DIAN delaying product launches. Distribution runs through value-added resellers and system integrators with vertical specialization in discrete manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled SAP and Oracle-certified consultant scarcity props pricing power for implementation services, constraining vendor capacity to serve mid-market expansion demand across secondary Latin American cities.
For Market Incumbents: Cement localization moats through accelerated Receita Federal and SAT certification investments ahead of regulatory tightening cycles. Deepen channel control by acquiring boutique system integrators in Bogotá and Santiago to preempt emerging pure-play cloud specialists from capturing Andean market share. For New Entrants and Emerging Players: Launch via managed services distribution to overcome internal IT capacity constraints among mid-market Colombian distributors and Peruvian mining exporters. Target underpenetrated supply chain management modules in Chilean copper concentrate trading and Ecuadorian agricultural logistics as the most penetrable whitespace. For Investors and Strategic Acquirers: Pacific Alliance regulatory harmonization announcements are the leading indicator that cross-border ERP standardization opportunities will concentrate acquisition value in multinational implementation specialists. Long-term viability favors platform-agnostic managed services providers with certified compliance engines across Brazilian, Mexican, and Colombian tax authority protocols. Watch for DIAN electronic invoicing mandate expansions beyond current mid-market thresholds as the signal for accelerated replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Regionalization | Oracle and Microsoft data regions in São Paulo and Mexico City reduce latency for real-time SAT CFDI connectivity. |
| Tax Authority Certification Acceleration | Pre-certified Nota Fiscal eletrônica and CFDI 4.0 engines compress 8-14 month approval timelines for new entrants. |
| Channel Partner Certification Programs | SAP and Oracle consultant pipelines in secondary cities address skilled implementation labor scarcity constraining mid-market growth. |
| AI-Driven Predictive Module Launch | Machine learning demand forecasting in Brazilian automotive clusters leverages accumulated cloud data lake transaction volumes. |
| Vertical Manufacturing Specialist Acquisition | Epicor and Infor positions in aerospace ISO traceability integrate with granular tax compliance workflows for export certification. |
Research Methodology
Document review covered SEC filings from SAP SE and Oracle Corporation, ANVISA pharmaceutical tracking mandates, and Receita Federal certification protocols, complemented by interviews with ERP implementation consultants, Brazilian manufacturing CIOs, Mexican SAT compliance officers, and Colombian system integrators. Secondary validation drew from customs data on software licensing imports, hyperscaler data region capex disclosures, and Pacific Alliance regulatory harmonization frameworks. Bottom-up deployment model estimates triangulated against top-down market sizing from cloud infrastructure expansion patterns.
Segment-level outputs across deployment architecture, organization scale, and compliance-intensive verticals fed into analytical framework spanning the projection horizon. CAGRs derived from cloud migration velocity in São Paulo industrial clusters, SAT electronic invoicing mandate compliance deadlines, and nearshoring logistics network investments in Nuevo León. Industry-specific inputs included Receita Federal certification timeline distributions and ISO traceability module adoption curves in Brazilian automotive exporters.
Regulatory divergence across Mercosur, Pacific Alliance, and Andean blocs, currency volatility in Argentine implementations, and cloud infrastructure latency constraints in secondary cities are the dominant revision risks to modeled assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Stock Media Software Market
Software & Services
Performance Management Software Market
Software & Services
Drone Mapping Software Market
Software & Services
Medical Equipment Repair Software Market
Software & Services
Discount Management Software Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
North America Deck Design Software Market
Software & Services
PLM Software Market
Software & Services
Middle East and Africa Workforce Management Software Market
Software & Services
Expense Management Software Market
Software & Services
Asia Pacific Content Services Platform Market
Software & Services
Global Calendar Scheduling Software Market
Software & Services
Visitor Identification Software Market
Software & Services
North America Enterprise Resource Planning Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
Cloud-Based Dental Practice Management Software Market