
 Embedded Hypervisor Market | 2026-2036
Embedded Hypervisor Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Hypervisor Market Intelligence
Asset-light licensing and subscription-based commercial models are reshaping competitive entry in embedded virtualization. Wind River Systems, Inc. sustains its position through deep aerospace and defense certification heritage. Microsoft Corporation leverages its Azure Sphere and cloud-edge integration stack to extend into IoT gateway virtualization. Green Hills Software differentiates through INTEGRITY-178B safety-critical certifications that anchor high-assurance segments.
An embedded hypervisor is a thin software abstraction layer that enables multiple isolated operating systems to execute concurrently on a single processor or SoC, typically with deterministic interrupt latency below 50 microseconds and hardware-assisted virtualization extensions such as ARM TrustZone or Intel VT-x. Its primary purpose is to consolidate heterogeneous workloads—combining real-time control with general-purpose compute—onto unified hardware in resource-constrained environments. Bare-metal hypervisors capture the dominant margin pool in automotive and aerospace deployments where determinism and certification rigor command premium positioning. Containerization is displacing traditional full virtualization in telecommunications NFV infrastructure, driven by lower overhead and faster instantiation cycles for network edge nodes.
FAA DO-178C and EU EASA certification requirements govern aerospace hypervisor deployments, while NHTSA FMVSS guidelines and ISO 26262 ASIL ratings shape automotive product development timelines and qualification costs. The EU Cyber Resilience Act introduces mandatory security update obligations that will force hypervisor vendors to rearchitect long-term support models for embedded devices with decade-long service lives. Stakeholders must decide whether to build in-house virtualization stacks or absorb third-party licensing costs as regulatory compliance complexity outpaces generic open-source alternatives.
Market Dynamics
Automotive OEMs are consolidating multiple electronic control units onto single SoCs using hypervisor-based virtualization, driven by EU Cyber Resilience Act mandates and ISO 26262 functional safety requirements that compress hardware diversity while expanding software complexity.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory security update obligations for connected devices with decade-long service lives force hypervisor vendors to architect long-term support frameworks, expanding recurring revenue pools.
- Automotive ECU consolidation:Virtualized platforms reduce hardware count by 40-60% in next-generation vehicle architectures, cutting bill-of-materials costs while enabling over-the-air update capabilities.
- Hardware-assisted virtualization:ARM TrustZone and Intel VT-x extensions now standard in automotive-grade SoCs from NXP and Renesas, lowering deterministic latency barriers below 50 microseconds.
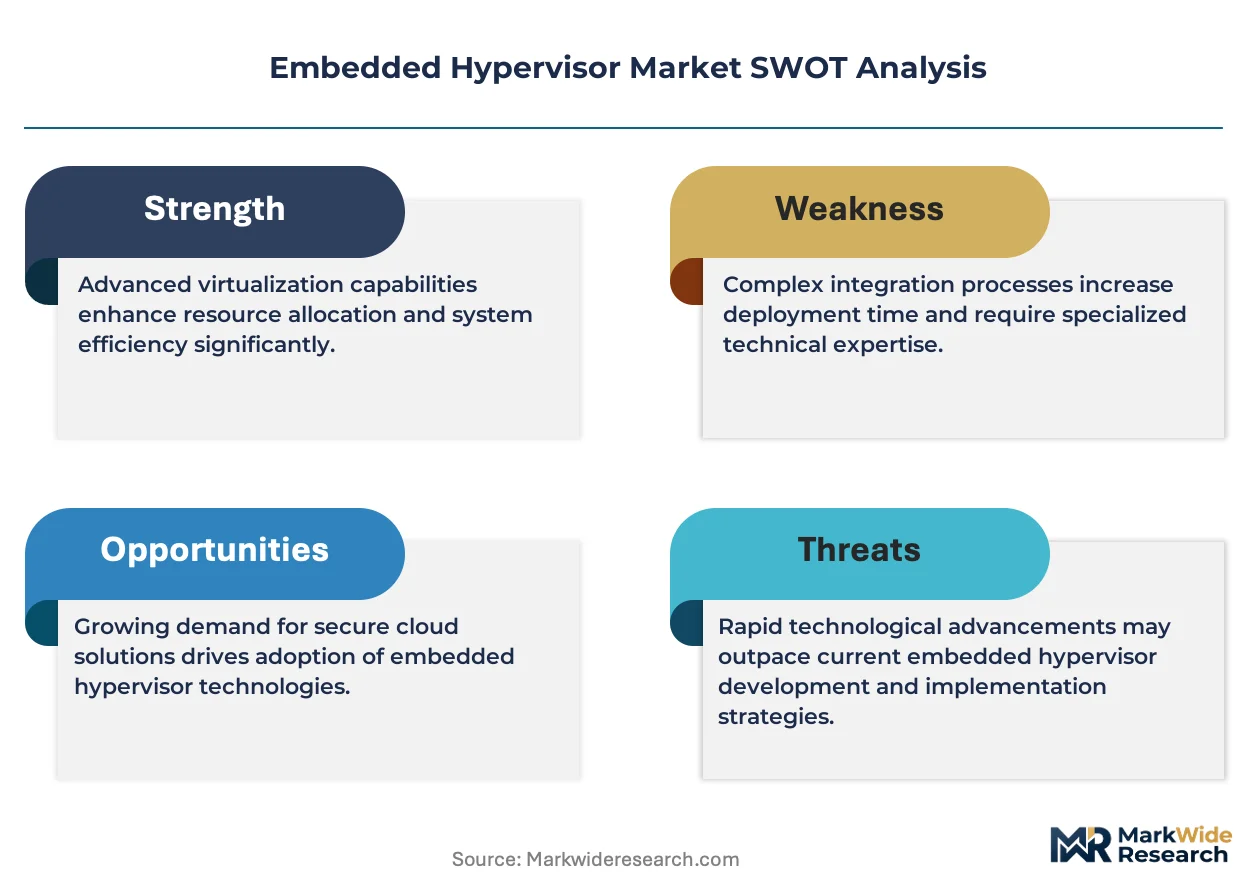
Market Restraints
- Certification cost structure:FAA DO-178C and EU EASA qualification timelines extend 18-36 months, absorbing 15-25% of development budgets for aerospace hypervisor deployments.
- Silicon supply concentration:Automotive-grade SoC fabrication concentrates at TSMC and Samsung foundries in Taiwan and South Korea, creating single-source vulnerability for virtualization-enabled hardware.
- Containerization substitution:Kubernetes-based container runtimes displace full virtualization in telecommunications NFV infrastructure, capturing network edge workloads with lower overhead.
Strategic Opportunities
- India automotive electronics:PLI scheme incentives for electric vehicle manufacturing create demand for localized hypervisor integration in battery management and motor control systems.
- Medical device convergence:IEC 62304 software lifecycle standards intersect with hypervisor isolation requirements, enabling mixed-criticality imaging and patient monitoring on unified hardware platforms.
- Cloud-edge orchestration:Azure Sphere and AWS IoT Greengrass integration patterns extend hypervisor management from device to cloud, creating subscription-based operational technology services.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D certified engineers command 40-60% salary premiums, constraining vendor scaling in automotive qualification programs.
- Legacy RTOS integration friction:Decades-old proprietary real-time operating systems in industrial automation resist containerized migration, requiring custom paravirtualization layers.
- Cross-certification complexity:Simultaneous FAA DO-178C and EU EASA approvals demand redundant documentation streams, diluting engineering resources across divergent audit frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Hypervisor Market |
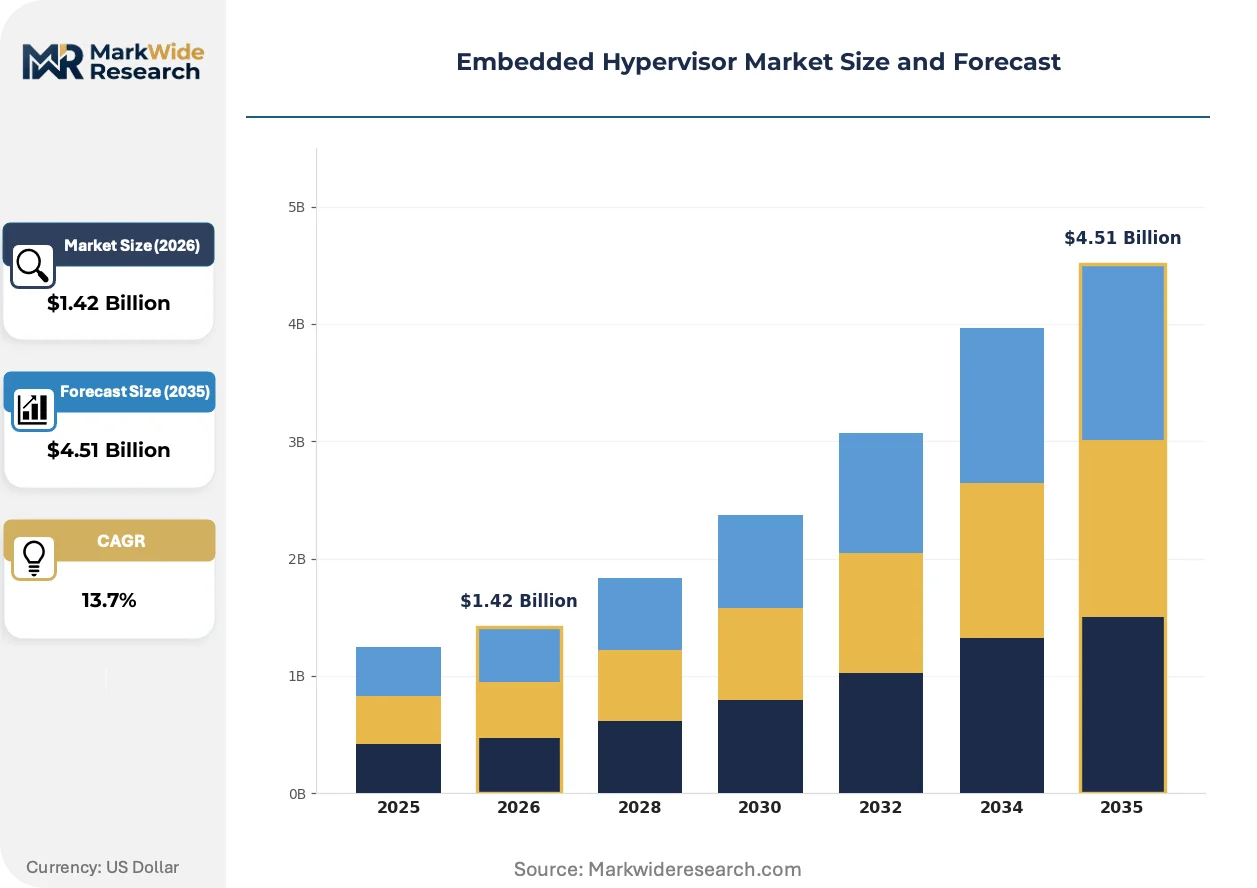
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type 1 Hypervisor, Type 2 Hypervisor, Bare-metal Hypervisor, Hosted Hypervisor Technology: Virtual Machine Monitor, Paravirtualization, Full Virtualization, Containerization End User: Automotive Systems, Aerospace Applications, Industrial Control, Telecommunications Application: Network Functions Virtualization, IoT Gateways, Cloud Infrastructure, Real-Time Systems |
| Companies Covered | Microsoft Corporation, Lynx Software Technologies, VMware, Inc, Thales Group, NXP Semiconductors, Wind River Systems, Inc., Citrix Systems, Inc., Green Hills Software, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Hypervisor Market Strategic Shifts & Innovations
Virtualization architectures are bifurcating between safety-critical bare-metal deployments and cloud-native containerized stacks, with regulatory mandates forcing convergence on common certification frameworks across automotive, aerospace, and industrial verticals.
Bare-metal hypervisors are migrating from proprietary closed-source implementations to certifiable open-source foundations. Wind River and Green Hills now contribute to Xen Project and seL4 microkernel initiatives to reduce customer qualification burden. Automotive Tier-1 suppliers adopt these pre-certified bases for domain controller consolidation, compressing time-to-market for mixed-criticality platforms by 12-18 months.
EU Cyber Resilience Act enforcement beginning in 2027 imposes mandatory vulnerability disclosure and security update obligations on all connected embedded devices. Hypervisor vendors must rearchitect decade-long support models, shifting from perpetual licenses to subscription-based maintenance contracts. Germany's KBA and France's ANSM align national type approval processes with these EU-wide mandates, accelerating compliance investments among Munich and Stuttgart automotive electronics clusters.
Buyer procurement patterns favor outcome-based certification packages over discrete software licenses. OEMs now contract hypervisor vendors for complete ASIL-D or DO-178C qualification evidence rather than bare software binaries. This bundling compresses vendor margins while extending customer lock-in through integrated safety case documentation, most visible in German automotive procurement where BMW and Mercedes-Benz mandate turnkey certification deliverables.
Embedded Hypervisor Market Segmentation
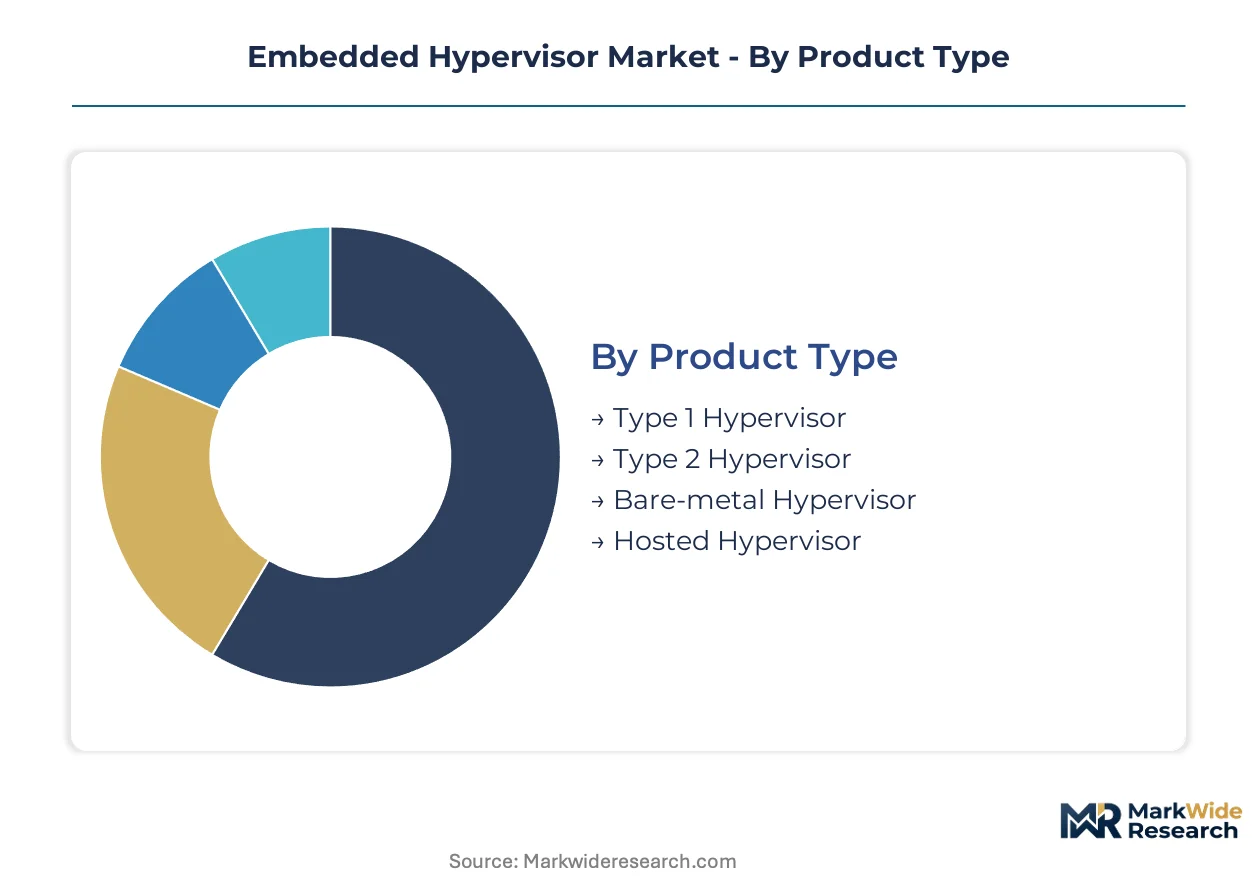
Embedded hypervisor segmentation reveals how architectural choices map onto certification requirements and hardware abstraction layers. Product type and technology selections determine whether deployments qualify for automotive ASIL-D ratings or aerospace DO-178C approval.
Product Type:
Cost tier separation between bare-metal implementations and hosted alternatives drives procurement decisions across safety-critical and general-purpose workloads.
- Bare-metal Hypervisor:Executes directly on processor hardware without intervening host operating system, achieving deterministic interrupt latency below 50 microseconds. Automotive domain controllers in Germany's Stuttgart electronics corridor demand this architecture for ISO 26262 ASIL-D qualification.
- Type 1 Hypervisor:Native virtualization layer with direct hardware access and minimal overhead footprint. Aerospace avionics suppliers prioritize this category for FAA DO-178C certification pathways in fly-by-wire and mission-critical systems.
- Type 2 Hypervisor:Runs atop conventional operating systems, trading performance for deployment flexibility. Development and simulation environments favor this approach where certification rigor is relaxed.
- Hosted Hypervisor:Relies on underlying general-purpose OS for hardware abstraction, limiting real-time determinism. Non-critical IoT gateway prototyping and edge analytics workloads tolerate this overhead.
Bare-metal Hypervisor holds installed capacity. Containerization is rotating up the share rankings.
Technology:
Application requirements for isolation strength versus instantiation speed determine which virtualization mechanism dominates specific end-use deployments.
- Full Virtualization:Complete hardware emulation enables unmodified guest operating systems to execute in isolated partitions. Medical device manufacturers in Switzerland leverage this for IEC 62304-compliant mixed-criticality platforms combining imaging and patient monitoring.
- Containerization:OS-level isolation delivers sub-second startup and minimal memory footprint compared to full VM instantiation. Telecommunications NFV infrastructure across South Korea's 5G edge nodes adopts this for network function elasticity.
- Paravirtualization:Modified guest kernels cooperate with hypervisor through explicit hypercalls, reducing overhead versus full emulation. Legacy industrial automation systems in Japan's METI-funded smart factory initiatives require this for proprietary RTOS integration.
- Virtual Machine Monitor:Core abstraction layer managing CPU, memory, and I/O allocation across concurrent guests. Foundational to all other virtualization implementations regardless of isolation mechanism.
Full Virtualization holds installed capacity. Containerization is rotating up the share rankings.
End User:
Customer type differentiation separates safety-critical verticals with decade-long certification cycles from commercial deployments with faster refresh rates.
- Automotive Systems:ECU consolidation platforms integrating powertrain, chassis, and infotainment domains onto single SoCs. India's PLI scheme for electric vehicle manufacturing is accelerating localized hypervisor integration in battery management systems.
- Aerospace Applications:Flight control, avionics, and mission computers requiring deterministic scheduling and fault containment. EU EASA and FAA dual certification demands absorb substantial engineering resources.
- Industrial Control:Factory automation and process control systems mixing real-time PLCs with supervisory HMI workloads. France's ANSM-aligned medical device regulations intersect here for diagnostic equipment.
- Telecommunications:Baseband processing, edge routing, and network function virtualization at 5G infrastructure scale. South Korea's MFDS and national telecom regulators shape deployment standards.
Automotive Systems holds installed capacity. Containerization is rotating up the share rankings.
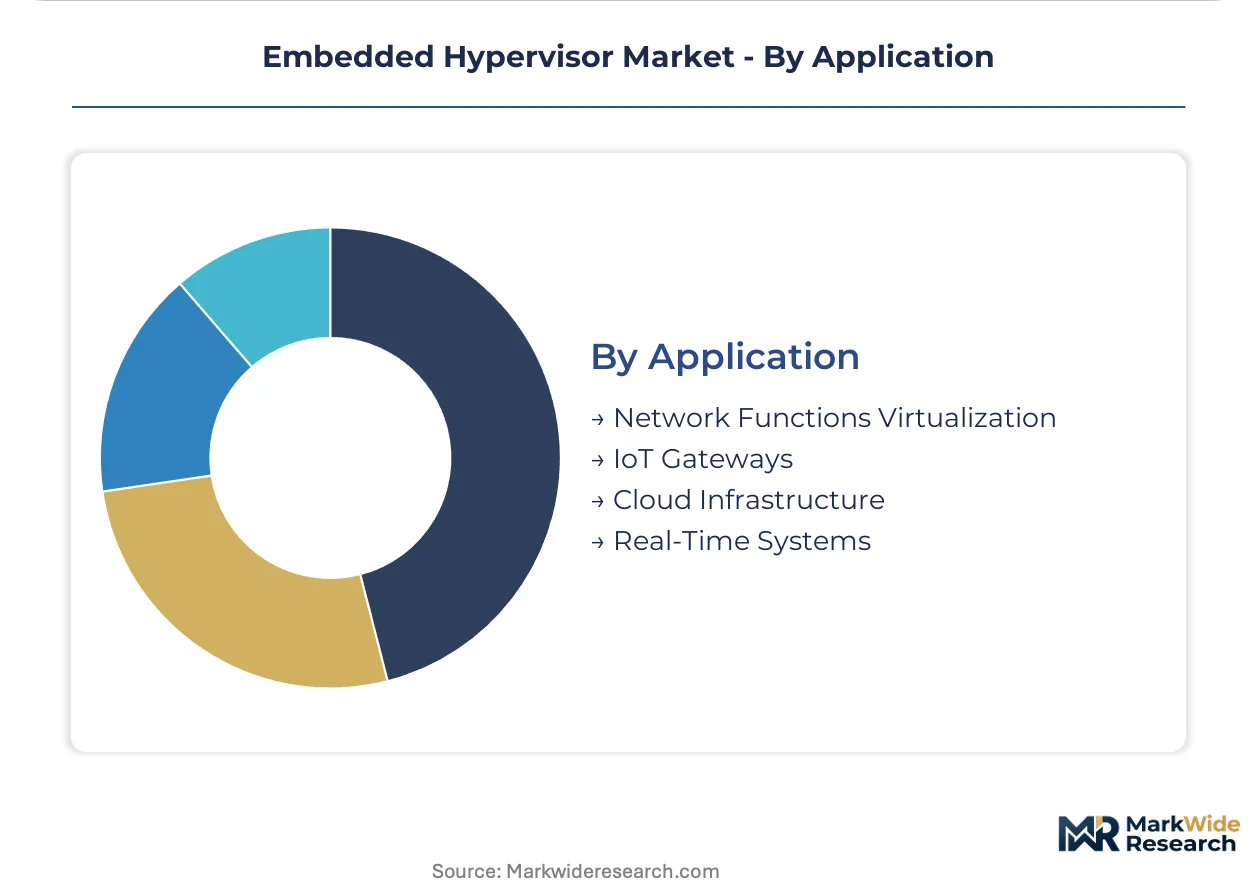
Application:
Volume concentration in cloud-edge orchestration versus latency-constrained real-time systems determines pricing and support model structures.
- Real-Time Systems:Deterministic response guarantees for robotics, autonomous vehicles, and safety interlocks. Germany's KBA type approval mandates shape automotive procurement specifications.
- IoT Gateways:Edge aggregation points bridging sensor networks to cloud backends. Microsoft's Azure Sphere integration patterns dominate this category.
- Network Functions Virtualization:Software-defined replacement for proprietary network appliances. Container runtimes are displacing full virtualization here.
- Cloud Infrastructure:Hyperscale data center virtualization underlying elastic compute services. Distinct from embedded deployments but shares foundational hypervisor technology.
Real-Time Systems holds installed capacity. IoT Gateways is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs extract 40-60% hardware consolidation savings through hypervisor deployments, while Indian PLI scheme incentives compress entry pricing for battery management virtualization by comparable margins.
United States
NHTSA FMVSS guidelines and FAA DO-178C certification requirements govern automotive and aerospace deployments respectively. The country's national automotive safety regulator mandates deterministic interrupt latency below 50 microseconds for autonomous vehicle platforms. Detroit's automotive electronics corridor concentrates Tier-1 supplier engineering centers where virtualized ECU consolidation accelerates.
Germany
KBA type approval processes align with EU Cyber Resilience Act mandates for decade-long security update obligations. The country's federal motor transport authority enforces ISO 26262 ASIL-D ratings for mixed-criticality domain controllers. Munich and Stuttgart anchor Europe's densest automotive electronics cluster, where BMW and Mercedes-Benz procurement teams mandate turnkey certification deliverables.
India
PLI scheme incentives for electric vehicle manufacturing create localized demand for battery management and motor control virtualization. The country's central automotive regulator harmonizes with BIS standards for embedded software lifecycle management. Tamil Nadu and Maharashtra host expanding automotive electronics manufacturing zones where hypervisor integration penetrates Tier-2 supplier networks.
Japan
METI-funded smart factory initiatives drive proprietary RTOS paravirtualization for legacy industrial automation systems. The country's ministry of economy, trade and industry coordinates JIS standards alignment with IEC 62304 for medical device convergence. Nagoya's Chubu industrial corridor concentrates robotics manufacturers deploying deterministic hypervisor isolation for safety interlocks.
South Korea
MFDS and national telecom regulators shape 5G edge node deployment standards for network function virtualization. The country's ministry of food and drug safety intersects with medical device software requirements for mixed-criticality imaging platforms. Seoul Capital Area hosts telecommunications infrastructure providers where container runtimes displace full virtualization at network edge scale.
Embedded Hypervisor Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower certification scope. The vendor base concentrates around three archetypes: aerospace heritage suppliers with DO-178C pedigree, cloud-edge extenders leveraging hyperscaler infrastructure, and safety-critical pure-plays anchoring ASIL-D qualification. Consolidation pressure intensifies through outcome-based procurement bundling and strategic licensing partnerships that compress discrete software margins.
Among established platform vendors, Microsoft Corporation exemplifies cloud-edge integration archetypes extending from Azure Sphere into IoT gateway virtualization. Wind River Systems, Inc. occupies a position within aerospace heritage tier, while Green Hills Software anchors the safety-critical pure-play segment through INTEGRITY-178B certification lineage. These three represent divergent strategic postures on subscription versus perpetual licensing, certification burden absorption, and vertical market concentration.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Lynx Software Technologies |
| VMware, Inc |
| Thales Group |
| NXP Semiconductors |
| Wind River Systems, Inc. |
| Citrix Systems, Inc. |
| Green Hills Software |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
Single-source dependency on TSMC and Samsung foundries for automotive-grade SoCs compresses margin buffers across certification tiers while forcing buyers into long-term offtake commitments that reshape working capital structures. This concentration amplifies price spreads between bare-metal safety-critical platforms and hosted alternatives, with procurement teams absorbing qualification cost premiums upfront to secure silicon allocation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification burden separates ASIL-D qualified bare-metal licenses from development-grade hosted alternatives, while subscription-based maintenance contracts displace perpetual licenses under EU Cyber Resilience Act mandates. Cost compression in standard-tier automotive integrations intensifies as Tier-1 suppliers bundle certification deliverables into turnkey packages. Battery management system OEMs in India exhibit highest price sensitivity, whereas aerospace avionics suppliers tolerate premium positioning for DO-178C pedigree.
Supply Chain Analysis
Extended payment terms from automotive OEMs strain Tier-2 hypervisor vendor cash cycles, accelerating supply-chain finance facility adoption. Silicon fabrication concentrates in Taiwan, South Korea, and Japan, with ARM TrustZone-enabled SoCs and Intel VT-x processors feeding from NXP and Renesas design houses. Single-source vulnerability at TSMC's advanced nodes threatens virtualization-enabled hardware pipelines. Distribution runs through direct OEM engineering engagements rather than channel intermediaries, with procurement teams mandating turnkey certification packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as regulatory divergence between FAA DO-178C and EU EASA frameworks creates specialist niches for dual-certification engineering services. Mixed-criticality demand across automotive, aerospace, and medical verticals multiplies addressable entry points beyond incumbent strongholds.
For Market Incumbents: Insulate certification heritage through captive supply of ASIL-D and DO-178C engineering talent pools. Acquire specialist consultancies in Germany's Stuttgart corridor to absorb BMW and Mercedes-Benz turnkey procurement mandates. Containerization substitution in telecommunications threatens legacy virtualization revenue streams; redirect R&D toward cloud-edge orchestration integration patterns.
For New Entrants and Emerging Players: Build out India PLI scheme localization services for battery management virtualization, where electric vehicle manufacturing incentives compress incumbent pricing power. Target medical device convergence applications under IEC 62304 standards, where imaging and patient monitoring isolation requirements outpace established vendor attention. Pursue outcome-based certification partnerships with Tamil Nadu Tier-2 suppliers rather than direct OEM competition.
For Investors and Strategic Acquirers: EU Cyber Resilience Act enforcement reshapes the acquisition landscape toward subscription-revenue hypervisor vendors with decade-long support infrastructure. Five-to-ten year viability favors platform-agnostic specialists capable of spanning automotive, aerospace, and industrial certifications without siloed legacy overhead. Monitor KBA and ANSM type approval alignment velocity as inflection signal for compliance service demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Bundle Integration | ASIL-D turnkey packages lock in German automotive procurement through integrated safety case documentation. |
| Cloud-Edge Orchestration Platform | Azure Sphere and AWS IoT Greengrass patterns extend hypervisor management from device to subscription services. |
| Open-Source Foundation Contribution | Xen Project and seL4 microkernel initiatives reduce customer qualification burden for Tier-1 suppliers. |
| India PLI Localization Partnership | Tamil Nadu and Maharashtra manufacturing zones create captive supply positions for battery management virtualization. |
| Dual-Certification Engineering Service | Simultaneous FAA DO-178C and EU EASA approval capabilities capture fragmented compliance demand. |
Research Approach
Operator-level perspectives from hypervisor platform engineers, automotive Tier-1 procurement directors, aerospace certification leads, and medical device software architects anchored the qualitative base. Primary interview intelligence combined with secondary validation from SEC 10-K filings, NHTSA FMVSS guidance documents, EU EASA certification databases, and ISO 26262 audit records. Bottom-up deployment estimates across automotive domain controllers, avionics platforms, and industrial control systems triangulated against top-down market sizing from semiconductor vendor disclosures.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning product type architecture, certification grade tier, end-use vertical, and regional regulatory cluster. CAGRs derived from installed base conversion rates for ECU consolidation platforms and greenfield 5G edge node deployments. Forecast inputs incorporated ARM TrustZone penetration curves in automotive-grade SoCs and EU Cyber Resilience Act compliance investment timelines.
Practitioners should monitor silicon allocation volatility at TSMC and Samsung, containerization substitution velocity in telecommunications infrastructure, and ISO 26262 ASIL-D engineer salary inflation for early signals. Forecasts reflect assumptions regarding sustained automotive ECU consolidation momentum and regulatory harmonization between FAA and EASA frameworks. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Meditation Software Market
Software & Services
Server Operating System Market
Software & Services
Global Offshore Software Development Market
Software & Services
Business Rules Management System Market
Software & Services
DevOps Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Desktop Hypervisor Market
Software & Services
Bridge Analysis Software Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Business Productivity Software Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Legal Practice Management Software Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Employee Advocacy Software Market
Software & Services
PCB Design Software Market
Software & Services
Global OEE Software Market