
 Global User Research and User Testing Software Market | 2026-2036
Global User Research and User Testing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global User Research and User Testing Software Market Foresight
Artificial intelligence is restructuring how user research platforms generate behavioral insights, replacing manual coding with automated sentiment analysis and pattern recognition. UserTesting leverages proprietary panel access to sustain premium positioning among Fortune 500 clients. Maze competes through rapid prototype testing workflows that compress iteration cycles for product teams. dscout anchors its model in longitudinal diary studies, occupying a defensible niche against synchronous testing alternatives.
User research and user testing software encompasses digital platforms that capture, analyze, and interpret user behavior through methods including session replay, eye tracking, and A/B testing, typically delivered via cloud architecture with API integrations into design and analytics stacks. The primary commercial purpose is to reduce product failure risk by grounding design decisions in observed rather than declared user behavior. Cloud-based deployment leads in revenue contribution due to lower onboarding friction and automatic feature updates, while session replay and heatmaps represent the fastest-expanding solution type as product teams prioritize quantitative behavioral validation over attitudinal survey data. Enterprise end user type commands the deepest contract values, though UX researchers remain the most influential internal champions during procurement cycles.
GDPR in Europe, the EU AI Act, and HIPAA in the United States impose strict consent and data residency requirements on platforms processing user recordings and biometric data, directly shaping product architecture and geographic hosting strategies. ISO 27001 certification has become a baseline threshold for enterprise procurement, filtering out smaller vendors lacking audit infrastructure. Stakeholders must monitor evolving cross-border data transfer rulings and invest in region-specific compliance tooling before regulatory fragmentation hardens into permanent market access barriers.
Market Dynamics
Automated behavioral analytics are compressing research timelines from weeks to hours, forcing platform vendors to re-architect around real-time inference pipelines or surrender enterprise accounts to AI-native competitors.
Growth Catalysts
- EU AI Act compliance mandates:Cloud migration requirements under the EU AI Act are accelerating platform refresh cycles as enterprises replace on-premise research infrastructure with compliant SaaS alternatives.
- Financial services UX expansion:Enterprise UX teams at banks and insurers are expanding software procurement budgets to reduce digital product failure rates in high-stakes customer journeys.
- Biometric data processing advances:Eye-tracking and facial coding algorithms now operate at sufficient accuracy to replace manual qualitative coding for emotional response measurement.
Market Restraints
- Cross-border data transfer friction:GDPR's Schrems II rulings and divergent national implementations are fragmenting cloud hosting strategies and inflating compliance engineering costs.
- ISO 27001 certification barriers:The audit infrastructure required for ISO 27001 certification filters smaller vendors from enterprise procurement shortlists, concentrating supply among established platforms.
- Biometric consent complexity:HIPAA in the United States and GDPR in Europe impose strict consent workflows for processing user recordings, adding friction to participant recruitment and session capture.
Strategic Opportunities
- South Korea SaaS adoption:Dense concentrations of SaaS-native product organizations in Seoul and Pangyo present underpenetrated demand for synchronous testing platforms.
- Longitudinal research tooling:Diary study methodologies remain underserved by current platforms, creating white space for vendors offering multi-day participant engagement infrastructure.
- API-first integration demand:Product teams are demanding native integrations with Figma, Amplitude, and Segment, rewarding vendors with open architecture over walled gardens.
Industry Challenges
- Qualitative research skill scarcity:The shortage of trained UX researchers capable of interpreting AI-generated behavioral insights is creating bottlenecks in insight-to-action workflows.
- Legacy analytics stack integration:Enterprises running Adobe Analytics or on-premise data warehouses face complex ETL requirements to merge user research data with existing behavioral datasets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global User Research and User Testing Software Market |
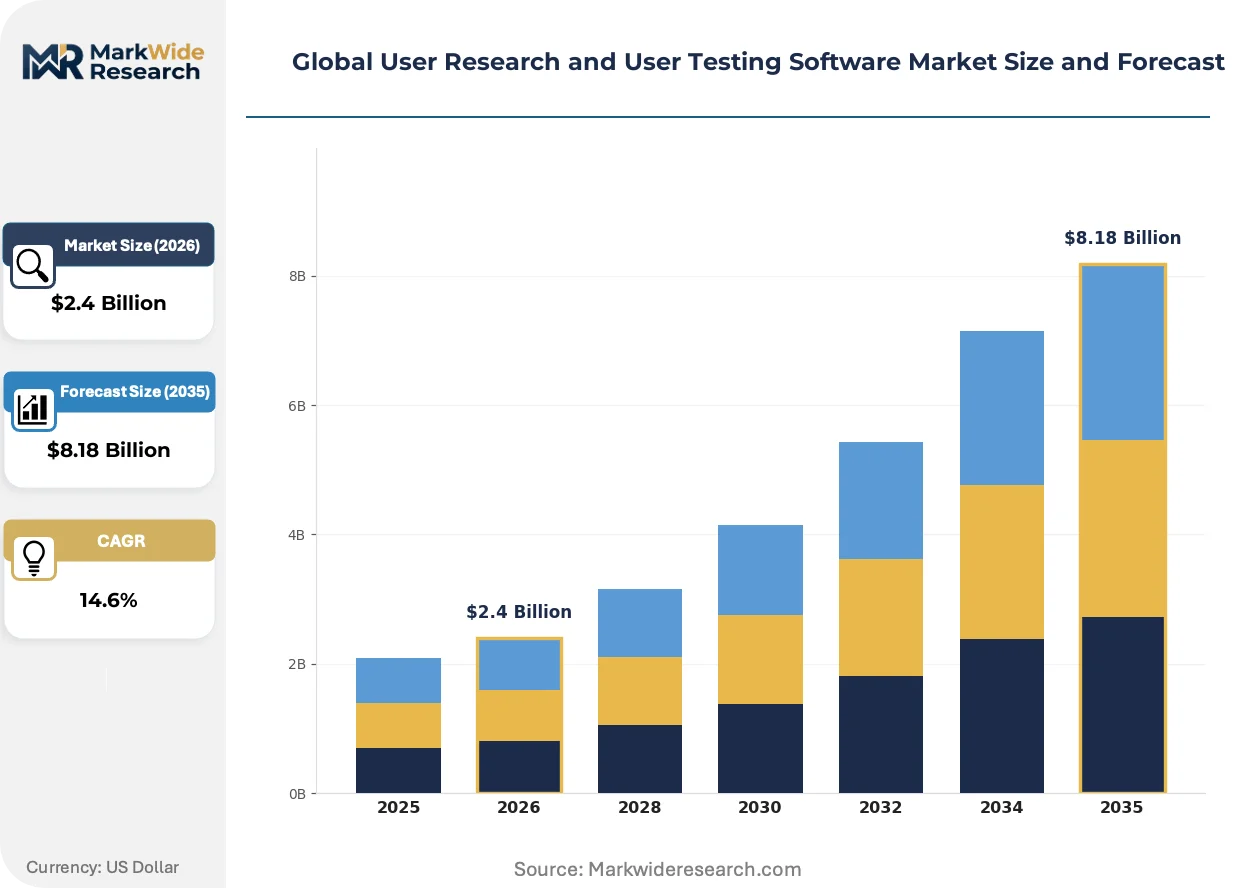
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Enterprise, Mobile Solution Type: Usability Testing, A/B Testing, Heatmaps, Session Replay, Surveys, Eye Tracking Application: Website Optimization, Mobile App Testing, Software Development, UX Design, E-Commerce, Digital Marketing End User Type: Product Managers, UX Researchers, Marketing Analysts, Quality Assurance Teams, Designers, Customer Experience Teams |
| Companies Covered | Respondent.io, Lookback, UserTesting, Great Question, dscout, CleverX, Prolific, Maze, User Interviews, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global User Research and User Testing Software Market Shifts & Advancements
Artificial intelligence is restructuring competitive positioning across user research platforms, compressing the value chain from data capture to insight delivery while raising the bar for differentiation.
Generative AI is automating thematic coding of interview transcripts and open-ended survey responses. UX researchers at technology companies are adopting these tools within eighteen-month procurement cycles. This capability is automating the labor-intensive analysis phase that previously consumed sixty percent of research project timelines.
The EU AI Act's risk classification framework for biometric identification systems is reshaping product architecture decisions. Platforms processing facial expression data must now implement technical documentation and human oversight protocols. European enterprise buyers are prioritizing vendors with pre-certified compliance pathways over faster deployment alternatives.
Self-serve research models are displacing full-service agency relationships among mid-market product teams. Maze and similar platforms enable designers to launch unmoderated tests without researcher involvement. This pattern is most visible in United States technology companies where product velocity metrics override methodological rigor in purchasing decisions.
Global User Research and User Testing Software Market Segmentation
Platform architecture and user workflow requirements create distinct purchasing patterns across deployment modes, solution types, and organizational roles. Segmentation reveals where compliance mandates, integration complexity, and research methodology preferences concentrate commercial value.
Deployment:
Supply concentration in cloud infrastructure is reshaping how vendors allocate engineering resources across hosting architectures.
- Cloud-Based:Multi-tenant SaaS architectures with automatic feature updates and elastic scaling. Financial services enterprises in Germany and the United States are migrating to these platforms to satisfy EU AI Act technical documentation requirements for biometric data processing.
- SaaS:Subscription models with API-first integration into Figma, Amplitude, and Segment stacks. Product teams at technology companies prioritize these deployments for velocity metrics over methodological rigor.
- On-Premise:Single-tenant installations within enterprise data centers. Healthcare organizations subject to HIPAA requirements in the United States maintain these deployments for patient recording consent workflows.
- Hybrid:Split architectures with sensitive data on-premise and analytics workloads in cloud environments. Banks managing cross-border data transfer restrictions under GDPR Schrems II rulings favor this configuration.
- Enterprise:Dedicated instances with custom SLAs and region-specific hosting. ISO 27001 certification is mandatory for procurement shortlists in this tier.
- Mobile:Native SDK deployments for iOS and Android testing with offline synchronization capabilities. South Korean SaaS-native product organizations drive demand for synchronous mobile testing infrastructure.
Cloud-Based absorbs the bulk of installed capacity; Mobile is expanding most quickly.
Solution Type:
Cost tier differentiation separates automated behavioral analytics from labor-intensive qualitative methods.
- Session Replay:Full-fidelity capture of mouse movements, scroll depth, and click sequences with AI-generated frustration indicators. E-commerce teams in the United States prioritize quantitative behavioral validation over attitudinal survey data.
- Heatmaps:Aggregated visualization of attention density and interaction frequency across page elements. Digital marketing agencies use these for conversion rate optimization on high-stakes customer journeys.
- Usability Testing:Task-based evaluation protocols with success rate and time-on-task metrics. UX Researchers remain the most influential internal champions during procurement cycles for this solution type.
- A/B Testing:Statistical hypothesis testing infrastructure with traffic allocation and significance calculation. Product Managers deploy these for feature rollout decisions without researcher involvement.
- Surveys:Structured and open-ended response collection with branching logic. Generative AI is automating thematic coding that previously consumed sixty percent of research project timelines.
- Eye Tracking:Biometric gaze path recording with facial coding algorithms for emotional response measurement. EU AI Act risk classification frameworks require technical documentation and human oversight protocols for these systems.
Session Replay commands the deepest contract values; Eye Tracking faces steepest regulatory compliance engineering costs.
Application:
Customer type maturity determines whether platforms serve iterative design workflows or post-launch optimization.
- Website Optimization:Conversion funnel analysis and page performance diagnostics. E-Commerce teams compress research timelines from weeks to hours using automated behavioral analytics.
- Mobile App Testing:Gesture-based interaction capture and crash correlation with user flows. Seoul and Pangyo clusters present underpenetrated demand for synchronous testing platforms.
- UX Design:Rapid prototype validation with unmoderated task completion. Designers at mid-market technology companies displace full-service agency relationships with self-serve models.
- Software Development:Integration with CI/CD pipelines for pre-release usability validation. Quality Assurance Teams embed these tools into release readiness checklists.
- E-Commerce:Checkout flow optimization and cart abandonment root cause analysis. Customer Experience Teams prioritize platforms with real-time inference pipelines.
- Digital Marketing:Campaign landing page performance and audience segmentation validation. Marketing Analysts demand native integrations with existing analytics stacks.
Website Optimization maintains the largest active user base; Mobile App Testing shows the steepest expansion trajectory.
End User Type:
Volume concentration among technical users is pulling platform roadmaps toward no-code interfaces.
- UX Researchers:Methodology-trained practitioners interpreting AI-generated behavioral insights. Scarcity of qualified researchers creates bottlenecks in insight-to-action workflows.
- Product Managers:Outcome-focused decision-makers prioritizing velocity metrics over statistical rigor. These users drive self-serve procurement without centralized research team involvement.
- Designers:Visual and interaction specialists conducting rapid prototype iteration. Figma-native integrations determine vendor selection for this segment.
- Marketing Analysts:Campaign performance optimizers merging research data with Adobe Analytics or on-premise warehouses. Complex ETL requirements fragment platform adoption.
- Quality Assurance Teams:Pre-release defect identification and regression testing. These teams require session replay correlation with technical error logs.
- Customer Experience Teams:Journey mapping and sentiment monitoring across touchpoints. Longitudinal diary study capabilities remain underserved for this use case.
UX Researchers anchor the highest per-seat pricing; Product Managers are multiplying fastest in platform user counts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software procurement concentrates in three national markets where SaaS-native product organizations cluster most densely. Regulatory mandates in each jurisdiction are reshaping hosting strategies and compliance tooling requirements.
United States
Financial services UX teams at banks and insurers are expanding software budgets to reduce digital product failure rates. HIPAA imposes strict consent workflows for processing user recordings and biometric data. Product organizations in San Francisco and New York Metro drive demand for self-serve research platforms with Figma-native integrations.
Germany
Enterprise buyers prioritize vendors with pre-certified EU AI Act compliance pathways over faster deployment alternatives. GDPR Schrems II rulings fragment cloud hosting strategies and inflate compliance engineering costs. Munich and Berlin host dense concentrations of automotive and industrial software teams migrating from on-premise infrastructure.
South Korea
SaaS-native product organizations in Seoul and Pangyo present underpenetrated demand for synchronous testing platforms. The MFDS regulates biometric data processing in healthcare-adjacent applications. Pangyo Techno Valley clusters mobile-first product teams requiring native SDK deployments with offline synchronization.
United Kingdom
Mid-market technology companies displace full-service agency relationships with rapid prototype testing workflows. The Information Commissioner's Office enforces GDPR consent requirements for eye-tracking and facial coding systems. London's fintech corridor drives procurement of session replay tools for quantitative behavioral validation.
Japan
Quality assurance teams embed usability testing into CI/CD pipelines for pre-release validation. METI guidelines shape technical documentation requirements for AI-enabled research platforms. Tokyo and Osaka product organizations demand API-first integrations with existing Adobe Analytics stacks.
Global User Research and User Testing Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors race to embed AI inference pipelines into design and analytics stacks. The vendor base separates into three tiers: panel-access incumbents with Fortune 500 relationships, workflow-native platforms compressing iteration cycles, and longitudinal methodology specialists occupying defensible niches. Two competitive moves define positioning: API-first architecture investments that reward open integration over walled gardens, and compliance pre-certification pathways that filter vendors from European enterprise shortlists.
Within the panel-access tier, UserTesting anchors premium positioning through proprietary participant networks. Workflow-native platforms include Maze, which exemplifies rapid prototype testing models displacing full-service agency relationships. Longitudinal specialists such as dscout occupy positions against synchronous testing alternatives through multi-day diary study infrastructure. These three archetypes represent the dominant competitive vectors reshaping procurement patterns across enterprise and mid-market segments.
| Leading Market Players |
|---|
| Respondent.io |
| Lookback |
| UserTesting |
| Great Question |
| dscout |
| CleverX |
| Prolific |
| Maze |
| User Interviews |
| Others |
Supply & Pricing Matrix
Cloud infrastructure costs cascade through SaaS pricing tiers as vendors balance elastic compute provisioning against enterprise demand for dedicated instances. Compliance engineering expenses under GDPR and the EU AI Act concentrate in premium tiers, while self-serve deployments absorb standardized hosting overhead.
Pricing Analysis
Volume concentration in mid-market SaaS subscriptions compresses margins, while enterprise contracts with ISO 27001 certification requirements sustain premium pricing. Price differentiation hinges on compliance certification tier and API integration depth. Pricing pressure stems from AI-native entrants automating insight delivery at lower cost points. Product Managers exhibit highest price sensitivity, prioritizing velocity metrics over methodological rigor, whereas UX Researchers anchor willingness-to-pay through procurement influence.
Supply Chain Analysis
Dual-sourcing requirements from financial services buyers mandate multi-cloud qualification across AWS, Azure, and Google Cloud Platform for resilience. Engineering talent pools concentrate in the United States, Germany, and South Korea. Raw material dependencies include GPU compute capacity, biometric sensor hardware, and panel participant networks. Single-source vulnerability sits with proprietary AI inference chip suppliers. Distribution runs through direct enterprise sales with channel partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Control over proprietary participant panels or AI training data repositories determines pricing power and defensibility against algorithmic commoditization.
For Market Incumbents: Anchor enterprise relationships through pre-certified EU AI Act compliance pathways before regulatory fragmentation hardens procurement criteria. Acquire longitudinal research tooling capabilities to defend against diary study specialists. Panel access remains the critical lever for sustaining premium positioning against workflow-native competitors. For New Entrants and Emerging Players: Generative AI-powered thematic coding offers a technology-first wedge into mid-market product teams displacing full-service agency relationships. South Korea's Pangyo Techno Valley presents the most penetrable geography for synchronous mobile testing infrastructure. API-first architecture with Figma-native integration determines go-to-market viability for designer-centric adoption. For Investors and Strategic Acquirers: ISO 27001 certification completion among target vendors is the leading indicator that enterprise procurement access will accelerate. Long-term viability over the next decade rests on compliance moats deepening faster than AI automation commoditizes core functionality. Acquisition targets should demonstrate panel network effects or specialized biometric data processing capabilities. Watch for Schrems II ruling expansions as the inflection signal for regional hosting infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Pre-Certification | EU AI Act technical documentation completion unlocks German enterprise procurement shortlists ahead of enforcement deadlines. |
| API-First Architecture Investment | Native Figma and Amplitude integrations capture designer and product manager workflows displacing full-service alternatives. |
| Longitudinal Research Capability Buildout | Multi-day diary study infrastructure addresses underserved Customer Experience Team demand against synchronous testing incumbents. |
| Panel Network Expansion | Proprietary participant access sustains premium pricing power and defends against algorithmic quality degradation in AI-moderated testing. |
| Regional Hosting Infrastructure | GDPR-compliant data residency configurations satisfy Schrems II requirements for financial services buyers in Germany and the United Kingdom. |
Research Methodology
Independent corroboration across UX research directors at Fortune 500 financial services firms, product managers at SaaS-native technology companies, and compliance officers navigating EU AI Act implementation underwrites the qualitative findings. Primary fieldwork involved structured interviews with platform engineers, procurement leads, and integration specialists at design tool vendors. Secondary validation drew from SEC filings of publicly traded software vendors, hyperscaler capex disclosures for cloud infrastructure trends, and regulatory documentation from the European Commission and national data protection authorities. Bottom-up segmentation modeling triangulated against top-down market sizing from enterprise software spending benchmarks.
Rate-of-change decomposition across deployment modes, solution types, and end user roles structured the analytical framework over the projection horizon. Segmentation dimensions modeled include cloud versus on-premise architecture, session replay versus eye-tracking solution categories, and enterprise versus mid-market organizational scale. CAGRs were derived from elasticity-adjusted adoption curves and replacement cycle analysis. Industry-specific forecast inputs incorporated EU AI Act compliance deadline impacts and financial services UX budget expansion trajectories.
Several conditions sit outside the modeled scope, including potential prohibition of biometric data processing under expanded GDPR interpretations, acquisition-driven consolidation among panel-access providers, and generative AI capability leaps that displace human-moderated research entirely. Deviation in cross-border data transfer rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Legal Software Market
Software & Services
Mining Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Test Automation Market
Software & Services
Global Client Portal Software Market
Software & Services
Device Tracking Software Market
Software & Services
Expense Management Software Market
Software & Services
Global Club Management Software Market
Software & Services
Integration Brokerage Software Market
Software & Services
Software Repository Market
Software & Services
Global Data Recovery Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Parametric Design Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Global API Management Software Market
Software & Services
Global Pre-Employment Testing Software Market