
 Europe Digital OOH Advertising Market | 2026-2036
Europe Digital OOH Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital OOH Advertising Market Intelligence
European screen network operators is broadening supply-side capacity across high-traffic transit corridors and retail precincts. JCDecaux leverages its longstanding concession relationships with municipal transit authorities to secure premium urban inventory. Ströer sustains dense digital coverage along German autobahns and city centers through integrated billboard and street furniture networks. Clear Channel Outdoor anchors market presence across the United Kingdom and continental European airports with large-format LED installations.
Europe Digital OOH Advertising encompasses programmatically traded and statically scheduled visual communication displayed on networked electronic screens in public spaces, typically operating at resolutions from 1080p to 4K with brightness calibration for ambient light conditions. Its primary commercial purpose is delivering targeted brand messaging to captive audiences in transit, retail, and entertainment environments where mobile device distraction remains lower than in-home media. Digital billboards command premium rate cards in high-visibility locations while programmatic buying reshapes transaction economics through automated audience-based trading. Data analytics capabilities embedded in demand-side platforms now enable impression-level attribution that retail marketing buyers prioritize for closed-loop campaign measurement.
GDPR enforcement by national data protection authorities across EU member states constrains how audience measurement data informs programmatic targeting, while the EU Green Deal pressures operators to demonstrate energy efficiency in LED display deployments. Ecodesign regulations under the European Commission's framework increasingly factor into procurement criteria for municipal screen concessions. Stakeholders must weigh data privacy compliance costs against programmatic revenue upside when allocating capital between interactive displays and conventional digital billboard formats.
Market Dynamics
Programmatic trading infrastructure is compressing transaction cycles and forcing asset-light business model pivots among European screen network operators. Real-time audience data integration now determines inventory valuation, while GDPR enforcement constrains how behavioral signals inform automated bidding.
Growth Catalysts
- Transit infrastructure digitization:Municipal authorities across Germany, France, and the United Kingdom are converting static concessions to digital-first contracts, expanding addressable inventory in captive-audience environments.
- EU Green Deal procurement mandates:Ecodesign regulations now embed energy efficiency criteria into LED display tenders, accelerating replacement cycles for legacy screen networks.
- Demand-side platform sophistication:Impression-level attribution capabilities enable retail marketing buyers to close measurement loops between outdoor exposure and point-of-sale conversion.
Market Restraints
- GDPR compliance cost burden:National data protection authorities in France, Germany, and Italy impose granular consent requirements that inflate operational overhead for audience measurement systems.
- Supply concentration in premium urban inventory:Longstanding concession relationships between JCDecaux, Ströer, and municipal transit authorities create barriers to new entrants seeking high-traffic locations.
- Technical limitation in cross-screen frequency capping:Fragmented measurement standards prevent unified reach management across billboard, transit, and retail screen networks.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland, Czech Republic, and Romania present expansion corridors where digital screen density remains below Western European benchmarks.
- Retail media network convergence:Grocery and convenience store operators are deploying in-store digital screens that integrate with programmatic outdoor buying workflows.
- CSRD disclosure requirements:Corporate sustainability reporting mandates create demand for carbon-transparent media planning tools that favor certified energy-efficient screen networks.
Industry Challenges
- Data engineering talent scarcity:Shortage of privacy-preserving analytics specialists constrains operator ability to build GDPR-compliant audience segmentation products.
- Capex intensity in 4K LED retrofit programs:Premium resolution upgrades require substantial capital deployment with extended payback periods in secondary cities.
- Integration complexity with legacy scheduling systems:Static-digital hybrid networks face technical debt when migrating to API-first programmatic workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital OOH Advertising Market |
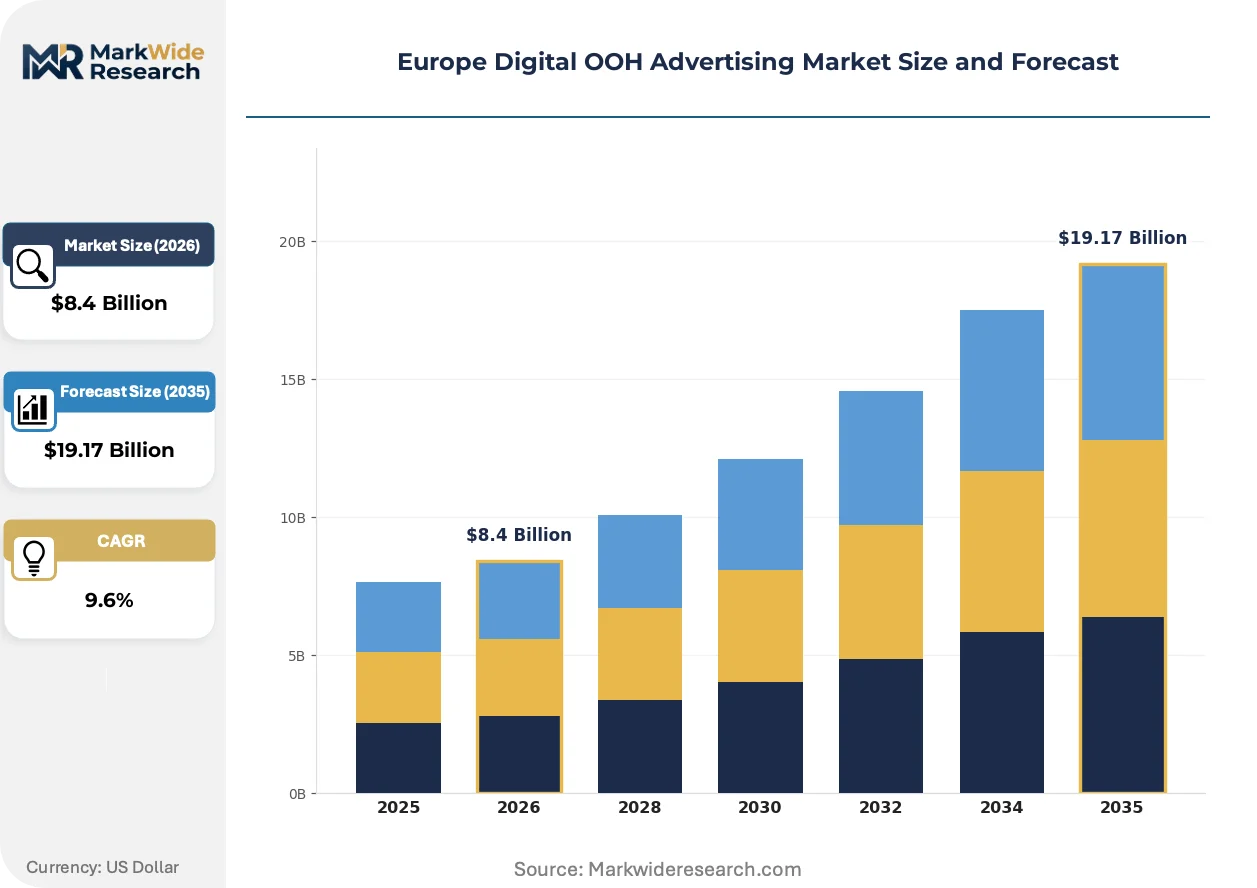
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.17 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
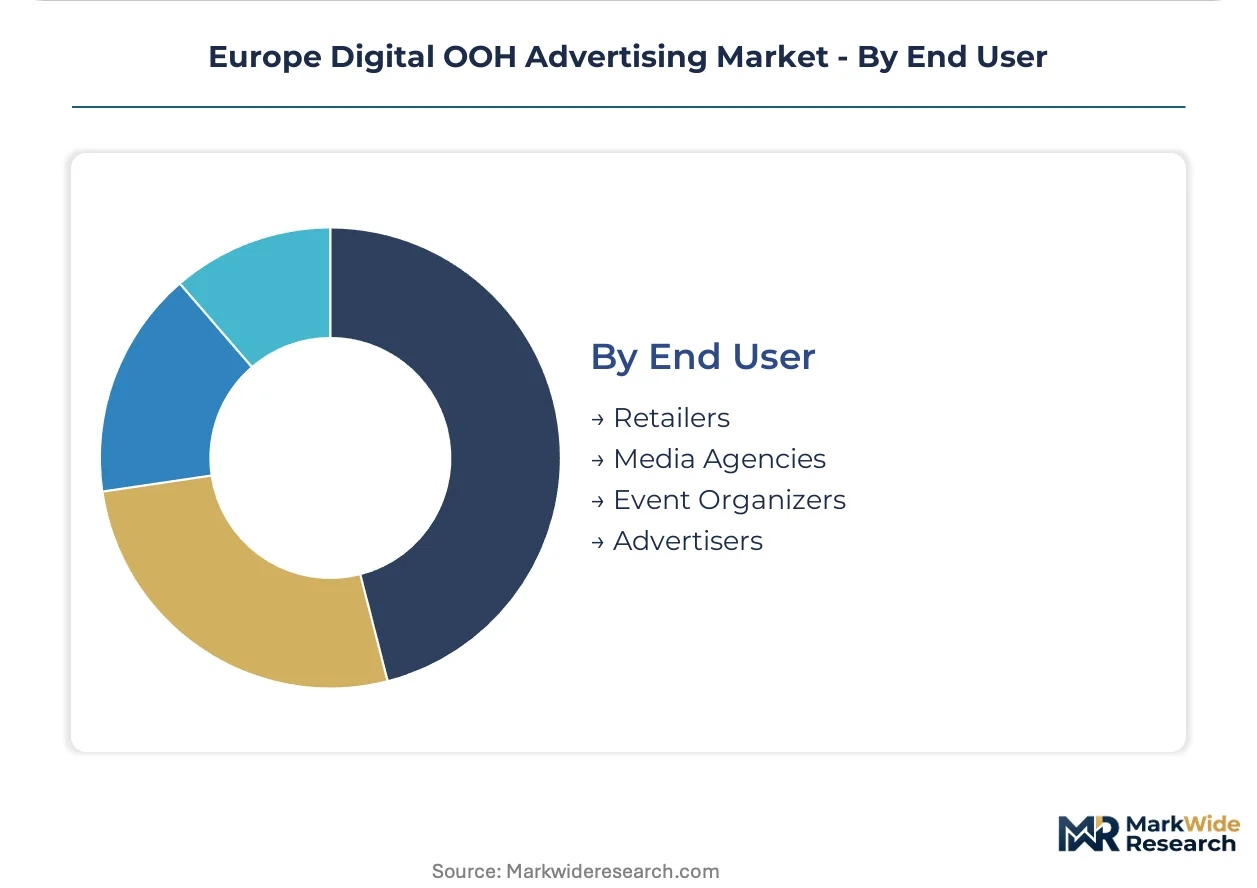
| Segmentation | Media Type: Digital Billboards, LCD Screens, LED Displays, Projection Advertising Application: Retail Marketing, Transit Advertising, Event Promotion, Brand Awareness Technology: Dynamic Content, Data Analytics, Interactive Displays, Programmatic Buying End User: Retailers, Media Agencies, Event Organizers, Advertisers |
| Companies Covered | Broadsign, Daktronics, JCDecaux, Talon Outdoor Ltd, Hivestack Inc., Ströer, Goldbach Group AG, Global, Clear Channel Outdoor, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital OOH Advertising Market Strategic Shifts & Innovations
Three interconnected developments are reconfiguring how inventory is traded, measured, and deployed across European public spaces. Technology automation, regulatory pressure on data practices, and compressed buying cycles collectively determine competitive positioning.
Programmatic direct deals are automating the negotiation and trafficking of reserved premium inventory alongside open-exchange transactions. Major retail marketing buyers in Germany and the United Kingdom are adopting automated guaranteed workflows for seasonal campaigns. This automation is compressing sales cycle duration from weeks to hours while reducing manual insertion order processing overhead.
GDPR enforcement patterns by CNIL in France and the Information Commissioner's Office in the United Kingdom are tightening consent requirements for mobile device signal collection used in audience measurement. Operators must now implement explicit opt-in frameworks or shift to aggregated, non-identifiable traffic analytics. Transit advertising segments in Paris and London are most affected, with several networks pivoting to contextual placement logic rather than behavioral targeting.
Buyer concentration among omnichannel retail marketing departments is consolidating planning authority previously dispersed across regional out-of-home specialists. Major FMCG advertisers in the Netherlands and Belgium now mandate programmatic buying interfaces for all outdoor media commitments. This consolidation is most visible in the Benelux corridor, where procurement teams have eliminated static-only network vendors from consideration sets.
Europe Digital OOH Advertising Market Segmentation
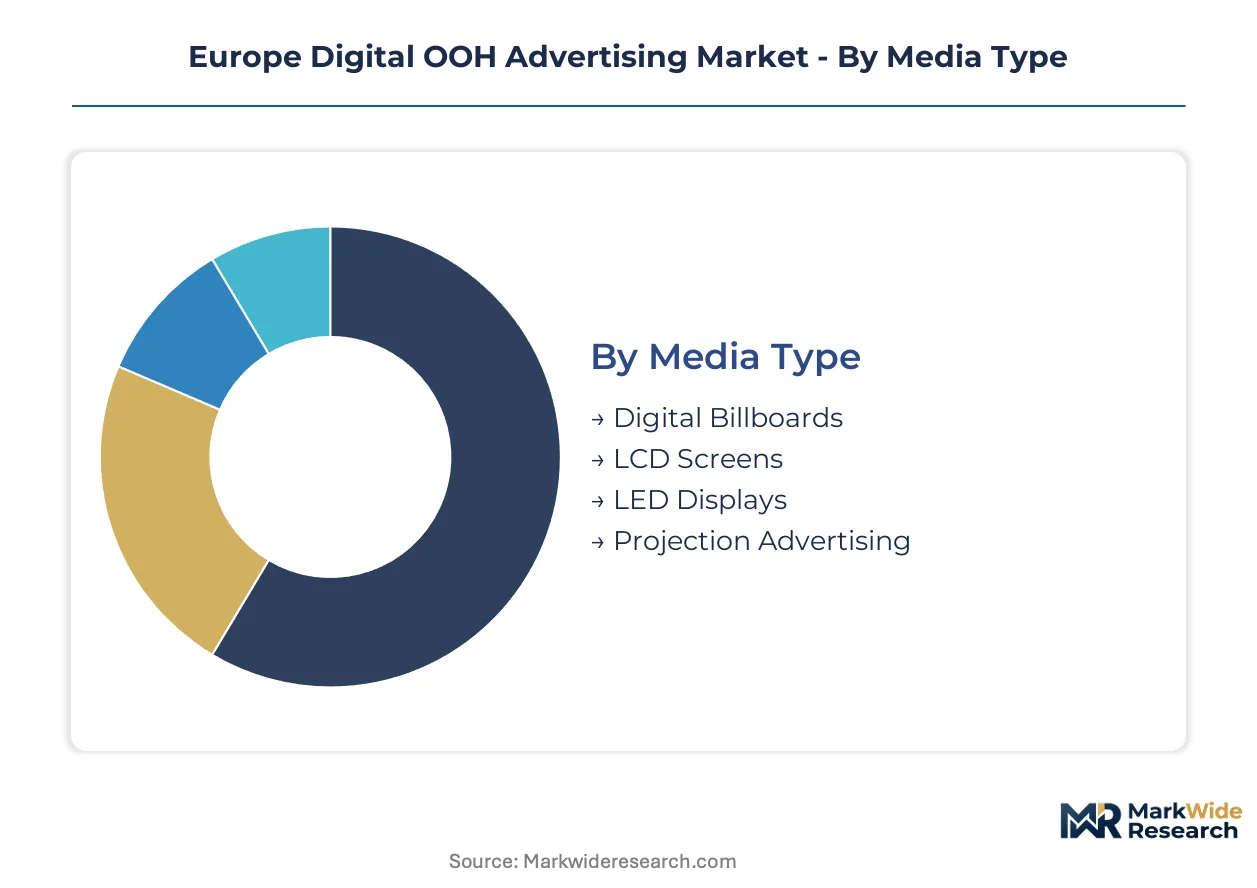
Digital OOH advertising in Europe segments across hardware formats, deployment contexts, and transaction technologies that determine pricing power and buyer access. Network operators structure commercial teams around these divisions, with concession economics varying sharply between transit corridors and retail precincts.
Media Type:
Supply concentration in large-format urban inventory favors operators with longstanding municipal relationships.
- Digital Billboards:Large-format LED installations dominate premium arterial roadways and city-center plazas across Germany, France, and the United Kingdom. JCDecaux and Ströer control the majority of high-visibility concessions, with rate cards reflecting captive commuter traffic volumes.
- LCD Screens:Indoor transit displays in metro systems, airports, and rail terminals operate at lower brightness calibration than outdoor equivalents. Demand concentrates in Paris Charles de Gaulle, London Heathrow, and Frankfurt Airport, where dwell times support extended message exposure.
- LED Displays:High-brightness outdoor panels with adaptive luminosity for ambient light conditions serve street furniture and building-mounted applications. Energy efficiency certifications under EU Green Deal procurement increasingly determine municipal tender outcomes.
- Projection Advertising:Temporary architectural mapping and guerrilla projection campaigns activate heritage building facades and event spaces. Regulatory fragmentation across EU member states constrains scalable deployment.
Digital billboards absorb the bulk of installed capacity; LED displays are expanding most quickly.
Application:
Buyer procurement patterns diverge between always-on retail networks and campaign-based transit bookings.
- Retail Marketing:In-store digital screens at grocery and convenience chains integrate with programmatic outdoor buying workflows. Carrefour, Tesco, and REWE networks in France, the United Kingdom, and Germany are converging retail media with street-level inventory.
- Transit Advertising:Metro, bus shelter, and airport concessions deliver captive audiences with lower mobile distraction than in-home media. GDPR enforcement by CNIL and the ICO constrains mobile signal-based audience measurement in Paris and London networks.
- Event Promotion:Temporary digital installations activate around sports venues, music festivals, and trade exhibitions. Seasonal demand spikes in Munich, Barcelona, and Milan align with major cultural calendars.
- Brand Awareness:Reach-focused campaigns prioritize high-traffic digital billboards in dense urban cores. FMCG advertisers in the Netherlands and Belgium now mandate programmatic interfaces for all outdoor commitments.
Transit advertising commands the deepest concession relationships; retail marketing is climbing the fastest.
Technology:
Margin structures compress as automation displaces manual insertion order processing.
- Dynamic Content:Real-time creative adaptation based on weather, traffic, or sports outcomes requires API-first content management systems. German autobahn networks pioneered traffic-triggered messaging for automotive advertisers.
- Data Analytics:Impression-level attribution capabilities enable closed-loop measurement between outdoor exposure and point-of-sale conversion. Privacy-preserving analytics specialists remain scarce across EU labor markets.
- Interactive Displays:Touchscreen and gesture-activated screens in retail and transit environments collect first-party engagement data. GDPR consent frameworks complicate deployment in French and Italian jurisdictions.
- Programmatic Buying:Automated guaranteed workflows compress sales cycles from weeks to hours. Major retail marketing buyers in Germany and the United Kingdom have adopted programmatic direct deals for seasonal campaigns.
Programmatic buying captures the steepest investment trajectory; dynamic content retains the largest installed base.
End User:
Procurement authority is consolidating from regional out-of-home specialists into centralized omnichannel retail marketing departments.
- Retailers:Grocery and convenience store operators deploy in-store digital networks that integrate with street-level programmatic platforms. Sustainability reporting mandates under CSRD drive carbon-transparent media planning priorities.
- Media Agencies:Holding company trading desks negotiate programmatic access across multiple screen network operators. Independent agencies face margin pressure from automated buying infrastructure.
- Event Organizers:Temporary digital activations require rapid deployment capabilities and flexible content scheduling. Technical integration with legacy static-digital hybrid networks creates operational friction.
- Advertisers:Direct brand procurement teams in FMCG and automotive sectors are building in-house programmatic competency. Benelux corridor advertisers have eliminated static-only vendors from consideration sets.
Media agencies intermediate the majority of transaction volume; retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban transit infrastructure and municipal screen concessions anchor digital OOH deployment across Europe, with premium inventory clustering in dense metropolitan corridors where GDPR enforcement patterns vary by national jurisdiction.
Germany
Autobahn digital billboard networks and dense city-center street furniture drive inventory expansion, with Ströer leveraging integrated coverage across both formats. The Federal Data Protection Authority enforces granular consent requirements for mobile signal-based audience measurement. Munich and Frankfurt concentrate premium LED installations where automotive advertisers trigger dynamic content based on real-time traffic conditions.
United Kingdom
Airport and London Underground concessions deliver captive audiences with extended dwell times, while programmatic adoption accelerates among retail marketing buyers. The Information Commissioner's Office mandates explicit opt-in frameworks for device signal collection, constraining behavioral targeting capabilities. Heathrow and Gatwick terminals host high-visibility LCD networks where FMCG brands prioritize closed-loop attribution measurement.
France
Paris Metro and RATP transit corridors dominate premium inventory allocation, with JCDecaux securing longstanding municipal concession relationships. CNIL enforcement has tightened consent requirements for mobile analytics, pushing networks toward contextual placement logic. La Défense business district and Champs-Élysées clusters concentrate large-format LED deployments with adaptive brightness calibration.
Netherlands
Benelux corridor procurement teams have eliminated static-only vendors from consideration sets, consolidating planning authority within omnichannel retail marketing departments. The Dutch Data Protection Authority aligns with GDPR enforcement patterns seen in neighboring jurisdictions. Amsterdam and Rotterdam harbor dense programmatic-ready networks where grocery retail media converges with street-level inventory.
Poland
Warsaw and Kraków present expansion corridors where digital screen density remains below Western European benchmarks, attracting capital deployment from regional operators. Polish data protection enforcement follows EU harmonized standards with implementation lag relative to France and Germany. Major retail chains in Warsaw are deploying in-store digital screens that integrate with programmatic outdoor buying workflows.
Europe Digital OOH Advertising Market Key Industry Players
Global majors compete with regional champions across concession relationships and programmatic infrastructure, producing a tiered structure where scale advantages concentrate in premium urban inventory. Longstanding municipal contracts create defensive moats around high-traffic transit corridors. Three archetypes dominate: integrated transit-street furniture operators, technology-enabled programmatic platforms, and retail media network specialists. Competitive dynamics center on concession renewal negotiations and API-first platform integration rather than price-based rivalry.
Among integrated European operators, JCDecaux, Ströer, and Clear Channel Outdoor exemplify the concession-heavy archetype, anchoring market presence through municipal relationships that span decades. Broadsign and Hivestack occupy positions on the technology platform vector, enabling automated inventory trading across fragmented screen networks. Talon Outdoor Ltd represents the agency-aligned intermediary model, bridging buyer procurement workflows with operator supply. These three groupings—concession incumbents, software enablers, and trading specialists—collectively determine how programmatic infrastructure penetrates national markets.
| Leading Market Players |
|---|
| Broadsign |
| Daktronics |
| JCDecaux |
| Talon Outdoor Ltd |
| Hivestack Inc. |
| Ströer |
| Goldbach Group AG |
| Global |
| Clear Channel Outdoor |
| Others |
Cost & Logistics Intelligence
Privacy-preserving analytics specialists concentrated in Germany and the United Kingdom command wage premiums that widen pricing spreads between GDPR-compliant premium networks and basic programmatic inventory. Labor-cost differentials across these talent pools directly determine whether operators bundle advanced audience measurement or sell unbundled impressions at lower rate cards.
Pricing Analysis
Warranty and service bundling separates premium network operators from asset-light competitors, with JCDecaux and Ströer including dedicated technical support and rapid hardware replacement in long-term concession contracts while smaller operators strip out after-sales coverage to hit lower price points. Three-tier pricing structure across premium, standard, and economy levels reflects certification status under EU Green Deal ecodesign criteria, with energy-efficient LED installations commanding rate premiums. Cost compression in economy-tier inventory is intensifying because municipal authorities are consolidating concessions to operators with integrated maintenance capabilities. Retail marketing buyers in the Benelux corridor show lowest price sensitivity, prioritizing closed-loop attribution over rate card discounts.
Supply Chain Analysis
CE marking and ecodesign qualification gating under EU procurement frameworks constrain which LED display manufacturers can bid on municipal tenders, filtering supply to certified producers. Hardware sourcing concentrates in China, South Korea, and Taiwan for LED modules and driver components, with final assembly increasingly shifting to Poland and Romania to manage logistics costs. European operators draw from captive relationships with these Asian component suppliers, exposing networks to tariff volatility in semiconductor inputs. Distribution runs through direct operator procurement for large-format installations and specialized AV integrators for retail and transit retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where GDPR enforcement by CNIL, the ICO, and Germany's Federal Data Protection Authority erects barrier-to-entry moats favoring operators with pre-built consent frameworks and privacy engineering capabilities.
For Market Incumbents: Lock in concession renewal advantages by embedding CSRD-aligned carbon reporting tools into municipal contracts before competitors can match compliance infrastructure. Prioritize API-first programmatic integration to defend against technology-enabled platforms poaching inventory access. Counter emerging retail media network specialists by securing exclusive grocery and convenience store partnerships that bridge in-store and street-level inventory.
For New Entrants and Emerging Players: Launch via white-label programmatic platform partnerships to bypass capital-intensive screen ownership and access fragmented secondary-city inventory. Poland, Czech Republic, and Romania present the most penetrable geographies where digital screen density trails Western benchmarks and municipal authorities lack entrenched incumbent relationships. Target retail media convergence as the primary go-to-market angle, offering grocery chains turnkey in-store network deployment that integrates with established outdoor buying workflows.
For Investors and Strategic Acquirers: Re-rating potential sits with privacy-engineering-capable operators given tightening GDPR enforcement patterns across France, Germany, and Italy. Long-term viability hinges on concession portfolio duration and programmatic platform integration depth rather than raw screen count. Watch for CNIL or ICO enforcement actions against non-compliant audience measurement practices as the signal indicating accelerated consolidation toward certified operators.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Programmatic Integration | Automated guaranteed workflows reduce sales cycle duration from weeks to hours for retail buyers. |
| GDPR-Compliant Audience Measurement | Explicit opt-in frameworks satisfy CNIL and ICO requirements while preserving targeting capabilities. |
| EU Green Deal Certification | Ecodesign credentials unlock municipal tender preferences and CSRD-aligned procurement mandates. |
| Retail Media Network Convergence | In-store screen integration with street-level programmatic platforms captures grocery advertising budgets. |
| Eastern European Expansion | Warsaw and Kraków deployment addresses underpenetrated markets with lower concession competition. |
Research Approach
Trade association filings, municipal concession registers, and national data protection authority enforcement records formed the secondary backbone of this analysis. Primary interviews with network operations directors, programmatic platform engineers, retail media buyers, and municipal procurement officers provided ground-truth validation. Bottom-up screen inventory counts by operator and geography were triangulated against top-down advertising spend estimates derived from media agency trading desk disclosures.
Historical deployment trajectories of digital billboards, transit screens, and retail networks established baseline growth patterns across the projection horizon. Segmentation modeling incorporated media type, application context, transaction technology, and end-user procurement authority dimensions. CAGRs were derived from fitted trend analysis adjusted for regulatory inflection points including GDPR enforcement intensification and EU Green Deal procurement mandate timelines.
Regulatory enforcement variance, technology substitution rates, and concession renewal timing are the dominant revision risks to modeled outputs. Forecasts embed assumptions regarding GDPR compliance cost trajectories and municipal digitization contract conversion rates. A model refresh is warranted upon material change in CNIL or ICO enforcement posture toward mobile signal-based audience measurement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Austria OOH and DOOH Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Global Advertising Agency Software Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
Multiscreen Advertising Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Europe Programmatic Advertising Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
Online Advertising Market