
 Online Advertising Market | 2026-2036
Online Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Online Advertising Market Intelligence
The Interactive Advertising Bureau's Digital Ad Operations Certification is bifurcating the market between certified professionals and unaccredited practitioners. This standard ensures proficiency in complex campaign management and ad tech platforms. Google LLC leverages its dominant search and video platforms to set de facto technical standards for ad delivery. Meta Platforms Inc. competes through its vast social graph and user engagement data across its family of apps.
Online advertising involves the delivery of promotional content to consumers through digital channels, utilizing data for targeting and measurement. Its function relies on programmatic auction systems that execute real-time bidding (RTB) for ad inventory in milliseconds. Within ad formats, video and social media ads represent the fastest-growing categories, commanding higher cost-per-mille rates. The mobile platform continues to absorb the majority of ad spend, while connected TV emerges as a high-value frontier.
Regulatory frameworks like Europe's GDPR and enforcement actions by the US Federal Trade Commission impose strict consent and data handling requirements. China's Personal Information Protection Law (PIPL) similarly governs data collection, shaping how multinational advertisers operate. These privacy-centric regulations compel advertisers to adopt new measurement techniques independent of third-party identifiers. Success now depends on developing effective first-party data strategies and navigating a complex compliance landscape.
Market Dynamics
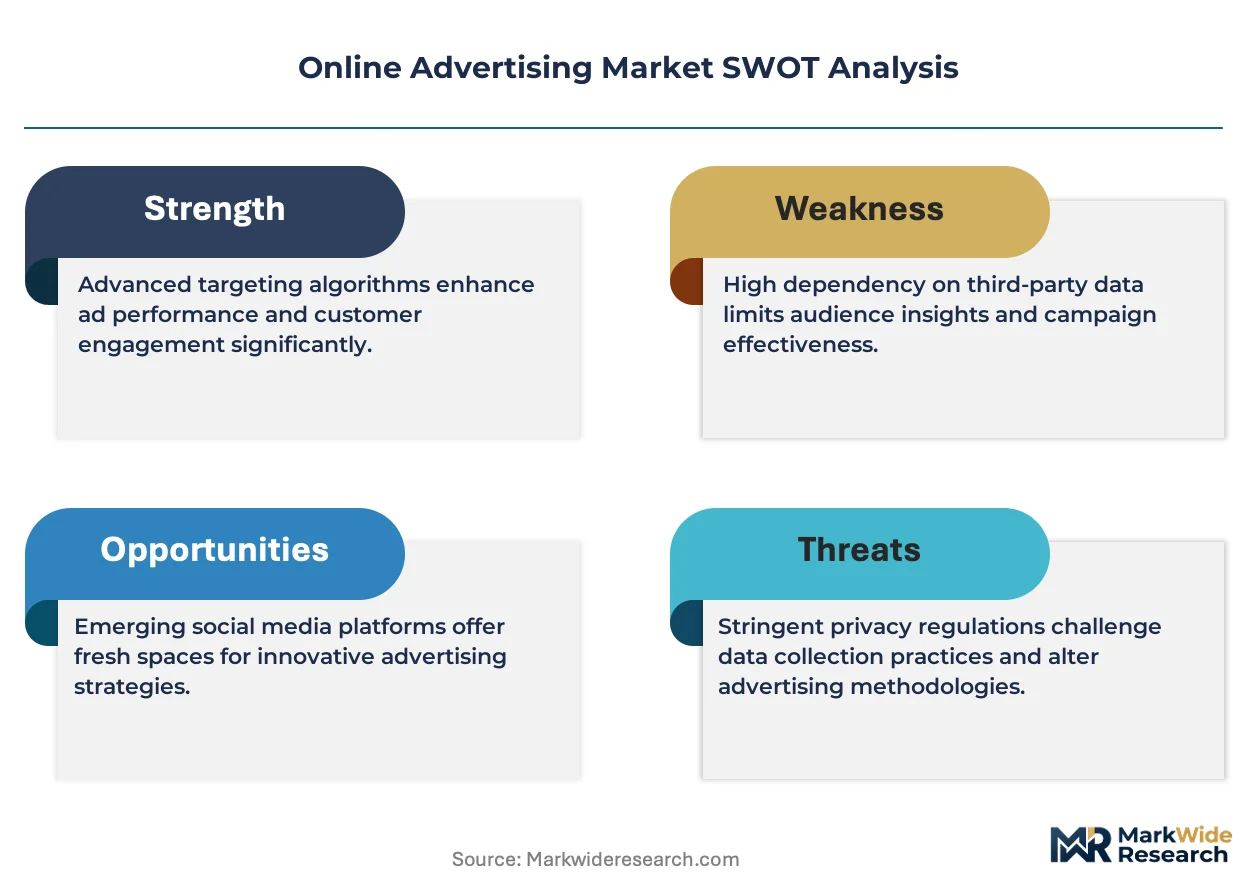
The online advertising market's core dynamic is the industry-wide pivot away from third-party identifiers. This shift, driven by regulatory pressure and platform policies, creates a fundamental tension between the demand for data-driven, personalized advertising and the imperative for user privacy.
Growth Catalysts
- Connected TV Expansion:The growth of ad-supported streaming services on connected TVs opens up high-value, non-skippable video inventory, attracting premium brand budgets previously allocated to linear television.
- Mobile-First Internet Growth:In developing economies, particularly India, the rapid expansion of the mobile internet user base creates a massive, addressable audience for mobile-centric ad formats like social and in-app video.
- Consumer Electronics Sector Spending:Manufacturers in the consumer electronics sector are increasing their digital ad spend to support frequent product launch cycles and drive e-commerce sales directly to consumers.
Market Restraints
- Regulatory Fragmentation:Navigating the complex and often conflicting requirements of privacy laws like Europe's GDPR, China's PIPL, and various US state laws increases compliance costs and operational friction for advertisers.
- Prevalence of Ad Fraud:Sophisticated invalid traffic and click fraud schemes continue to siphon off advertising budgets, eroding advertiser trust in the programmatic ecosystem and the reliability of performance metrics.
- Ad-Blocking Technology:The widespread adoption of ad-blocking software on both desktop and mobile browsers directly reduces the addressable ad inventory, forcing publishers to find alternative monetization models.
Strategic Opportunities
- In-Game Advertising:The integration of dynamic, non-intrusive ads within mobile, console, and PC gaming environments offers a new channel to reach highly engaged, younger demographics.
- Retail Media Networks:The convergence of retail e-commerce platforms and advertising technology allows brands to leverage retailers' first-party shopper data for highly effective, closed-loop campaigns.
- Latin American Market Penetration:With rising smartphone adoption and e-commerce growth, countries like Brazil and Mexico present significant opportunities for advertisers as digital infrastructure and consumer habits mature.
Industry Challenges
- Privacy Engineering Talent Gap:A shortage of professionals with dual expertise in data science and privacy-enhancing technologies (PETs) hinders the development and implementation of compliant, next-generation targeting solutions.
- Cross-Platform Measurement:The absence of a universal, post-cookie measurement standard makes it difficult for advertisers to accurately assess campaign ROI and attribute conversions across different platforms and devices.
- Compliance Audit Complexity:Maintaining and documenting auditable compliance with evolving data privacy regulations requires significant ongoing investment in legal, technical, and operational resources, particularly for smaller firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Advertising Market |
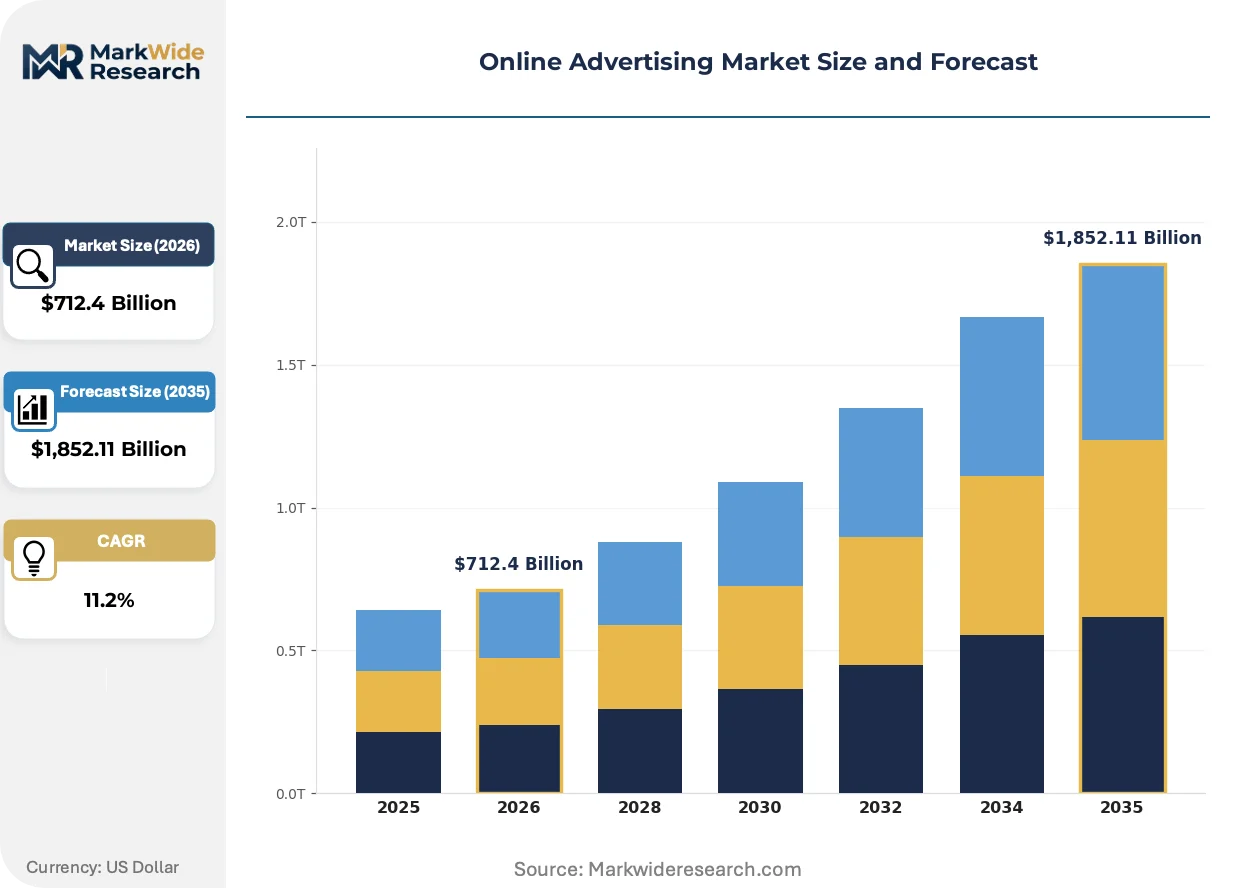
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $1,852.11 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Display Ads, Video Ads, Search Ads, Native Ads, Social Media Ads Platform: Mobile, Desktop, Connected TV, Digital Out-of-Home, Smart Devices Industry Focus: Consumer Electronics, Financial Services, Education Services, Travel & Hospitality, Telecommunications Pricing Model: Cost Per Click, Cost Per Mille, Cost Per Action, Cost Per View, Flat Rate |
| Companies Covered | Google LLC (Alphabet Inc.), Meta Platforms Inc., Amazon.com Inc., ByteDance Ltd., Microsoft Corporation, Baidu Inc., Alibaba Group, Tencent Holdings Ltd., The Trade Desk Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Advertising Market Strategic Shifts & Innovations
The market's evolution is defined by the dual forces of AI-driven automation in campaign execution and a foundational reinvention of targeting methodologies. These trends are not sequential but are occurring in parallel, forcing a rapid upskilling across the industry.
Generative AI tools for ad creative are automating the production of text, image, and video assets. Performance marketing teams within e-commerce and gaming are the primary adopters, using these systems to generate campaign variations at scale. This automation is displacing traditional manual A/B testing and creative development cycles, enabling a more dynamic approach to ad personalization.
Europe's General Data Protection Regulation (GDPR) continues to set a global precedent for data privacy and consent management. Its enforcement compels advertisers to obtain explicit and unambiguous user consent before processing personal data for targeted advertising. The consumer packaged goods and financial services sectors are most affected, investing heavily in consent management platforms and first-party data strategies to maintain compliance.
Advertisers are reallocating significant portions of their budgets to closed-ecosystem advertising platforms. This shift disrupts the open programmatic web in favor of walled gardens like social media and retail media networks where user identity is verified internally. This trend is most visible in the direct-to-consumer vertical, where brands seek the high-quality conversion data these platforms provide.
Online Advertising Market Segmentation
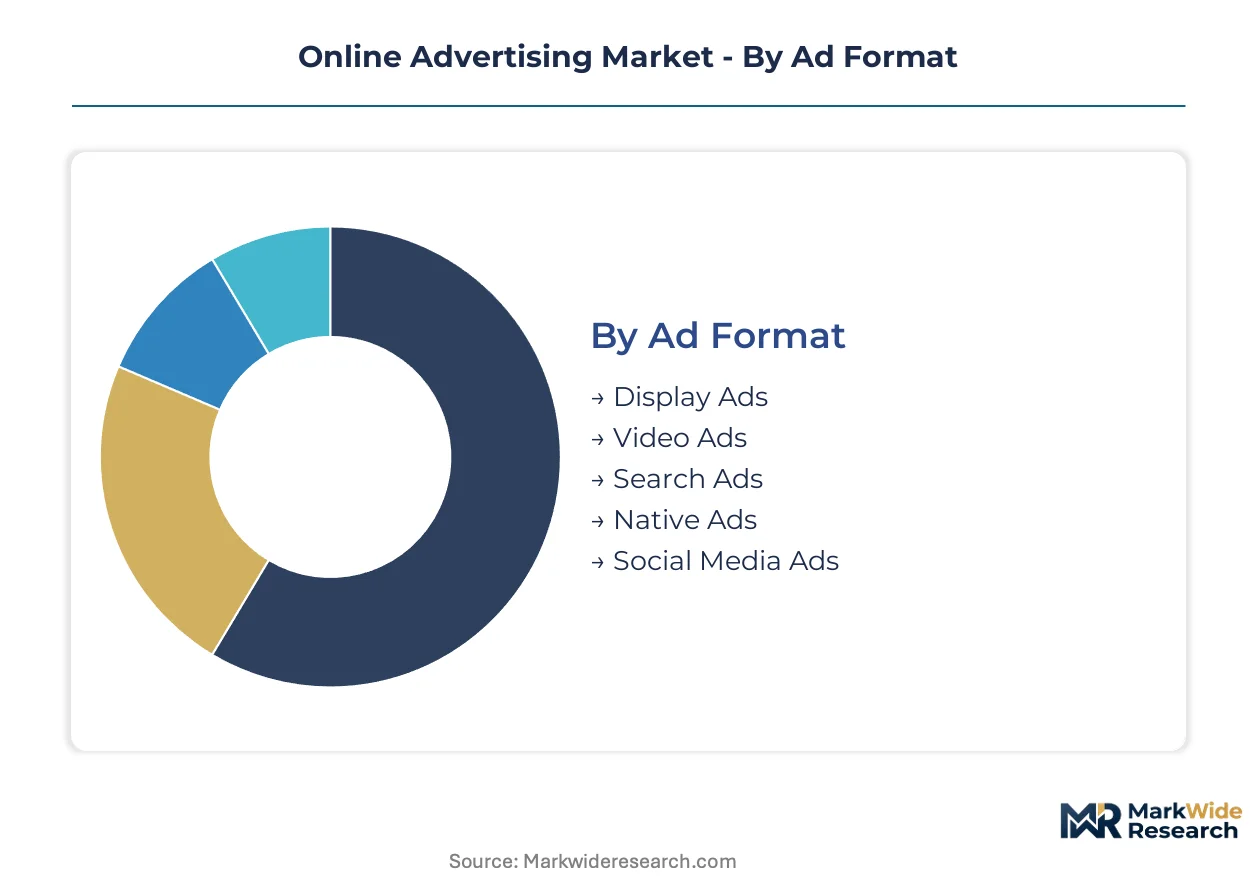
The online advertising market's segmentation reveals the diverse channels and strategies employed to reach digital consumers. Understanding these distinct categories allows advertisers to optimize campaign performance and allocate budgets effectively. Each segment reflects unique targeting capabilities and audience engagement models.
Ad Format:
The geographic spread of ad formats varies significantly, with some formats dominating mature digital economies while others gain traction in emerging mobile-first markets like India.
- Display Ads:These visual advertisements appear on websites, apps, and other digital interfaces, often served programmatically.
- Video Ads:These promotional units deliver content through pre-roll, mid-roll, or out-stream placements across digital platforms. Demand concentrates in the US and Europe, driven by increasing consumption of streaming content and higher engagement rates compared to static images.
- Search Ads:Text-based advertisements appear prominently on search engine results pages, driven by user intent signals.
- Native Ads:Designed to blend seamlessly with the surrounding editorial content, these ads aim for non-disruptive user experiences.
- Social Media Ads:Integrated directly within social networking platforms, these ads leverage extensive user data for precise targeting. Their adoption is particularly strong in Brazil and Indonesia, where platforms like Meta and TikTok command massive daily active user bases.
Search Ads command the established base. The steepest expansion runs through Video Ads.
Platform:
The market exhibits a clear application-driven segmentation, with platforms tailored to specific user interaction models and device capabilities.
- Mobile:This segment encompasses all advertising delivered via smartphones and tablets, including in-app and mobile web formats. Mobile absorbs the majority of ad spend globally, particularly in China, due to ubiquitous smartphone penetration and extensive app usage.
- Desktop:Advertising served on traditional personal computers and laptops includes display, search, and video formats.
- Connected TV:Advertising delivered through internet-connected television sets and streaming devices offers premium, full-screen video inventory. This platform is gaining significant traction in the US and UK, attracting large brand budgets previously allocated to linear television.
- Digital Out-of-Home:Digital screens in public spaces like malls and transit hubs deliver dynamic advertising content.
- Smart Devices:This emerging category includes ads on voice assistants, wearables, and other IoT devices.
Mobile platforms continue to hold the largest share. Connected TV is gaining share fastest.
Industry Focus:
The segmentation by customer type reflects varying advertising needs and budget allocations across different economic sectors.
- Consumer Electronics:Manufacturers in this sector heavily invest in digital advertising to support frequent product launches and direct-to-consumer e-commerce initiatives. This segment demonstrates high ad spend in markets like South Korea and Germany, driven by innovation cycles.
- Financial Services:This sector utilizes online advertising for lead generation, brand building, and customer acquisition for products like loans and insurance. Regulatory compliance mandates influence ad creative and targeting in markets such as the US and France.
- Education Services:Institutions and platforms employ digital ads for student recruitment and program promotion.
- Travel & Hospitality:Airlines, hotels, and booking sites use online ads for destination marketing and direct bookings.
- Telecommunications:Providers advertise new plans, devices, and services to acquire and retain subscribers.
Financial Services historically allocate substantial budgets. Consumer Electronics shows the most dynamic expansion.
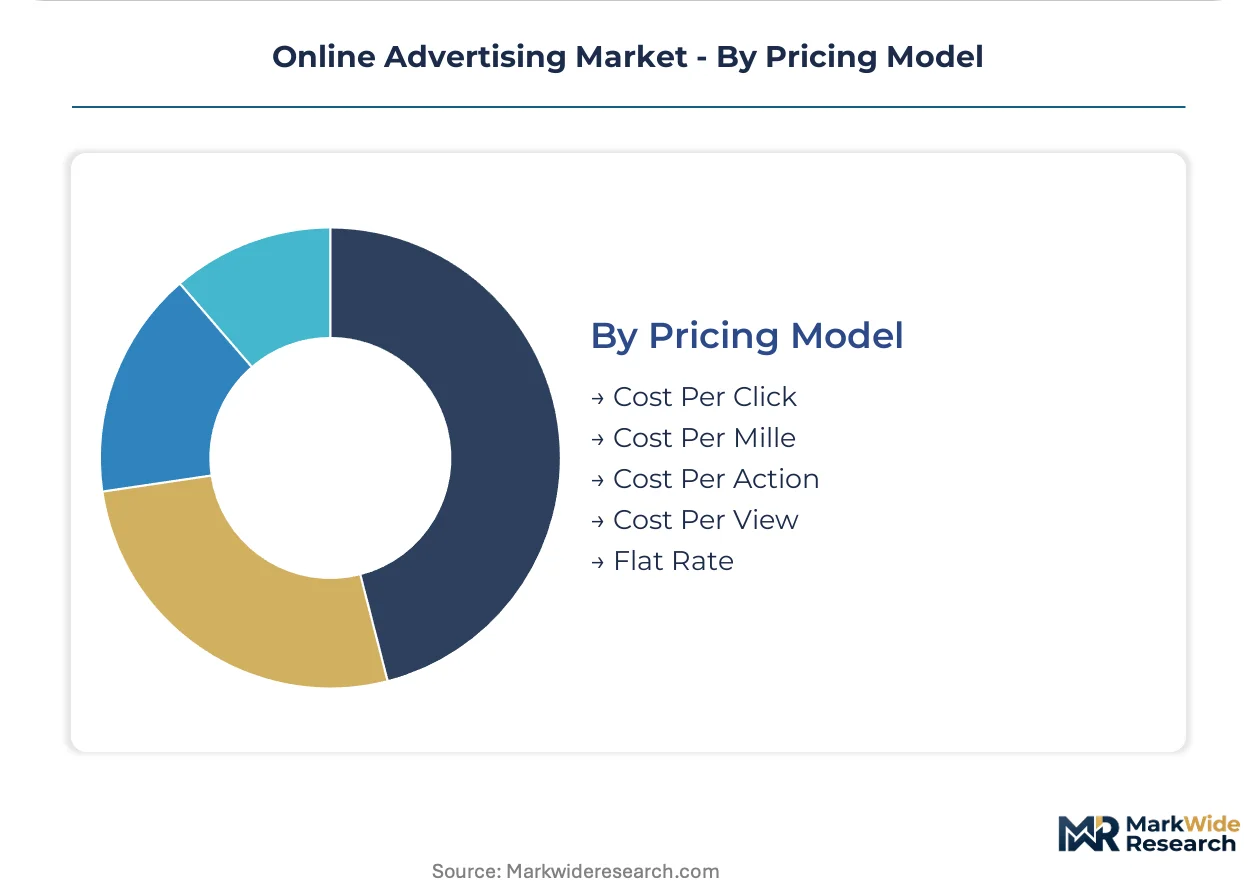
Pricing Model:
The pricing models employed in online advertising are primarily driven by the desired outcome, reflecting distinct cost-benefit structures for advertisers.
- Cost Per Click:Advertisers pay only when a user clicks on their advertisement, directly linking cost to user engagement. This model remains dominant for performance-driven campaigns in Google Search across most global markets.
- Cost Per Mille:This model charges advertisers for every thousand impressions (views) an ad receives, suitable for brand awareness campaigns. It sees extensive use in display and video advertising across Europe and Japan.
- Cost Per Action:Advertisers pay only when a specific action, such as a purchase or sign-up, is completed.
- Cost Per View:Payment is triggered when a video ad is watched for a defined duration or completion.
- Flat Rate:Advertisers pay a predetermined fixed price for a specific ad placement or duration.
Cost Per Click remains a foundational pricing model. Cost Per Mille is seeing increased adoption for branding initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government initiatives and privacy-centric regulations across diverse geographies are significantly shaping the online advertising landscape. These policies compel advertisers to adapt their strategies, fostering innovation in data handling and targeting methodologies. Digital infrastructure development also underpins market expansion in emerging economies.
United States
Robust e-commerce growth and extensive digital media consumption drive demand for online advertising in the United States. Federal Trade Commission (FTC) enforcement actions emphasize data privacy and consumer protection, influencing ad tech practices. Silicon Valley and New York City remain central to ad tech innovation, with numerous platforms developing advanced measurement solutions.
China
China's massive mobile-first internet user base and strong domestic e-commerce platforms fuel substantial online ad spend. The Personal Information Protection Law (PIPL) strictly regulates data collection and usage, necessitating localized compliance strategies. Major tech hubs like Beijing and Shenzhen host dominant advertising platforms and ad tech developers.
India
Rapid smartphone adoption and expanding internet penetration across India create a vast, addressable audience for digital advertisers. The country's regulatory bodies are developing frameworks for data governance that will impact targeting practices. Bengaluru and Mumbai serve as key centers for ad tech development and digital marketing agencies.
Germany
Germany's strong economic foundation and high consumer purchasing power support significant brand advertising budgets online. Europe's GDPR sets a high bar for data privacy and consent, directly influencing German advertisers' operational compliance. Munich and Hamburg are important regional hubs for media buying and creative advertising agencies.
Brazil
Brazil's rising smartphone penetration and active social media usage contribute to a dynamic online advertising market. The Lei Geral de Proteção de Dados (LGPD) governs personal data processing, requiring advertisers to implement transparent consent mechanisms. São Paulo functions as the primary commercial and advertising hub, driving digital campaign execution.
Online Advertising Market Key Industry Players
Player mix skews toward large platform providers that integrate advertising into their core services, alongside a fragmented ecosystem of specialized ad tech vendors. The market exhibits a tiered structure, with a few dominant players controlling significant inventory and data. Strategic partnerships and technology licensing are common competitive moves within this sector.
Archetype-first, platform giants like Google LLC and Meta Platforms Inc. anchor the market, leveraging their extensive user bases and proprietary data for targeted advertising. Amazon.com Inc. represents a significant force in retail media, integrating advertising directly into its e-commerce ecosystem. These entities set de facto standards for ad delivery and measurement, influencing the broader industry through their technological advancements and policy shifts.
| Leading Market Players |
|---|
| Google LLC (Alphabet Inc.) |
| Meta Platforms Inc. |
| Amazon.com Inc. |
| ByteDance Ltd. |
| Microsoft Corporation |
| Baidu Inc. |
| Alibaba Group |
| Tencent Holdings Ltd. |
| The Trade Desk Inc. |
| Others |
Cost & Logistics Intelligence
First-party data strategies replacing third-party cookie reliance simultaneously reshapes ad tech supply geography and pricing economics. This shift centralizes data control within major platforms, impacting inventory value.
Pricing Analysis
Precise targeting capabilities create the primary spread in online advertising pricing. Cost Per Click remains the dominant pricing model for performance campaigns, while Cost Per Mille sees increased adoption for branding initiatives. Pricing softness stems from the increasing prevalence of ad fraud and ad-blocking technologies. Performance marketers, particularly in e-commerce, exhibit high price sensitivity, contrasting with brand advertisers who prioritize reach.
Supply Chain Analysis
Platform control over vast user data underwrites the online advertising supply chain. Supply concentration centers on major technology companies like Google LLC, Meta Platforms Inc., and Amazon.com Inc., providing core ad inventory in the US, China, and India. Raw material dependencies include user data and digital ad placements, while regulatory restrictions like Europe's GDPR present a structural risk. Distribution runs through programmatic auction systems and direct platform sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The online advertising market is undergoing a platform-economics inflection, driven by the shift towards first-party data strategies within walled garden ecosystems. This redefines value creation and competitive advantage.
For Market Incumbents: Shield existing market share by investing heavily in privacy-enhancing technologies (PETs) to address regulatory pressure from GDPR and PIPL. Deepen vertical integration into first-party data collection and activation to mitigate third-party cookie deprecation. Control over proprietary user data remains a critical lever against emerging ad tech competitors. Expand into high-growth formats like Connected TV advertising to capture premium brand budgets.
For New Entrants and Emerging Players: Lead with specialized capabilities in niche ad formats or underserved geographies to penetrate the market. Target the in-game advertising segment with dynamic, non-intrusive ad solutions for highly engaged younger demographics. Focus on developing compliant, cross-platform measurement solutions for advertisers navigating post-cookie environments. Leverage first-party data partnerships with consumer brands to offer effective closed-loop campaigns.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with ad tech vendors specializing in privacy-centric measurement or retail media network enablement. Long-term viability depends on platforms that demonstrate robust first-party data capabilities and regulatory compliance. Acquire companies with strong expertise in privacy engineering and AI-driven creative automation to capitalize on industry shifts. Watch for consolidation among mid-tier ad tech providers as platform policies continue to evolve.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in First-Party Data Infrastructure | Enables advertisers to maintain targeting effectiveness and compliance amidst third-party cookie deprecation. |
| Develop AI-Powered Creative Automation | Automates ad asset production at scale, allowing e-commerce and gaming companies to personalize campaigns dynamically. |
| Expand Connected TV Advertising Offerings | Captures premium brand budgets previously allocated to linear television, leveraging high-value video inventory. |
| Acquire Privacy Engineering Expertise | Bridges the talent gap in data science and privacy-enhancing technologies, crucial for compliant targeting solutions. |
| Form Retail Media Network Partnerships | Leverages retailers' first-party shopper data for highly effective, closed-loop campaigns for consumer brands. |
Research Approach
Cross-validation between primary interviews and regulatory filings anchors the qualitative findings of this study. Analysts conducted interviews with ad tech executives, brand marketing directors, platform strategists, and data privacy officers. Secondary validation involved reviewing SEC 10-K filings, IAB reports, and academic research on digital advertising. A bottom-up and top-down triangulation approach ensured data consistency and comprehensive market coverage.
Sensitivity analysis underpins the quantitative framework, modeling market dynamics across the projection horizon. Segmentation dimensions included ad format, platform, industry focus, and pricing model, alongside regional adoption patterns. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected future growth drivers. Key forecast inputs included smartphone penetration rates and e-commerce transaction volumes.
The analysis sits within stated boundaries; outcomes outside significant regulatory shifts or unforeseen technological disruptions would require recalibration. Forecasts reflect assumptions regarding economic stability and consumer privacy preferences. Practitioners should keep alternative scenarios live as data privacy regulations and platform policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Global Cross Platform and Mobile Advertising Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Global Print Advertising Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Malaysia OOH and DOOH Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
Digital OOH Advertising Market
Advertising and Marketing Media
Adtech Market