
 Europe Programmatic Advertising Market | 2026-2036
Europe Programmatic Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Programmatic Advertising Market Foresight
The EU Green Deal's digital sustainability reporting requirements under CSRD is shifting how advertisers measure and disclose the carbon footprint of their media buys. Criteo leverages its commerce-focused data graph to sustain retail media dominance across French and German markets. Google (DV360) anchors the largest demand-side platform footprint in Europe, while The Trade Desk competes through its open-market UID2 identity framework.
Programmatic advertising denotes the algorithmic buying and selling of digital ad impressions through real-time bidding auctions, typically executing transactions within 100 milliseconds via ad exchanges connected to supply-side platforms and demand-side platforms. The primary commercial purpose centers on delivering targeted audience exposure at scale while optimizing cost-per-acquisition metrics through machine learning-based bid shading and frequency capping. Display Ads retain the largest volume share across European inventory pools, though Video Ads capture disproportionate margin as connected television supply tightens. Demand-side platform technology leads R&D investment as advertisers seek interoperable identity resolution outside deprecating third-party cookies.
GDPR enforcement by national data protection authorities and the EU AI Act's risk classification for automated decision-making systems are tightening consent requirements and algorithmic transparency obligations across the European Economic Area. The European Data Protection Board's cross-border enforcement mechanisms shape market access for non-European technology providers. EDPB guidelines on valid consent are forcing infrastructure investments in first-party data architecture and clean room deployments. Stakeholders must monitor how the Digital Markets Act's gatekeeper designations restructure platform access terms for independent ad technology vendors.
Market Dynamics
Retail media networks are consolidating automated inventory buying across Europe, compressing traditional display ad margins while redirecting brand budgets toward first-party data architectures. The EU AI Act's risk classification system for automated decision-making is forcing infrastructure rebuilds across the supply chain.
Growth Catalysts
- CSRD carbon disclosure mandates:Advertisers must now measure and report the environmental footprint of media buys, creating demand for carbon-aware programmatic platforms and clean room verification tools.
- Connected television inventory expansion:Broadcasters in Germany and France are opening premium video supply to programmatic pipes, capturing brand budgets that previously flowed through direct insertion orders.
- Retail media network automation:Commerce data graphs from major European retailers are enabling closed-loop attribution that outperforms open-market cookie-based targeting.
Market Restraints
- GDPR enforcement fragmentation:National data protection authorities in France, Germany, and Ireland apply divergent consent standards, multiplying compliance costs for cross-border campaigns.
- Third-party cookie deprecation:Google's Chrome phaseout timeline uncertainty is freezing R&D budgets as advertisers delay identity infrastructure commitments.
- Supply-side platform concentration:A handful of dominant exchanges control premium publisher inventory access in the United Kingdom and France, elevating take rates.
Strategic Opportunities
- UID2 and first-party identity frameworks:Advertisers adopting interoperable identity solutions are capturing addressable inventory as third-party signals degrade.
- Poland and Nordic markets:Underpenetrated programmatic adoption in Warsaw and Stockholm media markets offers expansion paths for demand-side platforms with localized language support.
- AI Act algorithmic transparency tools:Compliance software for automated bidding systems represents an emerging revenue stream as risk classification deadlines approach.
Industry Challenges
- Clean room engineering talent scarcity:Privacy-preserving data collaboration requires specialized cryptography and distributed systems expertise that commands premium compensation in London and Berlin.
- Legacy ad server integration friction:Publishers operating decades-old order management systems face multi-year migration timelines to enable real-time bidding infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Programmatic Advertising Market |
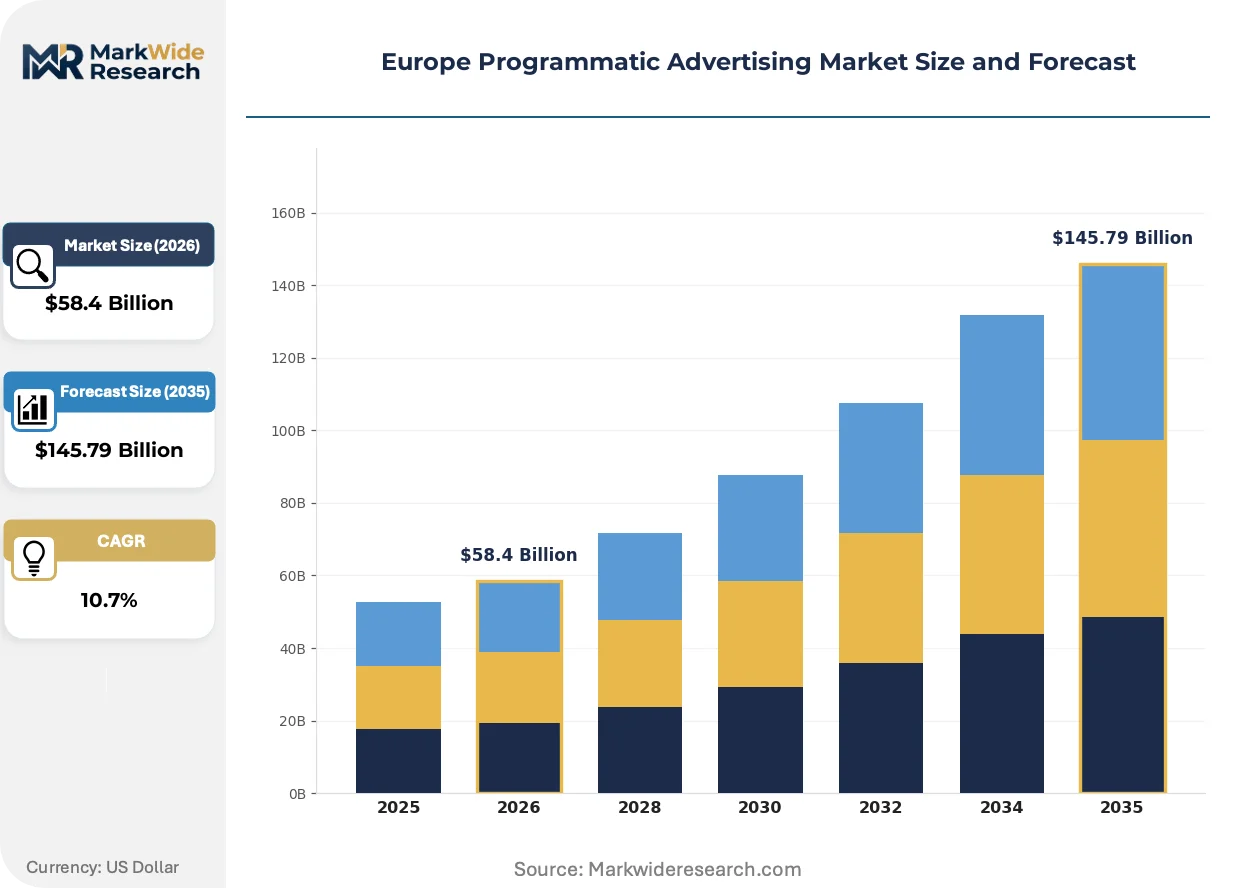
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $145.79 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Display Ads, Video Ads, Social Media Ads, Mobile Ads Ad Format: Standard Banner, Rich Media, Native Ads, Interstitials Technology: DMP, DSP, Ad Exchange, SSP Client Type: Advertisers, Agencies, Publishers, Brands |
| Companies Covered | Criteo, Adform, Google (DV360), Gamned!, datashake, The Trade Desk, Magnite, Tradelab, Amazon DSP, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Programmatic Advertising Market Shifts & Advancements
Algorithmic buying infrastructure is bifurcating between walled-garden retail media and open-market identity solutions, with regulatory pressure accelerating architectural decisions that were previously deferred.
Server-side ad insertion technology is expanding into connected television workflows, enabling broadcasters to replace client-side ad calls that leak audience data. French and German public service broadcasters are adopting these stacks to maintain GDPR compliance while opening inventory to programmatic demand. The technology is expanding into addressable linear television, compressing the technical distinction between digital video and traditional broadcast.
The EU AI Act's risk classification for automated decision-making systems is mandating algorithmic impact assessments for programmatic platforms operating in the European Economic Area. High-risk designations apply to systems processing sensitive audience data for targeted advertising, forcing documentation of training data provenance and bias testing. German regulators are leading enforcement, with the Federal Cartel Office coordinating closely with data protection authorities on dual competition-privacy investigations.
Commerce data collaboration is displacing demographic targeting as the primary audience construction method for consumer brands. Retail media networks in France and the United Kingdom are offering closed-loop measurement that ties ad exposure to in-store and online purchase behavior. Automotive and consumer packaged goods advertisers are reallocating budget toward these environments, reducing reliance on open-web prospecting that lacks transaction-level attribution.
Europe Programmatic Advertising Market Segmentation
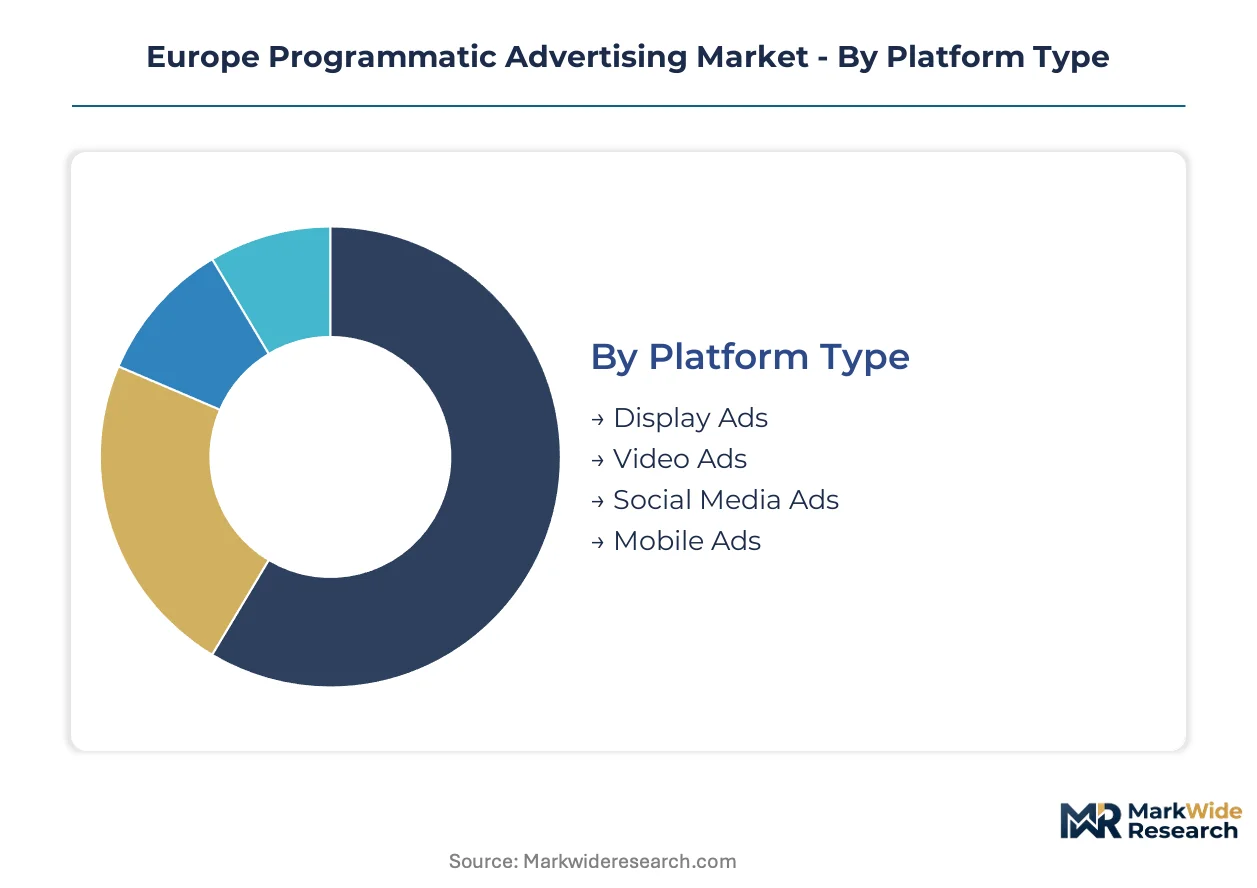
Programmatic advertising infrastructure fragments across platform architectures, creative formats, and technology layers. Buyers select combinations based on attribution precision, inventory access, and compliance architecture under GDPR and the EU AI Act.
Platform Type:
Budget allocation patterns diverge sharply based on whether buyers prioritize reach scale or closed-loop measurement.
- Display Ads:Standard IAB-format inventory transacts through open exchanges at high velocity. German and French retail media networks are compressing margins here as first-party data targeting outperforms cookie-based prospecting.
- Video Ads:Connected television supply from broadcasters in the United Kingdom and Germany commands premium CPMs through private marketplace deals. Inventory scarcity is accelerating server-side ad insertion adoption.
- Social Media Ads:Walled-garden environments from Meta and TikTok operate outside standard RTB infrastructure. Buyers access these through platform-native APIs rather than independent DSPs.
- Mobile Ads:In-app inventory from gaming and utility publishers dominates this segment. IDFA deprecation on Apple devices has shifted demand toward Android supply and SKAdNetwork modeling.
Display Ads lead volumes today; Video Ads are gaining share fastest.
Ad Format:
Creative specifications determine technical integration requirements and viewability measurement approaches.
- Standard Banner:Fixed-dimension units (300x250, 728x90) remain the workhorse of open-exchange trading. Polish and Nordic publishers rely heavily on this inventory as premium video supply remains limited.
- Rich Media:Expandable and interactive units require specialized ad serving and creative production workflows. Automotive advertisers in Germany deploy these for configurator integrations.
- Native Ads:In-feed placements mimic editorial content format. French publishers have standardized specifications through the IAB France Native Advertising Framework.
- Interstitials:Full-screen mobile placements trigger at natural app transition points. Gaming publishers in the United Kingdom monetize session breaks through programmatic demand.
Standard Banner dominates transaction counts; Native Ads show the steepest expansion trajectory.
Technology:
Infrastructure choices reflect buyer sophistication and data governance maturity.
- DMP:Data management platforms consolidate audience segments from multiple sources. GDPR consent string integration has become a core procurement criterion for German advertisers.
- DSP:Demand-side platforms execute bidding algorithms across inventory sources. The Trade Desk and Google DV360 compete on identity resolution approaches as third-party cookies degrade.
- Ad Exchange:Open-market liquidity pools connect supply and demand through second-price auctions. Supply concentration among a handful of dominant exchanges elevates take rates in the United Kingdom.
- SSP:Supply-side platforms manage publisher yield optimization and auction mechanics. French broadcasters are adopting SSP technology to open connected television inventory programmatically.
DSP commands the largest technology spend; SSP is climbing the fastest as publishers upgrade infrastructure.
Client Type:
Organizational buying centers determine contract structures and platform access tiers.
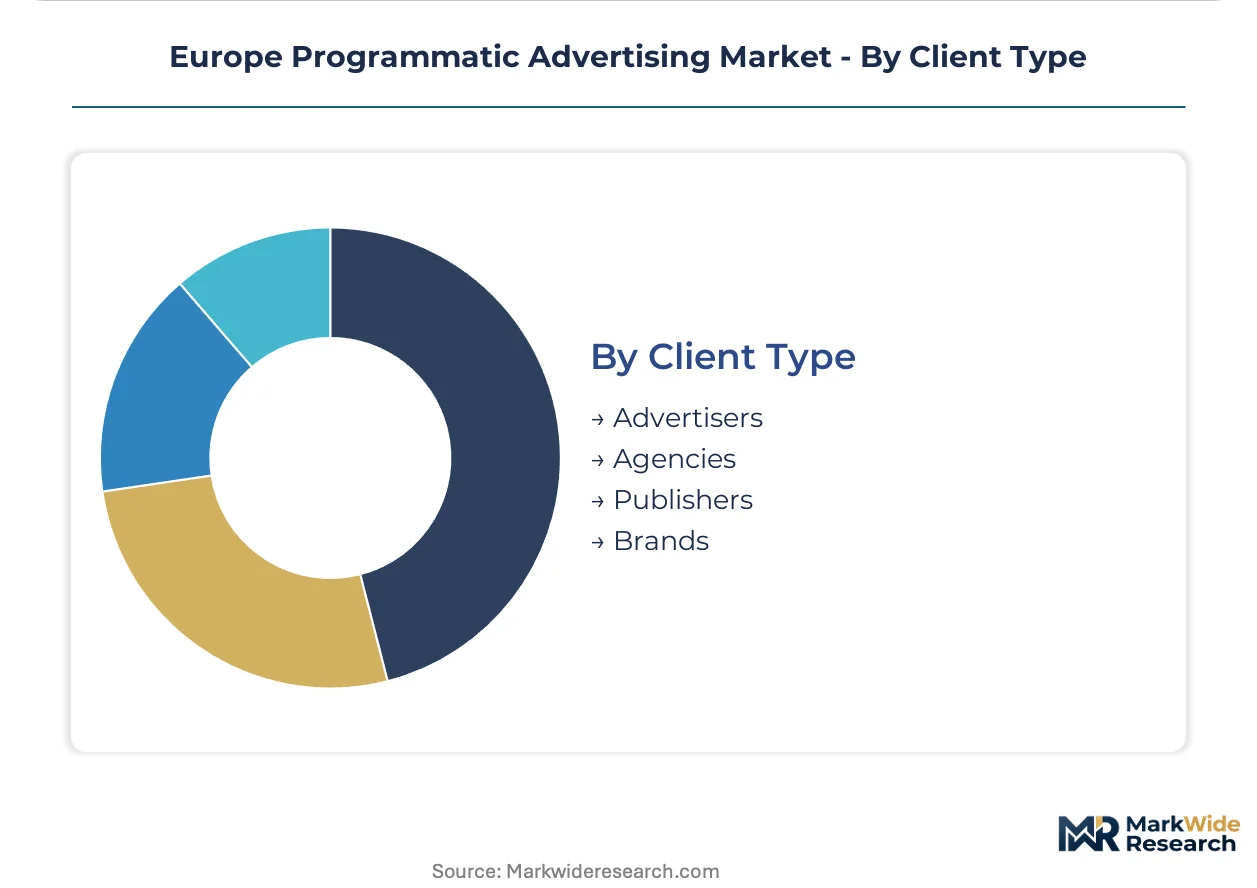
- Advertisers:Direct brand procurement teams negotiate platform licenses and data clean room deployments. Consumer packaged goods companies in Germany are building in-house programmatic capabilities.
- Agencies:Media buying groups aggregate demand across client portfolios. Holding companies face margin pressure as advertisers bring trading desk functions internal.
- Publishers:Inventory owners operate yield optimization and direct sales integration. Public service broadcasters in France balance GDPR compliance with programmatic revenue expansion.
- Brands:End-user marketing organizations define audience strategy and creative standards. Retail media network adoption is strongest among brands with first-party transaction data.
Agencies transact the largest gross volumes; Advertisers are expanding their share fastest through in-housing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Programmatic advertising infrastructure first achieved commercial scale in London and Frankfurt during the early 2010s, establishing the operational templates that later spread across the continent. These initial clusters concentrated demand-side platform engineering talent and publisher yield optimization expertise. Today, national regulatory interpretations of GDPR and the EU AI Act create divergent operating environments across member states.
Germany
Automotive and consumer packaged goods advertisers in Munich and Stuttgart drive substantial demand for closed-loop attribution systems. The Federal Cartel Office coordinates with data protection authorities on dual competition-privacy investigations affecting platform market access. Berlin hosts a dense concentration of supply-side platform engineering teams rebuilding infrastructure for algorithmic transparency compliance.
United Kingdom
London's financial services and luxury fashion sectors sustain premium CPMs for programmatic video inventory. The Information Commissioner's Office enforces consent standards that diverge from continental interpretations, multiplying cross-border campaign complexity. Manchester and Birmingham media markets are expanding connected television supply through broadcaster partnerships with ad technology vendors.
France
Public service broadcasters in Paris are adopting server-side ad insertion to maintain GDPR compliance while opening premium video inventory. The CNIL applies stringent consent validation requirements that shape platform procurement decisions. Lyon and Marseille retail media networks are consolidating automated inventory buying for consumer brands seeking transaction-level attribution.
Netherlands
Amsterdam's digital advertising ecosystem specializes in privacy-preserving data collaboration and clean room deployments. The Dutch Data Protection Authority participates actively in European Data Protection Board guideline development. Rotterdam logistics and e-commerce clusters are driving retail media network expansion across Benelux markets.
Poland
Warsaw's underpenetrated programmatic adoption offers expansion paths for demand-side platforms with localized language capabilities. The Polish data protection regulator applies GDPR standards with distinct procedural timelines affecting campaign launch velocity. Krakow and Wrocław gaming publishers are monetizing in-app inventory through programmatic pipes as mobile ad spending concentrates in these urban centers.
Europe Programmatic Advertising Market Competitive Landscape
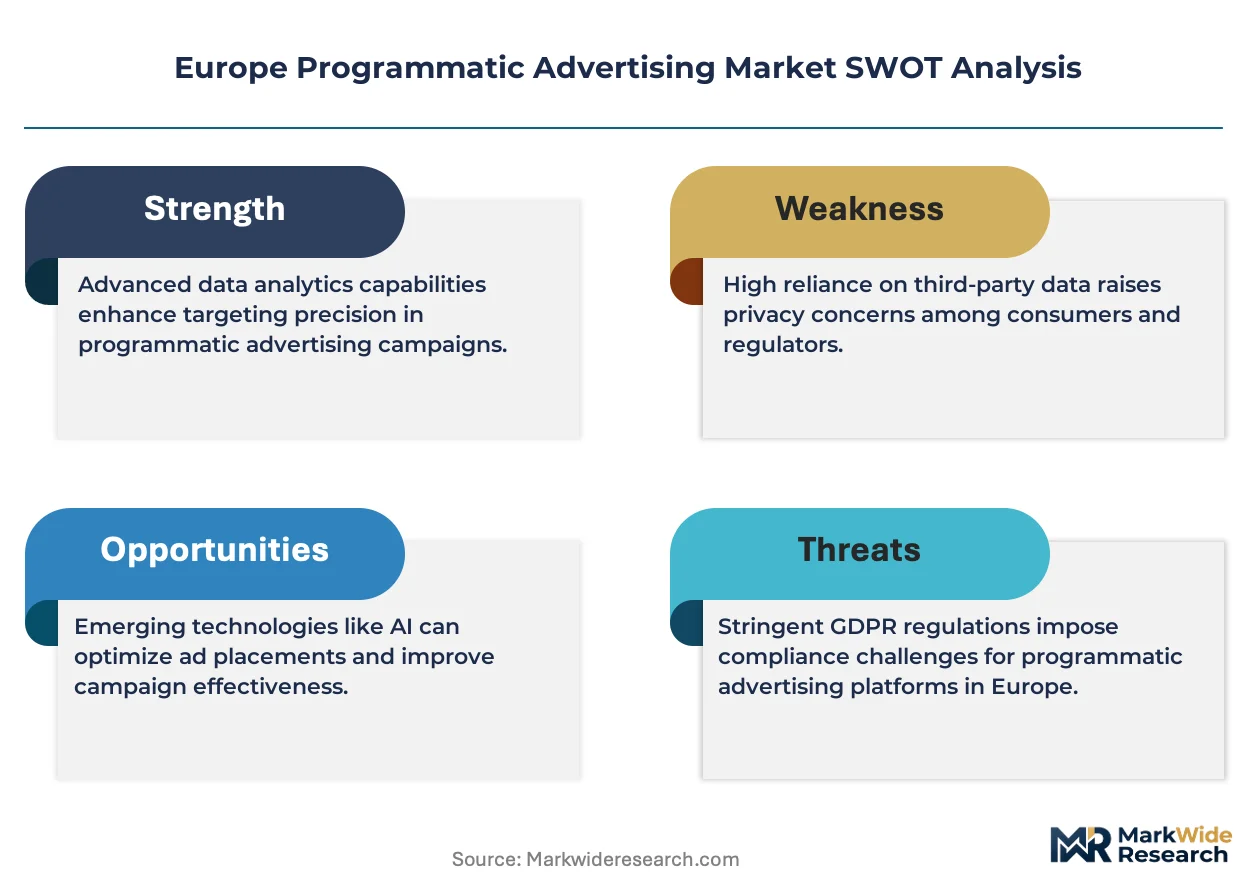
Premium-margin players sit above commodity-margin players across identity resolution sophistication and first-party data architecture depth. The vendor base organizes into three tiers: walled-garden platforms with captive commerce data, independent demand-side platforms competing on interoperable identity frameworks, and supply-side platforms controlling publisher inventory access. Strategic moves concentrate on first-party data clean room deployments and retail media network partnerships. Regulatory compliance tooling represents an emerging differentiation vector as AI Act deadlines approach.
Within the independent demand-side platform tier, The Trade Desk and Google (DV360) occupy positions defined by contrasting identity resolution approaches. Criteo exemplifies the commerce-data-centric archetype through its retail media focus. Among European-headquartered specialists, Adform and Tradelab represent regional platforms competing on localized GDPR compliance architectures.
| Leading Market Players |
|---|
| Criteo |
| Adform |
| Google (DV360) |
| Gamned! |
| datashake |
| The Trade Desk |
| Magnite |
| Tradelab |
| Amazon DSP |
| Others |
Supply & Pricing Matrix
Brand procurement teams at consumer packaged goods companies concentrate demand-side platform spending in annual subscription commitments, anchoring the dominant SaaS-tiered pricing model across European markets. This buyer archetype's volume concentration compresses per-seat rates while elevating platform switching costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs demand-side platform access, with price differentiation driven by data clean room inclusion and GDPR compliance certification tier. Pricing pressure stems from retail media networks capturing brand budgets previously allocated to open-exchange display inventory. Mid-market advertisers exhibit highest price sensitivity, while automotive and luxury brands prioritize attribution precision over cost.
Supply Chain Analysis
Data processing infrastructure refurbishment and server farm remanufacturing flows concentrate supply chain activity in Ireland, the Netherlands, and Germany as cloud providers cycle hardware for energy efficiency compliance. Raw material dependencies include specialized semiconductors for ad-serving acceleration, high-bandwidth fiber optic cable, and rare earth elements for server manufacturing. Single-source vulnerability in custom AI training chip supply from Taiwan elevates risk exposure. Distribution runs through hyperscaler co-location facilities and edge computing nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European programmatic advertising has entered late-cycle quality differentiation as advertisers shift demand toward carbon-aware media buying platforms with verified CSRD disclosure capabilities.
For Market Incumbents: Lock in retail media network partnerships before closed-loop attribution becomes table stakes. Secure first-party data clean room deployments to defend against independent demand-side platforms offering interoperable identity frameworks. Prioritize algorithmic transparency tooling investment as EU AI Act enforcement deadlines approach. For New Entrants and Emerging Players: Enter via Poland and Nordic markets where localized language support gaps persist among established platforms. Target Warsaw-based gaming publishers and Stockholm retail media networks as the most penetrable segments. Lead with GDPR compliance architecture as the primary go-to-market differentiator. For Investors and Strategic Acquirers: Commerce data platform specialists are the most active acquirer category in this space, consolidating retail media technology stacks. Five-to-ten year viability hinges on first-party data architecture depth rather than third-party cookie workarounds. Monitor Federal Cartel Office coordination with data protection authorities as the signal for platform market access restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Clean Room Deployment | Enables GDPR-compliant audience collaboration between retailers and brands in France and Germany. |
| Server-Side Ad Insertion Integration | Allows public service broadcasters to open connected television inventory while maintaining data protection standards. |
| Carbon-Aware Platform Certification | Positions demand-side platforms for CSRD-mandated media buying disclosure requirements. |
| Algorithmic Transparency Tooling | Supports EU AI Act compliance for automated bidding systems processing sensitive audience data. |
| Retail Media Network Partnership | Captures closed-loop attribution budgets shifting from open-web prospecting in United Kingdom markets. |
Research Methodology
Bottom-up advertiser spend modeling reconciled against top-down publisher inventory tracking forms the analytical core of this study. Primary interviews with demand-side platform product managers, publisher yield optimization directors, brand procurement leads, and retail media network operators combined with secondary validation from IAB Europe expenditure reports, national data protection authority enforcement disclosures, and CSRD implementation guidance documents. Triangulation across these sources ensures segment-level precision.
Input-output matrix framing connects platform type, ad format, technology layer, and client type dimensions across the projection horizon. CAGRs derive from segment growth rate reconciliation against macroeconomic indicators and regulatory timeline impacts. Forecast inputs include connected television inventory expansion trajectories, retail media network automation adoption curves, and GDPR consent string implementation rates.
Inputs from European Data Protection Board guideline releases and IAB technical specifications were available through the study window; gaps in real-time enforcement action data from national authorities introduce uncertainty bands. Practitioners should monitor Federal Cartel Office investigation announcements and CNIL consent validation rulings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Middle East and North Africa Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
South East Asia Advertising Market
Advertising and Marketing Media
North America Programmatic Advertisement Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
China OOH and DOOH Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
India OOH and DOOH Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
Europe Public Relation Services Market