
 Social Video Advertising Market | 2026-2036
Social Video Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Social Video Advertising Market Analytics
E-commerce and direct-to-consumer retail is realigning the buyer composition of social video advertising, pulling spend from traditional brand awareness campaigns toward performance-driven formats. Meta Platforms leverages its Reels infrastructure and AI-driven targeting to capture commerce advertiser budgets. ByteDance dominates short-form vertical video through TikTok's Shop integration and native checkout. Google sustains premium CTV inventory through YouTube's connected television expansion.
Social video advertising comprises paid promotional content distributed through algorithmic social platforms, typically rendered in 9:16 vertical aspect ratio with interactive elements and sub-15-second pacing optimized for mobile feed consumption. Its primary commercial purpose is to merge brand storytelling with direct response mechanics, enabling attribution from impression to purchase within closed platform ecosystems. In-stream and story ads command the highest CPMs due to forced-view completion rates and limited skip options, while out-stream inventory carries lower margins but scales across publisher networks. Sponsored content embeds within creator feeds and commands premium pricing where authenticity metrics outperform polished brand assets.
The Federal Trade Commission enforces disclosure requirements for sponsored content and native advertising, compelling platforms to maintain visible labeling standards that affect creative execution and audience trust. The EU Digital Services Act imposes algorithmic transparency obligations and restricts targeted advertising to minors, reshaping platform ad architecture across European operations. GDPR consent frameworks limit granular retargeting pools, pushing advertisers toward contextual and cohort-based alternatives. Stakeholders must monitor regulatory fragmentation between privacy-first jurisdictions and data-permissive markets when allocating platform-specific budgets and building measurement stacks.
Market Dynamics
Platform algorithm changes and privacy regulation are restructuring how advertisers allocate spend across social video inventory, forcing a rebuild of attribution infrastructure around first-party data and closed-loop measurement.
Growth Catalysts
- Shoppable Video Integration:E-commerce platforms are embedding native checkout within vertical video feeds, collapsing the path from impression to transaction. This format pulls budget from static display advertising.
- Connected TV Expansion:YouTube's connected television inventory is capturing premium brand dollars as viewing hours shift from linear broadcast to streaming platforms.
- GDPR Consent Frameworks:European privacy rules are accelerating investment in contextual targeting and cohort-based alternatives, creating new technical capabilities that export globally.
Market Restraints
- Attribution Fragmentation:Apple's App Tracking Transparency framework has degraded cross-platform measurement, forcing advertisers to maintain parallel attribution systems.
- Creative Production Costs:The volume demands of algorithmic feeds require continuous short-form asset generation, inflating operational expenditure versus traditional campaign cycles.
- Platform Concentration Risk:Dependence on Meta and ByteDance infrastructure creates pricing power asymmetry and inventory access vulnerability for media buyers.
Strategic Opportunities
- Creator Economy Infrastructure:Mid-tier influencer networks in India and Brazil remain undermonetized relative to audience scale, offering CPM arbitrage for early entrants.
- AI-Generated Creative:Generative video tools are converging with dynamic creative optimization, enabling real-time asset personalization at previously impossible production economics.
- EU Digital Services Act:Algorithmic transparency mandates are creating compliance service demand and opening inventory access for smaller advertisers previously disadvantaged by opaque ranking systems.
Industry Challenges
- Measurement Standardization:The absence of unified viewability and engagement metrics across TikTok, Instagram Reels, and YouTube Shorts complicates cross-platform budget allocation.
- First-Party Data Infrastructure:Building direct consumer relationships requires CRM and data engineering capabilities that strain mid-market advertiser technical capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Video Advertising Market |
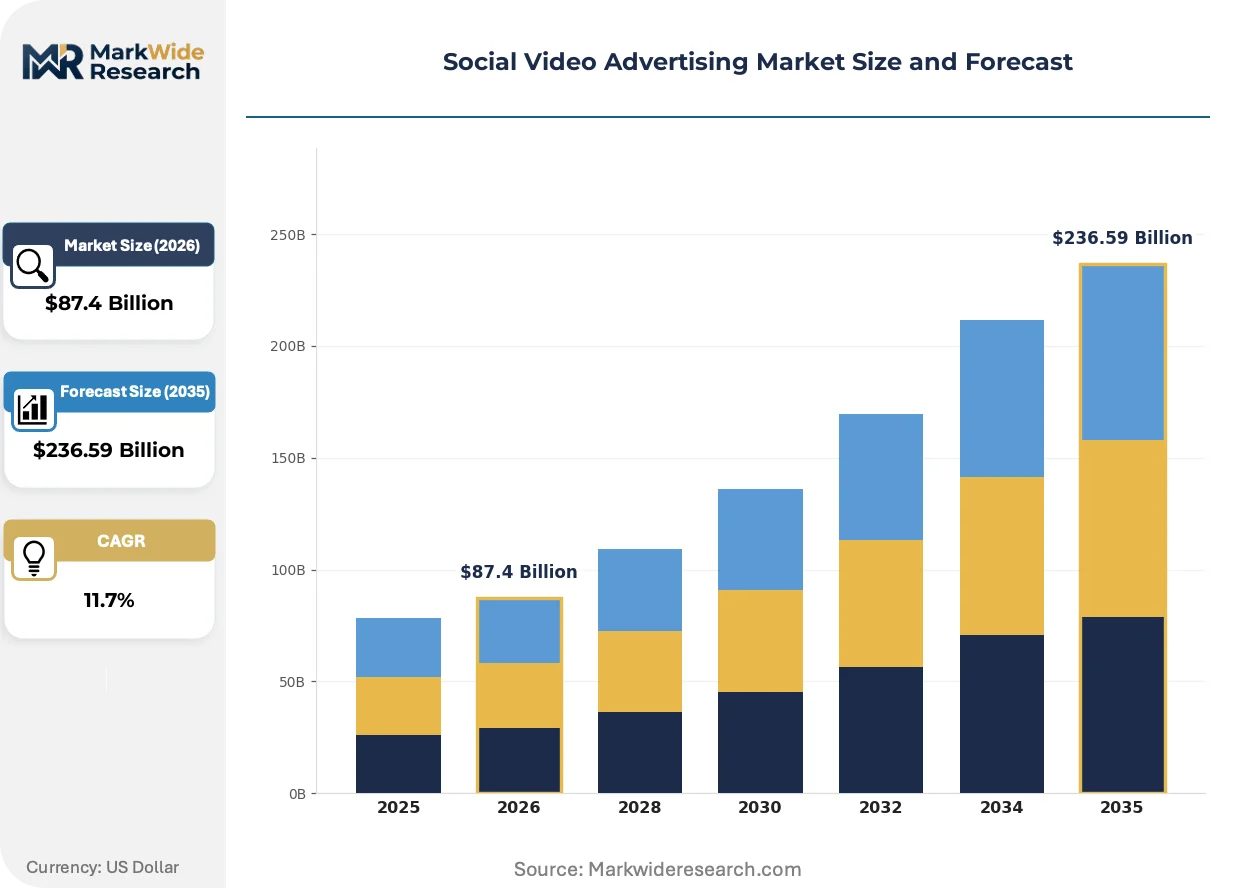
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $236.59 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Facebook, Instagram, YouTube, TikTok Ad Format: In-Stream, Out-Stream, Story Ads, Sponsored Content Target Audience: Millennials, Gen Z, Professionals, Parents Measurement Metric: Viewability, Engagement Rate, Click-Through Rate, Conversion Rate |
| Companies Covered | Meta Platforms, Inc., Google LLC, Amazon.com, Inc., ByteDance Ltd., PubMatic, Inc., Tremor International Ltd., SpotX, Inc., Innovid, The Trade Desk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Video Advertising Market Evolving Landscape
Artificial intelligence is compressing creative production timelines while privacy regulation fragments measurement standards, creating divergent technical requirements across jurisdictions.
Generative video production tools are overtaking traditional agency workflows for short-form social assets. Direct-to-consumer brands with high SKU velocity are adopting these systems fastest, often producing hundreds of variant creatives weekly. This compression is overtaking the conventional creative development cycle and collapsing the cost structure for performance marketing.
The EU Digital Services Act imposes algorithmic transparency obligations on platforms operating across European markets. This regulation forces disclosure of content ranking parameters and restricts targeted advertising to minors, compelling architectural changes in ad delivery systems. Platforms are responding by segmenting European technical infrastructure from global stacks, increasing operational complexity.
Commerce advertisers are consolidating spend with platforms offering closed-loop attribution from impression to purchase. This behavioral shift favors TikTok Shop and Instagram Checkout over open-web video inventory that lacks native transaction data. The concentration is most visible among beauty and apparel verticals in the United States, where return-on-ad-spend visibility determines budget allocation.
Social Video Advertising Market Segmentation
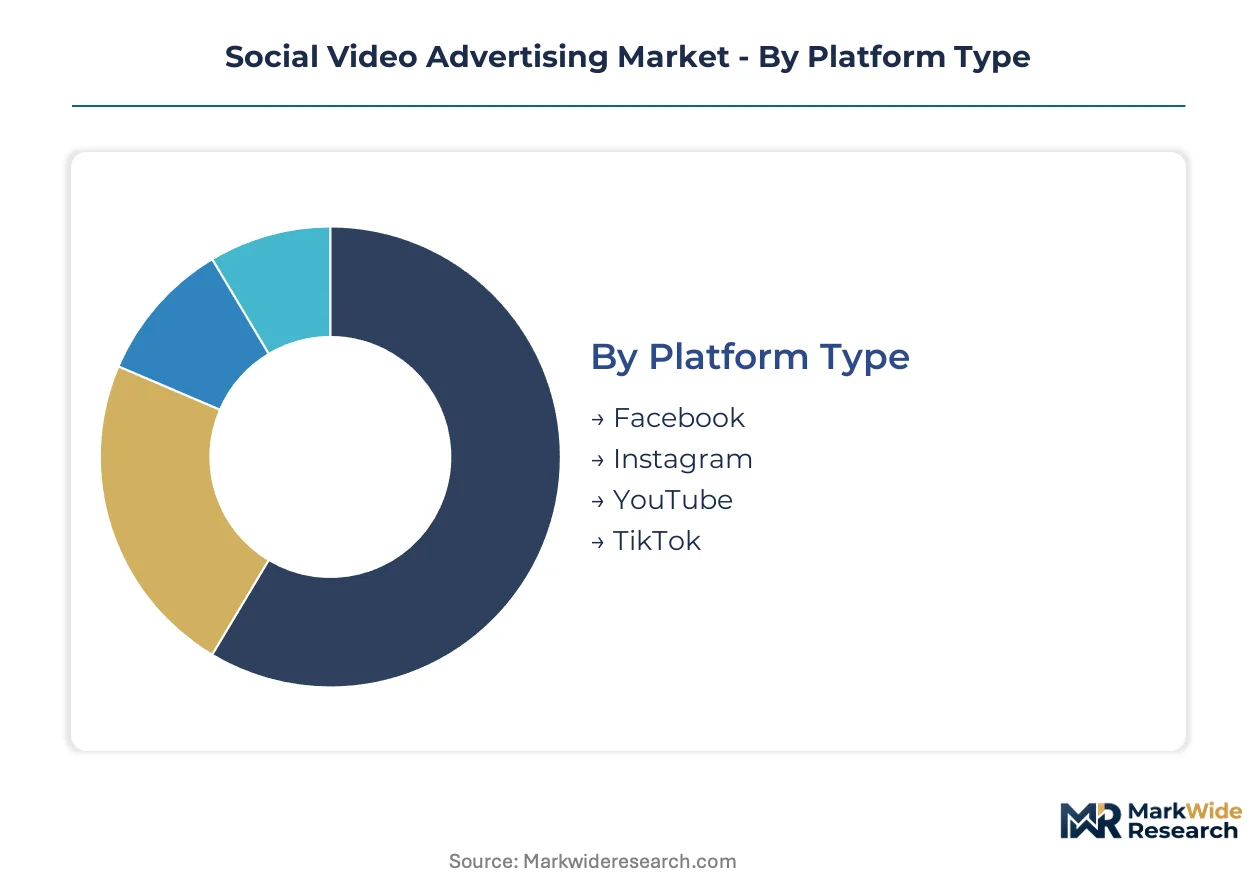
Social video advertising segmentation determines budget allocation efficiency across algorithmic platforms with divergent creative specifications and attribution capabilities. Advertisers match platform infrastructure to campaign objectives, balancing forced-view completion against scalable reach.
Platform Type:
Upgrade cycles in ad tech infrastructure drive advertiser migration toward platforms with superior closed-loop measurement and native commerce integration.
- TikTok:ByteDance's vertical video engine dominates short-form engagement through algorithmic content distribution and TikTok Shop checkout integration. Beauty and apparel advertisers in the United States concentrate spend here for attributable return-on-ad-spend visibility.
- Instagram:Meta's Reels infrastructure leverages AI-driven targeting to capture commerce budgets migrating from static display formats. The platform's creator economy tools and in-app checkout sustain premium pricing for direct-to-consumer campaigns.
- YouTube:Google's connected television inventory captures brand dollars shifting from linear broadcast as viewing hours migrate to streaming platforms.
- Facebook:The platform's aging user base sustains reach for parent and professional demographics, though Reels adoption lags vertical-native competitors.
TikTok sits at the top of the volume ranking for Gen Z engagement, with YouTube climbing the fastest in connected television ad spend.
Ad Format:
Cost tier differentiation separates premium forced-view inventory from scalable out-stream alternatives with variable completion rates.
- In-Stream:Pre-roll and mid-roll placements command elevated CPMs through non-skippable completion requirements. Connected television inventory within this format captures brand safety budgets from linear television advertisers.
- Story Ads:Full-screen vertical placements with limited skip options sustain engagement rates above feed-based alternatives. Instagram and Snapchat infrastructure dominates this category for direct response campaigns.
- Sponsored Content:Creator-embedded placements command authenticity premiums where organic performance metrics outperform polished brand assets.
- Out-Stream:Publisher network distribution enables scale across non-video content environments at reduced CPMs with lower viewability guarantees.
In-Stream maintains the highest revenue concentration, while Sponsored Content expands most quickly as creator economy infrastructure matures.
Target Audience:
Customer type segmentation aligns creative velocity requirements with generational consumption patterns and purchase authority.
- Gen Z:Vertical-native consumption habits demand sub-15-second pacing with interactive elements. TikTok and Instagram Reels capture disproportionate attention share from this cohort.
- Millennials:Cross-platform usage spans short-form discovery and long-form consideration, requiring asset adaptation across YouTube Shorts and connected television.
- Parents:Facebook and YouTube sustained viewership supports higher-consideration purchase decisions with longer creative formats.
- Professionals:LinkedIn video and YouTube command B2B campaign allocation, though volume remains concentrated in consumer platforms.
Gen Z commands the steepest creative investment per capita, with Parents delivering the highest average transaction values for commerce advertisers.
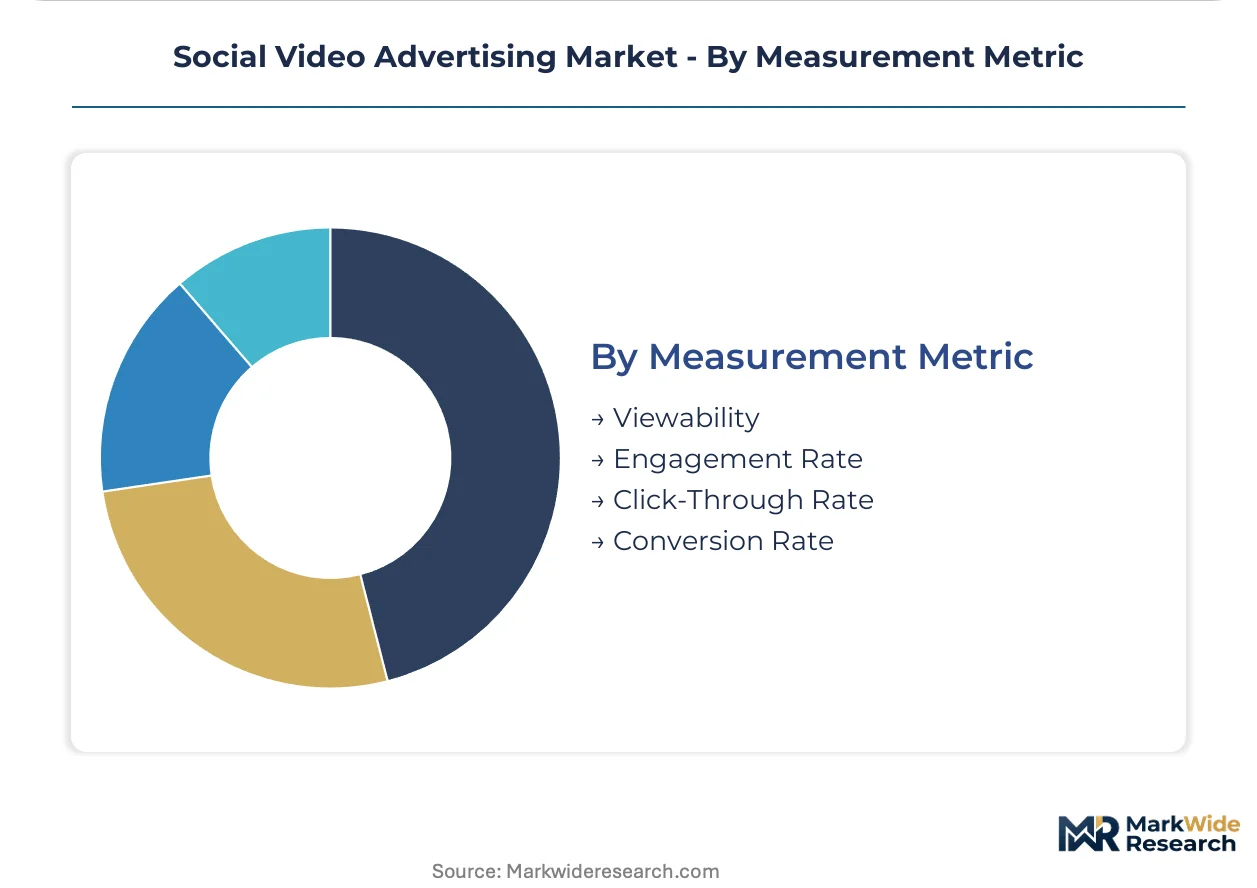
Measurement Metric:
Margin pressure from privacy regulation fragments attribution infrastructure, forcing parallel measurement system maintenance across jurisdictions.
- Conversion Rate:Closed-loop platform attribution from impression to purchase determines budget consolidation with TikTok Shop and Instagram Checkout. Commerce advertisers prioritize this metric above upper-funnel alternatives.
- Viewability:MRC standards for valid video impressions remain inconsistent across TikTok, Instagram Reels, and YouTube Shorts, complicating cross-platform comparison.
- Engagement Rate:Shares, saves, and comments indicate organic amplification potential for creator-sponsored content.
- Click-Through Rate:Signal degradation from Apple's App Tracking Transparency framework has reduced reliability for cross-platform retargeting optimization.
Conversion Rate anchors commerce advertiser decision frameworks, with Viewability gaining priority as third-party verification demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting social video advertising investment toward jurisdictions with permissive data frameworks and mature creator economy infrastructure. Advertisers migrate budgets from privacy-restrictive markets to regions offering granular targeting and closed-loop attribution.
United States
Connected TV inventory and TikTok Shop integration drive concentrated advertiser spend. The FTC enforces disclosure requirements for sponsored content, compelling platforms to maintain visible labeling standards. Los Angeles and New York anchor creator economy production clusters where influencer marketing agencies scale vertical video output for commerce brands.
China
ByteDance's domestic Douyin platform generates attributable commerce transactions through native checkout integration. SAMR and MIIT oversee algorithmic transparency and data localization requirements that shape platform architecture. Beijing and Hangzhou host the densest concentration of short-form video production studios serving live-stream commerce verticals.
United Kingdom
London's advertising agency ecosystem commands premium creative production for European campaign deployment. GDPR consent frameworks limit granular retargeting pools, pushing advertisers toward contextual targeting alternatives. The city's fintech and luxury brand concentration sustains demand for sophisticated attribution modeling.
India
Mid-tier influencer networks remain undermonetized relative to audience scale, offering CPM arbitrage for early entrants. TRAI guidelines on digital advertising transparency affect platform disclosure obligations. Mumbai and Bangalore concentrate creator economy infrastructure where regional language content production scales for vernacular market penetration.
Brazil
Latin America's largest social media user base attracts platform investment in localized commerce features. ANVISA and consumer protection agencies enforce advertising standards for health and beauty verticals. São Paulo anchors the regional headquarters for major platform sales operations serving Portuguese-language advertisers.
Social Video Advertising Market Competitive Landscape
Platform algorithm upgrades dominate the current competitive landscape as infrastructure investments determine advertiser budget capture. The market structure concentrates around three technology giants with closed-loop commerce capabilities and a tier of specialized ad tech vendors serving open-web inventory. Two strategic archetypes define positioning: vertically integrated platform operators and independent demand-side platforms. Competitive moves center on AI-driven creative tools and first-party data infrastructure expansion.
Within the integrated platform tier, Meta Platforms, Inc. and ByteDance Ltd. exemplify the commerce-attribution archetype through Reels and TikTok Shop infrastructure. Google LLC occupies a distinct position spanning short-form mobile inventory and premium connected television. Among independent ad tech vendors, The Trade Desk represents the demand-side platform model focused on unified cross-channel buying.
| Leading Market Players |
|---|
| Meta Platforms, Inc. |
| Google LLC |
| Amazon.com, Inc. |
| ByteDance Ltd. |
| PubMatic, Inc. |
| Tremor International Ltd. |
| SpotX, Inc. |
| Innovid |
| The Trade Desk |
| Others |
Value Network & Pricing Analysis
Captive production of short-form video assets through in-house creative studios anchors supply positioning for direct-to-consumer advertisers while compressing pricing power across agency-dependent competitors. This integration choice collapses production timelines from weeks to days, enabling real-time creative iteration that outsourced models cannot match.
Pricing Analysis
Platform take rates function as the dominant channel-margin layer, with Meta and ByteDance extracting substantial revenue shares before media buyers access inventory. Pricing stratifies across premium connected television, standard in-feed placements, and economy out-stream networks based on viewability guarantees and attribution depth. Cost compression in mid-tier creator sponsorships is intensifying because AI-generated creative tools democratize production capabilities previously requiring agency retainers. Direct-to-consumer brands with high SKU velocity exhibit lowest price sensitivity, while mid-market advertisers dependent on third-party production face margin erosion.
Supply Chain Analysis
Certification gaps in viewability measurement create gating friction as advertisers demand MRC-accredited verification across TikTok, Instagram Reels, and YouTube Shorts. Creative production concentrates in the United States, China, and the United Kingdom where platform sales operations and influencer marketing agencies cluster. Raw material dependencies include cloud compute capacity for AI rendering, licensed music catalogs for audio synchronization, and creator talent pools for authenticity-driven campaigns. Single-source vulnerability runs through ByteDance's algorithmic distribution infrastructure. Distribution runs through programmatic pipes and direct platform sales teams serving commerce advertisers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where advertisers redirect spend from GDPR-restrictive European markets toward the United States and privacy-permissive Asian jurisdictions offering granular targeting and closed-loop attribution.
For Market Incumbents: Deploy first-party data infrastructure as the primary defensive lever against Apple's App Tracking Transparency degradation and Google's cookie deprecation. Consolidate measurement stacks around closed-loop platform attribution while building direct consumer relationships through CRM investments. Threat substitution from retail media networks demands immediate response through commerce integration depth. For New Entrants and Emerging Players: Begin with mid-tier influencer networks in India and Brazil where CPM arbitrage opportunities persist against undermonetized audience scale. Target vernacular language content production for regional market penetration. Go-to-market angle centers on AI-powered creative generation serving high-velocity SKU advertisers. For Investors and Strategic Acquirers: Roll-up economics work for specialized creator economy infrastructure because platform algorithm opacity disadvantages smaller advertisers seeking transparency tools. Long-term viability hinges on regulatory fragmentation persisting across privacy-first and data-permissive jurisdictions. Acquisition target archetype: AI-native creative production platforms with direct-to-consumer brand relationships. Signal to watch is EU Digital Services Act enforcement intensity as inventory access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Creative Production | Generative video tools collapse asset generation costs for high-velocity commerce advertisers. |
| First-Party Data Infrastructure | CRM and data engineering capabilities rebuild attribution degraded by Apple's privacy framework. |
| Connected TV Inventory Expansion | YouTube's streaming capture redirects linear broadcast budgets toward addressable premium placements. |
| Creator Economy Platform Rollup | Mid-tier influencer network consolidation unlocks CPM arbitrage in undermonetized regional markets. |
| Closed-Loop Commerce Integration | Native checkout embedding collapses path from impression to transaction for attributable ROAS visibility. |
Research Methodology
Multiple input streams — platform sales leadership interviews, media buyer procurement panels, and creator economy operator discussions — were reconciled against regulatory filing analysis and ad tech vendor disclosures. Primary engagement spanned chief marketing officers, programmatic trading desk heads, influencer talent agency principals, and platform policy leads. Secondary validation drew from FTC enforcement actions, EU Digital Services Act implementation guidance, platform transparency reports, and commerce advertiser earnings disclosures. Bottom-up spend estimates were triangulated against top-down platform revenue attribution.
Historical growth patterns were cross-referenced against expert panel consensus to anchor projection assumptions across the modeling period. Segmentation dimensions modeled include platform type, ad format, target audience demographic, and measurement metric preference. CAGRs were derived from spend trajectory analysis calibrated to privacy regulation impact severity. Industry-specific forecast inputs encompassed TikTok Shop transaction velocity, Reels monetization rate progression, and connected television inventory expansion curves.
Several conditions sit outside the modeled scope, including unannounced platform algorithm changes, geopolitical restrictions on ByteDance operations, and breakthrough privacy legislation beyond current regulatory frameworks. Forecasts reflect assumptions around sustained commerce advertiser budget migration and creator economy infrastructure maturation. A model refresh is warranted upon material change in Apple or Google privacy policy enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Brazil OOH and DOOH Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market
Advertising and Marketing Media
Digital Advertising Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
Europe Programmatic Advertising Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
ASEAN OOH and DOOH Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Programmatic Advertising Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
Social Media Advertisement Market