
 Digital OOH Advertising Market | 2026-2036
Digital OOH Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Digital OOH Advertising Market Intelligence
Retail brands are realigning their media spend toward point-of-sale digital networks. JCDecaux SA leverages its street furniture concessions in European capitals to sustain premium inventory rates. Lamar Advertising Company anchors its growth strategy on highway digital billboard conversions across the United States. OUTFRONT Media Inc. competes through transit authority partnerships in North American metropolitan rail systems.
Digital out-of-home advertising comprises networked electronic display systems deployed in public and semi-public spaces for commercial messaging, typically operating through content management platforms that enable remote scheduling and real-time creative rotation. These systems rely on LED and LCD display technologies with brightness ratings exceeding 5,000 nits for daylight visibility, serving advertisers seeking audience reach outside residential media environments. Video ads command premium placement rates due to higher engagement metrics versus static creative formats. Dynamic campaigns integrating live data feeds represent the fastest-expanding content category as advertisers demand contextual relevance. Digital billboards retain the largest revenue share among medium types, though transit displays are gaining share in dense urban corridors.
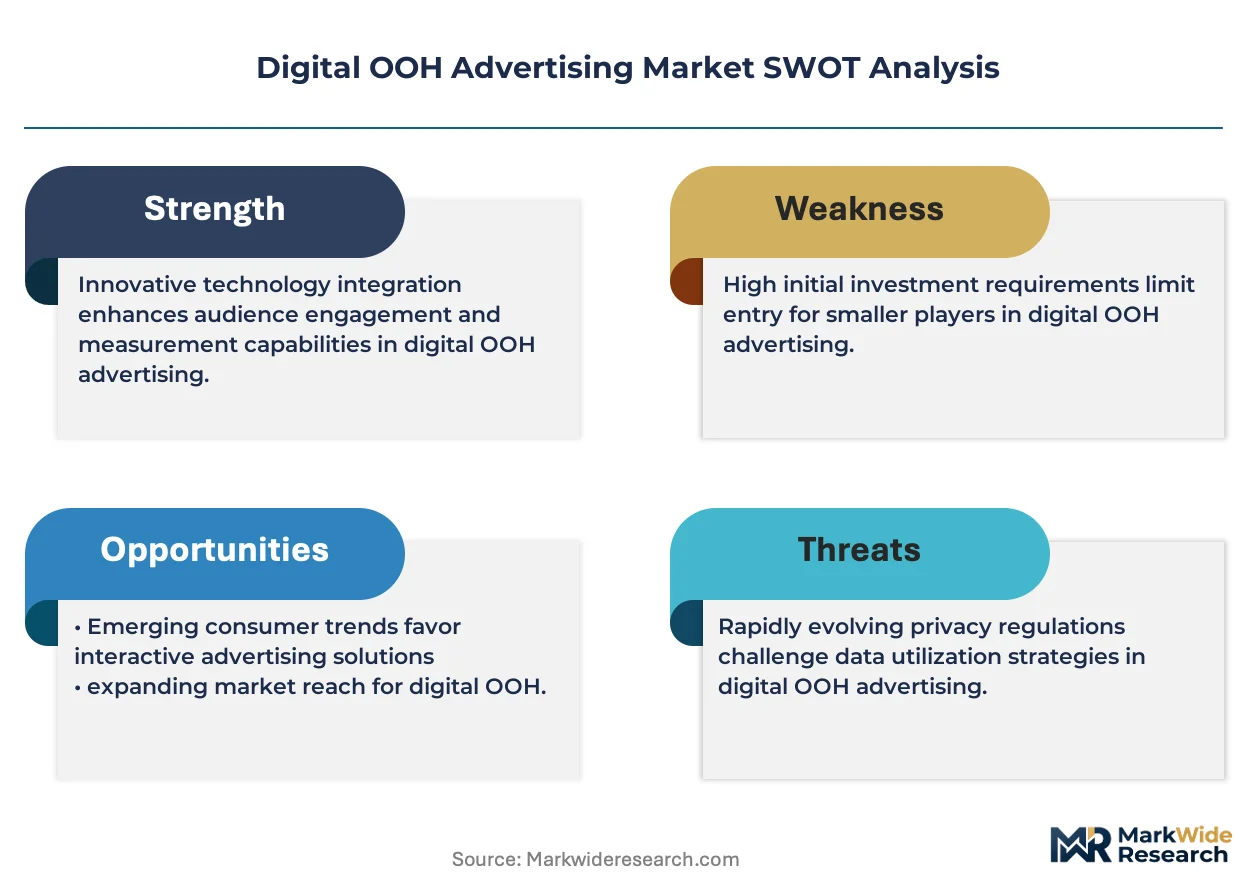
The FCC governs electronic display emissions and spectrum use for wireless content delivery in the United States, while the EU Green Deal's energy efficiency standards constrain display power consumption across European deployments. China's SAMR oversees advertising content compliance on digital screens, creating a fragmented compliance landscape for multinational operators. Stakeholders must weigh capital intensity against concession renewal timelines when allocating deployment budgets across medium types.
Market Dynamics
Transit authorities and municipal governments are accelerating digital screen deployments in urban corridors, while the EU Green Deal's energy efficiency directives force display manufacturers toward lower-power LED technologies. This dual pressure from infrastructure expansion and environmental compliance is compressing equipment replacement cycles.
Growth Catalysts
- EU Green Deal energy standards:European energy efficiency directives mandate reduced power consumption for public displays, accelerating replacement of legacy high-wattage systems with efficient LED arrays.
- China tier-one urban density:Elevator screen networks in high-rise residential and commercial towers capture captive commuter audiences during daily vertical transit.
- Real-time data integration:Dynamic content management platforms enable contextual creative rotation based on weather, traffic, and audience analytics.
Market Restraints
- Concession renewal concentration:Long-term municipal contracts for transit corridor and street furniture placements create barriers to new entrants in established European and North American markets.
- LED component supply volatility:Semiconductor substrate shortages and rare earth element pricing swings disrupt display manufacturing lead times.
- SAMR content compliance friction:China's advertising content regulations require pre-approval workflows that delay campaign deployment timelines.
Strategic Opportunities
- India smart city infrastructure:Municipal digital signage integration into urban transit and public safety networks remains underpenetrated relative to population density.
- FCC spectrum allocation:Expanded wireless content delivery frequencies enable remote management of highway billboard networks without fiber trenching.
- Programmatic trading convergence:Integration of OOH inventory into automated media buying platforms bridges traditional and digital advertising workflows.
Industry Challenges
- Installation coordination complexity:Highway digital billboard conversions require simultaneous electrical infrastructure upgrades and permitting across multiple jurisdictions.
- Content localization talent scarcity:Real-time creative adaptation for multilingual urban corridors demands specialized motion design capabilities that outpace workforce supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital OOH Advertising Market |
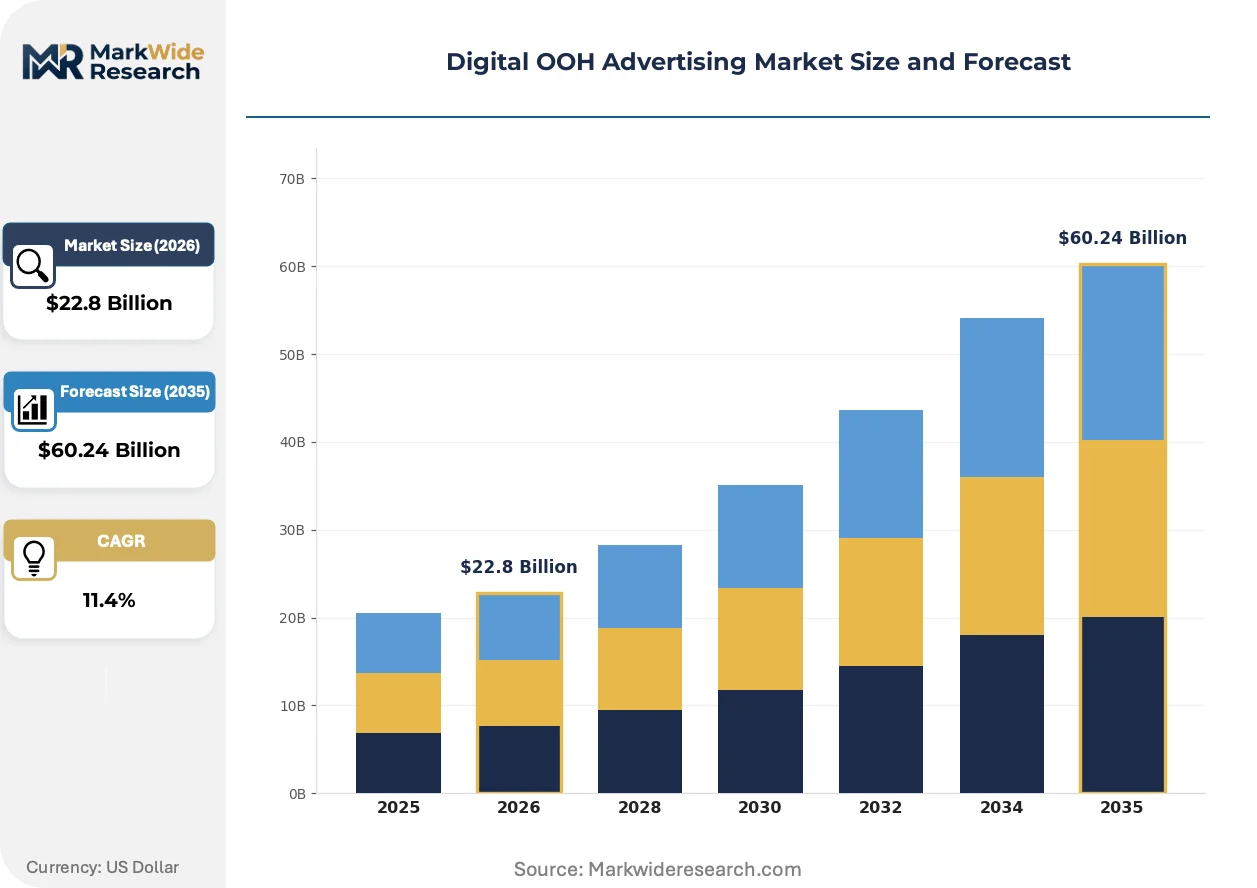
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $60.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medium Type: Digital Billboards, Transit Displays, Retail Screens, Street Furniture End User: Advertisers, Media Agencies, Retailers, Entertainment Content Type: Static Ads, Video Ads, Interactive Content, Dynamic Campaigns Technology: LED Displays, LCD Screens, Projection Mapping, Augmented Reality |
| Companies Covered | OUTFRONT Media Inc., Focus Media Information Technology Co Ltd, JCDecaux SA, Broadsign International LLC, oOh!media Limited, Clear Channel Outdoor Holdings, Inc., Ströer SE & Co. KGaA, Daktronics Inc., Lamar Advertising Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital OOH Advertising Market Strategic Shifts & Innovations
Cloud-based content management architectures are displacing on-premise server installations, enabling centralized creative deployment across dispersed screen networks. This infrastructure shift reduces operational overhead while accelerating campaign turnaround.
Edge computing nodes embedded within display housings are decentralizing content rendering from central servers to local processing units. Transit authorities in Germany and the Netherlands are deploying these systems to enable sub-second creative swaps based on train arrival data. The technology is decentralizing network architecture decisions away from IT departments toward operations teams managing physical infrastructure.
The EU Green Deal's F-Gas Regulation and ecodesign requirements are phasing out high-consumption display backlighting systems across member states. Manufacturers must redesign thermal management and power supply subsystems to meet standby wattage ceilings. Outdoor billboard deployments in France and Italy are most affected, with operators accelerating LED retrofit schedules to avoid non-compliance penalties.
Media buyers are consolidating spend through fewer agency partnerships while demanding impression-level verification metrics. This concentration is compressing the number of authorized resellers while elevating technical requirements for audience measurement integration. The shift is most visible in the United States, where large retail brands now require accredited third-party verification for all highway and transit network placements.
Digital OOH Advertising Market Segmentation
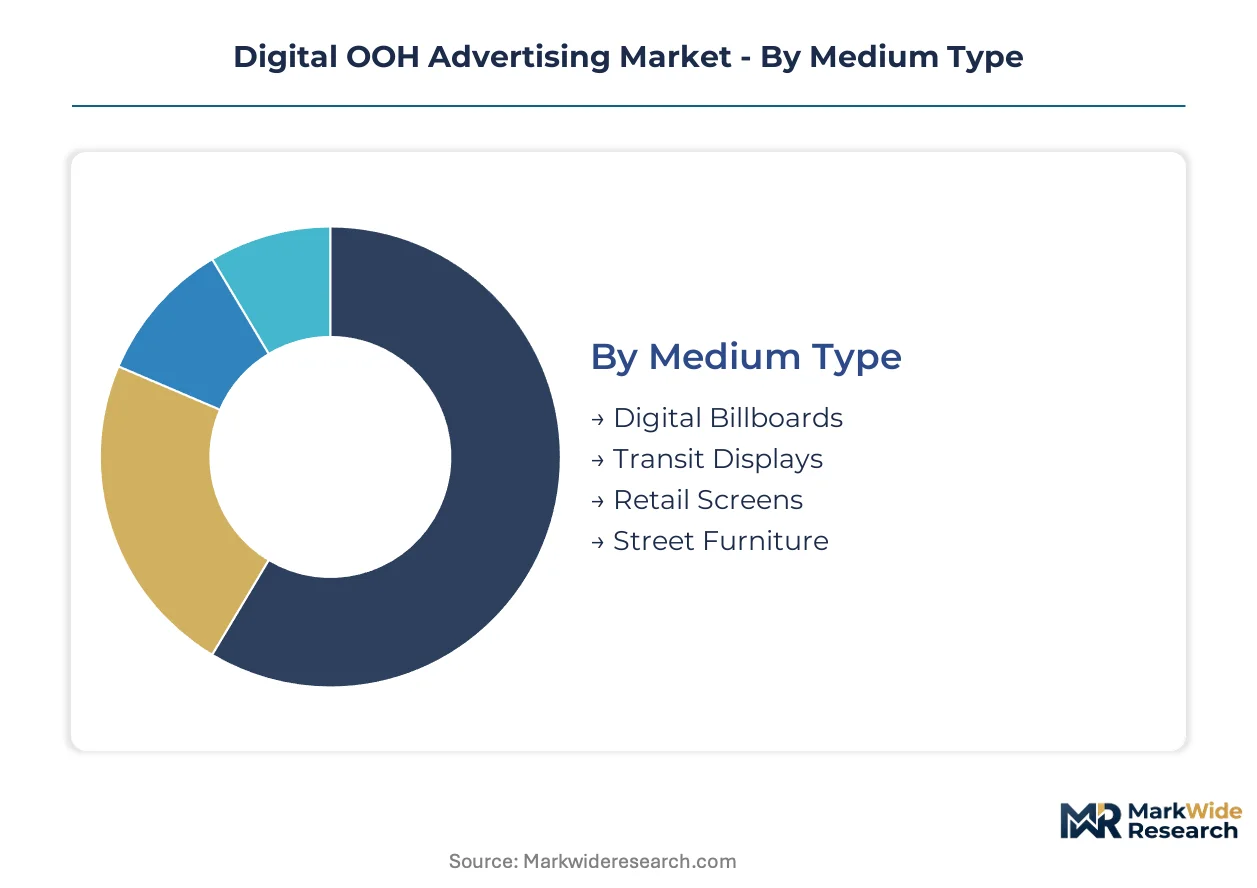
Segmentation in digital OOH advertising reveals how capital allocation, creative format, and deployment technology intersect to determine revenue capture. Buyers prioritize different combinations of reach, contextual relevance, and production complexity when selecting inventory categories.
Medium Type:
Buyers in this category differentiate primarily by audience mobility patterns and dwell time economics.
- Digital Billboards:Large-format LED arrays deployed along highways and arterial roads deliver mass reach to vehicular audiences. Highway conversions across the United States sustain premium rate cards due to scarcity of permitted locations and high traffic density.
- Transit Displays:Networked screens in subway stations, bus shelters, and rail platforms capture commuters during wait intervals. Dense urban corridors in China's tier-one cities generate the highest inventory utilization rates through high-frequency daily exposure.
- Retail Screens:Point-of-sale displays positioned near checkout zones and aisle endcaps influence purchase decisions at the final decision moment. Grocery and convenience chains deploy these networks to monetize foot traffic through programmatic retail media platforms.
- Street Furniture:Digital kiosks and bus shelter displays integrated into municipal concessions provide sidewalk-level engagement. European capitals maintain premium pricing through long-term exclusive operating agreements with outdoor advertising specialists.
Digital billboards lead volumes today; dynamic campaigns on transit displays are gaining share fastest.
End User:
Procurement authority in this category splits between direct brand spend and intermediated agency trading desks.
- Advertisers:Consumer brands and service providers purchase inventory directly for campaign-specific activations. Automotive and quick-service restaurant verticals dominate highway billboard commitments due to location-targeting requirements.
- Media Agencies:Trading desks consolidate spend across multiple inventory sources to optimize reach and frequency metrics. Agency holding companies are building dedicated OOH planning capabilities as the medium converges with programmatic buying infrastructure.
- Retailers:Grocery, pharmacy, and convenience chains operate captive screen networks for supplier-funded promotional placements. In-store retail media is displacing traditional circular advertising as margins compress in print distribution.
- Entertainment:Studios, streaming platforms, and live event promoters deploy high-impact video creative for tentpole releases. Entertainment verticals command priority positioning during premiere windows through upfront commitments.
Media agencies intermediate the largest transaction volumes; retailer direct purchases are climbing the fastest as retail media networks mature.
Content Type:
Creative format selection in this category hinges on production budget and contextual adaptability requirements.
- Video Ads:Motion creative with audio-off optimization for public environments commands rate premiums over static formats. Transit and retail networks in Germany and the Netherlands prioritize video inventory for engagement metrics.
- Dynamic Campaigns:Data-triggered creative rotation responds to weather, traffic, or sports outcomes in real time. The EU Green Deal's energy efficiency standards are accelerating LED hardware upgrades needed to support dynamic rendering at scale.
- Static Ads:Single-image creative with scheduled rotation remains cost-effective for sustained brand presence. Highway billboards in the United States retain substantial static inventory due to permitting constraints on electrical infrastructure.
- Interactive Content:Touch-enabled or mobile-integrated experiences activate audience participation in high-dwell environments. Shopping mall and airport deployments in China's tier-one cities pilot gesture and QR-triggered engagement layers.
Video ads lead volumes today; dynamic campaigns are expanding most quickly as data infrastructure and creative production tools converge.
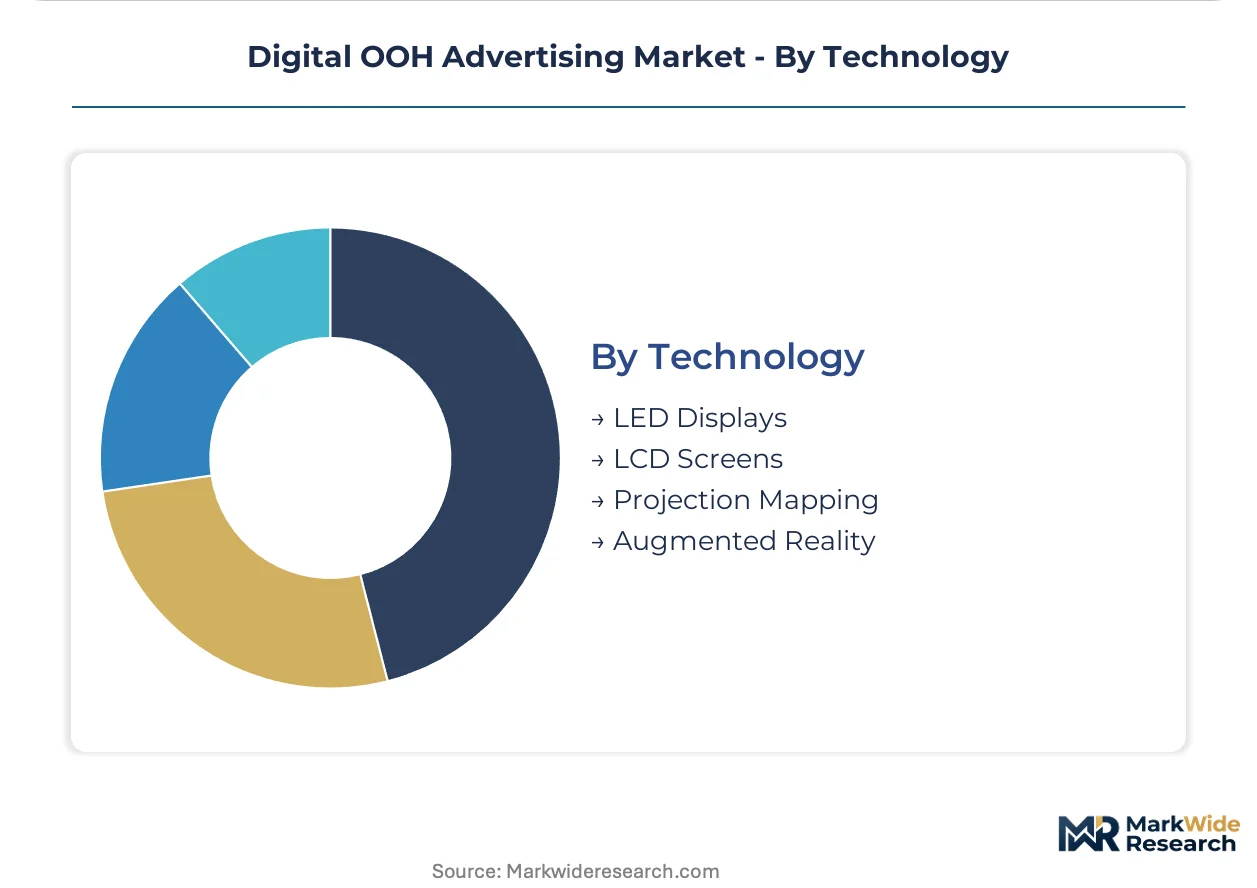
Technology:
Display technology selection separates deployments by brightness requirements, power constraints, and installation permanence.
- LED Displays:Direct-view LED modules with 5,000+ nit brightness ratings dominate outdoor daylight applications. The EU Green Deal's ecodesign requirements are forcing thermal management redesigns to meet standby power ceilings.
- LCD Screens:Backlit liquid crystal panels with localized dimming arrays serve indoor and covered outdoor environments. Transit authority deployments in North American metropolitan rail systems standardize on commercial-grade LCD for platform-level networks.
- Projection Mapping:Short-throw laser projectors transform architectural surfaces into temporary display canvases. Entertainment and cultural event activations in France and Italy leverage projection for landmark building takeovers without permanent hardware installation.
- Augmented Reality:Mobile device-integrated overlays extend physical screen content into personalized spatial experiences. Experimental deployments in Japan's METI-supported smart city pilots test AR layer monetization for transit corridor advertising.
LED displays lead volumes today; augmented reality integrations are gaining share fastest as spatial computing hardware penetrates consumer markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing digital OOH deployment capital toward jurisdictions with streamlined permitting and lower energy compliance costs. The EU Green Deal's ecodesign mandates accelerate equipment refresh cycles in member states, while tier-one Chinese cities attract dense screen network investments through municipal infrastructure partnerships.
United States
Highway digital billboard conversions and transit authority partnerships drive inventory expansion across metropolitan rail systems. The FCC governs wireless content delivery spectrum allocation for remote network management. Dallas-Fort Worth and Los Angeles corridors concentrate premium billboard placements due to traffic density and permitting availability.
China
Elevator screen networks in high-rise residential towers capture captive commuter audiences during daily vertical transit. SAMR advertising content regulations require pre-approval workflows that delay campaign deployment timelines. Shanghai and Beijing tier-one clusters generate the highest inventory utilization rates through dense urban population concentration.
Germany
Street furniture concessions in European capitals sustain premium inventory rates through long-term municipal operating agreements. The EU Green Deal's F-Gas Regulation phases out high-consumption display backlighting systems. Berlin and Frankfurt transit corridors deploy edge computing nodes enabling sub-second creative swaps based on train arrival data.
France
Outdoor billboard operators accelerate LED retrofit schedules to avoid EU ecodesign non-compliance penalties. ANSM and CNIL oversight creates layered regulatory compliance for public display deployments. Paris and Lyon street furniture networks maintain premium pricing through exclusive concession structures.
India
Municipal digital signage integration into urban transit and public safety networks remains underpenetrated relative to population density. BIS standards and state-level municipal corporation regulations fragment deployment approval processes. Mumbai and Delhi smart city infrastructure programs pilot integrated digital screen networks for transit corridor advertising.
Digital OOH Advertising Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with concession-holding network operators commanding premium positions in mature markets while technology vendors capture value from equipment refresh cycles. The vendor base organizes around three archetypes: municipal concession holders with long-term street furniture and transit contracts, display technology specialists manufacturing LED and LCD systems, and software platform providers enabling programmatic inventory trading. Consolidation pressures concentrate among concession-heavy European and North American markets, while Asian markets fragment across regional network operators. M&A activity targets municipal contract portfolios, and vertical integration into display manufacturing secures supply chain control against component volatility.
Among concession-based network operators, JCDecaux SA and Lamar Advertising Company exemplify the municipal-contract archetype through their European street furniture and U.S. highway billboard portfolios respectively. Focus Media Information Technology Co Ltd occupies a position representing dense urban screen network specialization in Chinese tier-one cities. These three entities anchor the competitive structure across distinct geographic and deployment-type vectors without overlapping core market positions.
| Leading Market Players |
|---|
| OUTFRONT Media Inc. |
| Focus Media Information Technology Co Ltd |
| JCDecaux SA |
| Broadsign International LLC |
| oOh!media Limited |
| Clear Channel Outdoor Holdings, Inc. |
| Ströer SE & Co. KGaA |
| Daktronics Inc. |
| Lamar Advertising Company |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's ecodesign mandates gate qualified supply and premium-tier pricing access by forcing display manufacturers toward lower-power LED retrofits that meet standby wattage ceilings, while transit authorities in Germany and France absorb cost premiums for compliant hardware to avoid non-compliance penalties.
Pricing Analysis
Direct-to-transit-authority contract structures dominate highway billboard and rail platform networks, bypassing distributor markups that inflate retail screen deployments. Price differentiation separates premium-tier LED arrays with sub-50-watt standby ratings from standard LCD panels lacking EU Green Deal certification, while economy positioning targets static billboard conversions with minimal electrical infrastructure. Pricing pressure stems from LED component supply volatility as semiconductor substrate shortages compress margins on high-brightness modules. Transit authorities in North American metropolitan rail systems exhibit lowest price sensitivity due to long-term municipal funding, while independent retail screen operators face acute cost compression.
Supply Chain Analysis
Regional distribution centers in China, South Korea, and Taiwan anchor LED module and semiconductor substrate flows through hub-and-spoke patterns serving display manufacturers. Raw material dependencies center on gallium nitride wafers, rare earth phosphors, and copper-clad laminates for thermal management substrates. Supply chain risk concentrates in single-source vulnerability for high-nit LED driver ICs sourced from Taiwanese foundries. Distribution runs through authorized reseller networks for transit authority contracts, while programmatic platform providers aggregate inventory for agency trading desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play where EU Green Deal compliance costs in France and Germany create 15-20 point operating margin spreads versus India's underpenetrated smart city corridors with streamlined municipal permitting.
For Market Incumbents: Hedge concession renewal concentration by diversifying into India's smart city infrastructure before municipal contracts lock up, while securing backward integration into LED driver manufacturing to offset semiconductor substrate volatility from Taiwanese foundries. For New Entrants and Emerging Players: Begin with elevator screen networks in China's tier-two cities where Focus Media's density advantage thins, leveraging SAMR pre-approval workflow expertise as a go-to-market differentiator against multinational operators unfamiliar with content compliance friction. For Investors and Strategic Acquirers: Valuations sit cheapest among municipal concession-heavy European operators facing accelerated LED retrofit cycles, where long-term viability over a 5-10 year window hinges on concession renewal success rates. The signal to watch is FCC spectrum allocation timing for wireless content delivery, which would unlock highway billboard network scalability without fiber trenching capital.| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Acceleration | EU Green Deal ecodesign mandates force thermal management redesigns to avoid non-compliance penalties in France and Italy. |
| Programmatic Platform Integration | Automated media buying convergence bridges traditional OOH workflows with agency trading desk infrastructure in the United States. |
| Edge Computing Deployment | Sub-second creative swaps based on train arrival data differentiate transit networks in Germany and the Netherlands. |
| India Smart City Partnership | Municipal digital signage integration captures underpenetrated population density relative to screen network deployment. |
| Concession Portfolio Consolidation | Long-term municipal contracts in European capitals sustain premium inventory rates against new entrant competition. |
Research Approach
Multiple input streams — primary interviews with transit authority procurement officers, display manufacturer R&D directors, and agency trading desk heads, alongside secondary validation through FCC spectrum filings, EU Green Deal regulatory texts, and SAMR advertising content directives — were reconciled through bottom-up equipment shipment analysis and top-down media spend triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including medium type, end-user procurement authority, content format, and display technology brightness tier, with CAGRs derived from equipment replacement cycle compression and programmatic trading penetration curves. Forecast inputs incorporated LED component supply lead times and municipal concession renewal probability distributions.
Caveats apply where semiconductor substrate shortages, rare earth element pricing swings, or SAMR content approval delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
Philippines OOH and DOOH Market
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
Programmatic Advertising Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Global Printed Signage Market