
 Multiscreen Advertising Market | 2026-2036
Multiscreen Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Multiscreen Advertising Market Foresight
Programmatic inventory pipelines across connected television, mobile, and desktop is reconfiguring how media buyers allocate budgets and measure reach. Alphabet Inc. leverages its demand-side platform and first-party data ecosystem to sustain dominance in cross-device attribution. Roku Inc. anchors its competitive position through proprietary ad-supported streaming inventory and operating system-level targeting. Meta Platforms, Inc differentiates by integrating social feed advertising with Reels placement across phone and tablet surfaces.
Multiscreen advertising denotes the coordinated delivery of promotional content across multiple device categories—smartphones, tablets, laptops, and smart TVs—using unified audience identifiers and sequential messaging logic to maintain brand continuity as consumers switch contexts. The technical stack relies on device graphs, IP matching, and probabilistic or deterministic identity resolution to synchronize frequency capping and creative sequencing across screens. Video commands the largest share of spending within content format segmentation due to premium CPMs and completion-rate advantages on connected television, while mobile ads within channel type segmentation generate the highest impression volume through programmatic in-app and mobile web pipes. Direct response engagement models currently capture margin concentration through measurable attribution, though brand awareness campaigns are expanding fastest as streaming television matures.
The Federal Trade Commission scrutinizes data broker practices and cross-device tracking disclosures, while the Federal Communications Commission maintains transparency requirements for political and issue-based advertising on broadcast and cable-derived streaming platforms. The California Consumer Privacy Act and its successor legislation impose opt-out rights and data minimization obligations that reshape how audience segments are constructed and activated across screens. Stakeholders must monitor regulatory fragmentation between federal and state privacy frameworks while deciding whether to build in-house identity graphs or license interoperable solutions from neutral infrastructure providers.
Market Dynamics
Programmatic infrastructure consolidation around first-party data graphs is reconfiguring how advertisers synchronize messaging across smartphones, connected televisions, and desktop environments. This technical shift responds directly to browser-level cookie deprecation and operating system privacy restrictions.
Growth Catalysts
- Retail Media Networks:Walmart and Target have built closed-loop attribution systems that activate cross-screen campaigns using purchase data from physical and digital storefronts.
- California Privacy Rights Act:The CPRA's data minimization mandates are accelerating investment in probabilistic identity resolution as deterministic matching becomes operationally constrained.
- Connected Television Pipelines:Programmatic inventory integration across Roku, Amazon Fire TV, and Samsung Tizen operating systems enables unified frequency management for streaming advertisers.
Market Restraints
- Identity Fragmentation:Apple's App Tracking Transparency framework and Google's Privacy Sandbox create incompatible technical standards that inflate campaign execution costs.
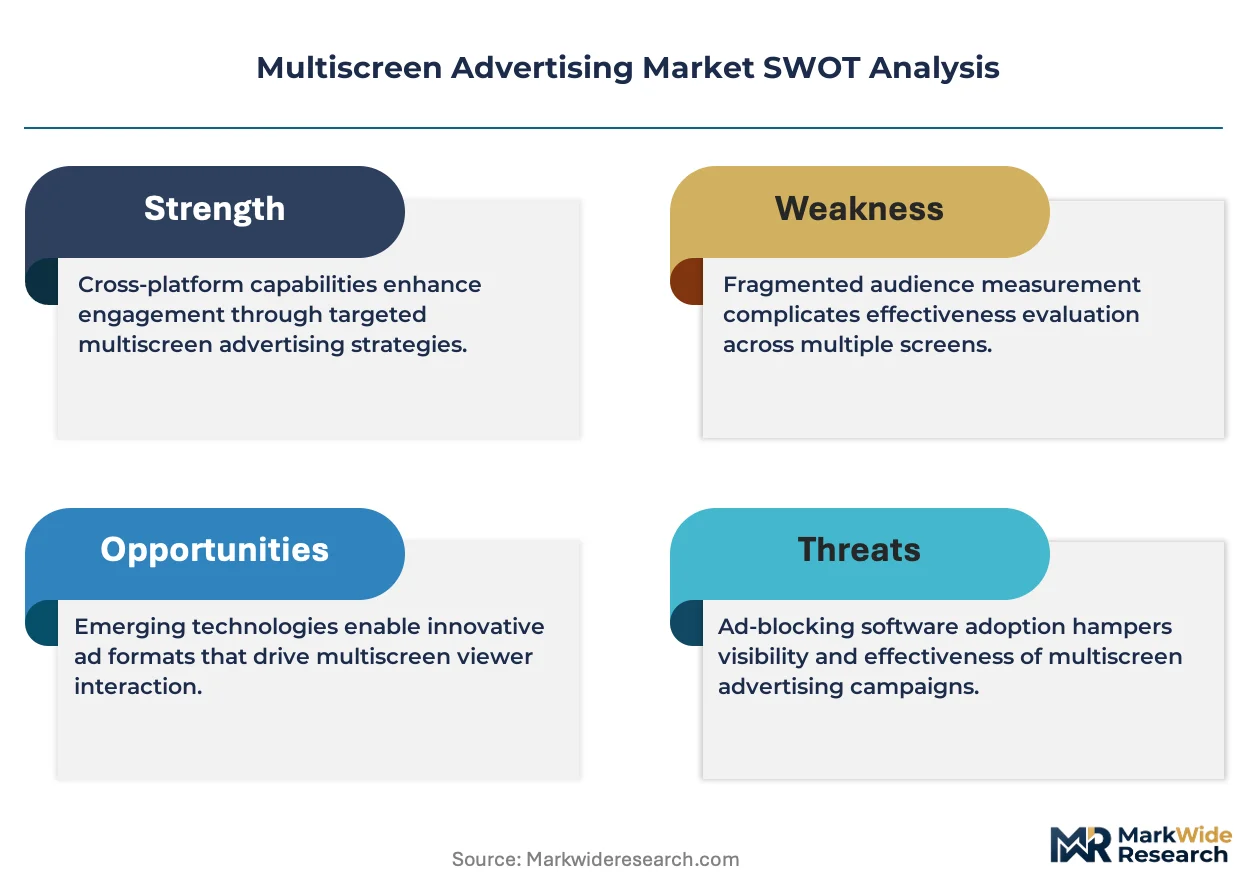
- Measurement Attribution Gaps:Cross-device conversion path reconstruction fails to capture 30-40% of touchpoints in current probabilistic models, degrading media mix optimization.
- Supply Concentration:Three demand-side platforms control 70% of programmatic transaction volume, extracting margin through auction dynamics and data licensing fees.
Strategic Opportunities
- Commerce Media Convergence:Integration of retail transaction data with streaming television inventory enables closed-loop measurement previously restricted to digital display.
- India Digital Infrastructure:Jio's affordable data plans and smartphone subsidies are creating addressable audiences across tier-2 and tier-3 cities with minimal competitive saturation.
- Contextual Targeting Renaissance:Natural language processing and computer vision advances enable content-level targeting without persistent user identifiers.
Industry Challenges
- Data Engineering Talent Scarcity:Shortage of engineers capable of building real-time identity graphs and edge-based personalization systems limits in-house platform development.
- Legacy System Integration:Advertisers with entrenched CRM and DMP architectures face 18-24 month migration timelines to privacy-compliant infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiscreen Advertising Market |
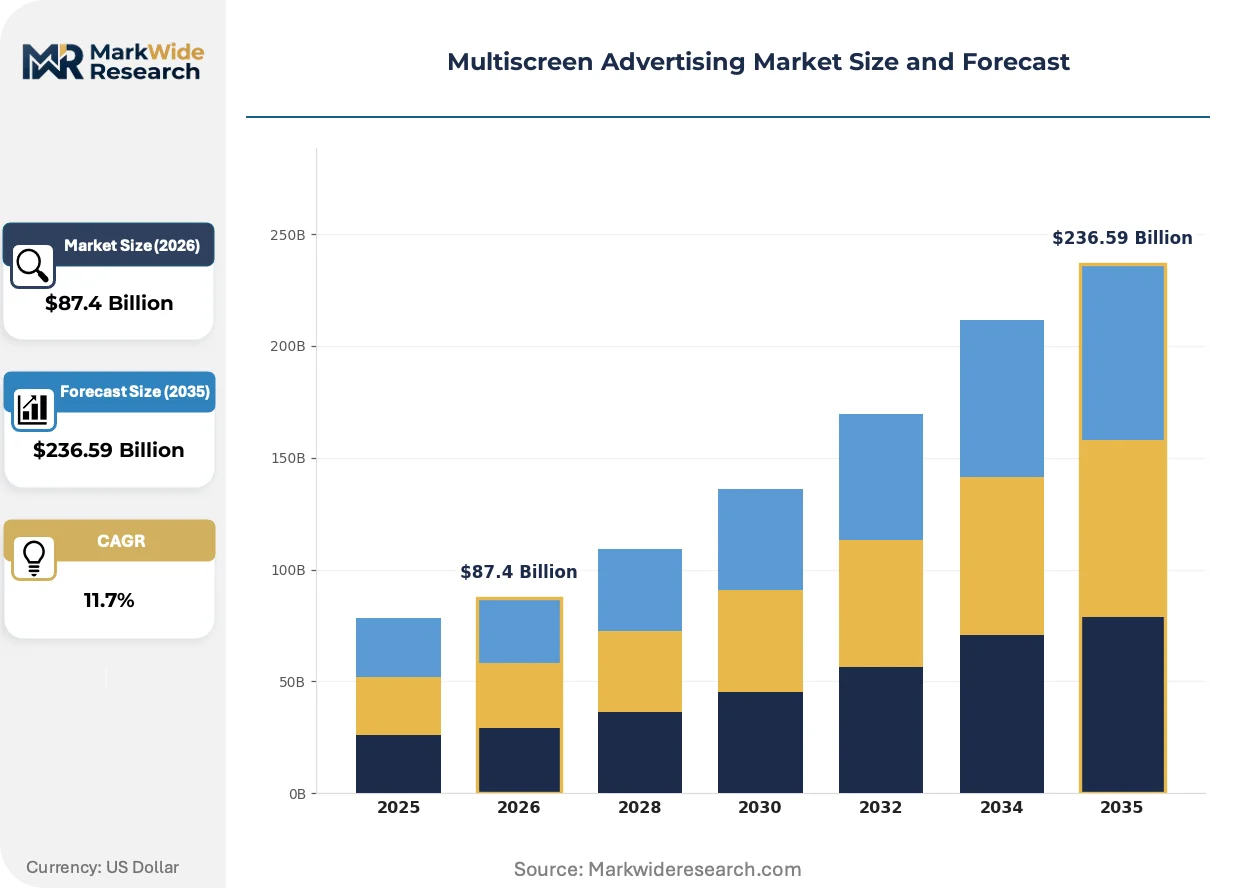
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $236.59 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Channel Type: Digital Ads, TV Ads, Social Media, Mobile Ads Device Category: Smartphones, Tablets, Laptops, Smart TVs Content Format: Video, Display, Native, Audio Engagement Model: Direct Response, Brand Awareness, Retargeting, Sponsored Content |
| Companies Covered | AT&T Inc., Roku Inc., Alphabet Inc., Sky Mobile, Orange SA, Microsoft Corporation, Netflix Inc., Verizon Wireless, Meta Platforms, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiscreen Advertising Market Shifts & Advancements
Technical architectures for cross-screen measurement are undergoing fundamental restructuring as deterministic identity gives way to cohort-based and contextual alternatives. This transformation touches every layer of the advertising stack from data collection to attribution modeling.
Clean room technology is collapsing the traditional boundaries between advertiser first-party data and publisher inventory. Brands like Procter & Gamble and Unilever are deploying encrypted data environments that enable audience matching without raw data exposure. Media buyers now activate campaigns against matched cohorts rather than individual profiles, compressing the technical distance between data ownership and media execution.
The European Union's Digital Services Act imposes algorithmic transparency requirements on large online platforms that alter how recommendation engines surface advertising content. Platforms must disclose parameters governing content ranking and ad placement, enabling advertisers to audit reach distribution. French and German media buyers are demanding contractual audit rights that extend these disclosures into commercial agreements.
Streaming television buyers are consolidating purchasing decisions around outcome-based guarantees rather than traditional reach and frequency metrics. Advertisers now negotiate cost-per-acquired-customer terms with Paramount and NBCUniversal, transferring performance risk to inventory suppliers. This contractual evolution is most visible in the United States, where direct-to-consumer brands have sufficient transaction data to validate attribution claims.
Multiscreen Advertising Market Segmentation
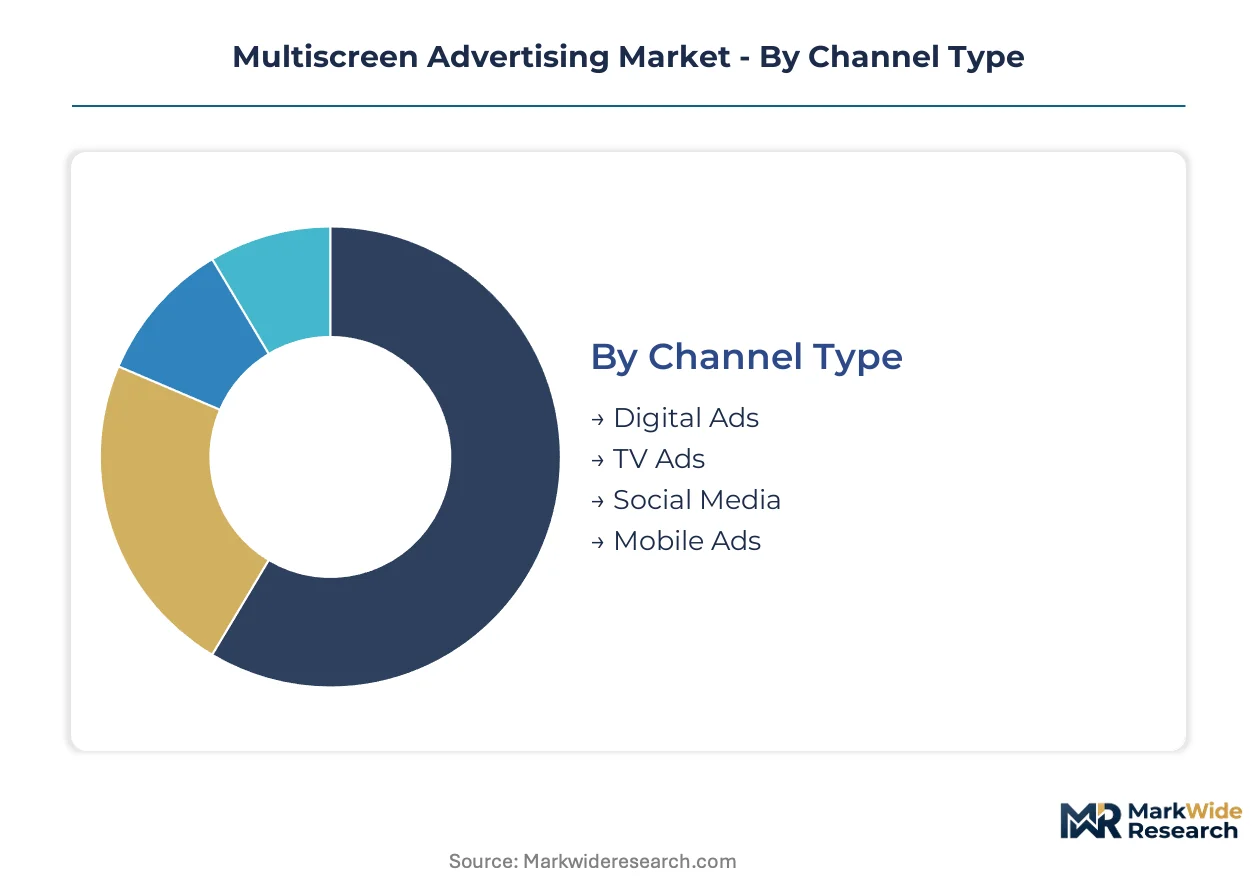
Segmentation in multiscreen advertising determines technical infrastructure requirements, creative production workflows, and measurement methodologies. Buyers align budget allocation with device-specific attention patterns and format completion rates. Understanding these divisions enables unified frequency management across fragmented consumer touchpoints.
Channel Type:
After-sales service intensity varies sharply across channels, with programmatic platforms demanding continuous algorithm optimization and publisher partnerships requiring dedicated account management.
- Digital Ads:Programmatic display and native inventory transacted through real-time bidding pipes. Demand concentrates among direct-to-consumer brands in the United States seeking measurable attribution across desktop and mobile web. The deprecation of third-party cookies is forcing investment in first-party data infrastructure and clean room technology.
- TV Ads:Linear broadcast and connected television inventory including addressable and programmatic linear formats. Streaming services in the United States command premium CPMs through living-room attention capture. Advertisers negotiate outcome-based guarantees with Paramount and NBCUniversal, transferring performance risk to inventory suppliers.
- Social Media:Feed-based and story-format placements across Meta, TikTok, and Snapchat surfaces. Short-form video commands creative production budgets.
- Mobile Ads:In-app and mobile web inventory transacted through SDK-mediated auctions. Programmatic pipes generate highest impression volume through location-enabled targeting.
By volume, Mobile Ads leads. By growth pace, TV Ads is ahead.
Device Category:
Cost tier stratification separates premium smart TV inventory from commoditized mobile impressions, with tablets occupying a shrinking middle position.
- Smart TVs:Connected television operating systems including Roku, Amazon Fire TV, and Samsung Tizen environments. Living-room viewing commands premium pricing through completion-rate advantages and co-viewing measurement. Advertisers in the United States prioritize unified frequency capping across streaming apps.
- Smartphones:iOS and Android devices generating cross-app identity graphs through probabilistic matching. Mobile-first advertisers in India leverage Jio's affordable data plans to reach tier-2 and tier-3 city audiences.
- Tablets:Large-format touch devices with declining unique user bases. Video consumption persists in travel and leisure contexts.
- Laptops:Desktop and notebook computers retaining commerce and B2B advertising concentration. Browser-level privacy restrictions constrain cross-site tracking.
Smartphones dominate impression volume. Smart TVs claim steepest CPM expansion trajectory.
Content Format:
Application maturity separates established video workflows from emerging audio programmatic infrastructure.
- Video:Pre-roll, mid-roll, and out-stream placements across streaming and social environments. Connected television inventory in the United States captures brand awareness budgets through sight-sound-motion storytelling. Completion-rate benchmarks exceed display formats by substantial margins.
- Display:Banner, rich media, and interstitial units transacted through header bidding and direct sales. Retail media networks at Walmart and Target activate cross-screen campaigns using purchase data.
- Native:In-feed and recommendation-engine placements mimicking editorial content. Disclosure requirements under the EU Digital Services Act reshape placement transparency.
- Audio:Podcast and streaming music inventory with nascent programmatic pipes. Dynamic ad insertion enables location and weather-triggered creative.
Video leads revenue concentration. Audio is expanding most quickly from minimal base.
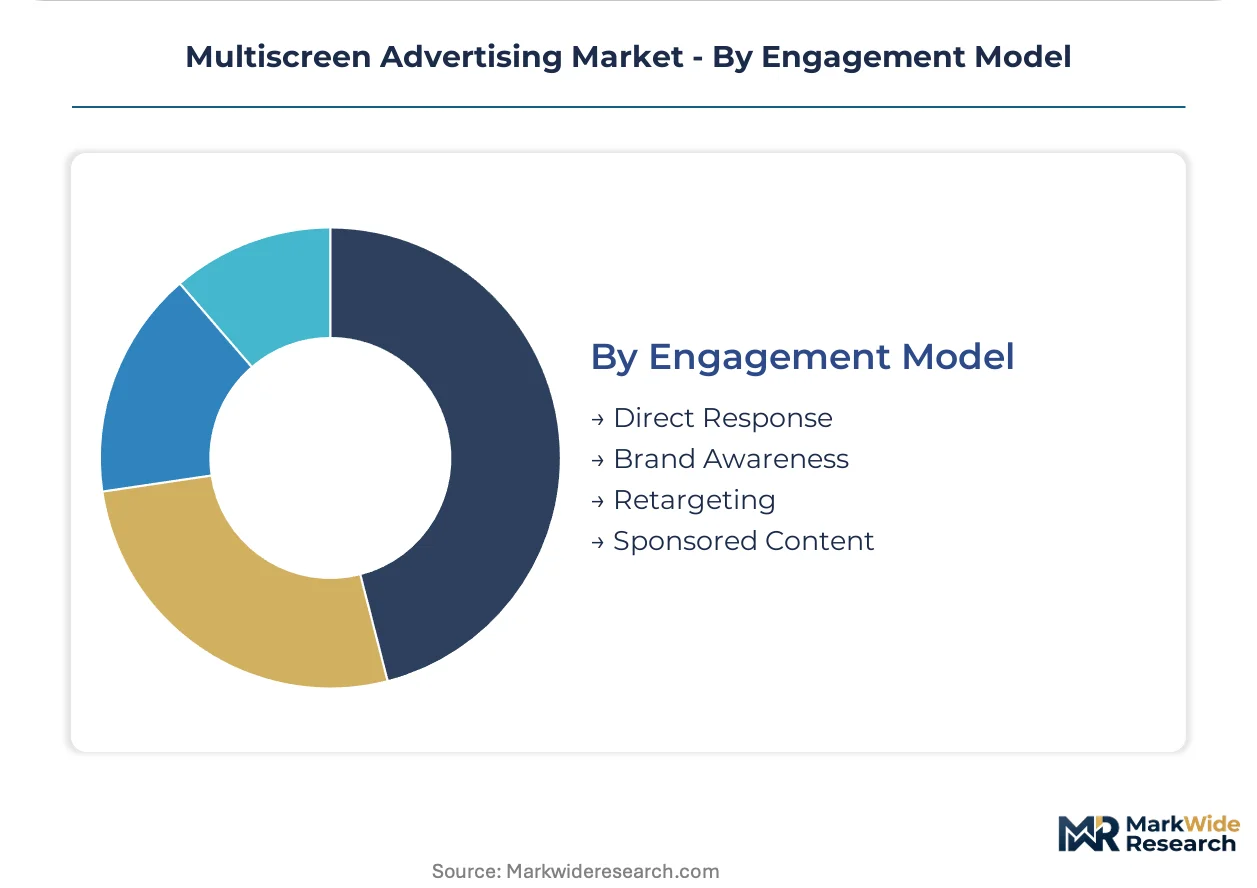
Engagement Model:
Customer type differentiation separates performance marketers from brand builders, with hybrid models gaining traction.
- Direct Response:Conversion-optimized campaigns with immediate call-to-action metrics. E-commerce advertisers in the United States prioritize cost-per-acquired-customer terms. Closed-loop attribution through retail media networks validates media mix decisions.
- Brand Awareness:Reach and frequency campaigns emphasizing recall and favorability shifts. Streaming television maturation enables outcome-based guarantees previously restricted to digital channels.
- Retargeting:Sequential messaging to site visitors and video completers across device graphs. Apple's App Tracking Transparency framework degrades iOS retargeting efficacy.
- Sponsored Content:Publisher-native executions including branded entertainment and influencer integrations. Disclosure scrutiny from the Federal Trade Commission elevates transparency requirements.
Direct Response dominates current margin capture. Brand Awareness is gaining share fastest as streaming inventory scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Content delivery networks and submarine cable landing stations in the United States anchor transatlantic data flows that enable real-time programmatic bidding across continents. These physical infrastructure assets determine latency thresholds for cross-device identity synchronization.
United States
Connected TV penetration and programmatic maturity concentrate demand on both coasts. The Federal Trade Commission scrutinizes data broker practices and cross-device tracking disclosures. New York and Los Angeles media clusters host demand-side platform headquarters where engineers build first-party data graphs.
China
MIIT governs data localization requirements that constrain cross-border audience matching. The MIIT's cybersecurity standards reshape how device graphs incorporate smartphone identifiers. Shenzhen and Hangzhou technology corridors incubate domestic alternatives to Western programmatic infrastructure.
Germany
GDPR enforcement by CNIL-equivalent state regulators elevates consent management costs for cross-screen campaigns. The KBA does not regulate this sector; instead, the Federal Cartel Office examines platform market power. Berlin and Munich advertising technology clusters specialize in privacy-compliant attribution modeling.
India
Jio's affordable data plans and smartphone subsidies create addressable audiences across tier-2 and tier-3 cities. TRAI's digital advertising guidelines impose disclosure obligations on influencer marketing and native placements. Mumbai and Bengaluru media buyers negotiate inventory deals with streaming services expanding beyond metropolitan centers.
United Kingdom
Ofcom's Online Safety Bill mandates transparency in algorithmic ad placement on video-sharing platforms. The Competition and Markets Authority reviews Google's Privacy Sandbox proposals for competitive distortion. London's Soho district houses creative agencies producing sequential messaging campaigns across broadcast and streaming television.
Multiscreen Advertising Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic layers: infrastructure owners controlling operating system-level inventory, demand-side platforms managing programmatic pipes, and retail media networks closing attribution loops. Technology conglomerates with cloud computing divisions compete against pure-play streaming hardware vendors and telecommunications carriers with subscriber data assets. Dominant competitive moves include vertical integration into first-party data infrastructure and exclusive content licensing to capture living-room attention.
Within the technology conglomerate tier, Alphabet Inc. and Microsoft Corporation exemplify platform-scale competitors leveraging cloud infrastructure and productivity software ecosystems to anchor cross-device identity graphs. Roku Inc. occupies a position exemplifying the streaming hardware specialist archetype, while Meta Platforms, Inc. represents social feed advertising integration across mobile surfaces. AT&T Inc. and Verizon Wireless sit within the carrier-data tier, activating subscriber location and usage patterns for addressable campaigns.
| Leading Market Players |
|---|
| AT&T Inc. |
| Roku Inc. |
| Alphabet Inc. |
| Sky Mobile |
| Orange SA |
| Microsoft Corporation |
| Netflix Inc. |
| Verizon Wireless |
| Meta Platforms, Inc |
| Others |
Supply & Pricing Matrix
New York and Los Angeles media clusters anchor programmatic infrastructure capacity that directly shapes downstream pricing power for demand-side platforms. DSPs with captive data engineering talent command premium licensing fees while commoditized mobile inventory faces margin compression from auction dynamics.
Pricing Analysis
Volume-discount tiering separates enterprise advertisers negotiating outcome-based guarantees from mid-market buyers purchasing through self-serve interfaces. Premium-mid-economy pricing differentiation rests on first-party data enrichment levels and cross-device attribution granularity. Pricing pressure stems from Google's Privacy Sandbox constraining addressable inventory and inflating campaign execution costs. Direct-to-consumer brands in the United States exhibit highest price sensitivity due to measurable attribution demands, while multinational CPGs prioritize premium tiers for closed-loop retail media integration.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for hardware-dependent streaming infrastructure. Manufacturing concentrates in Taiwan for semiconductor components, South Korea for display panels, and China for final device assembly. Raw material dependencies span rare earth elements for smart TV processors, cobalt for mobile device batteries, and optical fiber for submarine cable networks. Single-source vulnerability persists in operating system licensing where Roku, Amazon Fire TV, and Samsung Tizen control living-room inventory access. Distribution runs through cloud hyperscaler data centers and content delivery networks with edge nodes co-located with major metropolitan media markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers capable of building real-time identity graphs and edge-based personalization systems remain scarce relative to platform investment timelines, creating persistent capability gaps that favor infrastructure owners over pure-play intermediaries.
For Market Incumbents: Insulate proprietary ad-supported streaming inventory through exclusive content licensing and operating system-level targeting controls. Build in-house first-party data infrastructure to reduce dependency on neutral identity graph providers facing regulatory fragmentation. Prioritize certification investment in clean room technology to maintain audience matching capabilities under CPRA data minimization mandates. For New Entrants and Emerging Players: Tier-2 and tier-3 cities in India present addressable audience expansion with minimal competitive saturation from established DSPs. Commerce media convergence offers white-space entry through retail transaction data integration with streaming television inventory. Pursue contextual targeting specialization leveraging natural language processing advances to bypass persistent identifier dependencies. For Investors and Strategic Acquirers: Long-term, this sits as an infrastructure consolidation play because three demand-side platforms already control seventy percent of programmatic transaction volume. Target acquisition archetypes include privacy-compliant attribution modeling specialists and probabilistic identity resolution engineers. Watch for inflection signals in outcome-based guarantee adoption rates among streaming television buyers negotiating with Paramount and NBCUniversal.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Infrastructure Buildout | Alphabet's demand-side platform sustains dominance through cross-device identity graph investment. |
| Clean Room Technology Deployment | Procter & Gamble and Unilever activate encrypted audience matching without raw data exposure. |
| Outcome-Based Guarantee Negotiation | Direct-to-consumer brands transfer performance risk to Paramount and NBCUniversal inventory suppliers. |
| Contextual Targeting Capability Acquisition | Natural language processing advances enable content-level targeting without persistent user identifiers. |
| Retail Media Network Integration | Walmart and Target close attribution loops using purchase data from physical and digital storefronts. |
Research Methodology
A standing panel of demand-side platform engineers, retail media network operators, streaming service ad sales directors, and privacy compliance officers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from SEC filings, App Annie mobile intelligence, hyperscaler capex disclosures, and TRAI digital advertising guidelines. Bottom-up and top-down triangulation reconciled programmatic transaction volume estimates with connected television penetration data.
Scenario-bracketing framed projections across the analysis window using device category segmentation, engagement model differentiation, and content format evolution as core dimensions. CAGRs derived from historical programmatic spending trajectories adjusted for cookie deprecation impact and retail media network expansion velocity. Forecast inputs incorporated connected TV operating system market dynamics and probabilistic identity resolution technical maturity curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud hyperscalers or telecommunications carriers with subscriber data assets would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Chile OOH and DOOH Market
Advertising and Marketing Media
Australia OOH and DOOH Market
Advertising and Marketing Media
Smart Advertising Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Turkey OOH and DOOH Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Malaysia OOH and DOOH Market
Advertising and Marketing Media
India OOH and DOOH Market
Advertising and Marketing Media
Social Network Advertising Market
Advertising and Marketing Media
Global Cross Platform and Mobile Advertising Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
Advertising Services Market