
 Global Advertising Agency Software Market | 2026-2036
Global Advertising Agency Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advertising Agency Software Market Foresight
Programmatic media buying channels are rewriting how advertising agencies allocate technology budgets across client portfolios. Google leverages its search and display infrastructure to dominate data management platform integrations. Adobe sustains creative-to-analytics workflows that anchor enterprise agency retainers. The Trade Desk competes through independent demand-side technology that positions agencies outside walled-garden ecosystems.
Advertising agency software comprises cloud-deployed and on-premise applications that automate media planning, creative collaboration, campaign execution, and performance analytics through real-time bidding protocols and API-based data exchanges. Cloud-based deployment leads solution uptake among mid-size digital agencies seeking scalable infrastructure without capital expenditure. Campaign management and analytics & reporting capture concentrated margin pools as agencies prioritize outcome-based client billing. Creative collaboration tools represent the fastest-growing solution segment as distributed creative studios require synchronous asset development across time zones.
The EU AI Act and GDPR impose algorithmic transparency and consent-management requirements on programmatic platforms serving European clients. The US FTC scrutinizes dark-pattern advertising and deceptive automated targeting, forcing agencies to audit software vendor compliance. India's TRAI and proposed data protection frameworks shape how multinational agencies configure cross-border campaign data flows. Stakeholders must monitor evolving jurisdictional requirements to align vendor selection with enforceable privacy and AI governance standards.
Market Dynamics
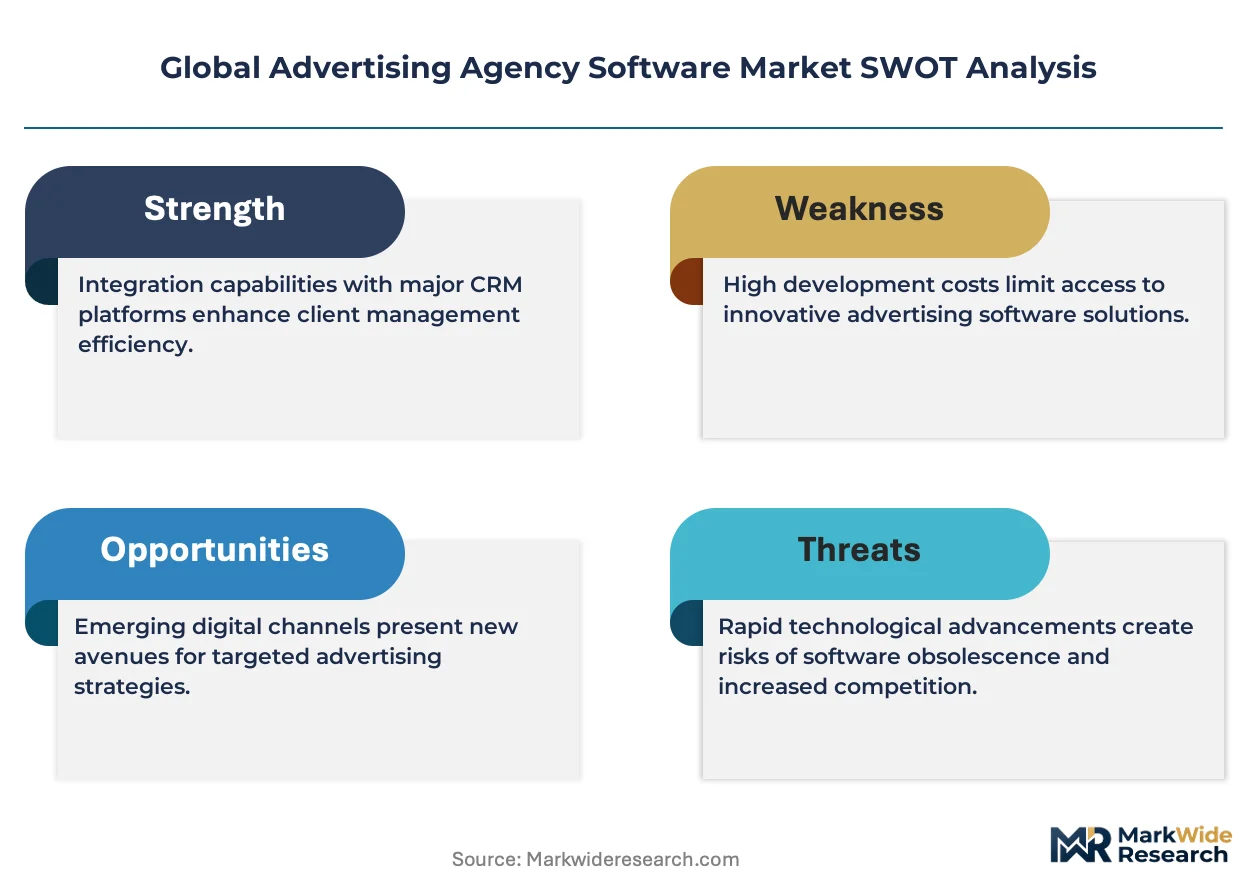
Programmatic media buying is hybridizing creative and data workflows, forcing agencies to restructure technology procurement around unified platforms rather than point solutions. EU AI Act algorithmic transparency mandates and US FTC dark-pattern enforcement are simultaneously reshaping vendor certification requirements and client liability exposure.
Growth Catalysts
- EU AI Act compliance mandates:European agencies must deploy auditable algorithmic decision systems, creating replacement demand for certified campaign management platforms.
- Real-time bidding protocol expansion:Connected TV inventory integration is pulling mid-size agencies into programmatic video buying faster than planned infrastructure upgrades.
- India:TRAI's proposed data localization frameworks are accelerating domestic software vendor partnerships among multinational agencies operating cross-border campaigns.
Market Restraints
- Cloud infrastructure concentration:Three hyperscale providers control essential compute and storage for campaign analytics, creating single-point-of-failure risk for agency operations.
- Technical debt accumulation:Legacy on-premise creative asset management systems resist API integration with modern programmatic stacks, slowing unified workflow deployment.
- GDPR enforcement variance:Inconsistent national interpretation of consent requirements across Germany, France, and Italy fragments campaign data architecture compliance costs.
Strategic Opportunities
- Saudi Arabia:Underdeveloped agency software penetration among Riyadh and Jeddah-based digital shops offers first-mover platform adoption potential.
- Generative AI and creative collaboration convergence:Synchronous asset development tools embedding large language models are opening new subscription tiers for distributed creative studios.
- Outcome-based client billing:Performance-linked agency retainers are creating demand for integrated attribution software that justifies technology stack consolidation.
Industry Challenges
- Cross-functional talent scarcity:Campaign managers who bridge creative strategy and data science command premium compensation, constraining mid-size agency hiring.
- Multi-jurisdictional compliance timelines:Simultaneous GDPR, EU AI Act, and US FTC audit requirements compress vendor due diligence windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advertising Agency Software Market |
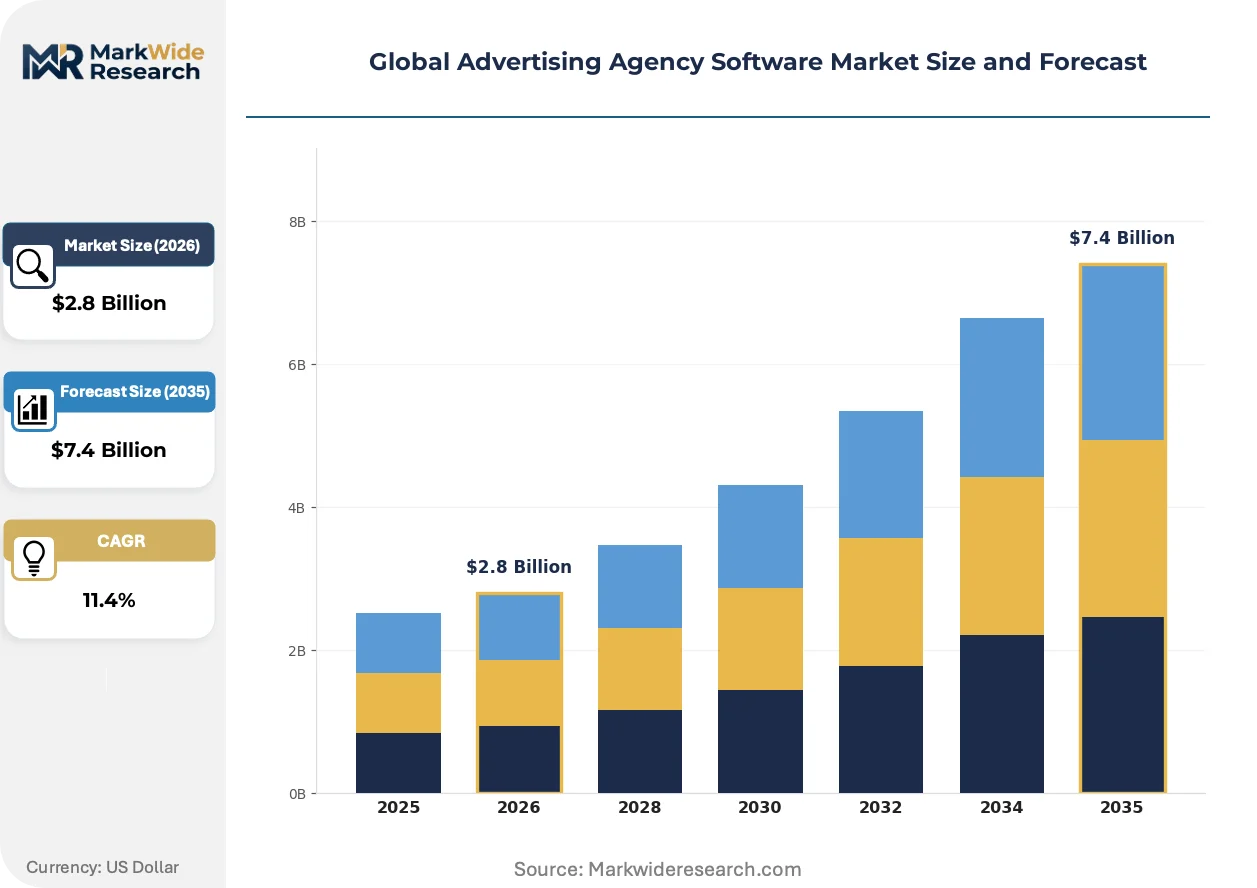
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Private Cloud Solution Offering: Campaign Management, Creative Collaboration, Analytics & Reporting, Client Management, Media Planning Use Case: Brand Awareness, Lead Generation, Customer Retention, Market Analysis, Content Optimization End User Type: Digital Agencies, Media Buyers, Creative Studios, Marketing Consultants, Social Media Managers |
| Companies Covered | Google, Adobe, The Trade Desk, Criteo, MediaMath, AppNexus, Adform, PubMatic, OpenX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advertising Agency Software Market Shifts & Advancements
Agency technology procurement is pivoting from best-of-breed point solutions toward vertically integrated suites that compress workflow handoffs. Three developments are restructuring competitive positioning and client retention mechanics.
Generative creative tools are hybridizing static and dynamic asset production, enabling agencies to produce variant-heavy campaigns for programmatic personalization. Boutique digital shops in London and Berlin are adopting these platforms fastest, collapsing traditional production timelines from weeks to hours. This compression is eroding hourly billing models and forcing agencies toward flat-fee outcome structures.
The EU AI Act's algorithmic transparency requirements are mandating explainable targeting logic in programmatic platforms serving European clients. Vendors must now document automated decision pathways and provide human-override capabilities. Campaign management software with built-in audit trails is capturing premium positioning among agencies with multinational brand portfolios.
Brand direct-to-platform procurement is bypassing traditional agency media buying functions in consumer packaged goods verticals. Marketers in the United States and Germany are licensing demand-side technology independently, unbundling execution from strategy. This disintermediation pressures agency software vendors to demonstrate strategic value-add beyond transaction facilitation.
Global Advertising Agency Software Market Segmentation
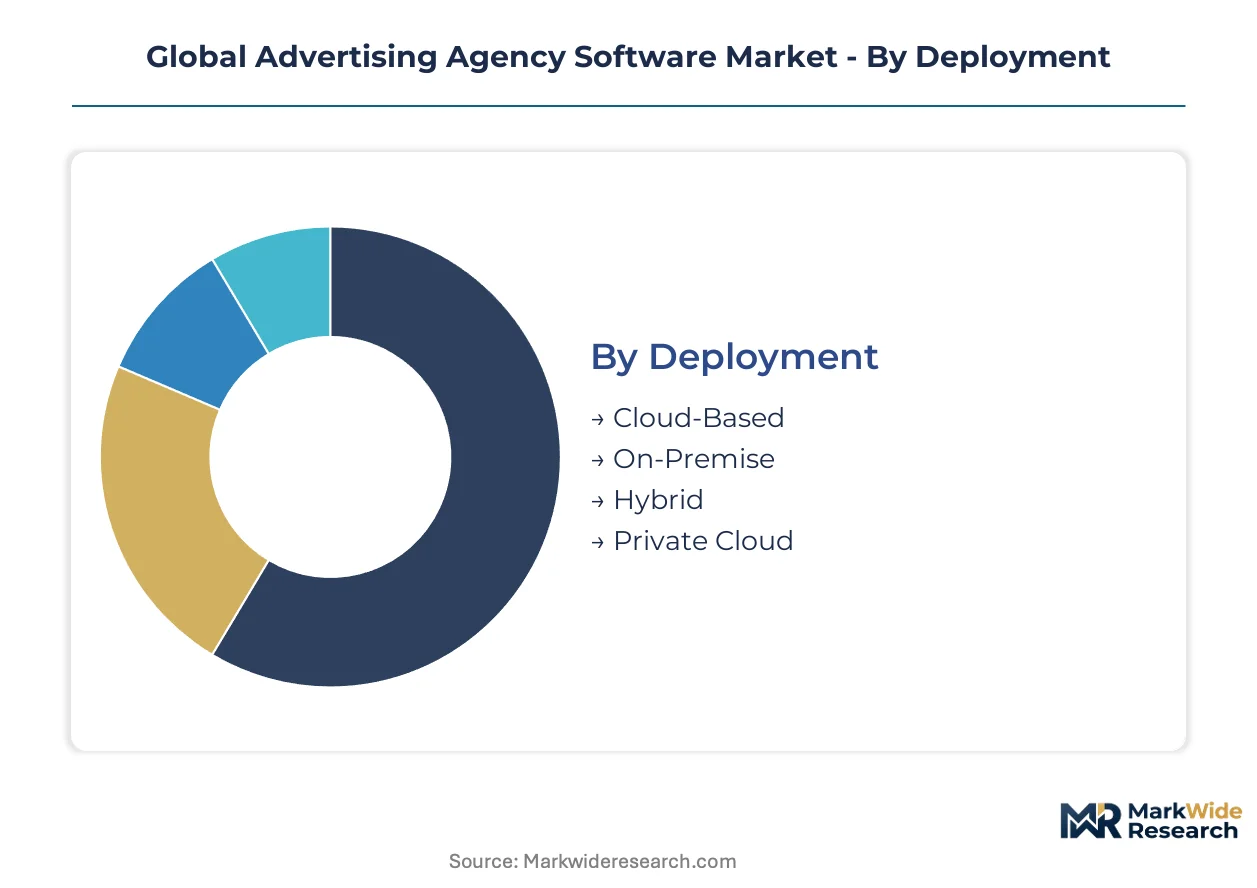
Agency software procurement patterns diverge sharply by operational scale and client complexity. Deployment preferences, solution bundles, and end-user workflows create distinct margin architectures that vendors must address through targeted packaging.
Deployment:
Mid-size digital agencies in Germany and India are driving infrastructure decisions across the use-case spectrum from campaign execution to creative asset storage.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure for agencies managing fluctuating client volumes. Demand concentrates among Berlin and Mumbai-based shops where technical staff scarcity makes self-managed infrastructure uneconomical.
- On-Premise:Dedicated hardware deployments persist where client contracts mandate data residency or where legacy creative asset libraries resist cloud migration. German agencies serving automotive and pharmaceutical verticals maintain these configurations to satisfy contractual audit requirements.
- Hybrid:Split workloads place sensitive client data on local servers while leveraging cloud elasticity for burst campaign processing. US agencies with defense sector clients favor this model to satisfy CMMC and ITAR compliance alongside operational flexibility.
- Private Cloud:Single-tenant dedicated environments serve holding company networks requiring unified infrastructure across acquired agency brands. French and UK-based multinationals deploy these to maintain cross-border data governance consistency.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
Solution Offering:
Margin capture varies by workflow integration depth, with bundled suites commanding premium positioning over standalone modules.
- Campaign Management:Centralized planning, trafficking, and optimization consoles form the operational core of agency technology stacks. US and German full-service agencies allocate the largest procurement budgets here due to outcome-based client billing requirements.
- Creative Collaboration:Synchronous asset development platforms with version control and approval workflows. Distributed creative studios across London, New York, and Singapore are expanding subscriptions fastest as production timelines compress.
- Analytics & Reporting:Cross-channel attribution and performance visualization tools. Indian digital agencies serving e-commerce clients are driving uptake as performance marketing mandates intensify.
- Client Management:CRM-integrated project tracking, time capture, and billing reconciliation. Boutique consultancies in France and Italy prioritize these to automate scope creep documentation and retention risk alerts.
- Media Planning:Inventory forecasting, rate negotiation support, and budget allocation modules. Independent media buyers in the US and UK license these separately as holding company consolidation reduces internal planning autonomy.
Campaign Management retains the largest installed base; Creative Collaboration is climbing the fastest.
Use Case:
Client budget cycles and measurement sophistication determine which use cases agencies can monetize through software-enabled service tiers.
- Brand Awareness:Reach and frequency optimization across display, video, and connected TV inventory. CPG marketers in the US and Germany fund these campaigns through annual brand equity budgets with established measurement frameworks.
- Lead Generation:Performance-driven acquisition with cost-per-lead or cost-per-acquisition pricing. Indian and UK agencies serving B2B technology and financial services verticals are expanding tool investments here.
- Customer Retention:CRM-triggered re-engagement and loyalty program automation. Subscription economy clients in France and the US are driving demand as churn economics reshape marketing allocation.
- Market Analysis:Competitive intelligence, audience segmentation, and trend forecasting. Strategic planning consultancies in Germany and Singapore license these capabilities for quarterly client reviews.
- Content Optimization:A/B testing, personalization, and dynamic creative assembly. Social-native agencies in London and Los Angeles are adopting these to justify premium creative retainers against platform-native tools.
Brand Awareness commands the deepest incumbent investment; Content Optimization shows the steepest expansion trajectory.
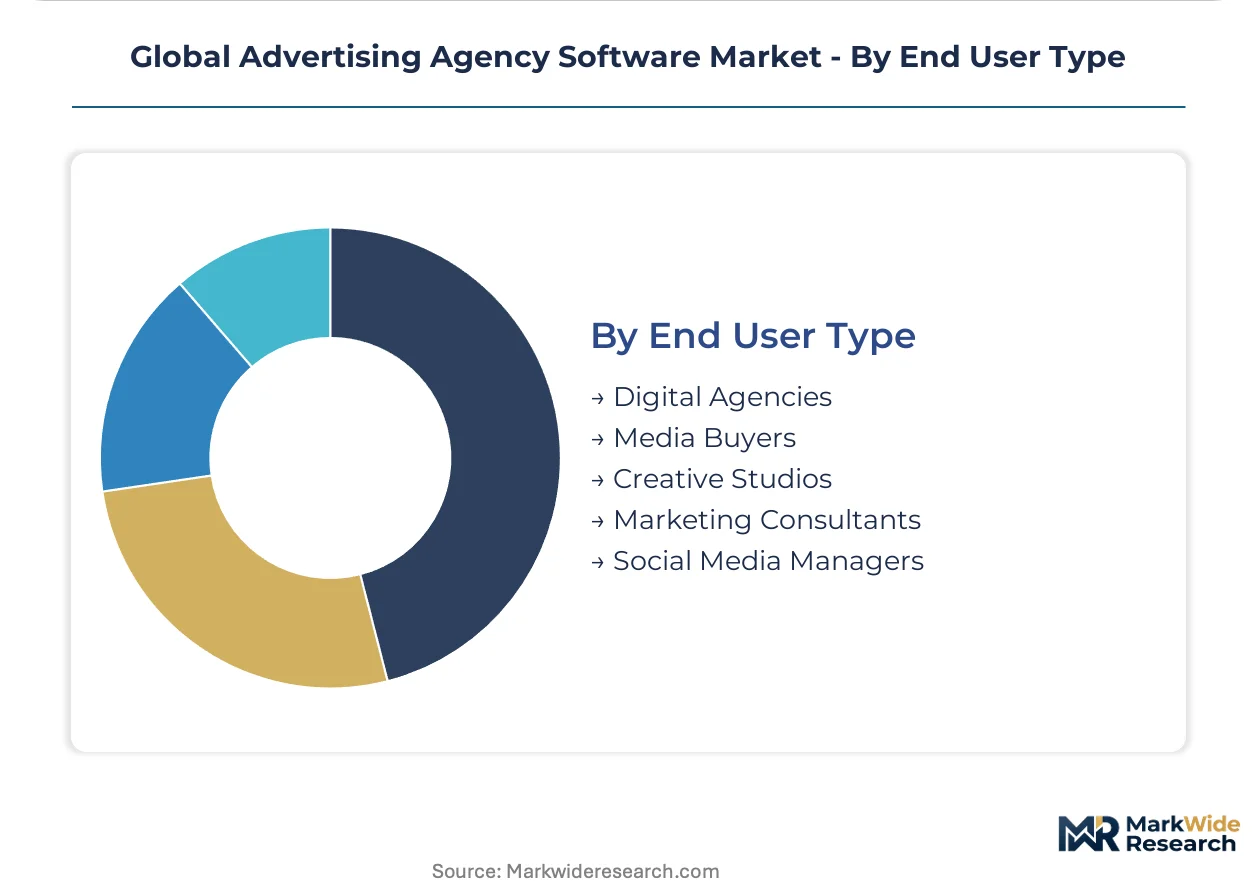
End User Type:
Procurement authority and technical sophistication create distinct vendor engagement models across user categories.
- Digital Agencies:Full-service shops with integrated creative, media, and strategy functions. These buyers in the US, Germany, and India consolidate technology decisions at the holding company or executive level.
- Media Buyers:Specialized execution teams focused on programmatic trading and inventory negotiation. Independent traders in London and New York select best-of-breed demand-side technology outside agency-mandated stacks.
- Creative Studios:Production-focused shops emphasizing asset development over media execution. Boutique operations in Berlin and Paris are expanding fastest as brand direct-to-platform procurement disintermediates traditional agency structures.
- Marketing Consultants:Strategy advisory practices without execution infrastructure. These users in Singapore and Dubai favor lightweight SaaS tools with minimal implementation overhead.
- Social Media Managers:Platform-native content and community specialists. In-house brand teams across US and UK consumer verticals are absorbing this function, reducing external agency dependency.
Digital Agencies represent the most concentrated procurement volume; Creative Studios are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while German agencies absorb compliance premiums for algorithmic transparency mandates. Indian digital shops compete on cost efficiency but face data localization pressures. United Kingdom boutiques capture creative collaboration premiums through synchronous production tools.
United States
Programmatic media buying consolidation and outcome-based client billing drive technology procurement among New York and Los Angeles full-service agencies. FTC dark-pattern enforcement and automated targeting audits reshape vendor certification requirements. Chicago-based media buyers license demand-side technology independently, accelerating disintermediation of traditional agency functions.
Germany
Automotive and pharmaceutical verticals mandate data residency for campaign analytics, sustaining on-premise infrastructure investments. EU AI Act algorithmic transparency requirements and GDPR consent-management frameworks impose auditable decision-system standards. Munich and Berlin digital agencies deploy hybrid cloud configurations to satisfy cross-border data governance while maintaining operational flexibility.
India
E-commerce performance marketing and B2B technology client acquisition fuel analytics software uptake among Mumbai and Bangalore digital shops. TRAI data localization proposals and draft data protection frameworks accelerate domestic vendor partnerships. Hyderabad-based agencies reconfigure cross-border campaign data flows to preempt regulatory enforcement timelines.
United Kingdom
Distributed creative studios and compressed production timelines expand synchronous asset development platform subscriptions. GDPR enforcement variance with France and Italy fragments compliance architecture costs for London-based multinationals. Manchester and Edinburgh boutiques adopt generative creative tools fastest, collapsing traditional production schedules from weeks to hours.
Saudi Arabia
Underdeveloped software penetration among Riyadh and Jeddah-based digital shops creates first-mover platform adoption potential. SFDA and national data governance frameworks shape how multinational agencies configure campaign infrastructure. Domestic agencies lack technical staff density, making multi-tenant SaaS architectures economically preferable to self-managed deployments.
Global Advertising Agency Software Market Competitive Landscape
Walled-garden platforms and independent demand-side technology providers split the market into divergent procurement camps. Consolidation pressure intensifies as brand direct-to-platform procurement bypasses traditional agency media buying functions. Three strategic archetypes dominate: infrastructure-integrated suites, independent programmatic specialists, and creative-to-analytics workflow platforms. Competitive moves concentrate on vertical capability acquisitions and geographic expansion into underpenetrated Middle Eastern and Southeast Asian markets.
Within the infrastructure-integrated tier, Google and Adobe occupy positions that anchor enterprise agency retainers through search, display, and creative-to-analytics workflow dominance. The Trade Desk exemplifies the independent demand-side archetype, positioning agencies outside walled-garden ecosystems through transparent programmatic technology. These three companies represent the primary competitive anchors around which mid-size agencies and boutique shops structure their technology procurement decisions.
| Leading Market Players |
|---|
| Adobe |
| The Trade Desk |
| Criteo |
| MediaMath |
| AppNexus |
| Adform |
| PubMatic |
| OpenX |
| Others |
Supply & Pricing Matrix
Transatlantic fiber-optic cable capacity constraints between Frankfurt and Virginia Beach compress margin structures for cloud-hosted campaign management platforms, amplifying price differentiation between hyperscale-backed suites and independent software vendors while forcing mid-size agencies toward multi-tenant SaaS architectures over self-managed deployments.
Pricing Analysis
The customization-premium spread separates configured-to-order private cloud deployments from standard multi-tenant SaaS tiers. Subscription-based pricing dominates, with differentiation driven by EU AI Act certification grade and integration depth with walled-garden data ecosystems. Price erosion runs through the mid-market tier as Google and Adobe bundle infrastructure-at-cost with creative workflows. Boutique creative studios exhibit highest price sensitivity; enterprise holding companies absorb premium positioning for audit-compliant algorithmic transparency.
Supply Chain Analysis
Upstream compute and storage feedstock draws from hyperscale data center concentrations in the United States, Ireland, and Singapore. NVIDIA GPU clusters, specialized AI inference chips, and low-latency edge nodes constitute critical input dependencies. Single-source vulnerability concentrates around AWS, Azure, and Google Cloud infrastructure for real-time bidding protocol processing. Distribution runs through API-first platform marketplaces and direct enterprise sales teams serving holding company procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Advertising Agency Software Market constitutes a high-growth disruption as generative AI collapses creative production timelines from weeks to hours and EU AI Act mandates force algorithmic transparency retrofitting across installed bases.
For Market Incumbents: Harden defensive moats by acquiring specialized creative collaboration vendors in London and Berlin to preempt generative AI disintermediation. Invest in EU AI Act audit trail certification to capture replacement demand from non-compliant legacy platforms. Prioritize backward integration into edge computing infrastructure to reduce hyperscale dependency. For New Entrants and Emerging Players: Build out white-space presence in Riyadh and Jeddah where domestic agencies lack technical density for self-managed infrastructure. Target creative studios disintermediated by brand direct-to-platform procurement with lightweight synchronous asset development tools. Pursue partnership-first go-to-market with Indian domestic vendors navigating TRAI data localization requirements. For Investors and Strategic Acquirers: Independent demand-side technology specialists with transparent programmatic positioning offer prime acquisition exposure as holding companies seek alternatives to walled-garden ecosystems. Long-term viability hinges on sustained outcome-based billing adoption justifying integrated attribution investments. Monitor Connected TV inventory integration velocity as inflection indicator for programmatic video infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies creative-to-analytics workflows for EU AI Act compliance across multinational brand portfolios. |
| Acquisition of Specialist Firm | Captures generative AI capabilities from Berlin and London boutique studios compressing production timelines. |
| Geographic Expansion | Establishes first-mover SaaS presence among Riyadh and Jeddah agencies lacking technical staff density. |
| Strategic Partnership | Aligns with Indian domestic vendors to preempt TRAI data localization enforcement on cross-border campaigns. |
| Product Launch | Deploys explainable targeting logic with human-override capabilities for GDPR and EU AI Act audit requirements. |
Research Methodology
Initial hypotheses were tested against primary input from agency CTOs, programmatic trading directors, creative studio heads, and holding company procurement officers and refined through secondary validation against SEC filings from listed software vendors, hyperscaler capex disclosures, EU regulatory filings on algorithmic transparency, and App Annie platform adoption metrics. Bottom-up sizing from individual vendor revenue streams converged with top-down demand modeling across deployment modes and use cases.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed deployment architecture, agency scale tier, vertical industry focus, and cross-border data governance complexity. CAGRs derived from logistic adoption curves fitted to programmatic technology penetration patterns. Forecast inputs incorporated Connected TV inventory growth trajectories and EU AI Act implementation timelines.
Practitioners should monitor Connected TV adoption velocity, EU AI Act enforcement variance across Germany and France, and hyperscale pricing actions for early signals warranting forecast revision. Cross-checking against IAB programmatic spending benchmarks and holding company technology disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
United States Marketing Agencies Market
Advertising and Marketing Media
Middle East and Africa Programmatic Advertising Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Digital Out of Home (OOH) Advertising Market
Advertising and Marketing Media
South East Asia Advertising Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Chile OOH and DOOH Market
Advertising and Marketing Media
In-App Advertising Market