
 France Digital Out-Of-Home (DOOH) Advertising Market | 2026-2036
France Digital Out-Of-Home (DOOH) Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
France Digital Out-Of-Home (DOOH) Advertising Market Insights
Retail and entertainment brand budgets are rebalancing toward transit and street furniture networks as post-pandemic foot traffic patterns stabilize. JCDecaux SE dominates Parisian airport and street furniture concessions through decades-long municipal contracts. Clear Channel France SAS leverages its nationwide transit display portfolio to anchor programmatic revenue streams across RATP-affiliated properties. Médiatransports specializes in rail-centric inventory along SNCF corridors, competing with national broadcast media for commuter attention spans.
Digital Out-Of-Home (DOOH) Advertising encompasses networked electronic display systems—typically LED, LCD, or projection-based—deployed in public spaces for commercial messaging, operating through content management systems that enable remote scheduling and audience analytics. These installations require IP connectivity, ambient light sensors, and thermal management to sustain visibility across variable outdoor conditions, serving advertisers seeking contextual relevance beyond residential screens. Digital billboards and transit displays command the largest share of installed base, though programmatic buying represents the fastest-expanding revenue mechanism as demand-side platforms integrate geofenced mobile data. Video ads and interactive content capture disproportionate creative investment, while static images retain utility in bandwidth-constrained or cost-sensitive deployments.
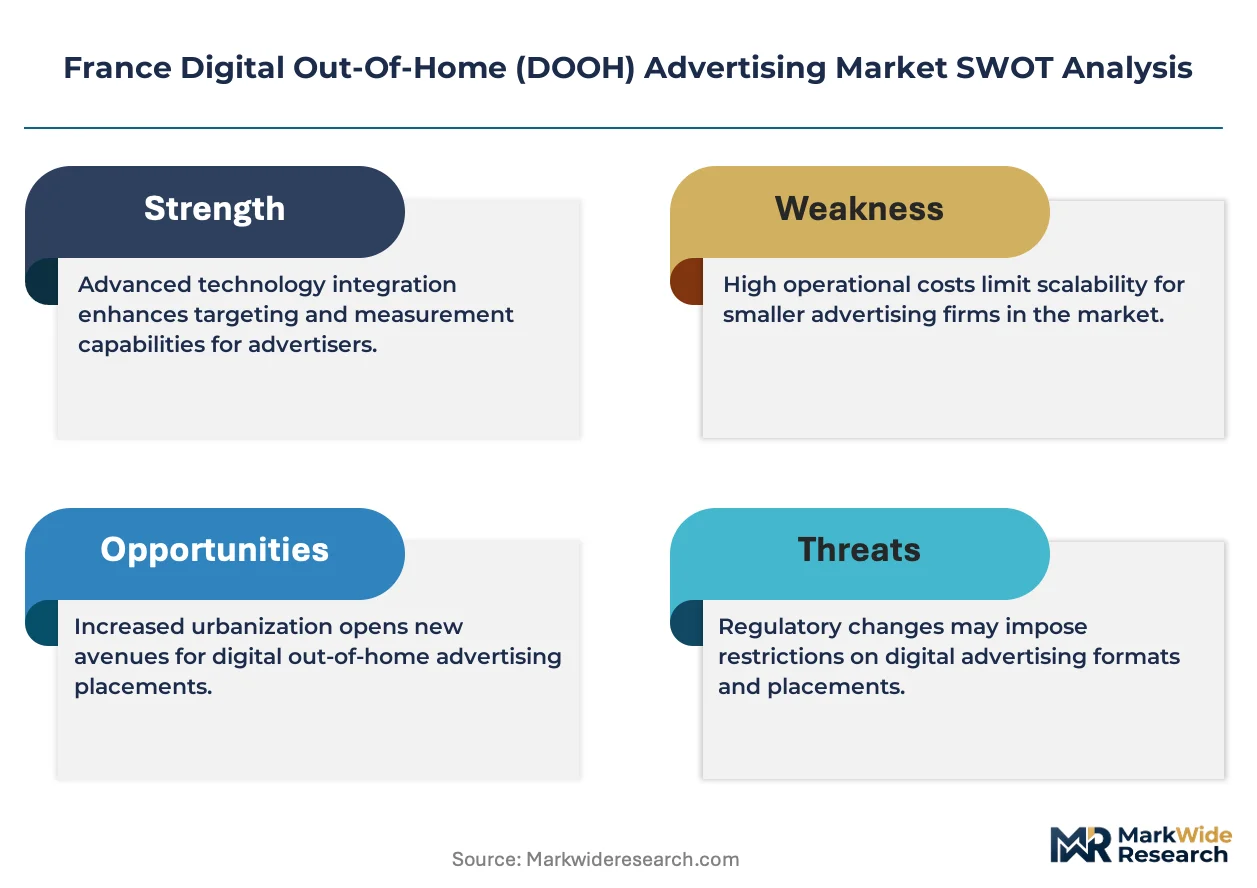
France's national advertising regulator, the ARPP, enforces truth-in-advertising standards that extend to DOOH content, while CNIL oversight of audience measurement technologies shapes data collection practices for programmatic targeting. The EU AI Act introduces compliance obligations for automated content personalization systems deployed in public spaces. Stakeholders must monitor how CNIL interprets biometric inference restrictions against camera-based attention metrics, as this determination will either unlock or constrain the next generation of audience-verified pricing models.
Market Dynamics
Programmatic trading infrastructure is compressing media buying cycles from weeks to hours across French transit and street furniture networks. The shift from static contract-based sales to real-time auction mechanics is redistributing margin capture toward data-enabled intermediaries and away from traditional concession holders.
Growth Catalysts
- EU Green Deal LED retrofit mandates:Municipal authorities in Paris, Lyon, and Marseille face binding energy-efficiency deadlines for public advertising infrastructure. Display replacement cycles are accelerating as legacy fluorescent and neon systems reach end-of-life under national decarbonization schedules.
- RATP and SNCF transit expansion:Metro, rail, and bus terminal screen density is increasing across Île-de-France and regional corridors. Commuter foot traffic recovery post-pandemic has restored audience reach metrics that advertisers require for budget allocation.
- Geofenced mobile data integration:Demand-side platforms are incorporating carrier-derived location signals for audience segmentation. This capability enables impression-level targeting that static billboards cannot replicate.
Market Restraints
- CNIL biometric inference restrictions:Camera-based attention measurement systems face uncertain compliance classification under France's data protection authority. Pending determinations on whether gaze tracking constitutes biometric processing are freezing capital deployment for next-generation analytics.
- Municipal concession concentration:Decades-long exclusive contracts for premium Parisian airport and street furniture inventory limit new entrant access. Incumbent operators control inventory aggregation that programmatic platforms require for liquidity.
- Energy input cost volatility:LED display operation depends on grid electricity subject to EU-wide price fluctuations. Thermal management and ambient light sensor optimization cannot fully offset exposure to wholesale power markets.
Strategic Opportunities
- Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur regional penetration:Secondary city transit authorities in Lyon and Marseille maintain less consolidated concession structures than Paris. Programmatic-first operators can establish inventory relationships before municipal contract renewal cycles.
- EU AI Act automated personalization compliance:Early alignment with emerging AI governance frameworks for public-space content systems creates differentiation. Operators demonstrating transparent algorithmic decision documentation may access public-sector advertising budgets with stringent procurement requirements.
- 5G network slicing and edge computing convergence:Low-latency connectivity enables interactive and augmented reality content delivery without local processing hardware. This architecture reduces capex per installation while enabling dynamic creative formats.
Industry Challenges
- Programmatic talent scarcity:The intersection of outdoor media operations and real-time bidding technology requires skill sets concentrated in digital advertising rather than traditional out-of-home. Recruitment competition with pure-play ad tech vendors elevates compensation costs.
- Legacy content management system integration:Decades-old scheduling infrastructure in municipal transit authorities lacks API connectivity for automated trading. Middleware development and security certification timelines extend deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Digital Out-Of-Home (DOOH) Advertising Market |
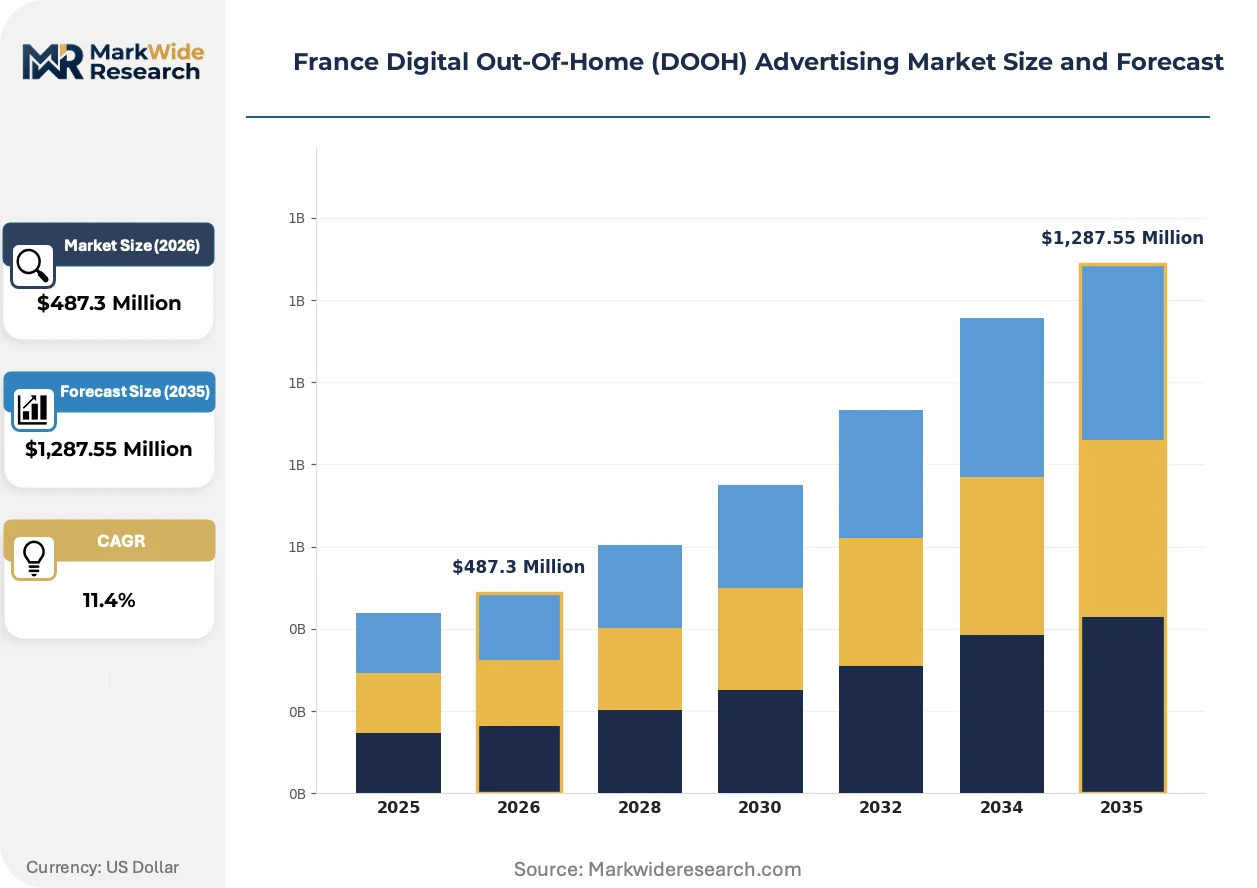
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,287.55 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Digital Billboards, Transit Displays, Indoor Screens, Street Furniture Content Format: Video Ads, Static Images, Interactive Content, Augmented Reality Advertising Strategy: Programmatic Buying, Location-Based Targeting, Real-Time Bidding, Event-Based Advertising Industry Sector: Retail, Entertainment, Automotive, Education |
| Companies Covered | JCDecaux SE, Clear Channel France SAS, Médiatransports, ExterionMedia, Vistar Media, DooH it, Exterior Plus, VIOOH, Quividi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Digital Out-Of-Home (DOOH) Advertising Market Trends and Innovations
Data-driven impression verification is displacing traditional audience estimation methods across French DOOH networks. The convergence of mobile location signals, computer vision, and programmatic infrastructure is redefining how inventory is priced and traded.
Edge computing nodes deployed at screen locations are electrifying content rendering and audience analytics capabilities. Retail and entertainment brands adopting these installations gain sub-second creative adaptation based on environmental and demographic triggers. This distributed architecture is compressing the gap between digital and physical advertising performance measurement.
France's national advertising regulator ARPP is extending truth-in-advertising enforcement to algorithmically selected DOOH content. The industrial consequence is mandatory human oversight requirements for automated creative rotation systems. Transit and street furniture operators in Paris are responding by building compliance documentation workflows that satisfy both ARPP standards and EU AI Act transparency obligations.
Buyer procurement patterns are fragmenting across centralized agency holding companies and direct brand relationships. National retailers are establishing in-house programmatic trading desks that bypass traditional media buying intermediaries. This disintermediation is most visible in Île-de-France, where premium inventory scarcity has intensified competition for direct access to RATP-affiliated display networks.
France Digital Out-Of-Home (DOOH) Advertising Market Segmentation
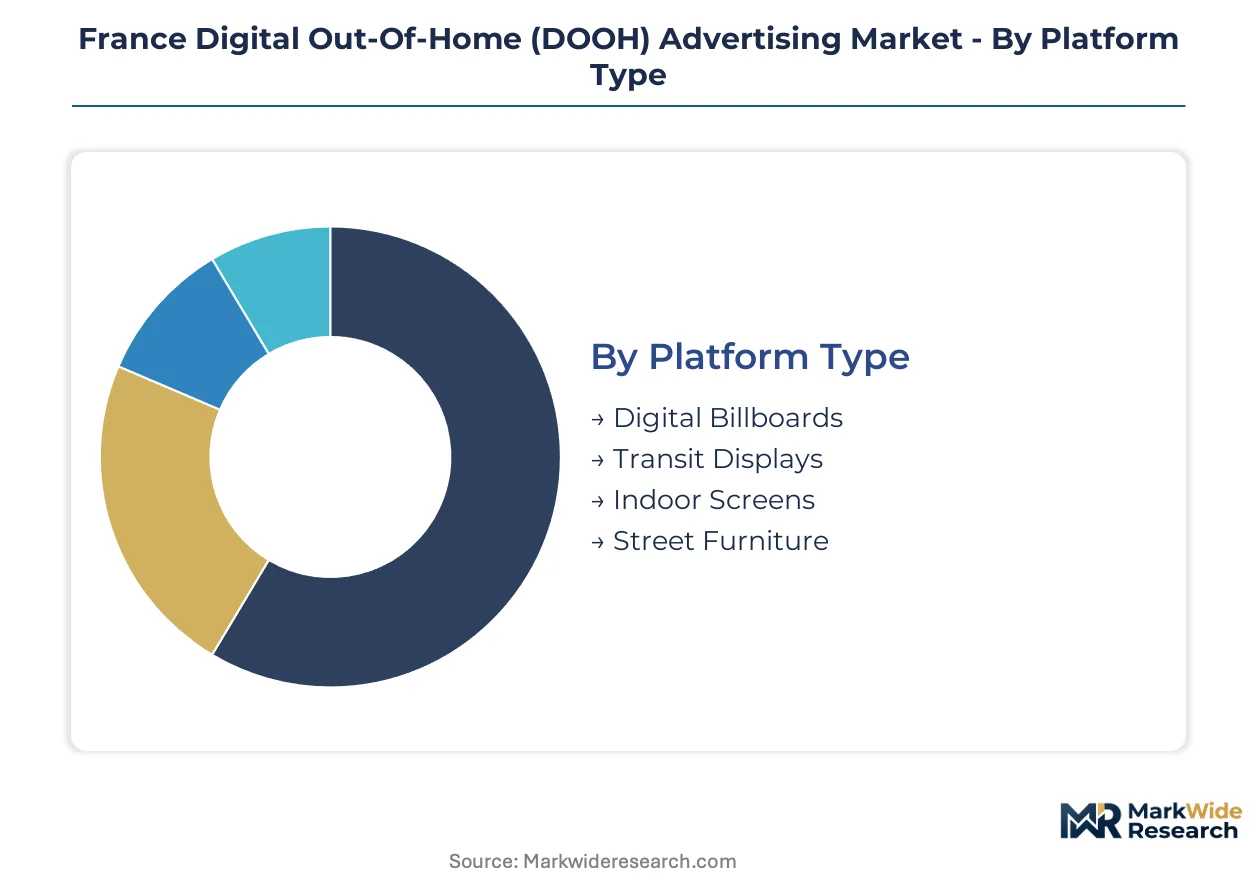
Platform specifications determine deployment economics and regulatory exposure across French DOOH networks. Content format choices shape bandwidth requirements and creative production workflows. Advertising strategy selection separates data-enabled operators from legacy contract-based sellers.
Platform Type:
LED and LCD specifications define visibility range, thermal management needs, and municipal compliance thresholds across French installations.
- Digital Billboards:Large-format LED installations mounted on highways and urban thoroughfares require high-lumen output for daylight visibility. Premium inventory along A1 and A6 autoroutes commands the highest CPM rates in Île-de-France as automotive and luxury brands compete for commuter attention.
- Transit Displays:Networked screens in RATP metro stations and SNCF rail terminals operate under concession agreements with stringent energy-efficiency mandates. Post-pandemic foot traffic recovery in Paris Gare du Nord and Lyon Part-Dieu has restored audience metrics that national advertisers require for budget allocation.
- Indoor Screens:LCD panels deployed in retail malls and entertainment venues operate in climate-controlled environments with lower thermal management costs.
- Street Furniture:Bus shelter and kiosk displays integrate ambient light sensors for automatic brightness adjustment across variable daylight conditions.
Digital billboards lead on scale; transit displays lead on momentum.
Content Format:
Production complexity and data transmission requirements separate premium creative formats from operational staples in French network planning.
- Video Ads:Motion-based creative formats require 4-10x bandwidth versus static alternatives and command production budgets that concentrate in retail and entertainment verticals. Advertisers in Paris premium transit zones prioritize video for brand recall metrics that static formats cannot replicate.
- Static Images:JPEG and PNG formats retain utility in bandwidth-constrained rural deployments and legacy content management systems. Municipal transit authorities in secondary cities maintain static-heavy rotations due to infrastructure upgrade timelines.
- Interactive Content:Touch-enabled and QR-code-triggered experiences demand edge computing nodes at screen locations.
- Augmented Reality:Camera-overlay experiences face CNIL scrutiny for biometric inference risks under pending regulatory determinations.
Video ads dominate revenue concentration; interactive content shows the steepest expansion trajectory.
Advertising Strategy:
Automation depth and data integration sophistication define margin capture and competitive differentiation in French DOOH trading.
- Programmatic Buying:Real-time auction mechanics through demand-side platforms enable impression-level targeting using geofenced mobile carrier data. Transit and street furniture operators in Île-de-France are prioritizing API connectivity to capture agency trading desk budgets.
- Location-Based Targeting:GPS-derived audience segmentation enables proximity-triggered creative rotation for retail and quick-service restaurant campaigns.
- Real-Time Bidding:Open exchange participation requires inventory liquidity that only consolidated networks in Paris currently satisfy.
- Event-Based Advertising:Triggered deployments around sports fixtures and cultural festivals demand rapid creative turnaround capabilities.
Programmatic buying leads on scale; event-based advertising leads on momentum.
Industry Sector:
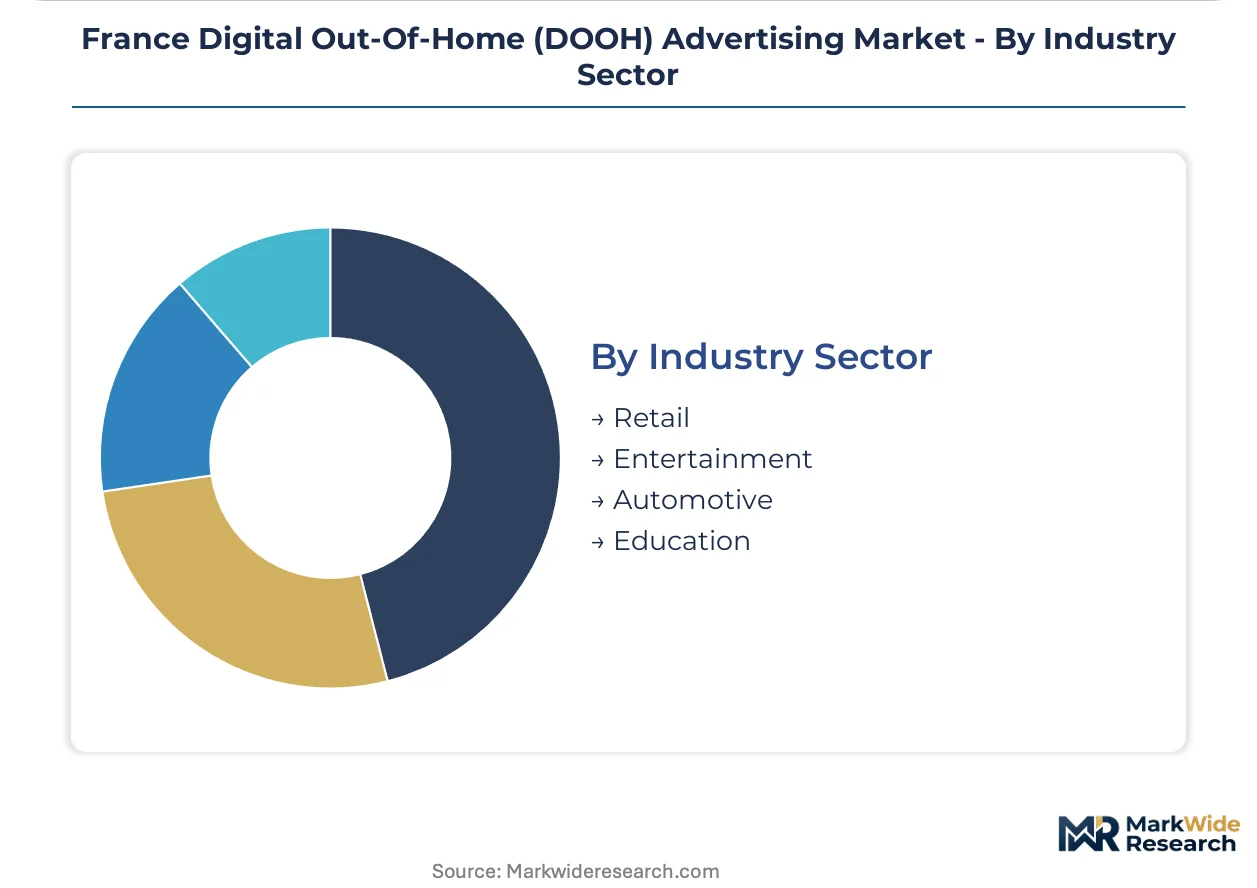
End-use concentration shapes seasonal demand patterns and creative format preferences across French DOOH inventory.
- Retail:National fashion and grocery chains are establishing in-house programmatic trading desks that bypass traditional media buying intermediaries. Direct relationships with RATP-affiliated networks in Île-de-France have intensified as premium inventory scarcity elevates competition.
- Entertainment:Cinema, streaming, and live event promoters prioritize video-heavy rotations in transit corridors with high evening commuter density.
- Automotive:Premium and electric vehicle manufacturers concentrate spend on highway digital billboards and airport terminals.
- Education:Universities and vocational training providers utilize static formats in secondary city transit networks.
Retail leads on scale; entertainment leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between French sub-regions are redirecting programmatic platform deployment toward secondary cities with less consolidated concession structures. Municipal contract renewal cycles in Lyon and Marseille create entry windows unavailable in Paris. Operators seeking inventory aggregation outside Île-de-France face lower barriers but thinner liquidity.
Île-de-France
RATP-affiliated metro and rail terminals concentrate premium DOOH inventory with the highest programmatic trading volumes in France. The EU AI Act transparency obligations apply directly to automated content systems deployed in Paris transit hubs. JCDecaux SE and Clear Channel France SAS anchor their nationwide operations through decades-long concessions in Charles de Gaulle Airport and Gare du Nord.
Auvergne-Rhône-Alpes
Lyon Part-Dieu and Perrache stations generate commuter density metrics comparable to secondary Paris terminals at lower CPM rates. France's national digital infrastructure investments extend LED retrofit mandates to SYTRAL-operated transit properties. Less consolidated concession structures allow programmatic-first operators to establish inventory relationships before municipal contract renewals.
Provence-Alpes-Côte d'Azur
Marseille Saint-Charles rail terminus and Aix-en-Provence TGV station anchor regional DOOH demand from tourism and luxury retail advertisers. CNIL biometric inference restrictions apply uniformly but enforcement intensity varies outside Paris scrutiny zones. RTM bus shelter networks maintain fragmented ownership that favors new entrant aggregation strategies.
Hauts-de-France
Lille Eurostar terminal and regional SNCF corridors serve cross-border commuter flows into Belgium. EU Green Deal energy-efficiency deadlines bind municipal authorities to accelerated display replacement cycles. Secondary city transit authorities in Lens and Amiens lack API-connected content management systems, extending deployment timelines for automated trading.
Nouvelle-Aquitaine
Bordeaux Saint-Jean station and Biarritz transit networks support seasonal tourism advertising demand with event-triggered deployment patterns. France's national decarbonization schedules mandate LED retrofits for public advertising infrastructure in coastal municipalities. Local operators control fragmented street furniture inventory that resists programmatic liquidity aggregation.
France Digital Out-Of-Home (DOOH) Advertising Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with concession-holding incumbents controlling premium Paris inventory while technology vendors supply programmatic infrastructure. The market exhibits tiered concentration: JCDecaux SE and Clear Channel France SAS dominate airport and transit concessions through municipal relationships, while ad tech intermediaries capture margin from data-enabled trading. Three archetypes define competitive positioning: legacy concession operators with decades-long municipal contracts, programmatic technology vendors integrating geofenced mobile data, and analytics specialists developing attention-measurement systems. Dominant competitive moves include API connectivity investments for automated trading integration and compliance documentation workflows satisfying ARPP and EU AI Act obligations.
Among France-based concession operators, JCDecaux SE exemplifies the integrated municipal-contract archetype through its Paris airport and street furniture portfolio. Clear Channel France SAS occupies a comparable position in RATP-affiliated transit properties nationwide. Médiatransports represents the rail-specialist tier, anchoring inventory relationships along SNCF corridors outside Île-de-France concentration.
| Leading Market Players |
|---|
| JCDecaux SE |
| Clear Channel France SAS |
| Médiatransports |
| ExterionMedia |
| Vistar Media |
| DooH it |
| Exterior Plus |
| VIOOH |
| Quividi |
| Others |
Pricing and Supply Chain Analysis
Captive LED panel production in East Asian manufacturing clusters anchors both supply security and margin structure for French DOOH operators. JCDecaux SE and Clear Channel France SAS leverage long-term component offtake agreements to buffer against spot-market volatility in display hardware while preserving pricing power in premium Paris transit inventory.
Pricing Analysis
Direct-to-transit-authority contract pricing dominates the French market, bypassing distributor markups that inflate costs in fragmented street furniture segments. Price differentiation rests on concession exclusivity duration and energy-efficiency certification tier under EU Green Deal mandates. Cost compression in secondary city deployments is intensifying because SYTRAL and RTM authorities negotiate shorter contract cycles. Municipal transit buyers exhibit highest price sensitivity; luxury automotive advertisers at Charles de Gaulle Airport show least.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Seoul, and Taipei feed LED module assembly operations that supply French installation contractors. Display hardware draws from gallium nitride substrates, driver ICs, and aluminum heat-sink components. Single-source vulnerability concentrates in advanced LED driver semiconductors from South Korean foundries. Distribution runs through specialized AV integrators with CNIL security certification rather than generalist electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France DOOH market functions as a regulatory compounder where EU AI Act transparency obligations and CNIL biometric rulings will progressively advantage compliant operators over the analysis window.
For Market Incumbents: Deploy API connectivity infrastructure to defend programmatic revenue streams against ad tech intermediaries capturing margin from data-enabled trading. Consolidate middleware development capabilities to accelerate legacy content management system integration at SNCF-affiliated properties. Threat: programmatic-first entrants establishing inventory relationships before Lyon and Marseille municipal contract renewals. For New Entrants and Emerging Players: Programmatic trading desk relationships offer the most penetrable route into French DOOH, bypassing decades-long concession barriers in Paris. Target Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur regional transit authorities with SYTRAL and RTM fragmentation. Go-to-market: edge computing partnerships with 5G network slicing providers for interactive content delivery without local hardware capex. For Investors and Strategic Acquirers: Consolidation pressure builds where municipal contract renewal cycles in secondary cities create inventory aggregation opportunities unavailable in Paris. Long-term viability favors operators with documented EU AI Act compliance workflows and CNIL-aligned audience measurement architectures. Signal to watch: CNIL determination on gaze-tracking classification as biometric processing.| Strategic Initiative | Industry Significance |
|---|---|
| API Connectivity Investment | Enables automated trading integration with agency demand-side platforms across RATP properties. |
| EU AI Act Compliance Documentation | Unlocks public-sector advertising budgets with stringent algorithmic transparency procurement requirements. |
| Edge Computing Node Deployment | Reduces screen-level hardware capex while enabling sub-second creative adaptation via 5G slicing. |
| Regional Concession Pre-emption | Establishes inventory aggregation in Lyon and Marseille before SYTRAL and RTM contract renewals. |
| CNIL-Aligned Analytics Architecture | Preserves attention-measurement revenue streams pending biometric inference regulatory determination. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with DOOH network operations directors, programmatic trading desk heads, municipal transit procurement officers, and ARPP compliance leads with secondary validation against RATP annual reports, SNCF infrastructure disclosures, CNIL regulatory guidance documents, and EU Green Deal implementation schedules. Bottom-up inventory aggregation estimates and top-down advertising spend allocation models were triangulated for convergence.
Segment-weighting approaches distributed value across platform type, content format, advertising strategy, and industry sector dimensions throughout the forecast period. CAGRs were derived from fitted growth curves calibrated to LED retrofit mandate deadlines and transit expansion timelines. Key inputs included concession contract renewal schedules, programmatic adoption trajectories in French media agencies, and 5G network deployment milestones affecting edge computing viability.
The model assumes a particular technology adoption path; alternative pathways for camera-based attention measurement would alter the outlook if CNIL restricts biometric inference more stringently than baseline assumptions. Forecasts reflect documented assumptions around municipal concession structures and energy-efficiency compliance timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Online Advertising Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
North America Advertising Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
Digital Ad Spending Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Digital OOH Advertising Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
Italy OOH and DOOH Market