
 Middle East and North Africa Digital Out-Of-Home (DOOH) Market | 2026-2036
Middle East and North Africa Digital Out-Of-Home (DOOH) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and North Africa Digital Out-Of-Home (DOOH) Market Foresight
Programmatic inventory trading is reconfiguring margin pools away from static placement fees toward data-augmented audience targeting. BackLite Media LLC leverages its premium roadside estate across Dubai and Abu Dhabi to sustain rate premiums on Sheikh Zayed Road corridors. JCDecaux SE anchors transit concession networks in Riyadh and Doha, competing for airport and metro exclusivity. Hypermedia FZ LLC specializes in retail mall networks, occupying high-dwell environments across UAE shopping destinations.
Digital Out-Of-Home refers to electronically displayed advertising content delivered via networked screens in public and semi-public spaces, typically operating at 500-5,000 nits brightness for daylight visibility and remotely managed through content management systems. The primary commercial purpose is to capture consumer attention during transit, dwell, or purchase moments with dynamic, contextually relevant messaging. LED deployment commands the largest revenue share given its scalability to monumental roadside formats, while interactive screen technology generates the fastest growth as gesture and mobile-responsive capabilities expand. Dynamic content programming, including weather-triggered and real-time data feeds, captures expanding media budgets from brands seeking contextual relevance.
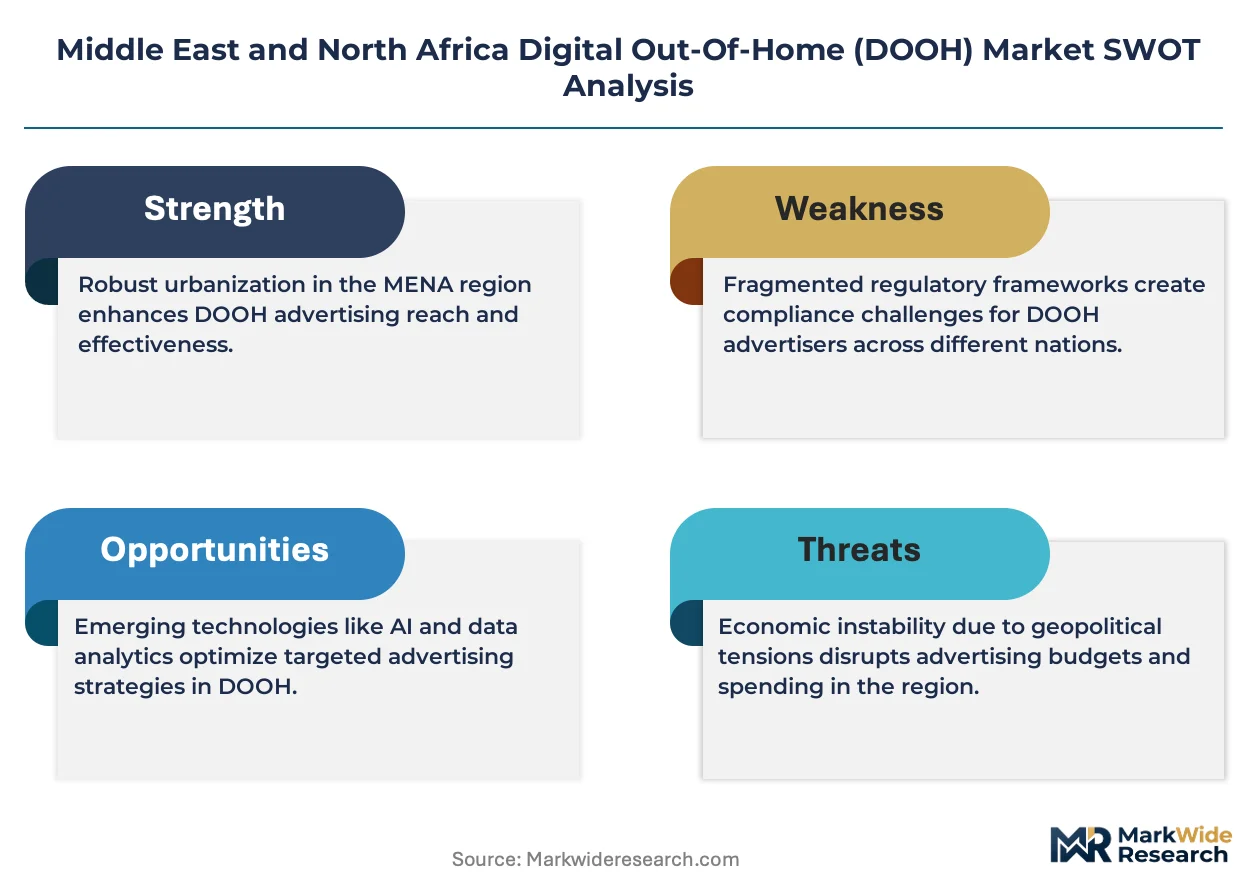
UAE's Telecommunications and Digital Government Regulatory Authority and Saudi Communications, Space and Technology Commission set electromagnetic emissions and content standards for networked displays, while Egypt's National Telecommunications Regulatory Authority governs spectrum allocation for connected signage. TRAI-equivalent bodies across North Africa are drafting data localization rules that will constrain cross-border audience profiling. Stakeholders must monitor evolving content compliance frameworks and spectrum licensing costs as regulatory divergence between Gulf and Maghreb jurisdictions intensifies.
Market Dynamics
Programmatic trading infrastructure is restructuring revenue capture across the Middle East and North Africa Digital Out-Of-Home ecosystem, displacing static rate cards with real-time audience-based pricing models that reward data-enriched inventory.
Growth Catalysts
- Smart city transit mandates:Dubai and Riyadh authorities are embedding DOOH networks into metro and bus infrastructure as mandatory digital communication layers, creating captive audience environments for advertisers.
- LED brightness standardization:Gulf regulators have adopted 500-5,000 nits visibility specifications that accelerate replacement of static billboards with daylight-readable digital formats.
- Data localization frameworks:Saudi Communications, Space and Technology Commission and UAE Telecommunications and Digital Government Regulatory Authority rules on domestic audience data processing are legitimizing privacy-compliant targeting for premium CPM rates.
Market Restraints
- Copper and semiconductor input volatility:LED module production depends on fluctuating rare earth and chip supply from East Asian foundries, compressing hardware margins on large-format roadside deployments.
- Spectrum licensing cost escalation:Egypt's National Telecommunications Regulatory Authority and Maghreb equivalents are auctioning 5G-adjacent bands used for networked signage connectivity, raising recurring operational expenditures.
- Static print residual preference:Heritage outdoor advertisers in North African markets maintain budget allocation to traditional paper-based formats, slowing digital conversion timelines outside Gulf urban cores.
Strategic Opportunities
- Morocco and Algeria urban corridors:Casablanca and Algiers retail districts remain underpenetrated by programmatic-enabled networks, offering first-mover positioning for mall and transit concession operators.
- Gesture-responsive interactive screens:Convergence of computer vision and mobile Bluetooth beacon technology enables dwell-time extension in high-traffic retail environments, commanding rate premiums over passive display inventory.
- Weather-triggered dynamic content:Real-time meteorological API integration allows advertisers to automate creative rotation based on temperature and air quality conditions, capturing incremental media budgets from weather-sensitive categories.
Industry Challenges
- Creative technologist scarcity:The intersection of data science, motion design, and hardware deployment expertise remains concentrated in Dubai and Riyadh, constraining network expansion into secondary MENA cities.
- Legacy CMS integration friction:Established roadside operators maintain proprietary content management architectures that resist API-based interoperability with programmatic demand-side platforms, complicating unified campaign execution.
- Electromagnetic emissions certification delays:Gulf regulatory testing protocols for networked display installations extend deployment timelines by 8-14 weeks, compressing campaign launch windows for time-sensitive advertisers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and North Africa Digital Out-Of-Home (DOOH) Market |
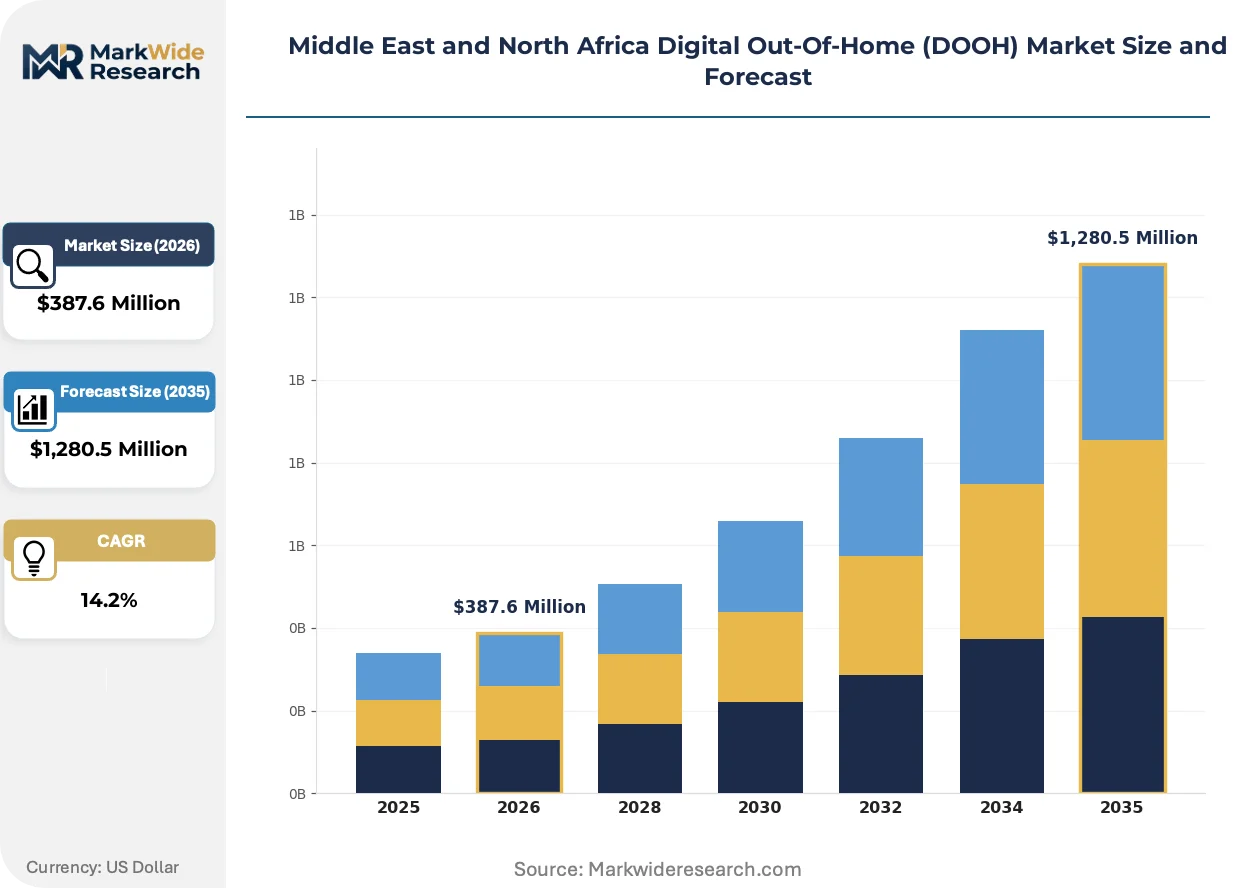
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Billboards, Transit Displays, Street Furniture, Retail Displays Technology: LED, LCD, Projection, Interactive Screens Customer Type: Advertisers, Agencies, Media Owners, Brands Content Type: Static Ads, Video Ads, Dynamic Content, Interactive Campaigns |
| Companies Covered | JCDecaux SE, ELAN Media W.L.L., BackLite Media LLC, Hypermedia FZ LLC, Abu Dhabi Media Company PJSC, Hills Advertising L.L.C., Elevision, Dooha Media, Mubashir, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and North Africa Digital Out-Of-Home (DOOH) Market Shifts & Advancements
Connectivity architecture and measurement methodology are converging to transform how inventory is valued and transacted across MENA DOOH networks, shifting buyer preference toward impression-verified placements over legacy location-based rate cards.
LED display technology is hybridizing with transparent and flexible substrate formats, enabling architectural integration into building facades and retail window environments that were previously inaccessible to conventional rigid panels. Luxury automotive and beauty brands operating in Dubai Mall and Riyadh Boulevard districts are piloting these formats at 3-4x standard CPM rates. This fusion is compressing the distinction between structural architecture and advertising surface, expanding addressable inventory without requiring additional real estate acquisition.
UAE and Saudi data privacy frameworks are mandating on-device audience processing rather than cloud-based facial analysis, forcing network operators to deploy edge computing hardware at screen locations. This regulatory pivot raises capital requirements per installation but creates compliance-based competitive moats against unlicensed competitors. Premium mall networks in Doha and Abu Dhabi are responding fastest, leveraging existing IT infrastructure partnerships to absorb edge deployment costs.
Advertiser buying patterns are fragmenting from annual fixed-site commitments toward flight-based audience guarantees traded through private marketplace deals. Media agencies representing FMCG and telecom clients are unbundling creative production from media placement, demanding impression-level verification through mobile device proximity signals. This behavioral pivot is most visible in Dubai and Jeddah, where programmatic-enabled inventory now commands 40-60% share of agency RFP volume.
Middle East and North Africa Digital Out-Of-Home (DOOH) Market Segmentation
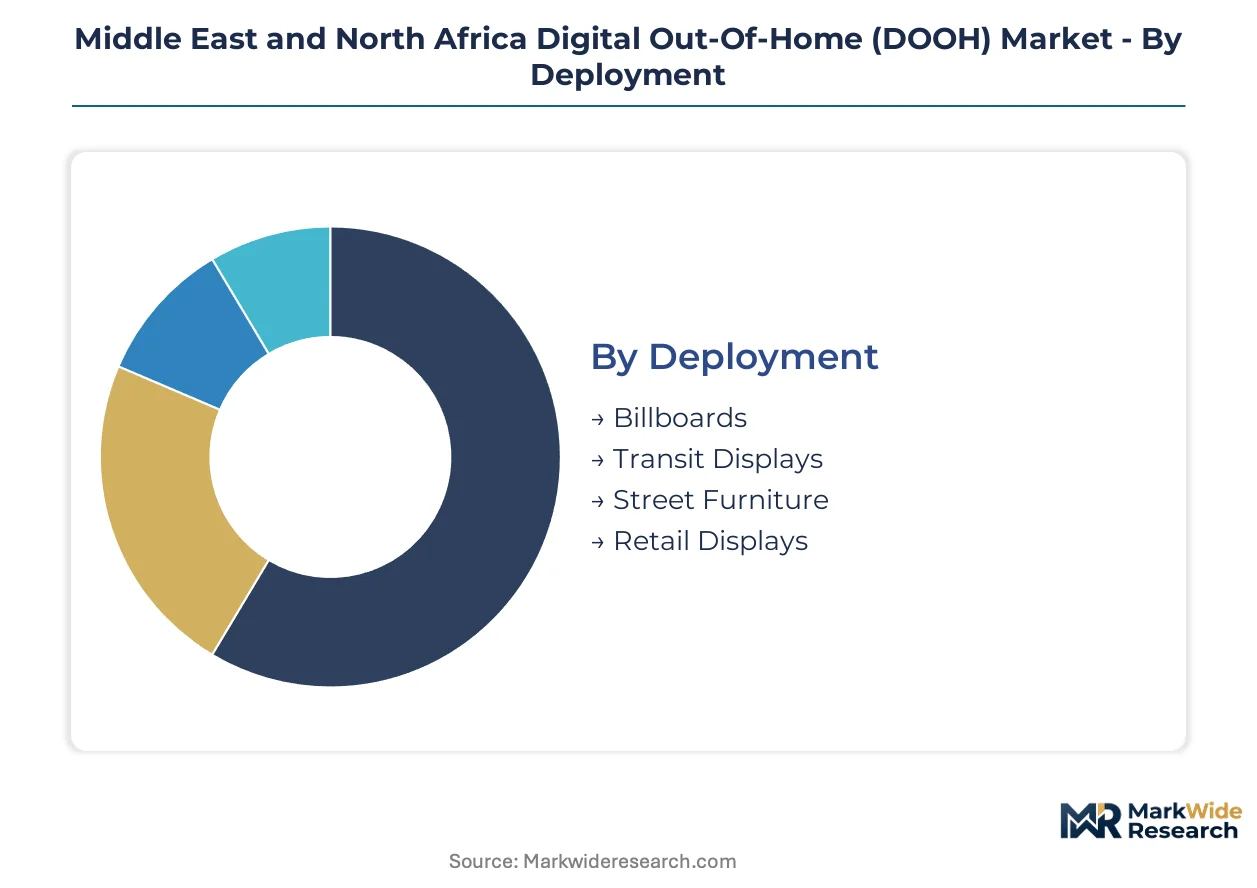
Segmentation reveals how capital cycles and margin structures vary across the MENA DOOH landscape. Deployment format determines hardware replacement cadence, while technology choice shapes energy costs and content flexibility. Understanding these divisions exposes where pricing power concentrates.
Deployment:
Billboards turn over slowest at 7-10 year replacement cycles, while retail displays refresh fastest as mall operators chase tenant turnover. Transit and street furniture occupy intermediate positions tied to municipal concession renewals.
- Billboards:Monumental roadside formats at 500-5,000 nits brightness dominate arterial corridors like Sheikh Zayed Road and Riyadh's King Fahd Road. Saudi Arabia and UAE authorities mandate daylight visibility standards that accelerate LED conversion from static vinyl. Hardware depreciation extends across decade-long asset lives, compressing annual capital intensity despite high absolute installation costs.
- Transit Displays:Metro, bus shelter, and airport screen networks embed into Dubai RTA and Riyadh Metro infrastructure as mandatory digital communication layers. Captive audience environments during commute dwell times command rate premiums over roadside inventory. Concession agreements typically span 5-7 years, creating predictable revenue visibility but limiting operator flexibility.
- Street Furniture:Kiosks, benches, and wayfinding-integrated screens occupy pedestrian zones in Doha Corniche and Abu Dhabi waterfront districts. Municipal ownership of right-of-way forces revenue-sharing structures that dilute operator margins versus wholly-owned billboard estates.
- Retail Displays:Mall atrium, elevator, and food court screens in Dubai Mall and Riyadh Boulevard capture high-dwell purchase moments. Tenant churn drives 3-5 year hardware refresh cycles, fastest among deployment categories. Interactive capabilities and mobile beacon integration expand fastest here.
Billboards dominate installed base across Gulf urban corridors. Retail displays are where expansion concentrates as mall operators digitize common areas.
Technology:
Cost tiers separate legacy LCD from premium LED and emerging interactive formats. Energy consumption and content flexibility drive technology selection more than hardware price alone.
- LED:Scalable to monumental formats with 100,000-hour operational lifespans and superior sunlight readability. Saudi Arabia's CSTC electromagnetic emissions certification adds 8-14 week deployment delays but creates compliance barriers against low-cost imports. LED commands the largest revenue share given roadside format dominance.
- LCD:Lower capital cost per square meter suits indoor retail and transit shelter applications where ambient light is controlled. Egypt's NTRA spectrum licensing for networked connectivity raises recurring operational expenditures that erode LCD's hardware cost advantage.
- Projection:Temporary architectural mapping and event-based activations in Dubai Festival City and Riyadh Season deployments. High setup labor and weather sensitivity constrain permanent installation economics.
- Interactive Screens:Gesture-responsive and mobile-integrated displays extend dwell time in mall environments. Computer vision and Bluetooth beacon convergence enables audience measurement that programmatic buyers demand. This technology is climbing the fastest as privacy-compliant edge computing satisfies UAE TDRA and Saudi CSTC data localization mandates.
LED anchors revenue concentration across Gulf roadside networks. Interactive screens are gaining share fastest as agencies unbundle creative from placement and demand impression verification.
Customer Type:
Procurement patterns diverge between direct advertiser relationships and agency-mediated buying. Media owners' infrastructure investments shape available inventory quality.
- Advertisers:Direct brand relationships with telecom and automotive clients in UAE and Saudi Arabia. Flight-based audience guarantees through private marketplace deals are displacing annual fixed-site commitments.
- Agencies:Media buyers representing FMCG and banking clients fragment RFPs across programmatic-enabled networks. Impression-level verification through mobile proximity signals now dominates Dubai and Jeddah RFP criteria.
- Media Owners:BackLite Media, JCDecaux, and Hypermedia control premium estate and set rate benchmarks. Infrastructure capital requirements and concession politics limit new entrant scale.
- Brands:Luxury automotive and beauty advertisers pilot transparent and flexible LED substrates at 3-4x standard CPM rates in Dubai Mall and Riyadh Boulevard districts.
Media owners control physical access to audiences. Agencies are where buying behavior shifts fastest toward programmatic trading.
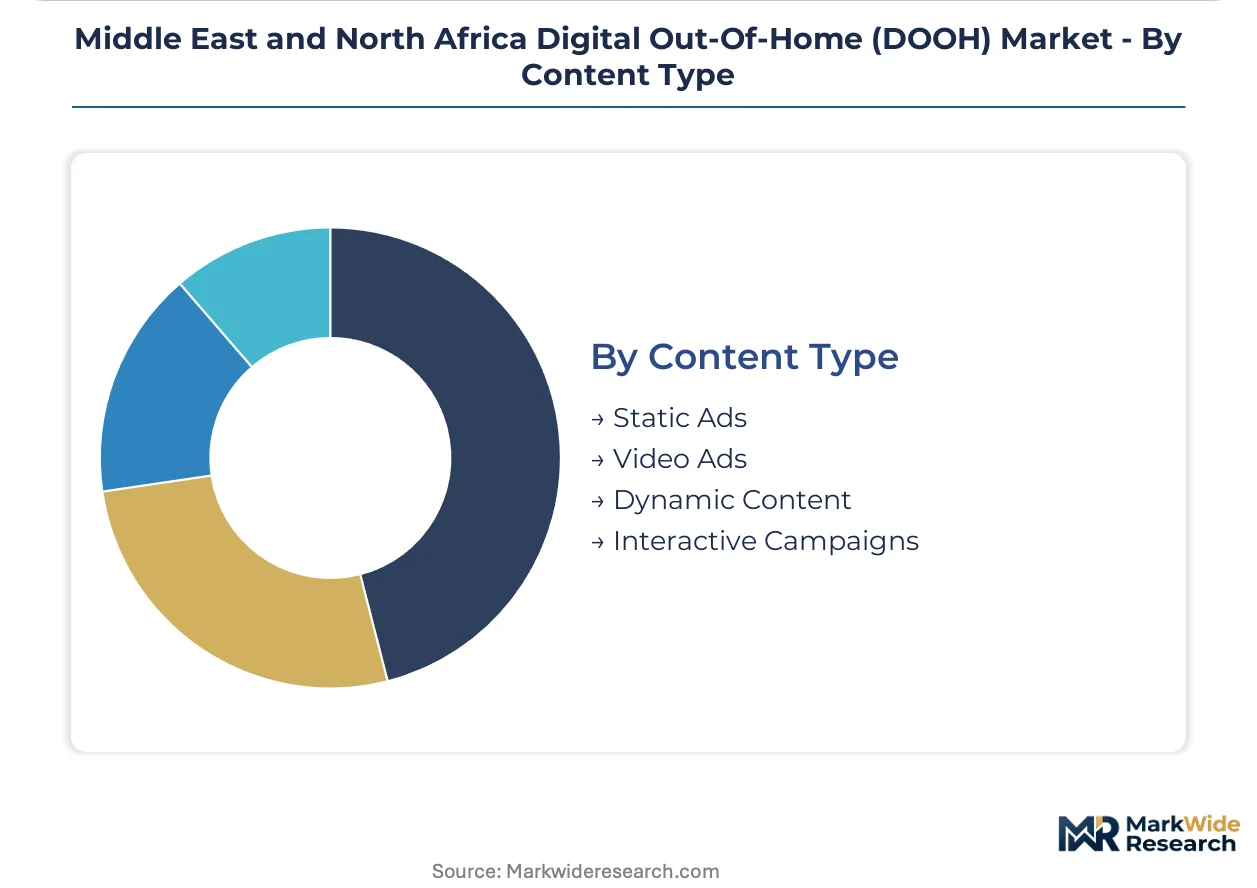
Content Type:
Production cost and data integration depth separate static from dynamic and interactive formats. Weather-triggered automation is capturing incremental budget from weather-sensitive categories.
- Static Ads:JPEG-based creative with lowest production cost and fastest approval turnaround. Residual preference in North African markets outside Gulf urban cores slows digital conversion timelines.
- Video Ads:15-30 second motion creative commands 40-60% CPM premiums over static in transit and retail environments. Higher production cost and longer approval cycles constrain deployment velocity.
- Dynamic Content:Real-time data feeds including weather, traffic, and sports scores automate creative rotation. Meteorological API integration captures incremental spend from beverage and apparel advertisers responding to temperature and air quality conditions.
- Interactive Campaigns:Gesture, touch, and mobile-responsive activations extend dwell metrics that programmatic platforms reward. Creative technologist scarcity concentrated in Dubai and Riyadh limits campaign execution capacity in secondary MENA cities.
Video ads dominate current media spend allocation. Dynamic content is expanding most quickly as advertisers automate contextual relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Cooperation Council states deploy DOOH as mandatory smart city infrastructure, while North African markets retain residual static print preference that slows digital conversion timelines. This consumption-mix differential creates divergent investment horizons across the MENA corridor.
United Arab Emirates
Dubai RTA mandates DOOH integration across metro and bus networks as digital communication layers, creating captive audience environments for advertisers. UAE Telecommunications and Digital Government Regulatory Authority data localization rules legitimize privacy-compliant targeting for premium CPM rates. Sheikh Zayed Road and Dubai Mall corridors anchor the region's highest-rate inventory as luxury automotive and beauty brands pilot transparent LED substrates.
Saudi Arabia
Riyadh Metro infrastructure embeds DOOH networks as compulsory passenger communication systems, generating predictable concession revenue streams. Saudi Communications, Space and Technology Commission electromagnetic emissions certification adds deployment delays but erects compliance barriers against low-cost imports. King Fahd Road and Riyadh Boulevard districts concentrate programmatic-enabled inventory trading.
Qatar
Doha Corniche pedestrian zones and Hamad International Airport sustain transit and street furniture concession networks with high-dwell audience capture. Municipal ownership of right-of-way forces revenue-sharing structures that dilute operator margins versus wholly-owned estates. Premium mall networks leverage existing IT infrastructure partnerships to absorb edge computing deployment costs mandated by data privacy frameworks.
Egypt
Cairo and Alexandria urban cores exhibit static print residual preference among heritage outdoor advertisers, compressing digital conversion velocity. National Telecommunications Regulatory Authority spectrum licensing auctions for 5G-adjacent bands raise recurring operational expenditures for networked signage connectivity. Nile-side retail districts remain underpenetrated by programmatic-enabled networks relative to Gulf urban cores.
Morocco
Casablanca retail districts offer first-mover positioning for mall and transit concession operators as programmatic infrastructure arrives. General functional descriptors for national telecommunications governance apply as spectrum allocation frameworks evolve. Urban corridors between Casablanca and Rabat concentrate underexploited roadside and retail inventory relative to saturated Gulf markets.
Middle East and North Africa Digital Out-Of-Home (DOOH) Market Competitive Landscape
Capability concentration sits with premium estate operators controlling Sheikh Zayed Road and Riyadh Boulevard corridors; scale advantage sits with transit concession holders anchoring metro and airport networks. The market structures around three archetypes: premium roadside estate owners, transit infrastructure concessionaires, and retail mall network specialists. Competitive moves concentrate on concession renewal positioning for smart city mandates and edge computing deployment for privacy-compliant audience measurement.
Within the premium estate tier, BackLite Media LLC and JCDecaux SE exemplify divergent geographic anchoring strategies across Dubai-Abu Dhabi and Riyadh-Doha corridors respectively. Hypermedia FZ LLC occupies a position within the retail mall specialist archetype, representing high-dwell environment concentration across UAE shopping destinations. These three entities collectively illustrate how physical access to audiences, concession politics, and IT infrastructure partnerships determine competitive positioning in privacy-regulated DOOH markets.
| Leading Market Players |
|---|
| JCDecaux SE |
| ELAN Media W.L.L. |
| BackLite Media LLC |
| Hypermedia FZ LLC |
| Abu Dhabi Media Company PJSC |
| Hills Advertising L.L.C. |
| Elevision |
| Dooha Media |
| Mubashir |
| Others |
Supply & Pricing Matrix
East Asian LED module foundries in Taiwan and South Korea concentrate upstream manufacturing capacity, anchoring margin capture downstream with premium roadside estate operators on Sheikh Zayed Road and King Fahd Road corridors. This geographic concentration of semiconductor and rare earth processing feeds directly into hardware cost structures that shape bidding dynamics for municipal transit concessions across Gulf urban cores.
Pricing Analysis
Long-term concession agreements spanning 5-10 years dominate pricing structures across Gulf DOOH markets, displacing spot-market transactions prevalent in North African jurisdictions. Rate differentiation hinges on electromagnetic emissions certification tier from Saudi CSTC or UAE TDRA, plus daylight visibility specifications at 500-5,000 nits brightness. Cost compression in hardware procurement intensifies pricing pressure as copper and semiconductor input volatility feeds through module costs. Transit authorities exhibit lowest price sensitivity given mandatory digital communication mandates, while heritage print advertisers in Egypt and Morocco retain highest sensitivity to CPM premiums.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Taiwanese and South Korean LED panel producers, supplemented by Chinese substrate fabricators serving transparent and flexible format pilots. Rare earth phosphors, driver ICs, and aluminum heat-dissipation components draw from East Asian supply tiers. Single-source vulnerability in semiconductor foundry capacity presents structural risk given 8-14 week Gulf regulatory certification delays. Distribution runs through Dubai and Jeddah logistics hubs serving GCC corridor deployments, with secondary routing to Casablanca and Algiers as North African programmatic infrastructure matures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge computing deployment expertise for privacy-compliant audience measurement remains concentrated in Dubai and Riyadh, constraining network scalability into secondary MENA cities and elevating acquisition premiums for operators with proven IT infrastructure partnerships.
For Market Incumbents: Entrench concession positioning by securing renewal options on Riyadh Metro and Dubai RTA transit networks before competitive bidding windows open. Acquire in-house edge computing deployment capabilities to satisfy Saudi CSTC and UAE TDRA data localization mandates without third-party dependency. Threat of programmatic-enabled new entrants with pure-play retail mall focus demands preemptive mall network consolidation in Abu Dhabi and Doha. For New Entrants and Emerging Players: Pursue underexploited Casablanca and Algiers retail corridors where programmatic infrastructure remains nascent and concession politics less entrenched than Gulf urban cores. Target gesture-responsive interactive screen deployments in high-dwell mall atriums, leveraging computer vision and Bluetooth beacon convergence that incumbent roadside operators lack technical capacity to replicate. Go-to-market angle should emphasize flight-based audience guarantees with impression-level verification through mobile proximity signals. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across interactive screen sub-segments as edge computing hardware raises per-installation deployment costs. Long-term viability across the 5-10 year horizon favors operators with diversified deployment format exposure spanning billboards, transit, and retail rather than single-format specialists. Acquisition target archetype: mid-scale mall network operators in Morocco and Algeria with existing IT infrastructure partnerships. Signal to watch is spectrum licensing auction outcomes from Egypt's NTRA and Maghreb equivalents that would escalate recurring connectivity expenditures.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Deployment | Satisfies UAE TDRA and Saudi CSTC data localization mandates while creating compliance moats. |
| Transit Concession Renewal | Secures captive audience environments as Dubai RTA and Riyadh Metro mandate DOOH integration. |
| Interactive Screen Pilot Programs | Captures 3-4x CPM premiums in Dubai Mall and Riyadh Boulevard luxury brand campaigns. |
| North African Geographic Expansion | Exploits underpenetrated Casablanca and Algiers corridors before incumbent Gulf operators arrive. |
| Programmatic Platform Integration | Enables impression-verified trading that now commands 40-60% of Dubai and Jeddah agency RFP volume. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of municipal transit authority procurement disclosures, electromagnetic emissions certification registries, and spectrum licensing auction records. Primary interviews engaged network operations directors, media agency trading desk leads, mall asset management executives, and regulatory compliance officers across UAE, Saudi Arabia, Qatar, Egypt, Morocco, and Algeria. Secondary validation drew from Saudi CSTC and UAE TDRA technical standards filings, Dubai RTA and Riyadh Metro concession documentation, and customs trade data on LED module imports. Bottom-up installation base enumeration triangulates against top-down media spend allocation estimates.
Forecast inputs incorporate deployment format replacement cycles, technology refresh cadences, and concession renewal timelines across the projection horizon. Segmentation dimensions modeled include deployment category, technology tier, customer procurement pattern, and content type complexity. CAGRs derive from hardware shipment trajectories, media budget reallocation patterns, and regulatory compliance cost absorption curves. Industry-specific inputs encompass electromagnetic emissions certification delay distributions and spectrum licensing fee escalation pathways.
Macroeconomic conditions sit as an overlay; deviation in Gulf construction activity, tourism recovery velocity, or North African currency stability would shift the trajectory. Forecasts reflect documented assumptions on smart city infrastructure commitment durability and data privacy framework enforcement intensity. Quarterly review of transit authority capital expenditure disclosures and spectrum auction calendars is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Philippines OOH and DOOH Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Europe Public Relation Services Market
Advertising and Marketing Media
Chile OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Vietnam OOH and DOOH Market
Advertising and Marketing Media
Europe Digital OOH Advertising Market
Advertising and Marketing Media
Native Video Advertising Market
Advertising and Marketing Media
Global Programmatic Advertisement Market