
 Brand Licensing Market | 2026-2036
Brand Licensing Market Size, Share, and Industry Trends Forecast 2026-2036
Brand Licensing Market Insights
North America is fragmenting as production capacity for licensed consumer goods disperses across Mexico, Canada, and domestic U.S. manufacturing zones. Warner Bros. Discovery leverages its deep content vault to sustain cross-category licensing across film, television, and gaming properties. The Pokémon Company International anchors its dominance in character-driven merchandise through tight control over regional distribution partnerships. Mattel competes aggressively in toy licensing by extending its Barbie and Hot Wheels portfolios into experiential retail formats.
Brand licensing constitutes the contractual authorization by an intellectual property owner to permit third-party use of trademarks, characters, logos, or designs on products, packaging, or services in exchange for royalty payments, typically structured as percentage fees on net sales or guaranteed minimums. The practice enables IP holders to monetize intangible assets without direct manufacturing investment while allowing licensees to differentiate offerings through established consumer recognition. Apparel and toys represent the most mature product type segments with entrenched supply chains, though accessories and home décor exhibit faster expansion as lifestyle branding penetrates adult demographics. Entertainment properties within the market segment command the largest royalty pools, while sports licensing generates higher per-deal consistency through longer contract durations.
FDA guidelines on product safety labeling affect toy and children's apparel licensees sourcing from U.S. distribution channels, while FTC endorsement disclosure rules govern influencer marketing collaborations tied to licensed properties. ESG reporting frameworks, including CSRD in Europe and SEC climate disclosure requirements in the United States, increasingly influence licensee selection criteria as sustainability credentials factor into brand alignment decisions. Stakeholders must monitor evolving digital asset licensing protocols for NFTs and virtual goods as new revenue channels emerge beyond physical merchandise.
Market Dynamics
Digital authentication technologies are compressing royalty verification cycles while fragmenting production geography across North American manufacturing zones. IP holders now demand real-time sales transparency, forcing licensees to retrofit legacy reporting infrastructure with blockchain-enabled tracking systems.
Growth Catalysts
- Streaming Content Proliferation:Entertainment properties from Netflix, Disney+, and Amazon Prime Video generate continuous character exposure that sustains merchandise demand across apparel and toy categories without traditional theatrical release windows.
- CSRD Alignment Requirements:European ESG reporting frameworks now mandate supply chain disclosure, pushing licensees to document carbon footprints and social compliance credentials as selection criteria tighten.
- NFT Protocol Standardization:Digital asset licensing for virtual goods creates new revenue streams beyond physical merchandise, with smart contracts automating royalty splits across secondary markets.
Market Restraints
- Input Cost Volatility:Cotton and synthetic textile prices fluctuate with energy markets, squeezing margin structures for apparel licensees operating on fixed royalty percentage terms.
- Supply Concentration Risk:Toy manufacturing clusters in Guangdong Province create single-point vulnerability for North American licensees facing shipping rate spikes and customs processing delays.
- Regulatory Friction:FDA product safety labeling requirements for children's goods impose testing costs and timeline extensions that deter smaller licensees from entering the category.
Strategic Opportunities
- Experiential Retail Formats:Immersive brand activations and pop-up installations enable premium pricing for licensed merchandise through destination shopping experiences in urban centers.
- India's PLI Scheme:Production-linked incentives for textiles and toys attract licensing partners seeking alternative manufacturing bases with favorable tariff access to Middle Eastern and African markets.
- AI-Generated Content Convergence:Machine learning tools for rapid design iteration merge with virtual try-on technologies, accelerating product development cycles for fashion licensees.
Industry Challenges
- Royalty Auditing Expertise Gap:Licensees lack personnel trained in forensic sales verification, creating disputes over reported net sales and deductible allowances.
- Legacy System Integration:ERP platforms at established manufacturers resist API connectivity with IP holder dashboards, delaying real-time data sharing mandated in new contracts.
- Cross-Border IP Enforcement:Trademark infringement in gray market channels requires legal resources across multiple jurisdictions, straining compliance budgets for mid-sized licensees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brand Licensing Market |
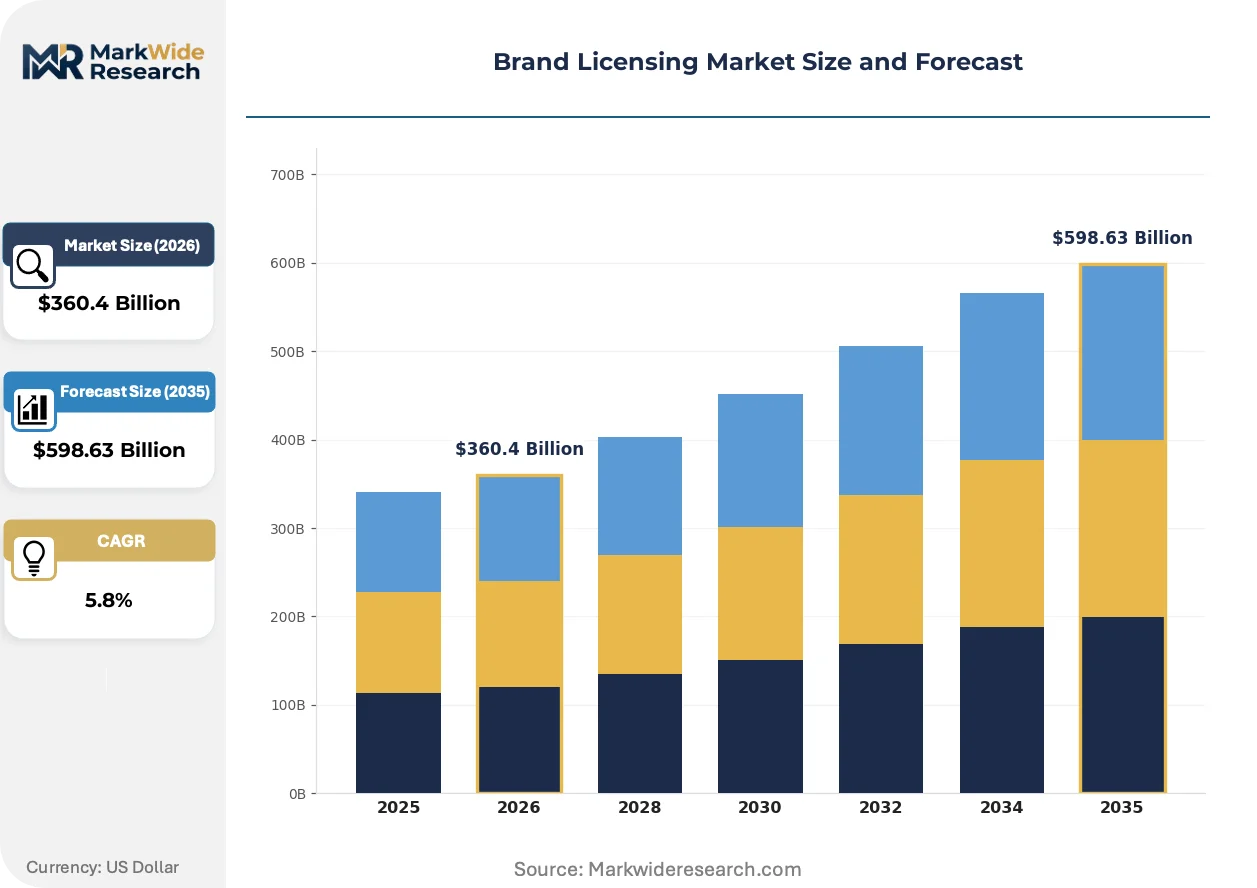
| Market Size in 2026 | $360.4 Billion |
| Market Size in 2035 | $598.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Accessories, Home Décor, Toys Licensee Type: Manufacturers, Retailers, Distributors, Online Platforms End User: Children, Teenagers, Adults, Seniors Market Segment: Entertainment, Sports, Fashion, Consumer Goods |
| Companies Covered | Warner Bros. Discovery, The Pokémon Company International, The Walt Disney Company, Sanrio, Mattel, Authentic Brands Group, Hasbro, Dotdash Meredith, NBCUniversal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brand Licensing Market Trends and Innovations
Authentication infrastructure is migrating from periodic audits to continuous verification, compressing the trust gap between IP holders and manufacturing partners. Three concurrent shifts are restructuring how value flows through licensing agreements.
Blockchain-based royalty tracking is migrating from pilot implementations to contractual standard. Mid-sized apparel licensees in the United States and Germany now embed smart contract logic into manufacturing agreements, enabling automatic payment triggers upon retail scan data. This compression of reconciliation cycles reduces working capital requirements for licensors while eliminating quarterly audit disputes.
CSRD disclosure mandates in Europe now require Scope 3 emissions documentation from licensing partners. Textile and toy manufacturers serving EU distribution channels must submit verified supply chain data or face exclusion from retail placement. French and German mass-market retailers have established sustainability scorecards that determine shelf space allocation for licensed properties.
Collector behavior is fragmenting across physical and digital ownership models. Adult demographics in Japan and South Korea now acquire virtual merchandise alongside tangible goods, with authentication serving as the unifying purchase trigger. This dual-channel consumption pattern forces licensees to coordinate release calendars across NFT drops and retail distribution, complicating inventory planning for properties with finite hype cycles.
Brand Licensing Market Segmentation
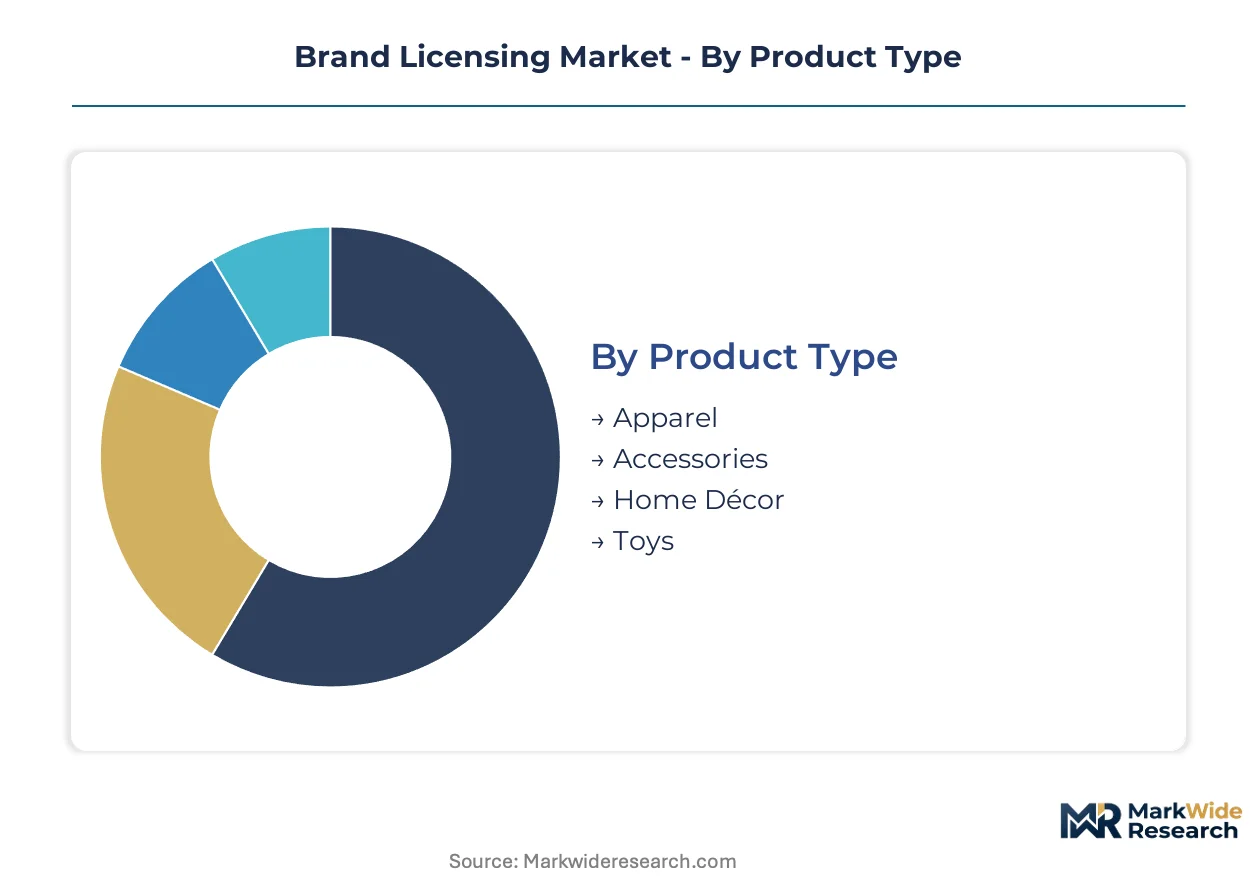
Segmentation in brand licensing determines royalty structures, contract duration, and territorial exclusivity. Product type dictates manufacturing complexity and margin profiles, while end-user demographics shape marketing spend and channel selection. Licensee capabilities directly influence speed-to-market and geographic reach.
Product Type:
After-sales service intensity varies sharply across physical goods categories, with durable home décor requiring minimal support while toys face safety recall protocols and apparel handles size exchanges.
- Apparel:Cotton-blend and synthetic textiles dominate licensed clothing production. Demand concentrates in the United States and China where character-driven fast fashion cycles compress design-to-shelf timelines to under eight weeks.
- Toys:Plastic injection molding and electronic components define manufacturing specifications. Guangdong Province clusters supply North American retailers facing FDA labeling mandates and seasonal inventory compression.
- Accessories:Licensed bags, jewelry, and small leather goods carry lower minimum order quantities than apparel, attracting mid-tier fashion houses seeking brand elevation.
- Home Décor:Bedding, furniture, and decorative items extend IP lifecycles through adult lifestyle positioning with reduced trend volatility.
Apparel holds the largest share; momentum sits with home décor as adult demographics expand licensed property engagement.
Licensee Type:
Cost tier stratification separates capital-intensive manufacturers from asset-light online platforms, with retailers occupying the middle ground through private label licensing programs.
- Manufacturers:Direct production control enables quality consistency for toy and apparel licensors. Shenzhen and Dongguan facilities serve multinational entertainment IP holders requiring CSRD-aligned supply chain documentation.
- Online Platforms:Marketplace operators leverage algorithmic personalization to match licensed merchandise with niche fandom segments, bypassing traditional retail gatekeepers.
- Retailers:Big-box chains negotiate exclusive distribution windows for blockbuster entertainment properties, capturing margin through controlled scarcity.
- Distributors:Regional wholesalers bridge language and regulatory gaps for European and Middle Eastern market entry, absorbing customs complexity.
Manufacturers retain volume leadership; online platforms are climbing the fastest as direct-to-consumer channels disintermediate legacy distribution.
End User:
Application context shifts dramatically across age brackets, with children's purchases parent-mediated and adult acquisitions increasingly self-directed through mobile discovery.
- Children:Safety certification and educational claims dominate purchase criteria. Japanese and South Korean parents prioritize character authenticity over price sensitivity.
- Adults:Nostalgia-driven collecting and lifestyle integration sustain premium pricing for vintage entertainment properties and designer collaborations.
- Teenagers:Social media virality determines demand spikes, with TikTok and Instagram driving rapid obsolescence for licensed fashion items.
- Seniors:Comfort-focused home textiles and heritage brand affiliations generate stable repeat purchase patterns with minimal marketing overhead.
Children's segment anchors revenue consistency; adults generate the steepest expansion trajectory through collectible and experiential merchandise.
Market Segment:
Margin profiles diverge substantially, with sports licensing offering contract stability through multi-year league agreements while entertainment properties capture higher peaks tied to release windows.
- Entertainment:Film, television, and streaming content IP command the largest royalty pools. Netflix and Disney+ original series now sustain merchandise demand outside traditional theatrical cycles.
- Sports:League and athlete licensing generates predictable recurring revenue through apparel and equipment categories with established retail placement.
- Fashion:Designer brand collaborations and luxury house extensions attract premium positioning in accessories and fragrance categories.
- Consumer Goods:Food, beverage, and household product licensing leverages trust transfer for market entry, particularly in emerging economies.
Entertainment dominates absolute value; fashion licensing is gaining share fastest through adult demographic penetration and luxury crossover strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies: Japanese collectors prioritize character authenticity and limited editions, while Chinese buyers favor streaming-tied merchandise with rapid release cycles, and U.S. consumers spread demand across experiential retail and digital collectibles.
United States
Entertainment IP from streaming platforms drives apparel and toy licensing through year-round content drops rather than theatrical windows. FTC endorsement disclosure rules govern influencer marketing collaborations tied to licensed properties. Los Angeles and New York anchor content-to-commerce pipelines where Warner Bros. Discovery and NBCUniversal coordinate cross-category licensing programs.
China
Domestic streaming platforms generate character exposure that sustains merchandise demand without traditional broadcast cycles. SAMR oversees trademark enforcement and product safety labeling for children's goods. Guangdong Province clusters toy manufacturing facilities serving both domestic distribution and export markets, though dual carbon goals pressure energy-intensive production.
Japan
Adult collectors sustain premium pricing for vintage entertainment properties and designer collaborations through lifestyle integration. METI promotes content export strategies that extend IP lifecycles into regional Asian markets. Tokyo and Osaka host dense retail networks where Sanrio and The Pokémon Company International coordinate character-driven merchandise with tight distribution control.
Germany
CSRD disclosure mandates require Scope 3 emissions documentation from textile and toy manufacturers serving EU distribution channels. ECHA oversees chemical safety standards affecting licensed children's apparel. Bavaria and North Rhine-Westphalia host sustainability-focused retailers that allocate shelf space based on verified supply chain credentials.
India
Production-linked incentives for textiles and toys attract licensing partners seeking alternative manufacturing bases with favorable tariff access to Middle Eastern and African markets. BIS certification requirements govern product safety for children's goods. Gujarat and Tamil Nadu develop specialized licensing manufacturing zones with integrated design-to-delivery capabilities.
Brand Licensing Market Competitive Landscape
Capability concentration sits with entertainment IP holders possessing deep content vaults; scale advantage sits with diversified manufacturers operating across multiple product categories. The market structures around three tiers: vertically integrated content studios, specialized character management firms, and multi-brand portfolio aggregators. Dominant competitive moves include portfolio diversification into experiential retail formats and strategic partnerships with streaming platforms for continuous character exposure.
Within the content studio tier, Warner Bros. Discovery and The Walt Disney Company exemplify vault-driven licensing strategies spanning film, television, and gaming properties. The Pokémon Company International occupies a specialized position in character-driven merchandise through controlled regional distribution. Mattel and Hasbro represent the diversified manufacturer archetype, extending toy portfolios into adjacent categories.
| Leading Market Players |
|---|
| Warner Bros. Discovery |
| The Pokémon Company International |
| The Walt Disney Company |
| Sanrio |
| Mattel |
| Authentic Brands Group |
| Hasbro |
| Dotdash Meredith |
| NBCUniversal |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific container freight corridors connecting Guangdong Province to Los Angeles and Long Beach anchor cost dynamics across licensed merchandise categories. Concentration of toy manufacturing in Shenzhen and Dongguan feeds pricing power to IP holders negotiating royalty terms, while apparel licensees face margin compression from volatile cotton futures and synthetic fiber energy-linkage.
Pricing Analysis
Long-term offtake agreements dominate entertainment property licensing, with guaranteed minimums securing IP holder revenue against retail volatility. Royalty structures stratify across premium character tiers, standard franchise extensions, and economy promotional lines, with price differentiation driven by exclusivity windows and retail channel tier. Pricing pressure stems from fixed-percentage royalty terms colliding with input cost spikes in textiles and plastics. Mass-market retailers exhibit highest price sensitivity, while collector-focused specialty channels absorb premium positioning.
Supply Chain Analysis
Supply-chain finance facilities extended by major retailers now fund working capital for Guangdong-based manufacturers serving North American distribution. Production concentrates in China, Vietnam, and Bangladesh for apparel, with toy molding anchored in Guangdong and alternative sourcing emerging in India under PLI incentives. Raw material dependencies span petroleum-derived plastics, cotton, and electronic components for interactive merchandise. Single-source vulnerability in Guangdong toy clusters creates disruption risk from customs processing delays. Distribution runs through big-box retail consolidation, direct-to-consumer platform expansion, and specialty collector channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as mass-market retailers consolidate shelf-space allocation authority, fragmenting manufacturer leverage across fragmented licensee bases.
For Market Incumbents: Pre-empt platform disintermediation by securing exclusive streaming-tied release windows before Amazon and Netflix verticalize merchandise operations. Invest in blockchain-enabled royalty tracking to defend margin position against audit disputes. Build backward integration into sustainable textile sourcing to meet CSRD documentation requirements from EU retailers. For New Entrants and Emerging Players: Build out experiential retail formats in secondary US metros where destination shopping gaps persist. Target India's manufacturing zones under PLI schemes for textiles and toys, leveraging tariff access to Middle Eastern markets. Pursue digital-first go-to-market angles through NFT-authenticated virtual merchandise alongside physical drops. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors character management firms with controlled distribution networks over pure content studios facing platform dependency. Long-term viability rests on IP lifecycle extension capabilities and regional exclusivity enforcement. Acquisition targets should demonstrate authenticated supply chain documentation and streaming platform partnership pipelines. Monitor CSRD compliance readiness as the inflection indicator for EU market access.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Royalty Integration | Smart contract automation reduces Warner Bros. Discovery audit cycles and working capital drag. |
| Experiential Retail Expansion | Mattel's immersive activations capture premium pricing through destination shopping in urban centers. |
| CSRD Supply Chain Documentation | Verified emissions data secures shelf placement with French and German sustainability-focused retailers. |
| India PLI Manufacturing Relocation | Gujarat and Tamil Nadu zones offer tariff-advantaged export positioning for Middle Eastern markets. |
| NFT Protocol Standardization | Digital asset licensing creates secondary market revenue streams beyond physical merchandise cycles. |
Research Methodology
Operator-level perspectives from licensing directors at entertainment studios, apparel procurement leads at mass-market retailers, toy manufacturing plant managers in Guangdong, and sustainability compliance officers at EU distributors anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, customs trade records, CSRD disclosure databases, and streaming platform content release schedules. Bottom-up licensee revenue modeling and top-down IP holder royalty pool estimates provided triangulation checks across the analysis window.
Scenario-bracketing framed the analytical approach, with baseline, accelerated streaming adoption, and supply chain disruption cases tested across the projection horizon. Segmentation dimensions modeled include product type, licensee category, end-user demographic, and market segment, with regional regulatory clusters treated as distinct adoption environments. CAGRs derived from historical royalty growth patterns, content release density correlations, and manufacturing capacity expansion trajectories. Forecast inputs incorporated streaming platform subscriber growth and ESG disclosure mandate enforcement timelines.
Practitioners should monitor streaming content release calendars, CSRD audit enforcement intensity, and India PLI scheme uptake rates for early signals of trajectory deviation. Forecasts reflect documented assumptions about content consumption patterns and manufacturing relocation economics. Macroeconomic recession compressing discretionary merchandise spend, regulatory acceleration of digital asset taxation, or breakthrough AI design tools displacing traditional licensing workflows would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Programmatic Display Advertising Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
Teleshopping Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
South East Asia Advertising Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Global Advertising Agency Software Market
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
Europe Programmatic Advertising Market
Advertising and Marketing Media
Big Data Pharmaceutical Advertising Market