
 Middle East and Africa Sports Betting Market | 2026-2036
Middle East and Africa Sports Betting Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Sports Betting Market Foresight
CE marking for remote gambling software is reorganizing which operators can legally serve consumers across the Middle East and Africa region. Betway leverages its established brand strength to sustain premium positioning in multiple regulated jurisdictions. 1xBet competes through aggressive geographic expansion and localized payment integration. Betsson AB anchors its regional presence through disciplined licensing compliance and technology leadership in platform stability.
Sports betting encompasses the contractual wagering of monetary stakes on athletic event outcomes through probabilistic pricing mechanisms, where bookmakers set odds reflecting implied event probabilities and retain margin through overround structures. The activity serves commercial entertainment consumption and generates taxable revenue streams for host governments. Mobile platforms now capture the fastest expansion as smartphone penetration deepens across sub-Saharan Africa, while retail over-the-counter channels retain dominance in markets with limited digital banking infrastructure. Fixed odds betting occupies the mature revenue core, though in-play wagering demonstrates the steepest growth trajectory as latency improvements enable real-time price updates during live events.
South Africa's National Gambling Board, Nigeria's National Lottery Regulatory Commission, and Kenya's Betting Control and Licensing Board collectively determine market access through divergent licensing frameworks and taxation regimes. These regulators shape product standards through advertising restrictions, responsible gambling mandates, and Know Your Customer requirements that increase operational complexity for cross-border operators. Stakeholders must monitor licensing reciprocity developments and payment system interoperability as the primary variables determining which platforms can scale beyond single-country footprints.
Market Dynamics
Mobile-first wagering platforms are compressing traditional retail betting channels across sub-Saharan Africa, as smartphone penetration and mobile money interoperability rewrite how casual bettors access probabilistic pricing markets. This structural shift concentrates competitive advantage among operators with localized payment rail integration.
Growth Catalysts
- Mobile money interoperability:Kenya's M-Pesa and Nigeria's banking agent networks reduce friction for unbanked populations entering wagering markets. Transaction settlement speeds now match developed-market standards.
- South Africa's National Gambling Board licensing reciprocity:Cross-border operator recognition agreements expand addressable markets for compliant platforms without duplicate regulatory overhead.
- Youth demographic bulge:Nigeria's median age of 18 concentrates demand among digital-native consumers predisposed to in-play betting formats.
Market Restraints
- Compliance cost escalation:South Africa's National Gambling Board mandates for enhanced Know Your Customer verification and responsible gambling infrastructure raise operational barriers for new market entrants.
- Payment rail fragmentation:Divergent mobile money protocols across Kenya, Nigeria, and Ghana force operators to maintain redundant technical integrations.
- Currency volatility exposure:Nigerian naira and Kenyan shilling fluctuations compress margin predictability for dollar-denominated platform providers.
Strategic Opportunities
- Ethiopia's unpenetrated market:Africa's second-most populous nation lacks formal sports betting regulation, creating first-mover positioning for licensed operators ahead of anticipated framework introduction.
- Esports wagering convergence:Mobile gaming adoption among African youth demographics enables platform extension into competitive video game betting categories.
- CE marking harmonization:Standardized remote gambling software certification across Middle East and Africa jurisdictions reduces per-market compliance engineering costs.
Industry Challenges
- Responsible gambling engineering talent scarcity:Platform operators struggle to recruit data scientists capable of building real-time behavioral intervention systems for at-risk user identification.
- Legacy retail integration complexity:Operators with established physical agent networks face technical debt in migrating offline customer bases to unified digital wallets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Sports Betting Market |
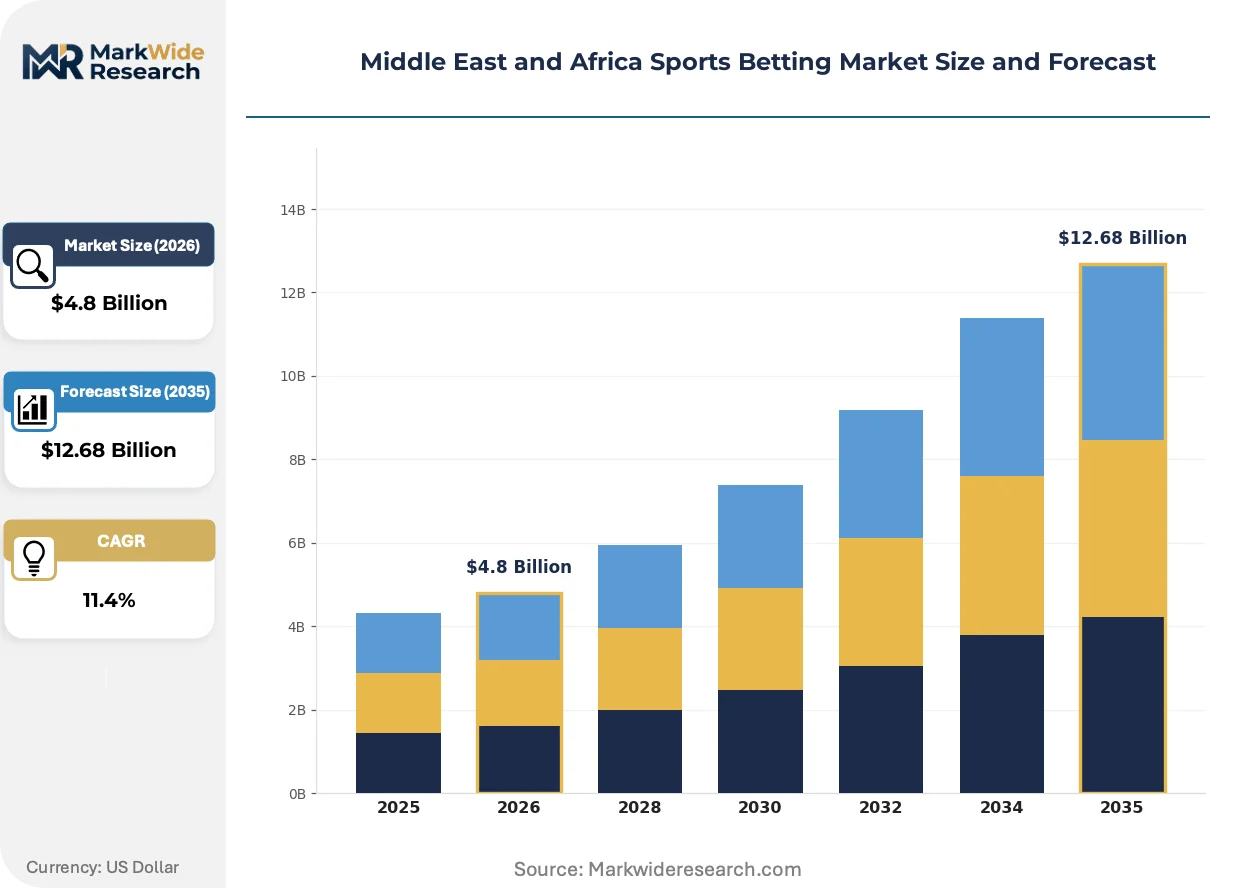
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Betting Platform: Online, Mobile, Retail, Over-the-Counter Customer Type: Aficionados, Casual, Professional, Newcomers Betting Type: Fixed Odds, In-Play, Parimutuel, E-sports Sport Type: Football, Basketball, Tennis, Horse Racing |
| Companies Covered | Betway, 22Bet, Betika, 1xBet, MozzartBet, Bet365, Betsson AB, 888 Holdings, Kindred Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Sports Betting Market Shifts & Advancements
Real-time data infrastructure and regulatory technology investments are restructuring competitive differentiation in Middle East and Africa sports betting. Operators now compete on latency reduction and compliance automation rather than odds margin alone.
Edge computing deployment for odds calculation is bifurcating platform architecture strategies across the region. Tier-one operators deploy localized server nodes in Lagos, Nairobi, and Johannesburg to achieve sub-100 millisecond price updates during live events. This infrastructure investment is compressing competitive viability for cloud-dependent smaller platforms unable to match latency performance.
Kenya's Betting Control and Licensing Board advertising restrictions are forcing product-led growth strategies over broadcast media dependence. Operators now redirect marketing spend toward influencer partnerships and organic social content. The policy most acutely impacts mass-market brands previously reliant on sports sponsorship visibility.
Agent network disintermediation is accelerating as direct-to-consumer mobile registration displaces retail over-the-counter onboarding. Younger bettors in Nigeria and Kenya bypass physical betting shops entirely, collapsing the historical role of commission-based street agents. This pattern concentrates most intensely in urban corridors with dense 4G coverage and established mobile money agent penetration.
Middle East and Africa Sports Betting Market Segmentation
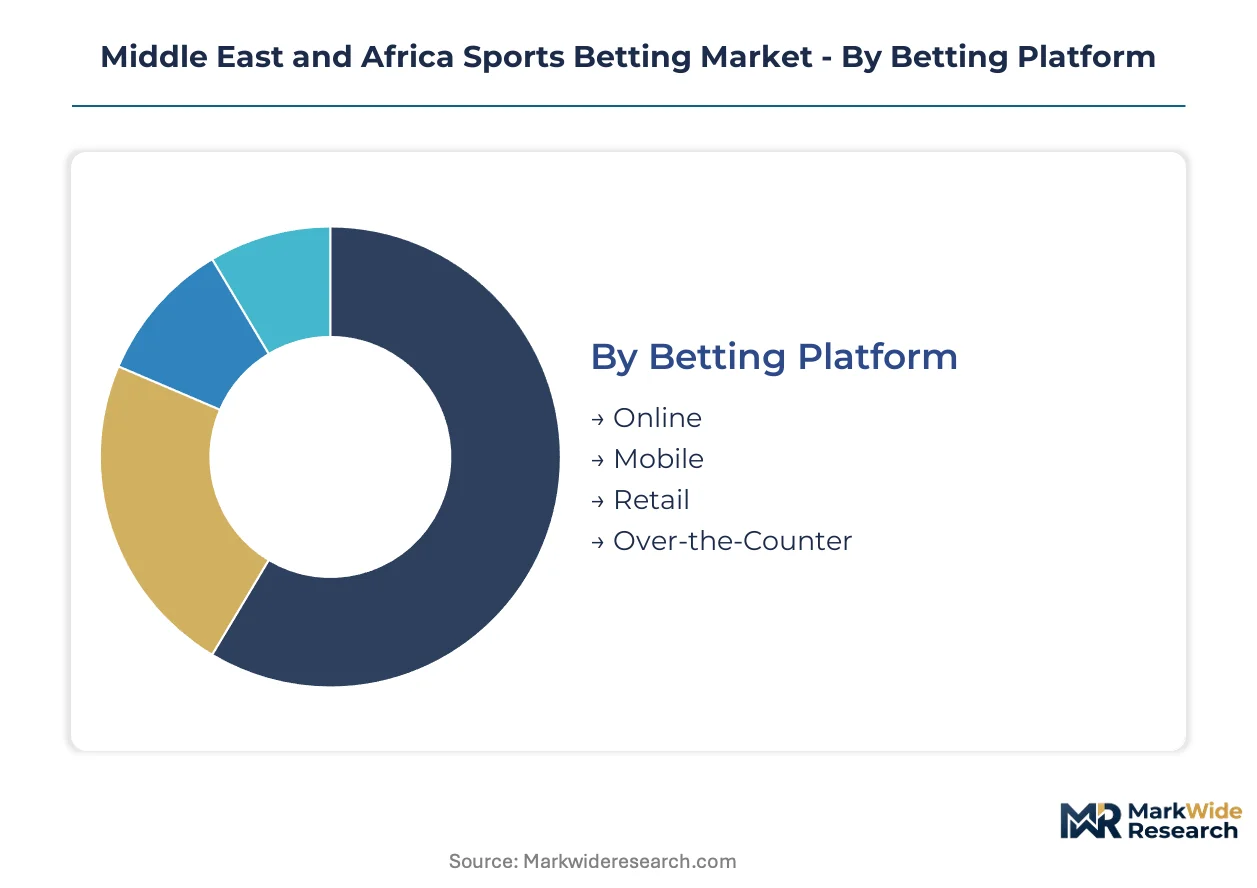
Sports betting market segmentation reveals how platform architecture, customer sophistication, and wagering mechanics reshape competitive strategy across Middle East and Africa. Operators must align product development with distinct behavioral clusters and regulatory constraints governing each channel.
Betting Platform:
Mobile platforms face the strongest substitution pressure as smartphone penetration renders retail channels increasingly obsolete among urban youth demographics.
- Online:Browser-based wagering interfaces deliver full-featured betting experiences through responsive web design. Demand concentrates among South African bettors with established banking relationships and fiber connectivity, though Kenya's Betting Control and Licensing Board advertising restrictions limit customer acquisition efficiency.
- Mobile:Native applications and mobile-optimized sites exploit M-Pesa interoperability and Nigeria's banking agent density. Nigeria's youth demographic bulge drives fastest adoption as median-age-18 populations bypass desktop entirely.
- Retail:Physical betting shops maintain relevance in peri-urban zones with erratic electricity and limited smartphone ownership.
- Over-the-Counter:Commission-based street agents serve cash-dependent populations in informal settlements across Lagos and Nairobi.
Mobile retains volume leadership; Online holds the steepest expansion curve.
Customer Type:
Cost-tier stratification separates high-frequency professional bettors from mass-market casual participants with divergent margin sensitivity.
- Aficionados:Deeply knowledgeable sports enthusiasts deploy sophisticated staking strategies across multiple leagues. South Africa's National Gambling Board responsible gambling mandates require enhanced monitoring for this high-activity segment.
- Casual:Event-driven participants wager intermittently on major tournaments and derby fixtures. Nigeria's improving payment rail density unlocks this largest addressable population.
- Professional:Systematic bettors treat wagering as primary income through arbitrage and value betting.
- Newcomers:First-time users require simplified onboarding and educational content to reduce churn.
Casual bettors dominate transaction volume; Newcomers exhibit the highest churn-adjusted acquisition cost.
Betting Type:
Margin structure varies dramatically across pricing mechanisms, with real-time wagering demanding infrastructure investments that smaller operators cannot replicate.
- Fixed Odds:Pre-event pricing with locked-in returns constitutes the mature revenue core. Kenya's retail-heavy legacy market sustains this format through established agent networks.
- In-Play:Live wagering with dynamic odds updates during matches commands premium engagement. Nigeria's 4G corridor density enables sub-100-millisecond latency that drives this segment's expansion.
- Parimutuel:Pool-based betting systems aggregate stakes for shared payouts, retaining niche presence in horse racing.
- E-sports:Competitive video game wagering targets digital-native demographics with distinct event calendars.
Fixed Odds maintains revenue primacy; In-Play climbs fastest on infrastructure investment.
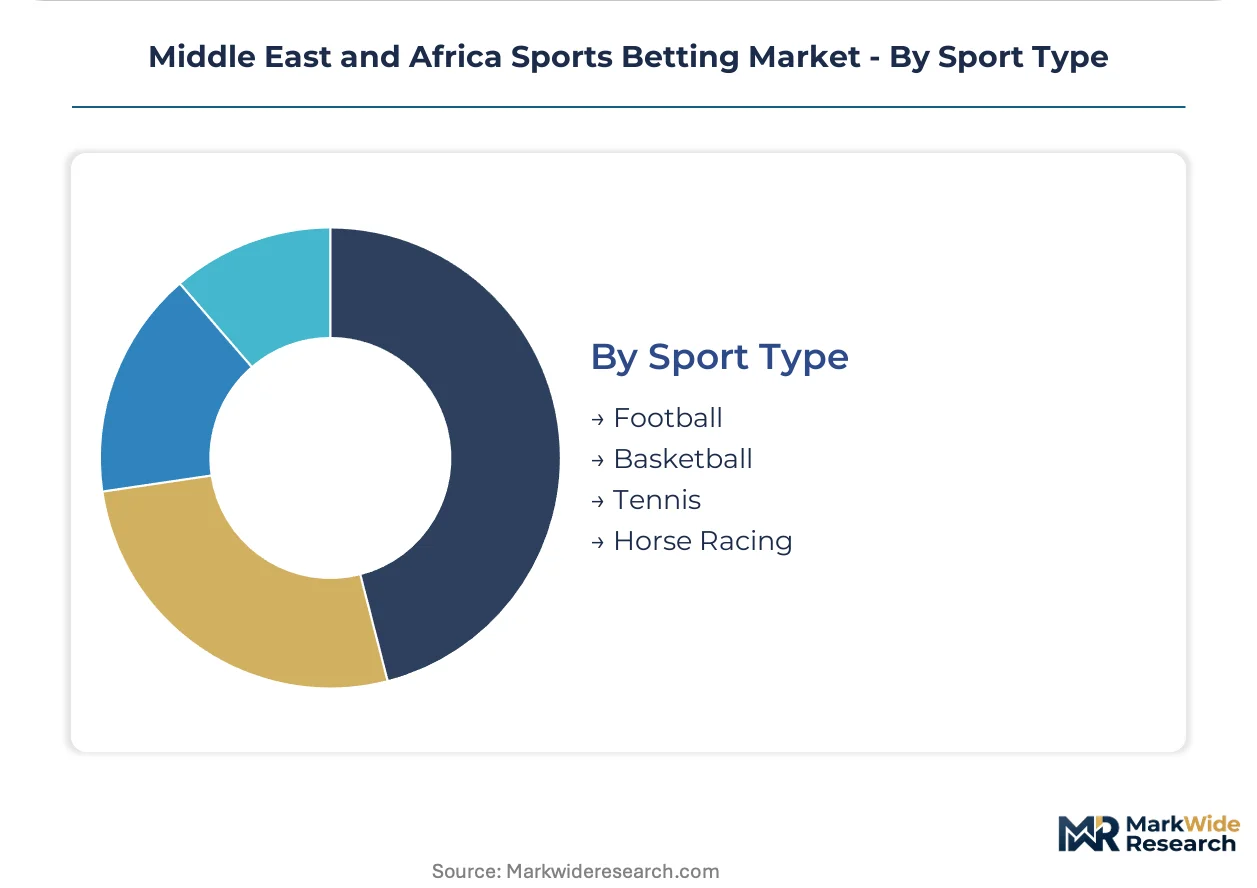
Sport Type:
Geographic preference clusters reflect colonial sporting heritage and contemporary media rights distribution across Middle East and Africa markets.
- Football:European league fixtures and African continental competitions generate overwhelming wager volume. Nigeria's Premier League broadcast access concentrates demand among male demographics aged 18-35.
- Basketball:NBA and domestic league wagering accelerates through mobile streaming integration. South Africa's National Gambling Board licensing reciprocity enables cross-border operator coverage of American league content.
- Tennis:Grand Slam calendars provide year-round betting liquidity through individual match formats.
- Horse Racing:Historic wagering category retains dedicated following in South Africa and select Middle East jurisdictions.
Football commands absolute volume dominance; Basketball gains share fastest on streaming platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's National Gambling Board licensing reciprocity agreements are reshaping cross-border operator access across the Middle East and Africa region. These policy frameworks enable compliant platforms to serve multiple jurisdictions without duplicate regulatory overhead. The analysis examines five national markets where regulatory divergence and infrastructure maturation create distinct competitive environments.
South Africa
Johannesburg and Cape Town host Africa's most mature wagering ecosystem with established retail networks and fiber-connected digital platforms. The National Gambling Board enforces stringent Know Your Customer mandates and responsible gambling infrastructure requirements that elevate operational costs for new entrants. Cape Town's technology corridor concentrates platform development talent for regional operators seeking compliance automation capabilities.
Nigeria
Lagos anchors the continent's largest addressable betting population through youth demographics and expanding mobile money agent density. The National Lottery Regulatory Commission governs licensing frameworks with taxation regimes that shape operator margin structures. Lagos-Ibadan corridor infrastructure investments enable sub-100-millisecond latency for live wagering platforms serving Nigeria's median-age-18 population.
Kenya
Nairobi's M-Pesa interoperability established the template for mobile-first wagering across unbanked populations throughout East Africa. The Betting Control and Licensing Board advertising restrictions force product-led growth strategies over broadcast media dependence. Nairobi's 4G corridor density enables real-time odds updates that drive in-play betting adoption among urban youth demographics.
Ghana
Accra's emerging regulatory framework attracts operators seeking West African expansion beyond Nigeria's saturated core. The country's Gaming Commission licensing protocols remain less burdensome than South African or Nigerian equivalents. Accra-Tema metropolitan infrastructure supports mobile platform deployment targeting Ghana's young professional demographic.
United Arab Emirates
Dubai's positioning as regional technology hub attracts platform providers serving Middle Eastern markets through compliant offshore structures. The UAE's federal framework permits limited wagering categories under strict regulatory oversight. Dubai Internet City clusters software development capabilities for operators seeking CE marking harmonization across Gulf Cooperation Council jurisdictions.
Middle East and Africa Sports Betting Market Competitive Landscape
Player mix skews toward multinational platform operators with established licensing compliance and localized payment integration. Market structure concentrates around tier-one operators with proprietary technology stacks and tier-two affiliates dependent on white-label infrastructure. Three archetypes dominate: pan-African mobile-first specialists, European incumbents leveraging brand recognition, and emerging local platforms with deep agent network penetration. Geographic expansion and payment rail localization represent the dominant competitive vectors as operators seek addressable market growth beyond single-country footprints.
Among European-anchored platform providers, Betway, Betsson AB, and 1xBet occupy positions exemplifying distinct strategic archetypes. Betway represents brand-premium positioning sustained through multi-jurisdiction licensing discipline. Betsson AB exemplifies technology-led platform stability investment with systematic compliance architecture. 1xBet anchors the aggressive geographic expansion archetype through localized payment integration across fragmented African markets. These three operators collectively illustrate how licensing reciprocity, payment rail density, and infrastructure latency shape competitive viability across Middle East and Africa wagering markets.
| Leading Market Players |
|---|
| Betway |
| 22Bet |
| Betika |
| 1xBet |
| MozzartBet |
| Bet365 |
| Betsson AB |
| 888 Holdings |
| Kindred Group |
| Others |
Supply & Pricing Matrix
Long-term licensing contracts with tier-one platform providers lock in both software access and margin visibility across Middle East and Africa wagering markets. These arrangements shield operators from currency volatility while binding them to compliance cost escalations under South Africa's National Gambling Board mandates.
Pricing Analysis
Certification level creates the primary spread between premium and economy platform tiers. Three-tier pricing structure across CE-marked, jurisdiction-specific, and unlicensed software levels stratifies operator cost bases. Pricing pressure stems from Kenya's Betting Control and Licensing Board advertising restrictions, which force marketing spend reallocation toward higher-cost influencer channels. Casual bettors in Nigeria exhibit highest price sensitivity to transaction fees, while South African aficionados tolerate premium odds margins for platform stability.
Supply Chain Analysis
Port congestion at Lagos Apapa and Mombasa container terminals elevates inbound logistics costs for server hardware and edge computing nodes. Supply concentrates in China, South Korea, and Germany for wagering platform infrastructure, with raw material dependencies spanning semiconductor chips, cooling systems, and fiber optic cabling. Single-source vulnerability in M-Pesa API integration creates operational risk for East African operators. Distribution runs through Dubai Internet City as the regional technology hub for Gulf Cooperation Council market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across payment rail protocols and regulatory frameworks creates niche positioning opportunities for specialized operators. Mobile-first wagering adoption among Nigeria's median-age-18 population fragments demand into distinct behavioral clusters.
For Market Incumbents: Shield market position by deepening proprietary edge computing deployment in Lagos and Nairobi to sustain sub-100-millisecond latency advantages. Invest in CE marking harmonization to reduce per-market compliance engineering overhead. Vertical integration into mobile money agent networks defends against disintermediation by direct-to-consumer registration flows.
For New Entrants and Emerging Players: Responsible gambling engineering talent scarcity presents service-layer gaps where incumbents under-serve at-risk user identification capabilities. Target Ethiopia's unpenetrated market ahead of anticipated regulatory framework introduction. Deploy influencer partnership go-to-market strategies to bypass Kenya's broadcast advertising restrictions.
For Investors and Strategic Acquirers: Capital is best deployed toward platform operators with disciplined licensing compliance and localized payment integration across multiple jurisdictions. Long-term viability hinges on regulatory reciprocity expansion rather than single-market dominance. Watch licensing reciprocity agreements between South Africa's National Gambling Board and Nigerian regulators as the primary inflection signal for scalable addressable market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Localization | Sub-100-millisecond latency in Lagos and Nairobi enables live wagering competitiveness against cloud-dependent rivals. |
| CE Marking Harmonization | Standardized certification across Middle East and Africa jurisdictions reduces duplicate compliance engineering costs. |
| Mobile Money Integration | M-Pesa and Nigeria banking agent interoperability unlocks unbanked population access in high-growth corridors. |
| Responsible Gambling Infrastructure | Real-time behavioral intervention systems satisfy South Africa's National Gambling Board mandates while reducing churn. |
| Esports Platform Extension | Competitive video game wagering captures digital-native demographics with distinct event calendars from traditional sports. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with platform operators, regulatory affairs specialists, and mobile money integration engineers; and secondary validation through National Gambling Board filings, Betting Control and Licensing Board licensing databases, and M-Pesa transaction disclosures. Bottom-up triangulation across operator revenue disclosures and top-down reconciliation against addressable population estimates anchored volume projections.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning betting platform architecture, customer sophistication tiers, wagering mechanics, and sport type preferences. CAGRs derived from smartphone penetration curves, payment rail density trajectories, and regulatory reciprocity probability assessments. Forecast inputs incorporated 4G corridor expansion timelines and mobile money interoperability milestones.
Material uncertainties — currency volatility in Nigerian naira and Kenyan shilling, unannounced regulatory framework introductions in Ethiopia, and advertising restriction tightening — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
Billboard and Outdoor Advertising Market
Advertising and Marketing Media
South East Asia Advertising Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
Australia OOH and DOOH Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Digital Ad Spending Market
Advertising and Marketing Media
Digital OOH Advertising Market
Advertising and Marketing Media
Vietnam OOH and DOOH Market