
 Saudi Arabia Marketing and Advertising Agency Market | 2026-2036
Saudi Arabia Marketing and Advertising Agency Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Marketing and Advertising Agency Market Insights
SFDA content guidelines for health and wellness advertising is broadening compliance requirements across the agency landscape. WPP plc leverages its integrated creative and media infrastructure to serve multinational clients entering the Saudi market. Publicis Groupe SA anchors its position through data-driven personalization platforms tailored to Arabic-language consumer segments. Omnicom Group Inc. competes by sustaining long-standing relationships with public sector entities and sovereign wealth-funded ventures.
The Saudi Arabia Marketing and Advertising Agency sector encompasses professional service firms that plan, create, produce, and place promotional content across paid, owned, and earned media channels, typically operating through multidisciplinary teams combining creative directors, media planners, account strategists, and digital technologists. These agencies function as outsourced marketing departments or project-based partners, translating brand objectives into campaign architectures measured by reach, engagement, and conversion metrics. Digital Marketing commands the largest share of billings as platform spending on Snapchat, TikTok, and Instagram displaces traditional television budgets among younger demographics. Brand Strategy represents a concentrated margin pool where UBRAND and Intouch MENA specialize in repositioning family-owned conglomerates for international investor audiences. Creative Services faces margin compression from freelance marketplaces and in-house studio buildouts at major retailers and hospitality groups.
SFDA, the Communications and Information Technology Commission, and the General Authority for Audiovisual Media regulate advertising content standards, data privacy in digital targeting, and media ownership structures respectively, collectively elevating compliance costs while creating barriers for unlicensed operators. The PLI scheme and SME enablement programs channel government procurement toward locally registered agencies with Saudi national talent quotas. Stakeholders must monitor regulatory harmonization between Gulf Cooperation Council states as cross-border campaign execution becomes the default operating model for scale.
Market Dynamics
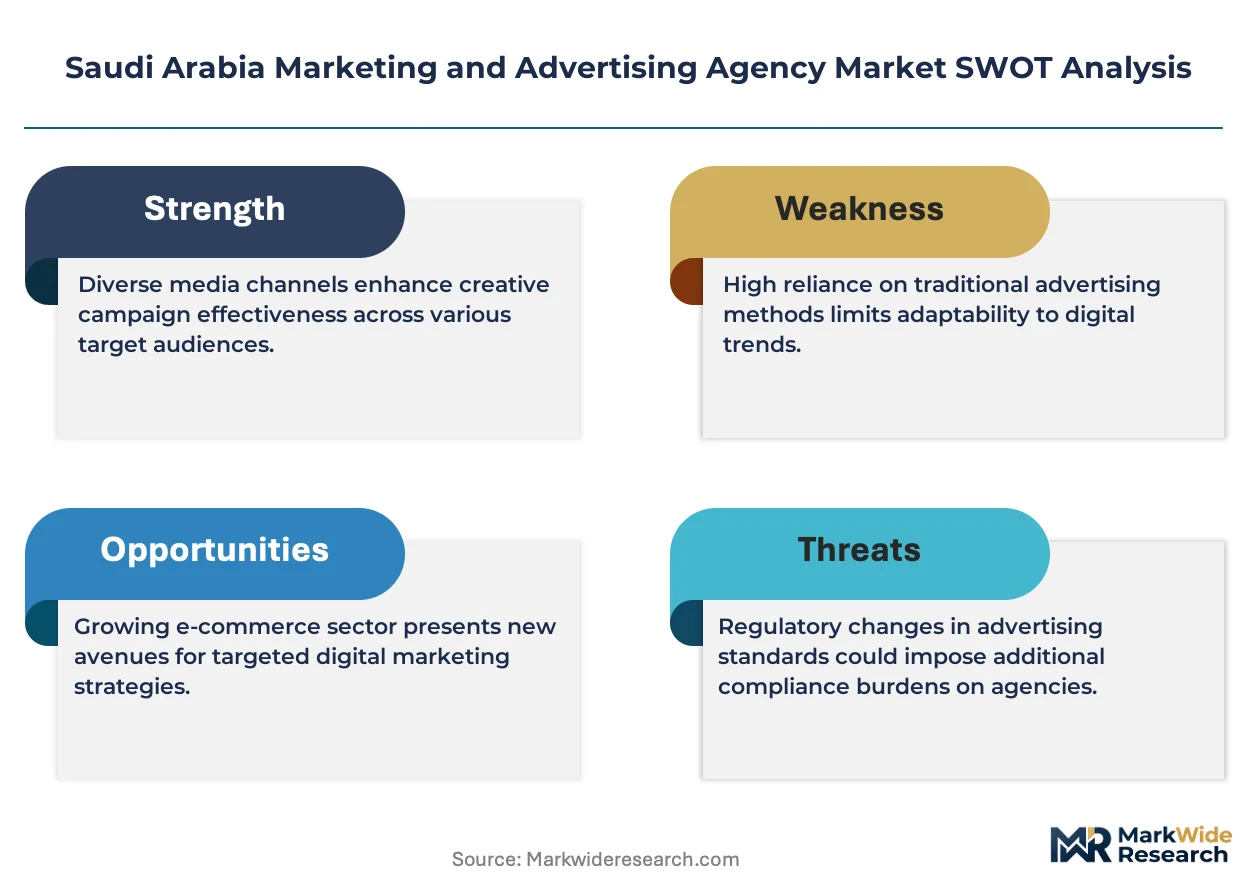
Digital transformation mandates under Vision 2030 are compressing traditional agency billing models as clients demand real-time performance analytics and platform-native creative production over broadcast-centric campaign architectures.
Growth Catalysts
- Vision 2030 diversification targets:Tourism, entertainment, and technology sectors are emerging as first-time advertisers with dedicated budgets, displacing oil and gas concentration in agency client rosters.
- Relaxed social content regulations:The General Authority for Audiovisual Media has streamlined approval timelines for digital-first campaigns, accelerating go-to-market velocity for influencer-led and user-generated content strategies.
- Riyadh-Jeddah corporate headquarters expansion:Multinational regional hubs are consolidating procurement decisions in Saudi Arabia, elevating local agencies to primary vendor status for Middle East and North Africa campaign execution.
Market Restraints
- SFDA health advertising compliance costs:Pharmaceutical and wellness clients now require dedicated regulatory review layers, inflating project overhead and extending delivery timelines.
- Freelance marketplace price compression:Creative Services margins are eroding as family-owned conglomerates and hospitality groups build in-house studios or source design talent through gig platforms.
- Saudi national talent quota requirements:The PLI scheme and SME enablement programs restrict government procurement to agencies meeting localization thresholds, limiting pool depth for specialized technical roles.
Strategic Opportunities
- Neom and Red Sea Project tourism campaigns:Giga-project developers require sustained multi-year brand building and destination marketing partnerships unavailable to short-term project shops.
- Arabic-language data personalization platforms:Converging customer data infrastructure with generative content tools creates first-mover advantage for agencies serving regional fintech and e-commerce clients.
- Cross-border GCC campaign execution:Regulatory harmonization between Gulf Cooperation Council states enables Saudi-registered agencies to capture regional accounts without establishing separate legal entities in each market.
Industry Challenges
- Platform algorithm expertise scarcity:Snapchat, TikTok, and Instagram content optimization requires specialized talent pools that outpace domestic training program output, forcing reliance on expatriate specialists.
- Legacy broadcast integration friction:Clients maintaining television budgets demand unified measurement frameworks that reconcile linear reach metrics with digital engagement data, complicating media planning workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Marketing and Advertising Agency Market |
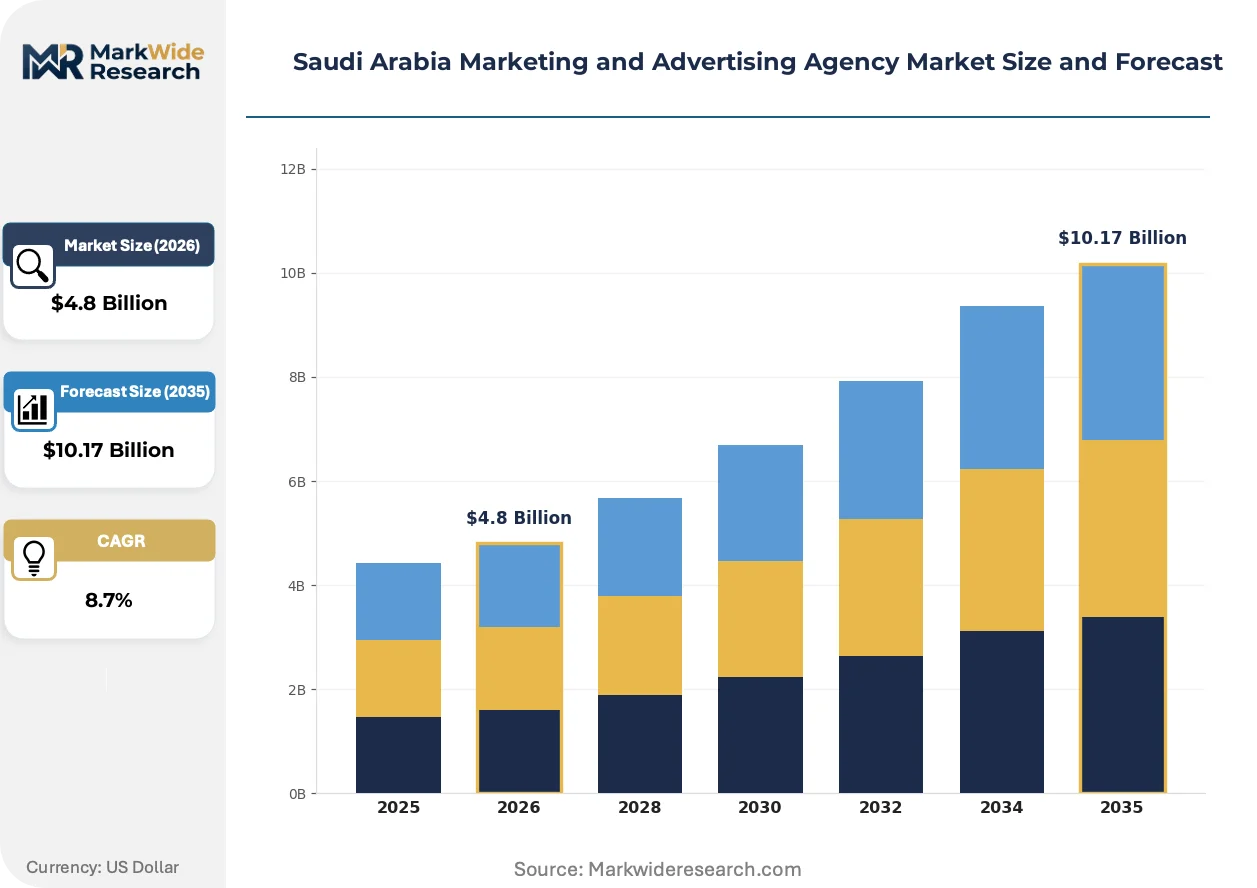
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Digital Marketing, Brand Strategy, Media Buying, Creative Services Client Type: SMEs, Corporates, Startups, Nonprofits Channel: Social Media, Traditional Media, Direct Mail, Events Industry Vertical: Retail, Hospitality, Technology, Healthcare |
| Companies Covered | WPP plc, Publicis Groupe SA, Omnicom Group Inc., The Interpublic Group of Companies, Inc., Dentsu Group Inc., Extend Advertising, UBRAND, Intouch MENA, Vital Media Agency, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Marketing and Advertising Agency Market Trends and Innovations
Generative artificial intelligence tools are reshaping creative production economics, compressing concept-to-asset timelines while forcing agencies to restructure retainer models around strategic advisory rather than hourly execution.
Generative AI content suites are automating variant production for platform-specific formats. Mid-market retail and quick-service restaurant clients now expect fifty to one hundred creative permutations per campaign flight. This capability is expanding into premium brand strategy engagements previously reserved for manual craft.
SFDA content guidelines for health and wellness advertising now mandate pre-submission review for all digital collateral. Pharmaceutical advertisers must maintain dedicated compliance officers. The clinical and wellness vertical is responding by consolidating agency rosters to partners with embedded regulatory affairs functions.
Performance-based compensation structures are displacing traditional retainer arrangements in the Saudi market. Procurement teams at sovereign wealth-funded ventures now tie agency fees to attributable conversion metrics. This behavioral shift is most visible in Riyadh-based fintech and e-commerce advertisers with direct-to-consumer transaction data infrastructure.
Saudi Arabia Marketing and Advertising Agency Market Segmentation
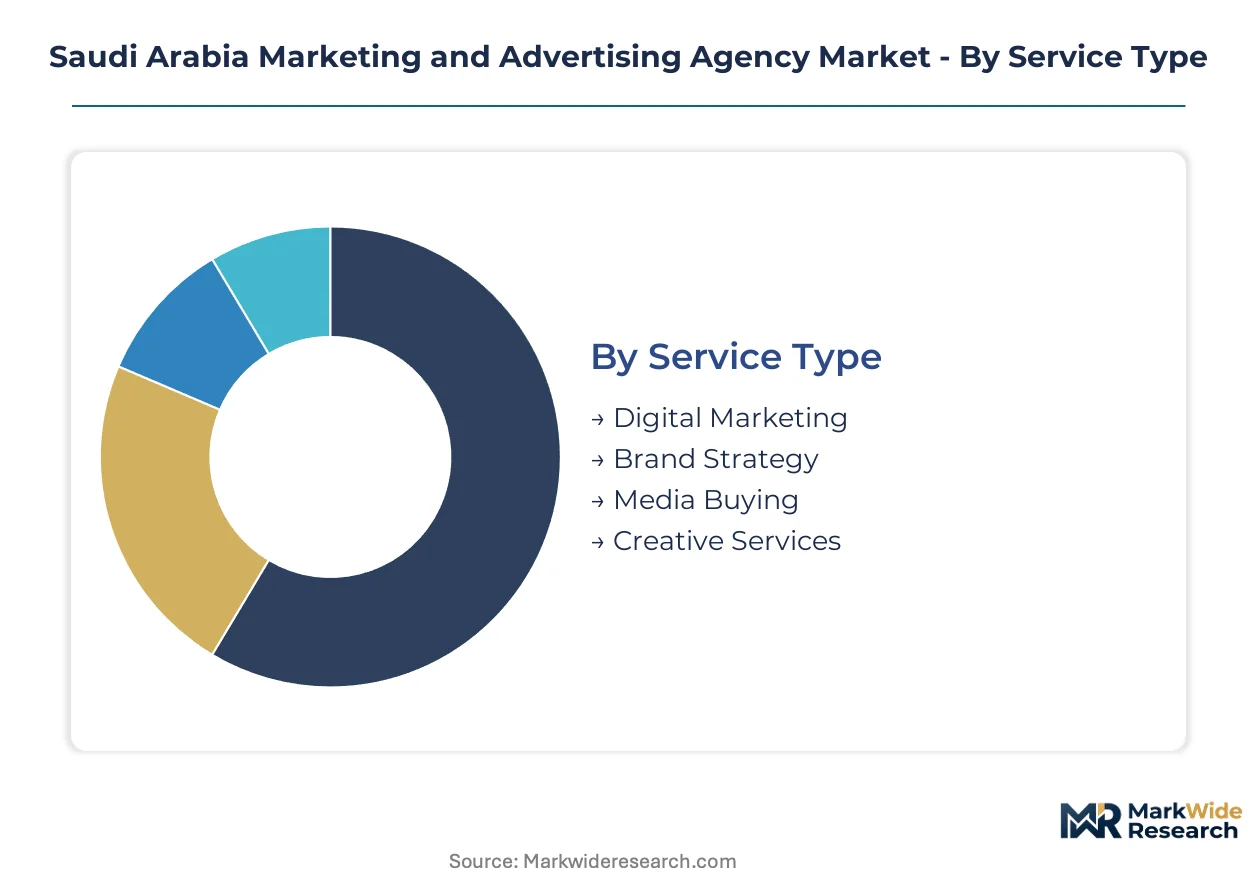
Agency service configurations in Saudi Arabia diverge sharply between standardized media execution and bespoke strategic advisory. Procurement patterns across Riyadh and Jeddah headquarters increasingly favor modular service bundling over monolithic retainers. Understanding segment boundaries reveals where margin pools concentrate versus where commoditization pressures dominate.
Service Type:
Customization intensity varies from algorithmic media optimization to highly interpretive brand repositioning work.
- Digital Marketing:Platform-native campaign execution spans programmatic buying, search optimization, and influencer network management. Demand concentrates among Riyadh-based fintech and e-commerce advertisers with direct attribution infrastructure. Vision 2030 digital transformation mandates accelerate procurement velocity for real-time analytics capabilities.
- Brand Strategy:Conglomerate repositioning for international investor audiences requires deep Arabic-language cultural interpretation and stakeholder mapping. Family-owned groups in Jeddah commercial districts drive sustained engagement for reputation architecture and merger communications.
- Media Buying:Consolidated television and digital inventory procurement leverages volume discounts across Snapchat, TikTok, and Instagram.
- Creative Services:Asset production faces margin compression from freelance marketplaces and in-house studio buildouts.
Leading the category by volume: Digital Marketing. Expanding most quickly: Brand Strategy.
Client Type:
Budget scale and procurement sophistication create four distinct engagement archetypes.
- SMEs:Project-based relationships favor modular digital packages with clear performance benchmarks. PLI scheme procurement preferences channel government contracts toward locally registered agencies meeting Saudi national talent quotas.
- Corporates:Multinational regional headquarters consolidate Middle East and North Africa campaign decisions in Riyadh, elevating local agencies to primary vendor status.
- Startups:Venture-funded technology ventures demand agile creative production with minimal retainer commitments.
- Nonprofits:Social impact campaigns operate under constrained budgets with heightened regulatory scrutiny from the General Authority for Audiovisual Media.
Dominant by spend: Corporates. Gaining share fastest: Startups.
Channel:
Platform selection reflects demographic targeting precision versus mass reach requirements.
- Social Media:Snapchat, TikTok, and Instagram command dominant platform spending among younger demographics. Algorithm expertise scarcity forces reliance on expatriate specialists.
- Traditional Media:Television maintains residual budgets among heritage brands demanding unified measurement frameworks.
- Direct Mail:Physical collateral persists in luxury retail and automotive segments.
- Events:Experiential activation supports Neom and Red Sea Project destination marketing requirements.
Highest revenue concentration: Social Media. Steepest expansion trajectory: Events.
Industry Vertical:
Regulatory exposure and creative risk tolerance segment vertical demand profiles.
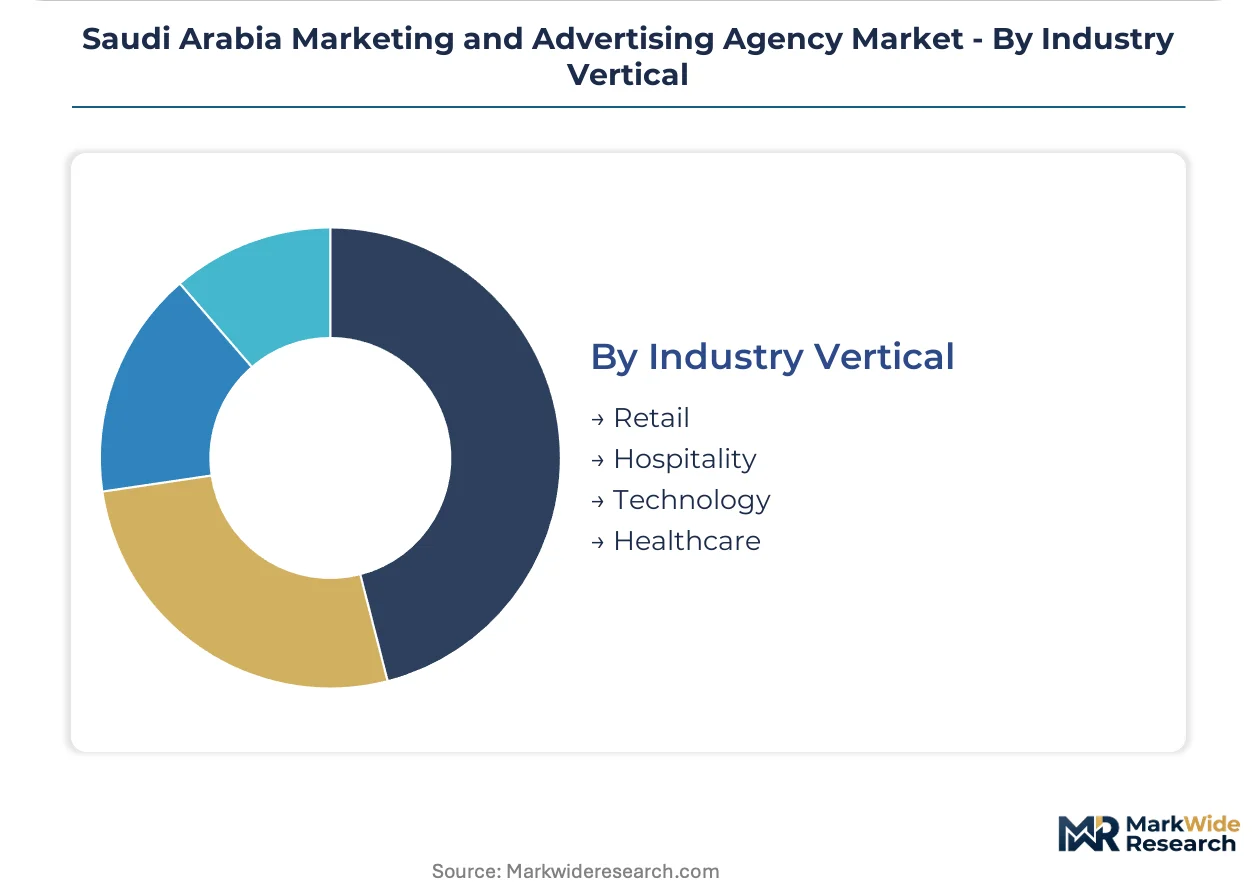
- Retail:Quick-service restaurant and mid-market fashion clients expect fifty to one hundred creative permutations per campaign flight.
- Hospitality:Giga-project developers require sustained multi-year brand building partnerships unavailable to short-term project shops.
- Technology:Fintech advertisers tie agency fees to attributable conversion metrics through performance-based compensation structures.
- Healthcare:SFDA content guidelines mandate pre-submission review for all digital collateral, inflating project overhead.
Largest current spend: Retail. Fastest-climbing vertical: Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors the Saudi Arabia Marketing and Advertising Agency Market, concentrating corporate headquarters procurement and sovereign wealth-funded campaign budgets in the capital's expanding commercial districts.
Riyadh
Riyadh's King Abdullah Financial District and Diriyah Gate developments attract multinational regional headquarters consolidating Middle East and North Africa marketing decisions. The PLI scheme channels government procurement toward agencies meeting Saudi national talent quotas. Diriyah Gate and Qiddiya entertainment city projects sustain multi-year destination marketing partnerships with established creative networks.
Jeddah
Jeddah's Red Sea port corridor and historic commercial districts host family-owned conglomerates seeking Arabic-language brand repositioning for international investor audiences. The General Authority for Audiovisual Media maintains streamlined approval timelines for digital-first campaigns originating from Western Region studios. Jeddah Economic City and King Abdullah Economic City clusters concentrate hospitality and retail advertising demand.
Eastern Province
The Eastern Province's Dammam-Khobar-Dhahran metropolitan area retains residual oil and gas advertising budgets while diversifying into petrochemical and industrial technology verticals. Aramco's localization procurement policies favor agencies with embedded regulatory affairs capabilities. Dhahran Techno Valley and King Fahd Industrial City host specialized B2B marketing requirements for energy sector suppliers.
NEOM Northwest
NEOM's Tabuk province development zone generates sustained demand for giga-project brand building unavailable to short-term project shops. The Communications and Information Technology Commission's digital infrastructure mandates accelerate platform-native creative production requirements. The Line and Oxagon industrial city developments require multi-year destination marketing partnerships with integrated creative and media capabilities.
Makkah Province
Makkah Province's religious tourism and hospitality infrastructure drives seasonal campaign spikes targeting pilgrimage and Umrah visitor segments. SFDA content guidelines for health and wellness advertising mandate pre-submission review for pharmaceutical collateral targeting the province's medical city developments. Jeddah-Makkah corridor logistics hubs concentrate quick-service restaurant and retail advertising procurement.
Saudi Arabia Marketing and Advertising Agency Market Competitive Landscape
The competitive structure tilts toward multinational network dominance in premium strategic advisory, with independent boutiques capturing specialized vertical niches. Consolidated holding companies command sovereign wealth and multinational procurement through integrated creative and media infrastructure. Three archetypes define positioning: global network full-service providers, regional Arabic-language specialists, and vertical-focused regulatory compliance shops. M&A activity concentrates on acquiring data personalization capabilities, while strategic partnerships target Neom and Red Sea Project giga-project mandates.
Within the global network tier, WPP plc, Publicis Groupe SA, and Omnicom Group Inc. occupy positions as primary vendors for multinational clients entering the Saudi market. WPP plc exemplifies integrated creative and media infrastructure deployment. Publicis Groupe SA anchors data-driven personalization platforms tailored to Arabic-language consumer segments. Omnicom Group Inc. represents sustained public sector relationship models with sovereign wealth-funded ventures. These network structures compete against regional independents including UBRAND and Intouch MENA in conglomerate repositioning engagements.
| Leading Market Players |
|---|
| WPP plc |
| Publicis Groupe SA |
| Omnicom Group Inc. |
| The Interpublic Group of Companies, Inc. |
| Dentsu Group Inc. |
| Extend Advertising |
| UBRAND |
| Intouch MENA |
| Vital Media Agency |
| Others |
Pricing and Supply Chain Analysis
Digital media inventory indices on Snapchat, TikTok, and Instagram cascade through Saudi agency billing models, compressing retainer margins as platform-native creative production displaces traditional broadcast-centric campaign architectures. Cost structures stratify between compliance-heavy healthcare verticals absorbing SFDA review overhead and agile fintech clients demanding performance-based fee arrangements.
Pricing Analysis
Outcome-tied compensation anchors value-based pricing for Riyadh-based fintech and e-commerce advertisers with direct attribution infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates multinational network full-service providers from regional Arabic-language specialists and compliance-focused boutiques. Pricing pressure stems from freelance marketplace price compression in Creative Services as family-owned conglomerates build in-house studios. SME advertisers exhibit highest price sensitivity due to constrained project budgets, while sovereign wealth-funded ventures prioritize capability over cost.
Supply Chain Analysis
Freight costs for physical event production and experiential activation materials concentrate procurement leverage in Riyadh and Jeddah commercial districts. Talent supply draws from Lebanon, Egypt, and the UAE for Arabic-language creative specialists, while platform algorithm expertise rests on expatriate specialists from the UK and US. Single-source vulnerability sits with Snapchat and TikTok content optimization talent pools outpacing domestic training output. Distribution runs through multinational network holding companies commanding consolidated media inventory access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA content guidelines for health and wellness advertising erect a cost-of-compliance barrier that favors established agencies with embedded regulatory affairs functions over unlicensed operators. This regulatory moat protects compliant incumbents while constraining new entrant viability in pharmaceutical and wellness verticals.
For Market Incumbents:Acquire data personalization platform capabilities to defend against Publicis Groupe SA and WPP plc's integrated infrastructure advantages. Build embedded regulatory affairs teams to capture pharmaceutical client roster consolidation driven by SFDA pre-submission mandates. Capacity addition in NEOM Tabuk province secures giga-project destination marketing partnerships unavailable to short-term project shops.
For New Entrants and Emerging Players:Enter via Arabic-language generative AI content tools serving mid-market retail clients expecting fifty to one hundred creative permutations per campaign flight. Target Jeddah-based family-owned conglomerates seeking brand repositioning for international investor audiences with lower compliance overhead than Riyadh government procurement. White-space opportunity sits with cross-border GCC campaign execution as regulatory harmonization enables Saudi-registered agencies to capture regional accounts.
For Investors and Strategic Acquirers:Distressed-cycle entries favor vertical-focused regulatory compliance shops in Riyadh with established SFDA relationships and sovereign wealth client access. Long-term viability over a five-to-ten year window hinges on agencies' ability to pivot from hourly execution toward strategic advisory retainer models. Watch for performance-based compensation structure adoption rates among fintech advertisers as inflection indicator for value-based pricing normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Function Buildout | SFDA compliance capabilities unlock pharmaceutical client consolidation and defend margin against unlicensed competitors. |
| Arabic-Language Data Platform Acquisition | Personalization infrastructure captures fintech and e-commerce demand for real-time customer segmentation. |
| NEOM Giga-Project Partnership | Multi-year destination marketing contracts provide revenue visibility unavailable to project-based competitors. |
| Cross-Border GCC Expansion | Regulatory harmonization enables Saudi-registered agencies to serve regional accounts without local entity establishment. |
| Performance-Based Compensation Transition | Outcome-tied fee structures align agency incentives with sovereign wealth-funded venture procurement requirements. |
Research Methodology
Document review covered regulatory filings with the Saudi Food and Drug Authority, Communications and Information Technology Commission guidelines, and General Authority for Audiovisual Media standards, complemented by interviews with creative directors, media planners, account strategists, and digital technologists. Secondary validation drew from agency holding company annual reports, Vision 2030 policy documents, and SME enablement program procurement records. Bottom-up service segment sizing and top-down macroeconomic triangulation anchored market estimates.
Segment-level projections across service type, client archetype, channel, and industry vertical fed into consolidated market sizing over the projection horizon. CAGRs derived from historical billing trend analysis and forward-looking procurement pattern assessment. Model inputs included platform spending shifts from television to Snapchat, TikTok, and Instagram; PLI scheme localization thresholds; and giga-project advertising commitment timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory harmonization delays or accelerated freelance marketplace penetration. Forecasts reflect assumptions around Vision 2030 diversification pace and digital transformation mandate implementation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Global Advertising Agency Software Market
Advertising and Marketing Media
Europe Digital OOH Advertising Market
Advertising and Marketing Media
Online Advertising Market
Advertising and Marketing Media
In-Game Advertising Market
Advertising and Marketing Media
China OOH and DOOH Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
Global Contextual Advertising Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market