
 Europe Dental Tourism Market | 2026-2036
Europe Dental Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dental Tourism Market Insights
Market Context
ISO 9001 clinic certification is reorganizing competitive hierarchies across European dental tourism corridors. Fortis Healthcare Limited leverages its hospital infrastructure to anchor premium surgical dentistry packages in key source markets. Clove Dental competes on volume-scale cosmetic procedures, while Oris Dental specializes in orthodontic tourism workflows that reduce treatment cycle times for international patients.
Technical Definition and Segment Structure
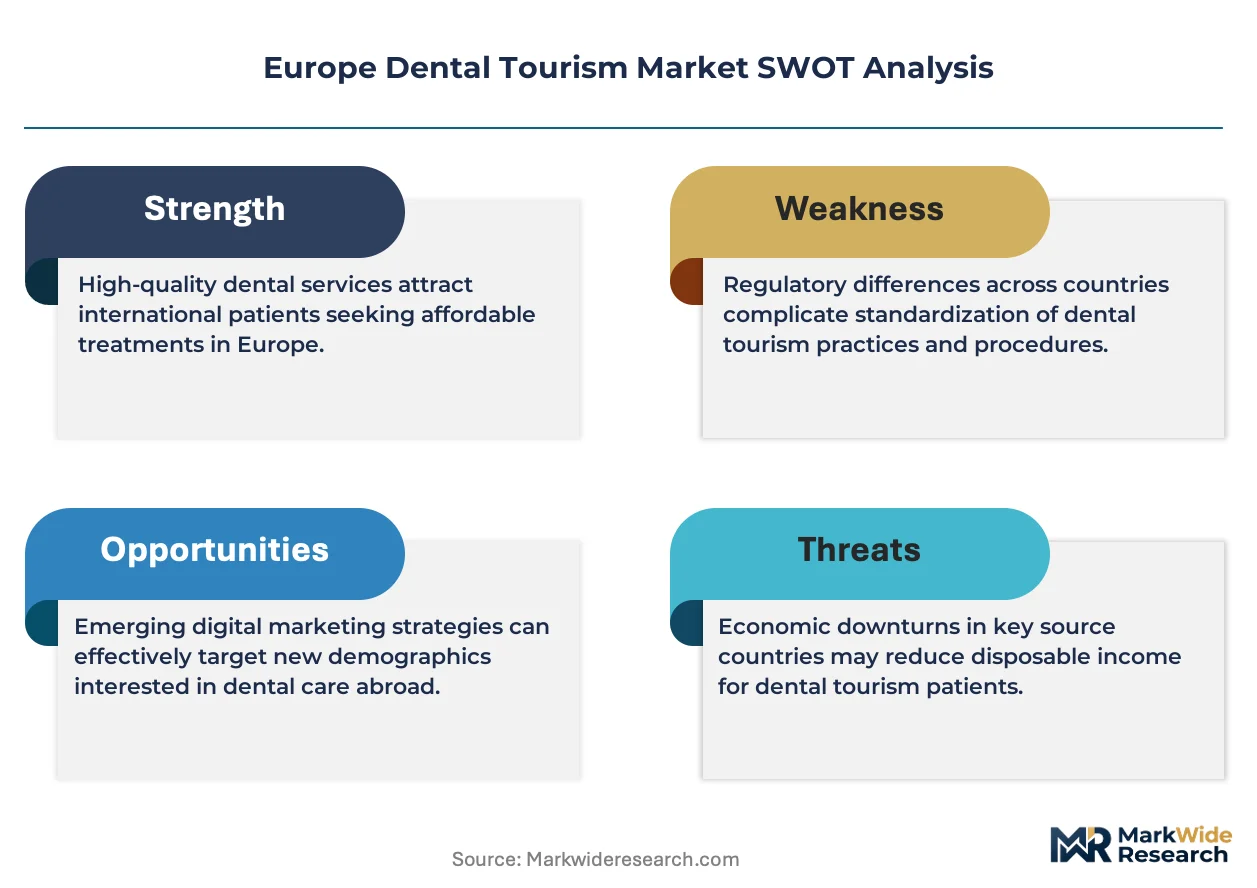
Europe dental tourism encompasses cross-border travel for oral healthcare services, typically involving titanium implant systems, zirconia crown fabrication, and CAD/CAM-milled prosthetics delivered through compressed treatment schedules. The practice functions as a cost-arbitrage mechanism connecting high-price home markets with accredited lower-cost destinations. Implant dentistry occupies the largest revenue pool due to procedure complexity and material intensity, while cosmetic dentistry registers the fastest expansion as social media visibility amplifies aesthetic demand. Destination type segmentation reveals private clinics capturing disproportionate margin as they control end-to-end patient experience without hospital overhead structures.
Regulatory Environment and Outlook
EU MDR, CE marking requirements, and EMA-adjacent national health ministry oversight govern device standards and clinic operating permissions across European dental tourism corridors. These frameworks shape patient trust thresholds and determine which facilities qualify for insurance reimbursement partnerships in source countries. Stakeholders must monitor evolving GDPR health data portability rules and national reimbursement policy shifts that could redirect patient flows between established and emerging destination clusters.
Market Dynamics
EU MDR compliance deadlines and CE marking recertification cycles are compressing clinic accreditation timelines across European dental tourism corridors, forcing destination facilities to consolidate quality management systems or exit cross-border patient markets entirely.
Growth Catalysts
- Titanium implant systems:Hungarian clinics leverage bulk procurement of osseointegration hardware to compress per-procedure costs below Nordic domestic rates by 40-60%.
- EU MDR harmonization:Standardized device traceability requirements reduce patient litigation risk and enable insurance reimbursement partnerships in German and Dutch source markets.
- CAD/CAM milling clusters:Polish prosthetic laboratories in Wrocław and Kraków achieve 48-hour crown turnaround through concentrated digital dentistry infrastructure.
Market Restraints
- Zirconia supply concentration:Ukrainian and Russian raw material disruptions have redirected ceramic powder sourcing to German and Japanese suppliers at 15-25% premium.
- GDP health data portability:Cross-border patient record transfers face 30-90 day compliance review cycles that delay treatment scheduling.
- Domestic provider retaliation:Swedish and Norwegian dental associations lobby national insurers to exclude non-Nordic clinic reimbursements from public health schemes.
Strategic Opportunities
- Romania and Bulgaria:Underserved Black Sea corridor offers 50-70% cost arbitrage against Western European rates with EU regulatory equivalence.
- Orthodontic tourism workflows:Clear aligner remote monitoring enables 6-12 month treatment cycles with only two in-person visits to destination clinics.
- EU Green Deal medical waste standards:Early adopters of mercury-free amalgam replacement and biodegradable impression materials qualify for sustainability-linked procurement contracts.
Industry Challenges
- ISO 9001 auditor scarcity:Accredited certification bodies face 8-14 month backlog for clinic quality system validation across Central European destinations.
- Prosthetic technician migration:Skilled CAD/CAM operators relocate from Polish and Hungarian labs to German manufacturing facilities at 2-3x wage multiples.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dental Tourism Market |
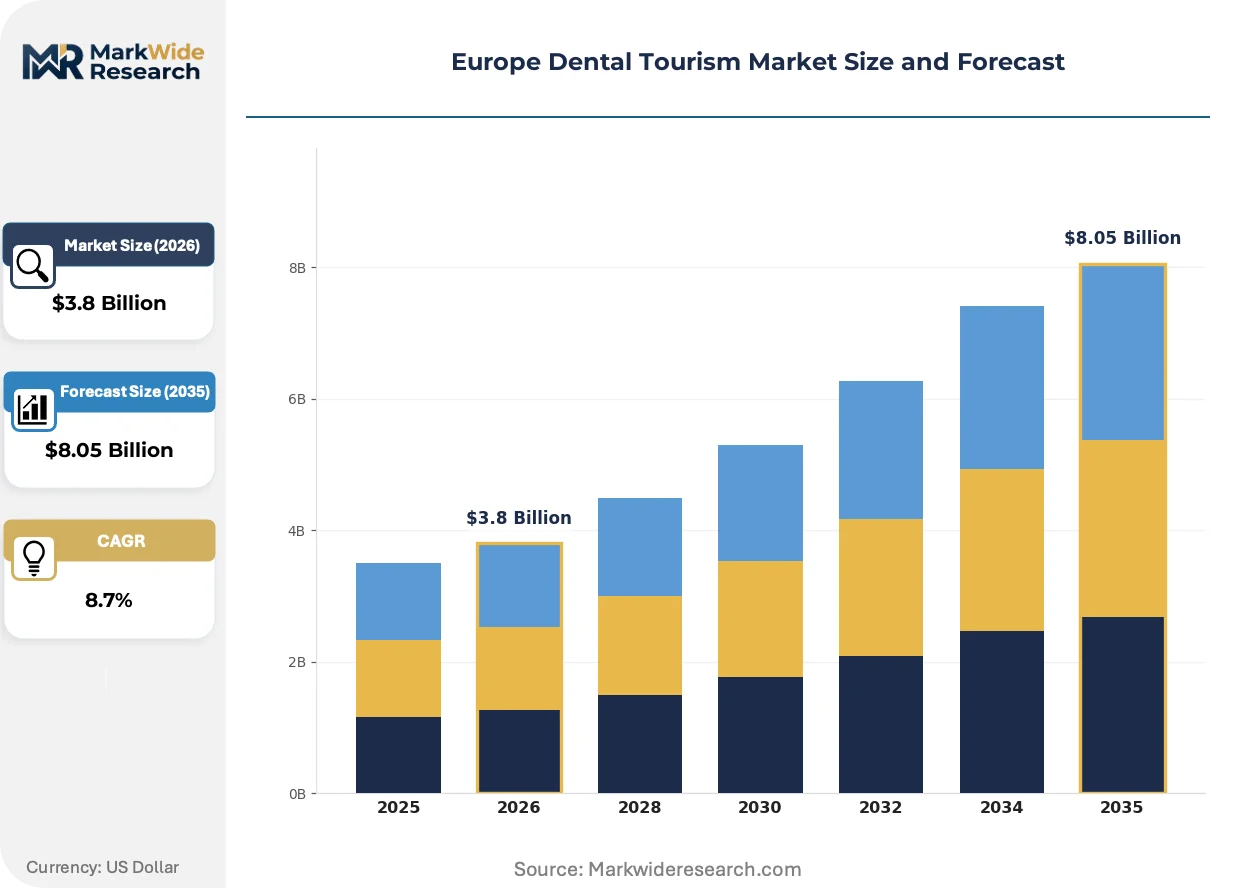
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Implant Dentistry, Cosmetic Dentistry, Orthodontics, Periodontics Patient Demographic: Adults, Seniors, Families, Corporate Clients Destination Type: Private Clinics, Hospitals, Dental Tourism Agencies, Wellness Resorts Treatment Method: Conservative Treatment, Surgical Treatment, Laser Treatment, Endodontics |
| Companies Covered | Fortis Healthcare Limited, Clove Dental, Oris Dental, Dubai Dental Hospital, Medlife Group, ACIBADEM Healthcare Group, Apollo Hospitals Enterprise Limited, Imperial Dental Specialist Centre, Raffles Medical Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dental Tourism Market Trends and Innovations
Digital workflow integration and remote patient monitoring protocols are compressing traditional dental tourism treatment cycles from multi-week stays to 48-72 hour surgical interventions with follow-up managed through telemedicine platforms.
Cone-beam computed tomography (CBCT) combined with intraoral scanning is decomposing the traditional impression-to-laboratory workflow. Turkish and Hungarian clinics now fabricate surgical guides and provisional prosthetics before patient arrival. This pre-arrival manufacturing compresses chair time and enables higher patient throughput per operatory.
EU MDR Article 10 technical documentation requirements are mandating device-specific clinical evidence portfolios for implant systems. Manufacturers must submit post-market surveillance data to notified bodies. Smaller destination clinics in Poland and Croatia face supplier consolidation as distributors drop marginal product lines to manage compliance costs.
Package pricing transparency platforms now dominate patient acquisition channels in Northern European source markets. Aggregator sites displaying all-inclusive treatment quotes displace traditional referral networks. German and Dutch patients increasingly book directly through comparison engines rather than domestic dentist intermediaries, compressing commission structures and forcing destination clinics to absorb marketing spend previously outsourced.
Europe Dental Tourism Market Segmentation
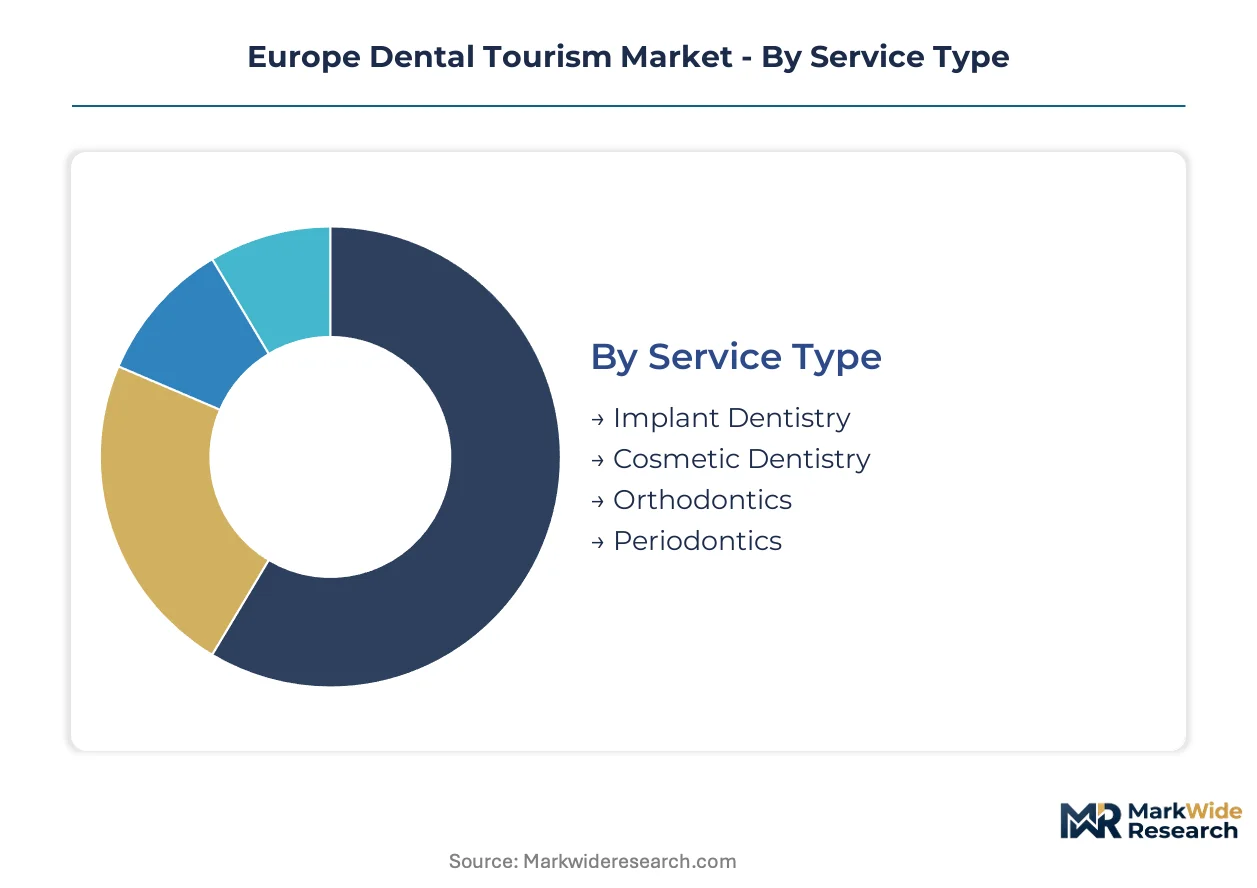
Segmentation in dental tourism reveals how patient priorities diverge across clinical complexity, travel convenience, and price sensitivity. Service mix and destination format choices determine margin structures and patient acquisition costs for European providers competing for cross-border revenue.
Service Type:
Cosmetic dentistry faces the strongest substitution threat from home-market clear aligner mail-order services, while implant dentistry's surgical complexity protects it from remote alternatives.
- Implant Dentistry:Titanium fixture placement with immediate or delayed loading protocols requires osseointegration monitoring and bone grafting adjuncts. German and Dutch seniors dominate demand as domestic reimbursement gaps push them toward Hungarian and Polish surgical centers offering compressed treatment schedules.
- Cosmetic Dentistry:Veneer preparation, whitening protocols, and composite layering address aesthetic concerns with shorter chair time. Social media visibility drives patient flow from Nordic countries to Turkish clinics marketing smile transformations through influencer partnerships.
- Orthodontics:Fixed appliance and aligner therapies with remote monitoring capabilities.
- Periodontics:Soft tissue grafting and guided bone regeneration for compromised dentition.
Implant dentistry retains volume leadership; cosmetic dentistry holds the steepest expansion curve.
Patient Demographic:
Cost tier stratification separates high-volume seniors seeking functional restoration from premium-priced corporate clients demanding concierge scheduling.
- Seniors:Fixed-income retirees from Sweden, Norway, and the UK pursuing full-arch rehabilitation. EU MDR-compliant implant systems reduce their litigation risk perception, while package pricing transparency enables budget certainty for pension-dependent households.
- Adults:Working-age patients aged 35-55 balancing treatment complexity against annual leave constraints. Polish clinics capture this cohort through weekend implant protocols that compress surgery and provisional placement into 72-hour windows.
- Families:Multi-generational travel units combining pediatric orthodontics with parental restorative work.
- Corporate Clients:Employer-sponsored dental benefit programs with negotiated clinic networks.
Seniors generate the highest procedure volume per capita; corporate channels are climbing fastest as benefits administrators consolidate vendor panels.
Destination Type:
Supply concentration in private clinic formats reflects their operational flexibility compared to hospital overhead structures.
- Private Clinics:Independent facilities controlling end-to-end patient experience from airport transfer through follow-up telemedicine. Hungarian operators in Budapest and Sopron leverage ISO 9001 certification to qualify for Dutch insurer reimbursement partnerships.
- Hospitals:Integrated medical campuses with anesthesia support and inpatient capacity for complex maxillofacial reconstruction. Fortis Healthcare Limited anchors premium surgical packages through hospital infrastructure in source market proximity.
- Dental Tourism Agencies:Intermediary booking platforms aggregating clinic availability and package pricing.
- Wellness Resorts:Hospitality-integrated facilities combining recovery accommodation with spa amenities.
Private clinics dominate revenue capture; hospital-based dentistry is expanding most quickly as surgical case complexity rises.
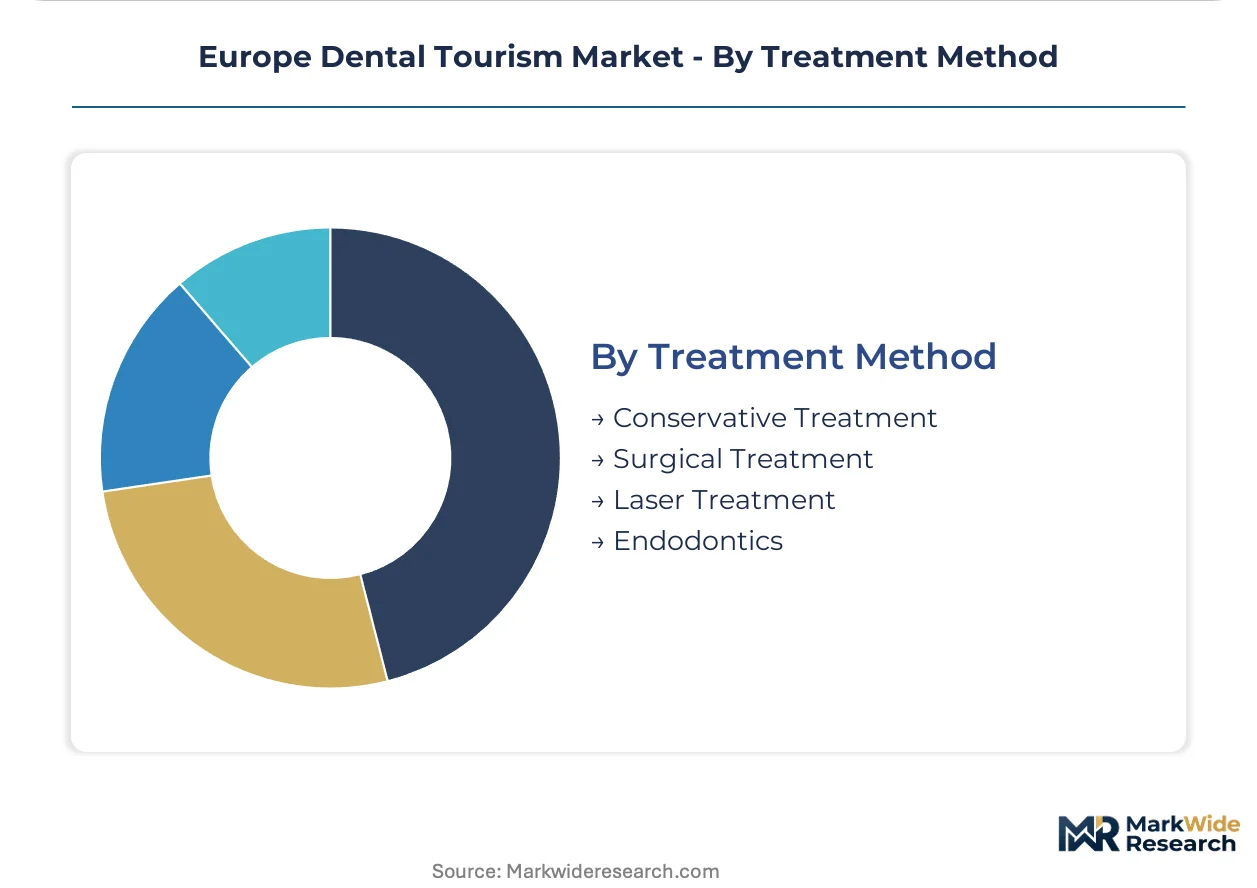
Treatment Method:
Technology intensity separates laser-assisted protocols commanding premium pricing from conventional mechanical approaches competing on cost.
- Surgical Treatment:Flap elevation, bone augmentation, and implant osteotomy requiring sterile field maintenance. Turkish clinics in Istanbul and Antalya invest in CBCT-guided surgery centers to differentiate from competitors relying on two-dimensional radiography.
- Conservative Treatment:Direct restorations, inlays, and preventive interventions preserving tooth structure. Romanian clinics in Bucharest and Cluj-Napoca attract price-sensitive patients through composite artistry at 60% below Western European rates.
- Laser Treatment:Soft tissue contouring and peri-implantitis management with reduced healing times.
- Endodontics:Microscopic root canal therapy and retreatment of failed previous interventions.
Surgical treatment retains volume leadership; laser protocols hold the steepest expansion trajectory as patient comfort preferences intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Destination capacity concentrates in Central and Eastern European corridors where EU MDR harmonization enables cross-border patient flows from high-price Nordic and Western European source markets. Clinic accreditation density and cost arbitrage differentials determine competitive positioning across national borders.
Hungary
German and Dutch retirees seeking full-arch implant rehabilitation dominate inbound demand. EU MDR-compliant titanium implant systems qualify Budapest and Sopron clinics for Dutch insurer reimbursement partnerships. The capital's ISO 9001-certified surgical centers leverage 48-hour crown turnaround from local CAD/CAM milling clusters.
Turkey
Social media-driven cosmetic dentistry attracts Nordic patients through influencer-marketed smile transformation packages. CE marking requirements for zirconia crown imports from Ukrainian alternative suppliers have shifted sourcing to German ceramic powder at elevated cost. Istanbul and Antalya CBCT-guided surgery centers differentiate through pre-arrival surgical guide fabrication.
Poland
Working-age adults aged 35-55 from the UK and Germany compress treatment into 72-hour weekend windows. GDPR health data portability compliance reviews delay cross-border record transfers by 30-90 days. Wrocław and Kraków prosthetic laboratories achieve compressed turnaround through concentrated digital dentistry infrastructure.
Romania
Price-sensitive patients from Western Europe pursue composite artistry and conservative restorations at 60% below domestic rates. National health ministry oversight aligns with EU MDR device traceability standards. Bucharest and Cluj-Napoca clinics capture volume through EU regulatory equivalence without Schengen border friction.
Bulgaria
Underserved Black Sea corridor positioning attracts cost-arbitrage seekers from Italy and Greece. EMA-adjacent regulatory frameworks enable device standard parity with Western European destinations. Sofia and Varna private clinics invest in ISO 9001 quality system implementation to qualify for emerging reimbursement partnerships.
Europe Dental Tourism Market Competitive Landscape
Concentration sits with private clinic networks controlling end-to-end patient experience through integrated airport transfer, accommodation, and telemedicine follow-up protocols. Hospital-based operators capture complex maxillofacial surgical cases requiring anesthesia support and inpatient capacity. Three archetypes dominate: ISO 9001-certified surgical centers competing on accreditation transparency, volume-scale cosmetic dentistry operators, and hospital-anchored premium surgical packages. Competitive moves center on M&A consolidation of prosthetic laboratory capacity and backward integration into CAD/CAM milling to compress crown turnaround times.
Among hospital-anchored operators, Fortis Healthcare Limited exemplifies the premium surgical package archetype through integrated medical campus infrastructure. Clove Dental occupies a position within the volume-scale cosmetic segment, while Oris Dental represents the orthodontic tourism workflow specialization. These three entities anchor distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| Fortis Healthcare Limited |
| Clove Dental |
| Oris Dental |
| Dubai Dental Hospital |
| Medlife Group |
| ACIBADEM Healthcare Group |
| Apollo Hospitals Enterprise Limited |
| Imperial Dental Specialist Centre |
| Raffles Medical Group |
| Others |
Pricing and Supply Chain Analysis
EU MDR harmonization gates both implant system qualification and price differentiation simultaneously, compressing clinic margins while elevating certified providers above uncertified competitors. CE marking tiers separate Budapest surgical centers commanding Dutch insurer partnerships from Bucharest operators competing solely on spot pricing.
Pricing Analysis
EU MDR dictates the pricing tier structure across European dental tourism corridors. Three-tier pricing structure across premium ISO 9001-certified surgical centers, mid-tier CE-marked clinics, and economy operators without full quality accreditation dominates the landscape. Price differentiation hinges on certification level and geographic delivery cost, with Nordic patient transport packages absorbing 15-20% of total procedure value. Cost compression in economy tiers is intensifying because Ukrainian zirconia supply disruptions forced ceramic powder sourcing to German and Japanese suppliers. Pension-dependent seniors from Sweden and Norway exhibit highest price sensitivity, while corporate benefit administrators demonstrate lowest sensitivity due to negotiated volume contracts.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains titanium implant hardware delivery schedules to Hungarian and Polish milling clusters. Manufacturing concentrates in Germany, Switzerland, and South Korea for precision-machined implant fixtures, while zirconia ceramic blanks draw from Japanese and German powder processing facilities. Raw material dependencies span titanium alloy rod, yttria-stabilized zirconia, and cobalt-chrome milling stock. Single-source vulnerability sits with Ukrainian ceramic feedstock alternatives now sanctioned. Distribution runs through authorized distributor networks holding EU MDR technical documentation rather than direct clinic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe dental tourism sits in early-cycle expansion as remote orthodontic monitoring protocols unlock patient segments previously blocked by travel constraints. Clear aligner telemedicine integration expands addressable demand beyond traditional surgical tourism.
For Market Incumbents: Consolidate prosthetic laboratory capacity in Wrocław and Kraków to defend 48-hour crown turnaround advantages against emerging Romanian competitors. Lock in CAD/CAM operator retention through equity participation before German manufacturing facilities absorb skilled technician migration. ISO 9001 auditor scarcity threatens certification renewal timelines; preemptive quality system investment separates sustainable operators from forced exits. For New Entrants and Emerging Players: Lead with orthodontic tourism workflows targeting UK and German working-age adults seeking 6-12 month aligner protocols with minimal chair time. Black Sea corridor positioning in Varna and Sofia offers 50-70% cost arbitrage with EU regulatory equivalence. Remote patient monitoring platform integration enables direct patient acquisition without aggregator commission structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Hungarian clinic networks holding Dutch reimbursement partnerships but facing technician wage inflation. Five-to-ten year viability favors operators with backward integration into CAD/CAM milling rather than third-party laboratory dependency. Watch for GDPR health data portability rule harmonization as inflection signal enabling compressed treatment scheduling.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9001 Quality System Implementation | Budapest clinics qualify for Dutch insurer reimbursement partnerships through accredited certification. |
| Backward Integration into CAD/CAM Milling | Wrocław operators compress crown turnaround from 96 hours to 48 hours through captive laboratory capacity. |
| Remote Patient Monitoring Platform Launch | Clear aligner workflows reduce in-person visits from twelve to two across 6-12 month treatment cycles. |
| CE Marking Pathway Investment | Turkish zirconia crown imports maintain EU market access through EMA-adjacent national health ministry alignment. |
| Strategic Partnership with Aggregator Platforms | German and Dutch patients increasingly book directly through comparison engines displacing traditional referral networks. |
Research Methodology
Desk research of EU MDR compliance databases, national health ministry reimbursement registries, and clinic accreditation listings preceded structured interviews with dental clinic operations directors, prosthetic laboratory managers, and cross-border patient coordinators. Primary fieldwork with Hungarian and Polish clinic networks validated pricing transparency and package structure assumptions. Secondary sources encompassed CE marking notified body filings, GDPR health data portability guidance documents, and dental device manufacturer technical documentation. Bottom-up patient flow modeling triangulated against top-down market sizing from reimbursement partnership coverage data.
Variance decomposition across service type, patient demographic, destination format, and treatment method segmentation dimensions anchored the analytical framework. Growth trajectories derived from procedure volume elasticity to cost arbitrage differentials and regulatory harmonization progress across the analysis window. Modeled inputs spanned titanium implant system pricing indices, zirconia ceramic supply chain disruption scenarios, and ISO 9001 certification penetration curves by destination country.
Underlying assumptions cover sustained EU MDR enforcement consistency and stable Nordic pension travel budgets, with deviation risk concentrated in German ceramic powder supply shocks and Swedish domestic provider retaliation through reimbursement exclusion lobbying. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Outbound Medical Tourism Services Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market