
 South Korea Medical Tourism Market | 2026-2036
South Korea Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Medical Tourism Market Intelligence
Korea Medical Service Accreditation (KOIHA) standards is reorganizing which hospitals qualify for government-backed medical tourism promotion. Samsung Medical Center leverages its integrated diagnostic and surgical campus to anchor high-complexity cases from Central Asia. Severance Hospital competes through its specialized spine and joint reconstruction unit. Korean Air controls a significant share of medical traveler logistics through dedicated patient concierge routing.
South Korea medical tourism encompasses the organized provision of clinical, rehabilitative, and wellness services to foreign nationals seeking elective or essential care outside their home jurisdiction, typically bundled with travel, accommodation, and interpreter coordination. Cosmetic surgery procedures incorporate advanced 3D imaging pre-consultation and minimally invasive techniques that reduce recovery stay duration. Orthopedic surgery leads service type revenue due to bundled knee and hip replacement packages priced below US and European benchmarks. Rehabilitation segments are expanding fastest as post-surgical recovery stays extend average trip duration and accommodation spend.
MFDS pharmaceutical and device standards, KOIHA hospital accreditation, and Ministry of Health and Welfare promotional frameworks collectively shape which facilities receive inbound patient referrals and government marketing support. MFDS approval requirements for implants and aesthetic devices used in tourist-facing procedures create compliance barriers that filter lower-capacity clinics from premium positioning. Stakeholders must monitor how KOIHA accreditation tiers and MFDS device registration timelines affect which hospitals maintain preferred status under shifting bilateral health agreements.
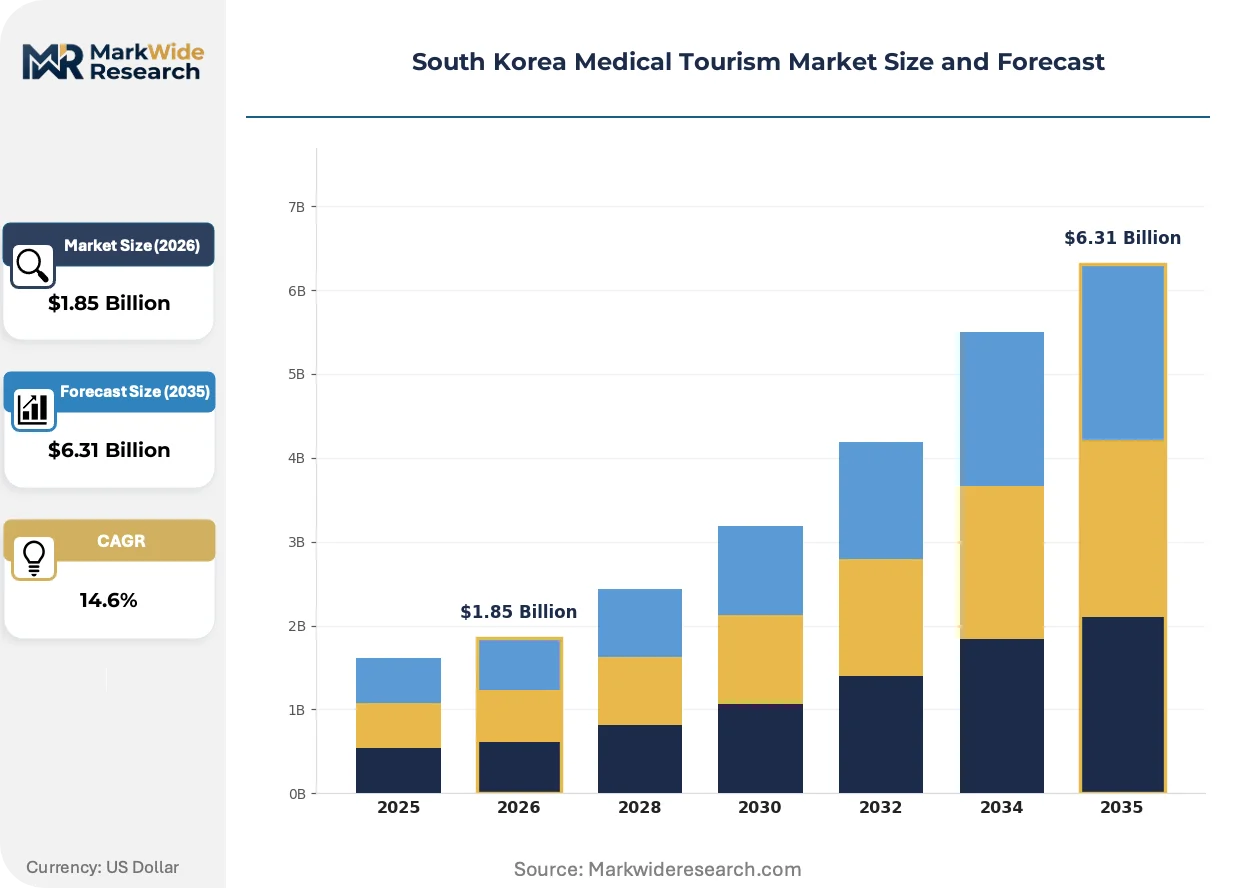
Market Dynamics
KOIHA accreditation tiers are restructuring which South Korean hospitals receive government-backed medical tourism promotion, filtering lower-capacity clinics from premium patient referrals while concentrating inbound volume in Seoul's Gangnam-certified facilities.
Growth Catalysts
- MFDS Device Registration:Accelerated approval timelines for aesthetic implants and orthopedic devices expand the procedure catalog available to foreign patients seeking bundled surgical packages.
- Southeast Asian Demand Concentration:Rising middle-class disposable income in Vietnam, Indonesia, and Thailand generates patient flow specifically targeting cosmetic and dental procedures priced below Singapore benchmarks.
- 3D Imaging Pre-Consultation:Virtual surgical planning technology reduces required on-ground stay duration, lowering total trip cost and expanding addressable patient segments with limited vacation allowances.
Market Restraints
- KOIHA Compliance Burden:Tiered accreditation requirements demand capital investment in interpreter services, international billing systems, and dedicated foreign patient wards that exclude smaller clinic operators.
- Airline Route Concentration:Korean Air and Asiana control the majority of medical traveler logistics through dedicated concierge routing, creating dependency on limited carrier capacity during peak seasonal demand.
- Post-Surgical Recovery Infrastructure:Shortage of licensed rehabilitation facilities near accredited hospitals extends patient stay requirements beyond standard hotel accommodation capacity.
Strategic Opportunities
- Central Asian Patient Flow:Samsung Medical Center's integrated diagnostic campus anchors high-complexity oncology and cardiovascular cases from Kazakhstan and Uzbekistan with limited domestic tertiary capacity.
- Rehabilitation Segment Expansion:Post-surgical recovery stays lengthen average trip duration and accommodation spend, creating white space for medically supervised wellness resorts outside Seoul's core district.
- Ministry of Health and Welfare Promotional Frameworks:Bilateral health agreements with Middle Eastern governments generate pre-qualified patient referrals for orthopedic bundled packages covered by sovereign insurance funds.
Industry Challenges
- Interpreter Certification Bottlenecks:MFDS and KOIHA mandate medically trained interpreters for accredited facilities, but national certification programs graduate insufficient candidates to match hospital expansion timelines.
- Implant Inventory Financing:Aesthetic and orthopedic procedures require pre-positioned high-value device inventory, tying working capital in FDA- and CE-marked implants awaiting patient confirmation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Medical Tourism Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Orthopedic Surgery, Cardiology, Rehabilitation End User: International Patients, Local Residents, Insurance Companies, Healthcare Facilitators Accommodations: Hotels, Guest Houses, Clinics, Wellness Centers Payment Method: Insurance, Out-of-Pocket, Medical Loans, Credit Cards |
| Companies Covered | Hilton Hotels, VIP Travel Korea, Samsung Medical Center, Korea Tourism Organization, Bookimed, Severance Hospital, Taj Hotels, Ministry of Health and Welfare, Korean Air, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Medical Tourism Market Strategic Shifts & Innovations
Digital patient journey orchestration and minimally invasive surgical platforms are compressing recovery timelines while regulatory tightening around device traceability reshapes procurement compliance requirements.
Robotic-assisted surgical systems are bifurcating the orthopedic procedure market. High-volume joint replacement centers in Seoul's Gangnam district adopt da Vinci and ROSA platforms for precision alignment. This technology is bifurcating patient segmentation into premium robotic-assisted bundles versus conventional open-procedure pricing tiers.
MFDS pharmaceutical and device standards now mandate blockchain-based implant traceability for all tourist-facing procedures. Hospitals must register device serial numbers to patient passports before discharge. Severance Hospital and affiliated clinics have reconfigured procurement workflows to comply, shifting supplier relationships toward MFDS-registered distributors with integrated serialization capabilities.
Patients from the Middle East and Southeast Asia increasingly book complete surgical packages through dedicated medical travel agencies rather than direct hospital contact. These intermediaries aggregate interpreter coordination, accommodation, and post-operative nursing into flat-fee bundles. This channel consolidation is most visible in Dubai and Bangkok origin markets where agency certification by the Korean Ministry of Health and Welfare serves as a quality signal displacing direct-to-hospital research.
South Korea Medical Tourism Market Segmentation
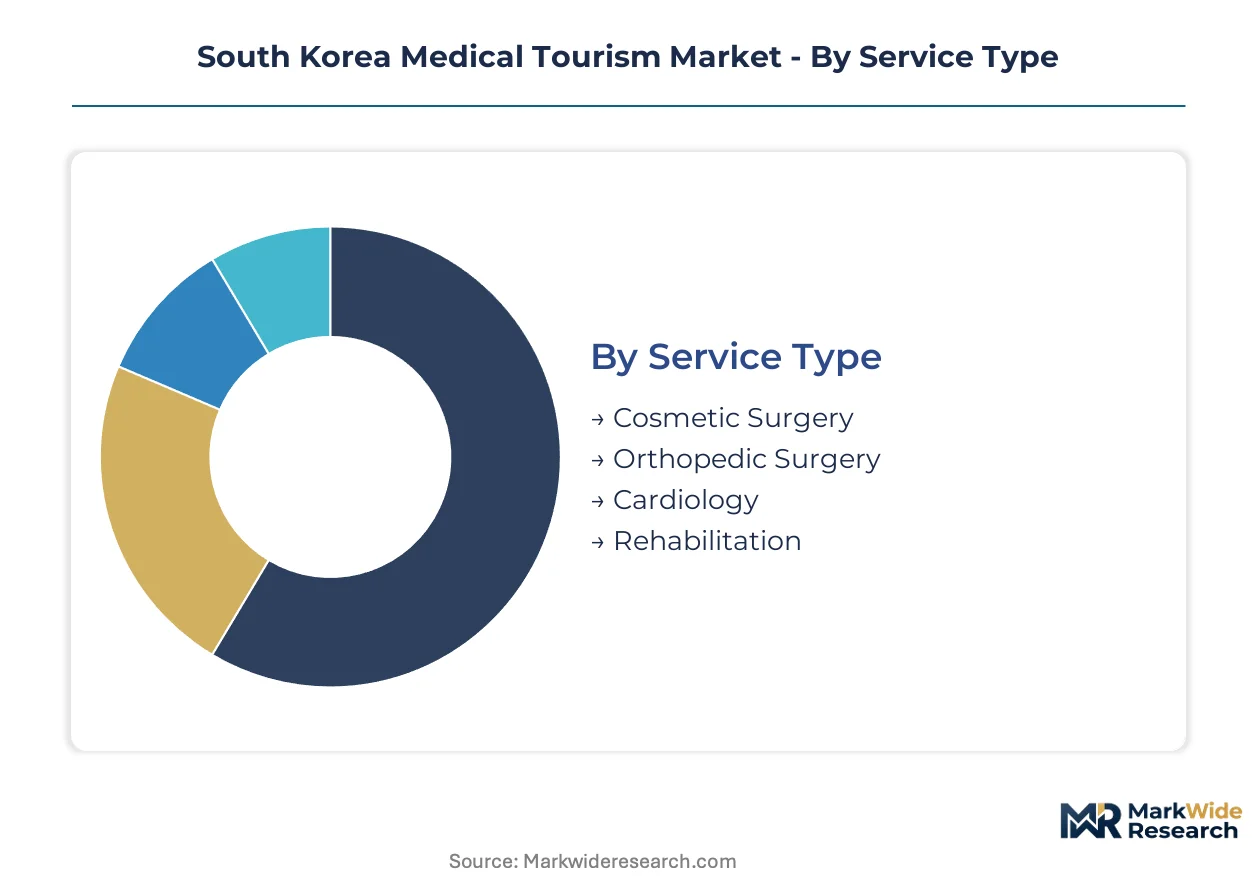
Segmentation in South Korea medical tourism reveals how patient origin, procedure complexity, and financing source determine facility investment priorities. Service mix and accommodation tier directly influence KOIHA accreditation requirements and government promotional eligibility.
Service Type:
Substitution pressure from Thailand and Singapore cosmetic clinics forces Korean providers to differentiate through technology density and bundled recovery protocols.
- Cosmetic Surgery:Procedures incorporate 3D imaging pre-consultation and minimally invasive techniques that compress recovery timelines. Demand concentrates among Southeast Asian patients from Vietnam and Indonesia seeking price positioning below Singapore benchmarks, with MFDS device registration timelines determining which clinics maintain preferred status.
- Orthopedic Surgery:Bundled knee and hip replacement packages leverage robotic-assisted surgical systems for precision alignment. Samsung Medical Center and Severance Hospital anchor high-complexity cases from Central Asian markets with limited domestic tertiary capacity, with KOIHA accreditation tiers filtering referral volume toward Gangnam-certified facilities.
- Cardiology:Integrated diagnostic campuses support interventional procedures requiring extended monitoring protocols.
- Rehabilitation:Post-surgical recovery stays extend average trip duration and accommodation spend, creating white space for medically supervised wellness resorts outside Seoul's core district.
Orthopedic Surgery retains volume leadership; Rehabilitation holds the steepest expansion curve.
End User:
Cost tier stratification separates sovereign-funded referrals from self-pay segments with divergent price sensitivity and service expectations.
- International Patients:Origin markets bifurcate between Middle Eastern patients arriving through bilateral health agreements and Southeast Asian patients booking via Dubai and Bangkok-based medical travel agencies. Korean Ministry of Health and Welfare certification of these intermediaries displaces direct-to-hospital research.
- Local Residents:Domestic demand for premium cosmetic and orthopedic procedures competes for surgeon capacity during peak international booking seasons.
- Insurance Companies:Sovereign funds from Kazakhstan and Uzbekistan pre-qualify patient referrals for bundled orthopedic packages.
- Healthcare Facilitators:Agency channel consolidation aggregates interpreter coordination, accommodation, and post-operative nursing into flat-fee bundles.
International Patients dominate revenue contribution; Healthcare Facilitators are gaining share fastest through channel consolidation.
Accommodations:
Supply concentration near Gangnam-certified hospitals determines patient routing and average trip cost structure.
- Hotels:Premium hospitality infrastructure clusters near specialized clinics, with standard hotel capacity constraints emerging during peak seasonal demand.
- Guest Houses:Budget alternatives serve extended-stay rehabilitation patients with limited accommodation spend.
- Clinics:Dedicated foreign patient wards within KOIHA-accredited facilities meet interpreter and international billing requirements.
- Wellness Centers:Medically supervised recovery properties outside Seoul's core district address post-surgical stay demand.
Hotels maintain the dominant share; Wellness Centers show the strongest momentum from rehabilitation segment expansion.
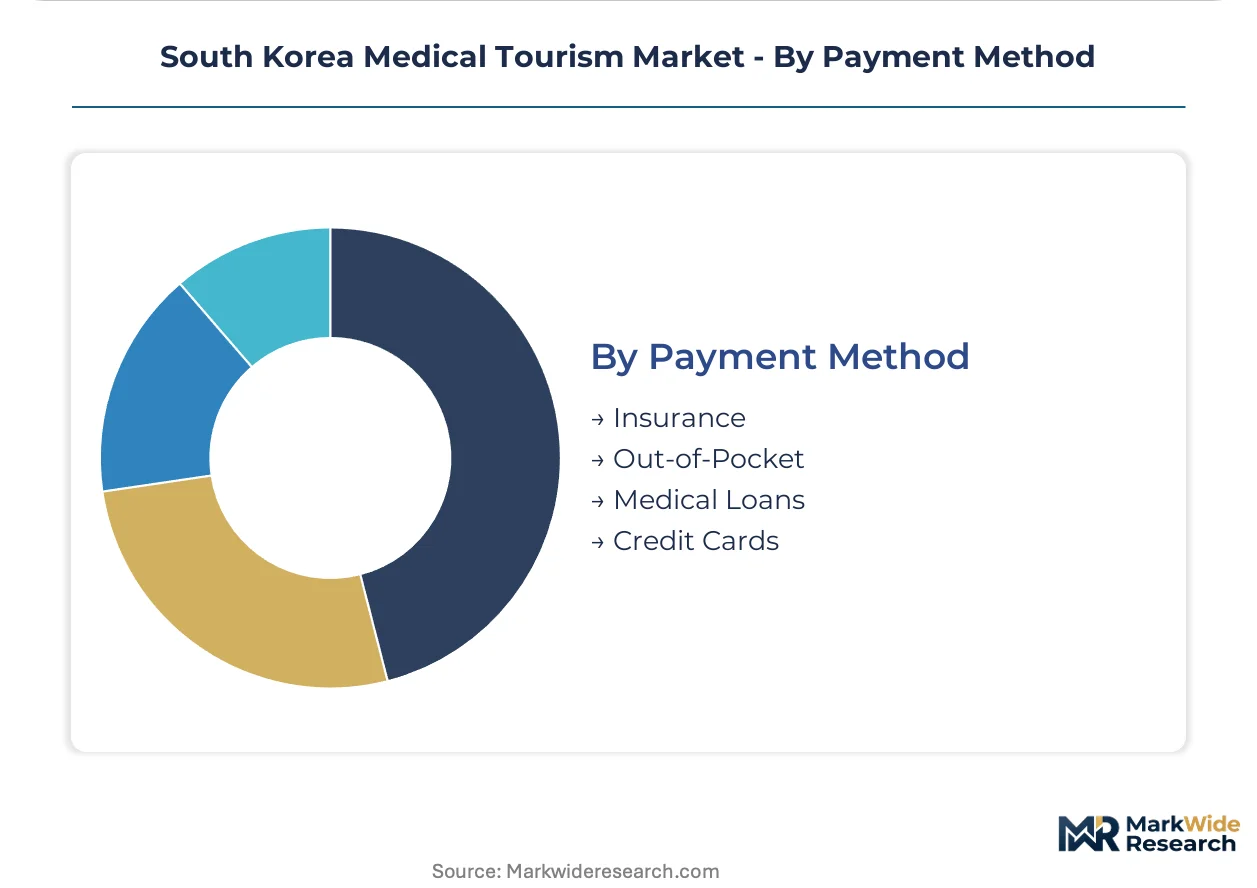
Payment Method:
Financing source maturity separates established insurance channels from emerging medical loan products with varying approval friction.
- Insurance:Bilateral health agreements with Middle Eastern governments generate covered referrals for orthopedic bundled packages.
- Out-of-Pocket:Self-pay cosmetic surgery from Southeast Asian markets drives volume during currency-favorable periods.
- Medical Loans:Financing products extend addressable segments with limited liquid savings but stable income profiles.
- Credit Cards:Point-of-sale payment processing integrates with international billing systems at KOIHA-accredited facilities.
Insurance anchors the largest transaction value; Medical Loans demonstrate the most rapid uptake among price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS promotional frameworks and KOIHA accreditation tiers are concentrating inbound patient flow into specific metropolitan clusters across South Korea. The analysis examines how sub-regional infrastructure specialization shapes competitive positioning within the national medical tourism ecosystem.
Seoul Capital Area
Gangnam district anchors the highest concentration of KOIHA-accredited cosmetic and orthopedic clinics serving Southeast Asian and Middle Eastern patients. Samsung Medical Center and Severance Hospital leverage integrated diagnostic campuses for complex oncology and cardiovascular cases from Central Asia. MFDS device registration timelines determine which facilities maintain preferred status under bilateral health agreements.
Busan-Ulsan
Port-city logistics infrastructure supports medical traveler arrivals from Japan and coastal China seeking dental and ophthalmology procedures. The region competes through lower accommodation costs compared to Seoul while maintaining KOIHA certification standards. Local hospital networks coordinate with Korean Air for dedicated patient concierge routing through Gimhae International Airport.
Daegu-Gyeongbuk
Specialized spine and joint reconstruction units in this southeastern cluster attract patients from Mongolia and Russian Far East regions with limited tertiary capacity. The Ministry of Health and Welfare designates select facilities for government-backed promotional campaigns targeting Central Asian markets. Rehabilitation segment expansion creates demand for medically supervised recovery properties outside dense urban cores.
Daejeon-Sejong
Administrative proximity to national regulatory bodies accelerates MFDS approval processes for aesthetic implants and orthopedic devices used in tourist-facing procedures. Research hospital networks in this central region pilot blockchain-based implant traceability systems mandated for foreign patient procedures. KOIHA compliance investments filter smaller operators from premium positioning.
Gwangju-Honam
Southwestern regional hospitals compete on bundled pricing for standard orthopedic and cosmetic procedures, targeting price-sensitive segments from Vietnam and Indonesia. Guest house accommodation infrastructure supports extended-stay rehabilitation patients with limited hospitality spend. The Korean Ministry of Health and Welfare certification programs for medical travel agencies channel pre-qualified referrals to accredited facilities.
South Korea Medical Tourism Market Key Industry Players
Player mix skews toward integrated hospital-hotel conglomerates and specialized clinic chains with dedicated foreign patient infrastructure. Market structure concentrates around tiered accreditation levels that determine government promotional eligibility and inbound referral priority. Two strategic archetypes dominate: flagship tertiary hospitals with comprehensive diagnostic-surgical campuses, and boutique cosmetic clinics with technology-dense pre-consultation platforms. Competitive moves center on KOIHA tier advancement and bilateral health agreement negotiation with sovereign insurance funds.
Within the flagship hospital tier, Samsung Medical Center and Severance Hospital anchor high-complexity case positioning through integrated specialty units. Korean Air occupies a distinct logistics-archetype role controlling medical traveler routing through dedicated concierge services. Among hospitality-integrated operators, Hilton Hotels and Taj Hotels represent international brand penetration near Gangnam-certified clinic clusters. The Korea Tourism Organization and Ministry of Health and Welfare function as regulatory-promotional anchors shaping accreditation standards and bilateral referral frameworks rather than direct service provision.
| Leading Market Players |
|---|
| Hilton Hotels |
| VIP Travel Korea |
| Samsung Medical Center |
| Korea Tourism Organization |
| Bookimed |
| Severance Hospital |
| Taj Hotels |
| Ministry of Health and Welfare |
| Korean Air |
| Others |
Cost & Logistics Intelligence
Bundled surgical package contracts lock in both procedure access and cost visibility for Middle Eastern sovereign funds and Southeast Asian medical travel agencies negotiating multi-patient volume commitments with Seoul's Gangnam-certified facilities. These agreements concentrate pricing power with KOIHA-accredited hospitals while filtering smaller clinics from premium positioning through MFDS device registration and interpreter service mandates.
Pricing Analysis
Certification level (KOIHA tier/MFDS-grade) creates the primary spread between premium robotic-assisted orthopedic bundles and conventional open-procedure tiers. Three-tier pricing structure across premium, standard, and economy levels segments patients by procedure complexity and accommodation tier, with self-pay Southeast Asian cosmetic patients exhibiting highest price sensitivity. Cost compression in standard-tier cosmetic procedures is intensifying because Thai and Singapore clinics compete on bundled recovery pricing. Sovereign-funded Central Asian orthopedic referrals through bilateral health agreements show lowest price sensitivity due to comprehensive coverage.
Supply Chain Analysis
Korean Air and Asiana's dedicated patient concierge routing constitutes a logistics chokepoint that concentrates medical traveler flow through Incheon and Gimhae International Airports. Implant and device supply draws from domestic MFDS-registered distributors, US FDA-cleared manufacturers, and EU CE-marked producers, with blockchain-based serialization now mandatory for tourist-facing procedures. Single-source vulnerability runs through concentrated airline capacity during peak seasonal demand. Distribution runs through Ministry of Health and Welfare-certified medical travel agencies in Dubai and Bangkok that aggregate interpreter coordination, accommodation, and post-operative nursing into flat-fee patient bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated medical travel agencies that aggregate patient volume and negotiate preferred rates with accredited hospitals, fragmenting direct-to-hospital booking channels. This consolidation demands strategic repositioning across stakeholder archetypes.
For Market Incumbents: Fortify KOIHA tier positioning through accelerated MFDS device registration and dedicated foreign patient ward capacity expansion in Seoul's Gangnam district. Incumbent hospitals must deepen interpreter certification pipelines to offset agency channel consolidation threatening direct patient relationships. Vertical integration into medically supervised wellness resorts outside dense urban cores captures rehabilitation segment white space. For New Entrants and Emerging Players: Anchor in Daegu-Gyeongbuk's specialized spine and joint reconstruction corridor targeting underpenetrated Mongolian and Russian Far East markets with limited domestic tertiary capacity. New clinic operators should pursue KOIHA accreditation for government-backed promotional eligibility while pricing bundled packages below Gangnam benchmarks. A direct sovereign fund contracting angle bypasses agency channel gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward hospitality-integrated clinic conglomerates with established bilateral health agreement relationships and scalable interpreter infrastructure. Long-term viability hinges on MFDS regulatory compliance capabilities and Ministry of Health and Welfare promotional framework access. The signal to monitor is shifting bilateral health agreement coverage toward rehabilitation and wellness segments.| Strategic Initiative | Industry Significance |
|---|---|
| KOIHA Tier Advancement | Unlocks government-backed medical tourism promotion and inbound referral priority from sovereign funds. |
| Robotic Surgical Platform Investment | Enables premium orthopedic bundles that differentiate from Thai and Singapore competitors. |
| Interpreter Certification Pipeline | Addresses MFDS-mandated staffing shortages that constrain hospital expansion timelines. |
| Bilateral Health Agreement Negotiation | Secures pre-qualified patient referrals from Kazakhstan and Uzbekistan sovereign insurance funds. |
| Wellness Resort Development | Captures rehabilitation segment expansion extending average trip duration and accommodation spend. |
Research Approach
A spread of perspectives from hospital international patient coordinators, medical travel agency operators, MFDS regulatory affairs specialists, and sovereign fund health attachés converged on the working assumptions shaping procedure volume and pricing dynamics. Primary fieldwork combined structured interviews with secondary validation against KOIHA accreditation databases, Ministry of Health and Welfare promotional framework disclosures, and MFDS device registration records. Bottom-up patient flow estimates from origin market agencies triangulated with top-down hospital capacity assessments across Seoul, Busan, and Daegu metropolitan clusters.
Segmentation dimensions modeled include service type complexity tier, patient origin market, financing source, and accommodation category across the projection horizon. CAGRs were derived from procedure volume trajectories, average revenue per patient, and trip duration expansion in rehabilitation segments. Forecast inputs incorporated bilateral health agreement negotiation timelines, KOIHA accreditation tier advancement rates, and MFDS regulatory compliance cost burdens.
Decision-makers should treat outputs as directional under stable bilateral health agreement coverage and KOIHA accreditation tier structures; material deviation in sovereign fund reimbursement policies or regulatory tightening would warrant model refresh. Practitioners should keep alternative scenarios live as Middle Eastern and Southeast Asian patient origin market preferences and currency conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Outbound Medical Tourism Services Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
Dental Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
Medical Tourism Market