
 Spain Medical Tourism Market | 2026-2036
Spain Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Medical Tourism Market Insights
Aftercare service revenue is fragmenting across Spain's private hospital networks as international patients extend stays for rehabilitation and follow-up consultations. Fundació Puigvert leverages its urology specialization to capture recurring post-surgical visits from European patients. Sant Joan de Déu-Barcelona Children's Hospital anchors pediatric medical travel through dedicated family accommodation programs. Barnaclínic competes on boutique surgical volumes with concentrated cosmetic and orthopedic offerings.
Spain medical tourism encompasses cross-border travel to access private healthcare services spanning elective surgery, specialized diagnostics, and wellness recovery programs, typically priced below Northern European equivalents while maintaining Joint Commission International accreditation standards. Cosmetic surgery and dental treatments lead service-type revenue as British and Irish patients seek cost-differentiated aesthetic procedures. Fertility treatments represent the fastest-growing segment as Spanish legislation permits broader assisted reproduction access than several neighboring jurisdictions. Orthopedic procedures within treatment-type categories carry premium pricing due to robotic surgical infrastructure investments and compressed recovery protocols.
Spain's Ministry of Health coordinates with regional authorities in Catalonia and Andalusia to license international patient units, while the country's national pharmaceutical regulator oversees medical device standards for implantable materials used in tourist-facing procedures. EU cross-border healthcare directives shape reimbursement frameworks for insured visitors from member states. Stakeholders must monitor evolving autonomous community licensing requirements as Madrid and Valencia expand dedicated medical travel infrastructure.
Market Dynamics
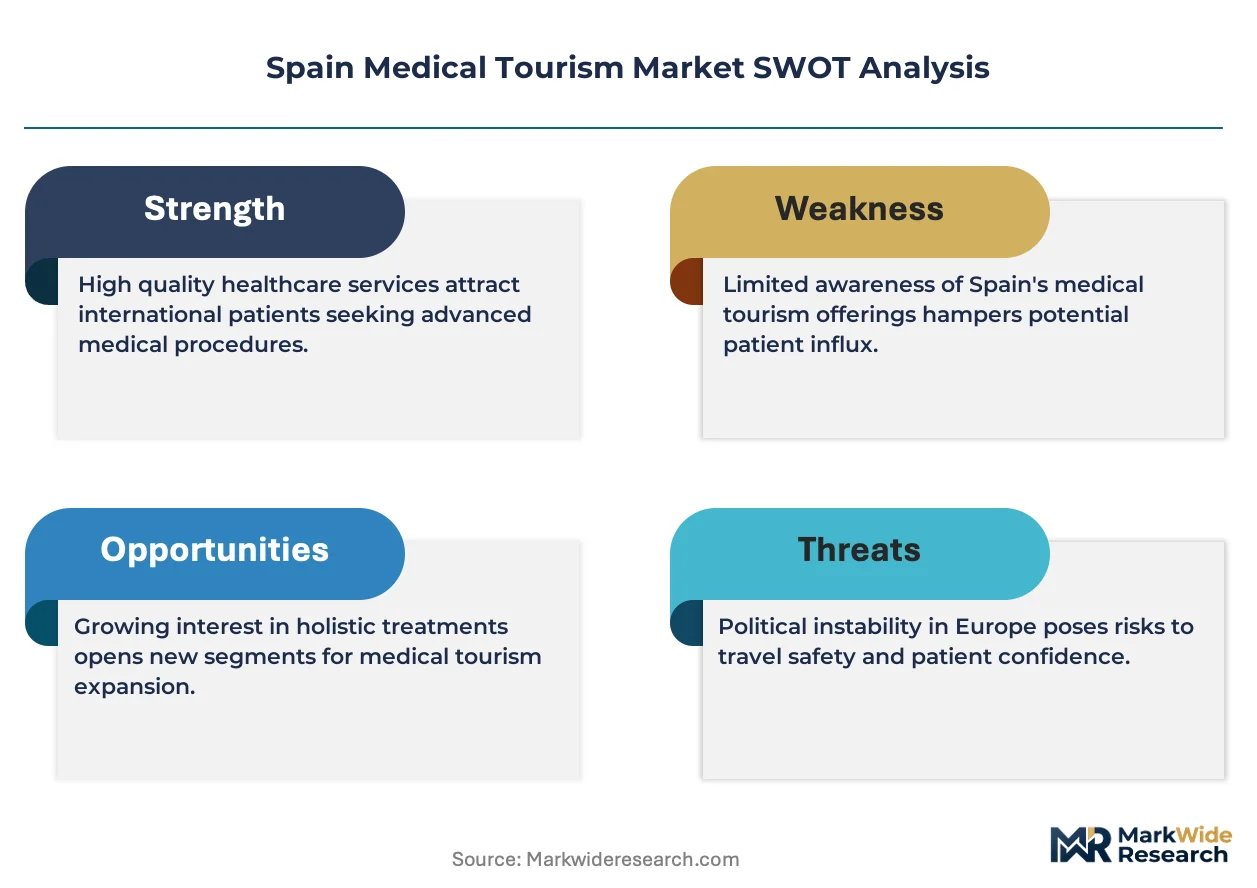
Autonomous community licensing fragmentation creates divergent entry pathways for private hospitals seeking international patient accreditation across Spain's seventeen regions. Madrid and Catalonia maintain stricter facility certification standards than Andalusia or Valencia, forcing operators to maintain multiple compliance protocols.
Growth Catalysts
- EU Cross-Border Healthcare Directive:Insured EU citizens claim reimbursement for private Spanish procedures, eliminating upfront cost barriers for British and Irish patients seeking orthopedic and cosmetic interventions.
- Robotic surgical infrastructure:Barcelona and Madrid hospital clusters deploy da Vinci systems for compressed recovery protocols, attracting German and French patients seeking faster return-to-work timelines.
- Fertility tourism:Spanish legislation permits broader assisted reproduction access than Italy or France, driving inbound volume from jurisdictions with restrictive donor anonymity laws.
Market Restraints
- Regional regulatory fragmentation:Each autonomous community maintains distinct licensing requirements for international patient units, multiplying compliance costs for multi-site operators.
- Post-Brexit reimbursement uncertainty:British patients face evolving EHIC replacement scheme coverage gaps, creating payment friction for NHS-funded elective procedures in Spain.
- Specialized nursing shortages:Rehabilitation and post-surgical care units in Barcelona report insufficient bilingual staff capacity to match rising Northern European patient volumes.
Strategic Opportunities
- Andalusian wellness corridor:Costa del Sol hospitals underutilized for medical travel could capture German retirement-community demand through dedicated orthopedic rehabilitation packages.
- Telemedicine integration:Remote pre-consultation and post-operative monitoring extends patient relationship duration beyond physical stays, creating recurring revenue streams.
- Valencia infrastructure expansion:Regional health authority incentives for international patient units offer first-mover advantages in an underpenetrated Mediterranean hub.
Industry Challenges
- Joint Commission International accreditation timelines:Madrid hospitals report eighteen-month certification delays, constraining capacity expansion for premium-priced service tiers.
- Legacy IT interoperability:Autonomous community health data systems lack standardized interfaces with Northern European electronic health record platforms, complicating pre-arrival diagnostics.
- Rehabilitation facility scaling:Extended-stay aftercare demand outpaces physical therapy center construction in Barcelona's urban core, forcing patient dispersal to satellite locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Medical Tourism Market |
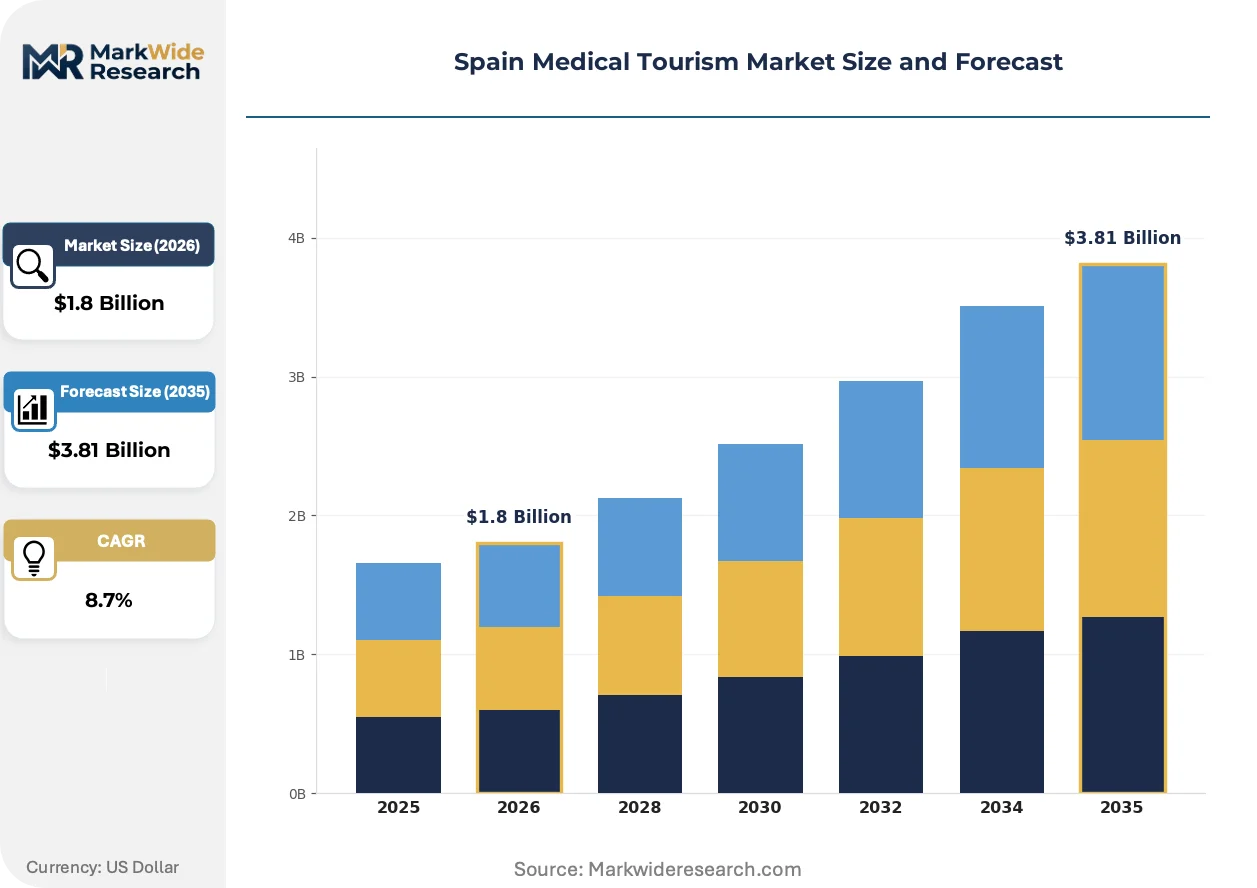
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Dental Treatments, Cardiac Surgery, Fertility Treatments End User: Individuals, Couples, Families, Corporates Treatment Type: Orthopedic Procedures, Neurological Care, Oncology, Transplants Accommodations: Luxury Hotels, Health Resorts, Affordable Lodging, Short-term Rentals |
| Companies Covered | Fundació Puigvert, Sant Joan de Déu-Barcelona Children’s Hospital, Barnaclínic, Centro de Oftalmología Barraquer, Dexeus, Centro Médico Teknon, Hospital Quirón Barcelona, Vithas Xanit International Hospital, HM Hospitals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Medical Tourism Market Trends and Innovations
Telemedicine platforms are compressing pre-arrival consultation cycles while robotic surgical systems redefine recovery expectations for cross-border patients. These shifts alter how Spanish hospitals structure international patient units and price bundled procedure packages.
Remote patient monitoring technology is digitizing pre-operative assessment workflows, enabling Madrid hospitals to complete diagnostic workups before patient arrival. German health insurers now mandate virtual consultations for covered cross-border procedures, accelerating platform adoption. This compression of front-end logistics is digitizing traditional medical travel agency functions into direct hospital-patient channels.
Spain's Ministry of Health coordinates with regional authorities to harmonize autonomous community licensing standards for international patient units under emerging national framework guidelines. The industrial consequence is reduced compliance redundancy for multi-regional operators while preserving Catalonia's stricter facility requirements. Private hospital groups with Barcelona-Madrid-Valencia footprints face phased adaptation timelines, with Madrid facilities adjusting first.
British and Irish patients increasingly book procedures through hospital-direct digital platforms rather than traditional medical travel intermediaries, unbundling accommodation and transport from clinical service pricing. This channel shift pressures Barcelona operators to develop in-house concierge capabilities or cede margin to specialized booking platforms. The transformation is most visible in cosmetic surgery segments, where price transparency demands drive direct-to-consumer marketing investments.
Spain Medical Tourism Market Segmentation
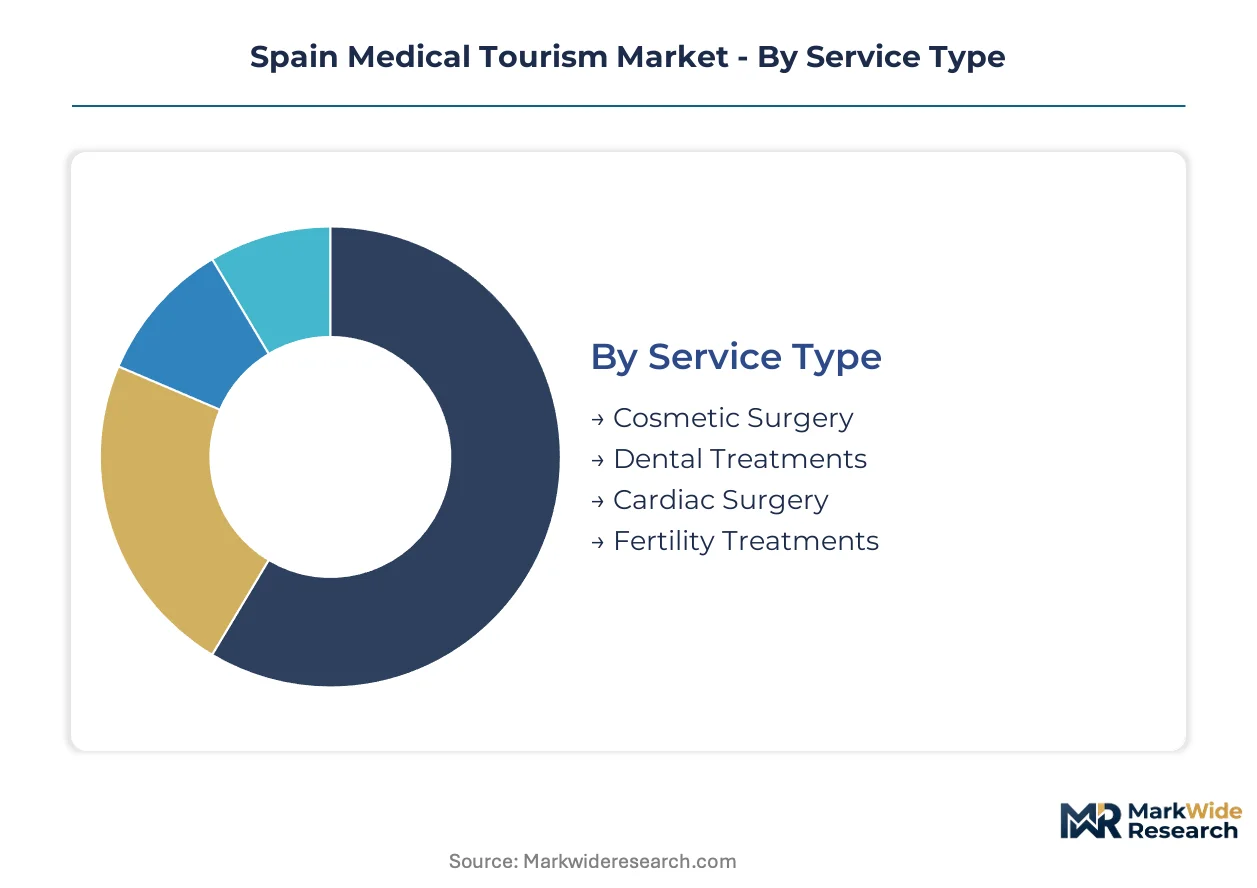
Medical tourism in Spain fragments across four distinct dimensions that shape how private hospitals configure their international patient units. Each segmentation axis carries different margin profiles, regulatory requirements, and geographic concentration patterns that operators must navigate across autonomous communities.
Service Type:
Cost tier differentiation separates high-acuity surgical interventions from outpatient aesthetic procedures, with pricing power varying dramatically by clinical complexity and recovery duration.
- Cosmetic Surgery:Elective aesthetic procedures including rhinoplasty, breast augmentation, and body contouring attract British and Irish patients seeking cost arbitrage against domestic private clinics. Demand concentrates in Barcelona and Madrid where boutique surgical centers cluster near international airports.
- Dental Treatments:Implantology, orthodontics, and full-mouth rehabilitation represent high-frequency, short-stay visits with minimal aftercare requirements. Costa del Sol dental clinics capture German and Scandinavian retirement-community patients through package pricing that bundles accommodation with clinical services.
- Cardiac Surgery:Coronary artery bypass grafting and valve replacement procedures leverage Spain's Joint Commission International-accredited cardiac centers. Madrid hospital clusters attract complex cases from Eastern European markets where specialized cardiac infrastructure remains limited.
- Fertility Treatments:In-vitro fertilization, egg freezing, and donor-assisted reproduction benefit from Spanish legislation permitting broader access than Italy or France. Barcelona fertility clinics report the steepest expansion trajectory as Northern European patients circumvent restrictive donor anonymity laws in their home jurisdictions.
Cosmetic surgery holds installed capacity. Fertility treatments are rotating up the share rankings.
End User:
Customer type determines booking channel preferences, accommodation requirements, and post-procedure support intensity that hospitals must provision.
- Individuals:Solo travelers pursuing single-procedure interventions drive the highest volume of cosmetic and dental bookings. Barcelona operators report shorter lead times for individual patients booking through direct digital platforms rather than medical travel intermediaries.
- Couples:Partners traveling together for fertility treatments or mutual cosmetic procedures generate extended-stay revenue through companion accommodation packages. Madrid fertility clinics structure bundled pricing that captures both clinical and lodging margins.
- Families:Pediatric medical travel anchored by Sant Joan de Déu-Barcelona Children's Hospital requires dedicated family accommodation programs and multilingual care coordination. Demand concentrates in specialized pediatric oncology and rare disease diagnostics.
- Corporates:Employer-sponsored wellness programs and executive health screenings represent emerging volume through occupational health contracts. Andalusian health resorts underutilized for medical travel are capturing German corporate wellness demand through dedicated rehabilitation packages.
Individual travelers dominate current volume. Corporate contracts are climbing the fastest as occupational health budgets expand cross-border coverage.
Treatment Type:
Clinical complexity tiering separates routine interventions from resource-intensive specialties that require robotic infrastructure and compressed recovery protocols.
- Orthopedic Procedures:Hip and knee replacements, spinal fusion, and sports medicine interventions carry premium pricing due to da Vinci robotic surgical systems and accelerated rehabilitation protocols. Barcelona and Madrid hospital clusters attract German and French patients seeking faster return-to-work timelines.
- Neurological Care:Deep brain stimulation, epilepsy surgery, and complex spine interventions leverage Spain's specialized neurosurgical centers. Demand concentrates in Madrid where academic medical centers maintain research partnerships with Northern European referral networks.
- Oncology:Proton therapy, precision radiotherapy, and experimental immunotherapy protocols attract patients from markets with limited specialized cancer infrastructure. Valencia's emerging medical travel infrastructure targets oncology volume through regional health authority incentives.
- Transplants:Organ transplantation remains restricted by Spanish national organ allocation protocols that prioritize domestic patients, limiting medical tourism applicability to living-donor procedures and pre-transplant evaluation services.
Orthopedic procedures hold installed capacity. Neurological care is gaining share fastest as robotic surgical infrastructure expands.
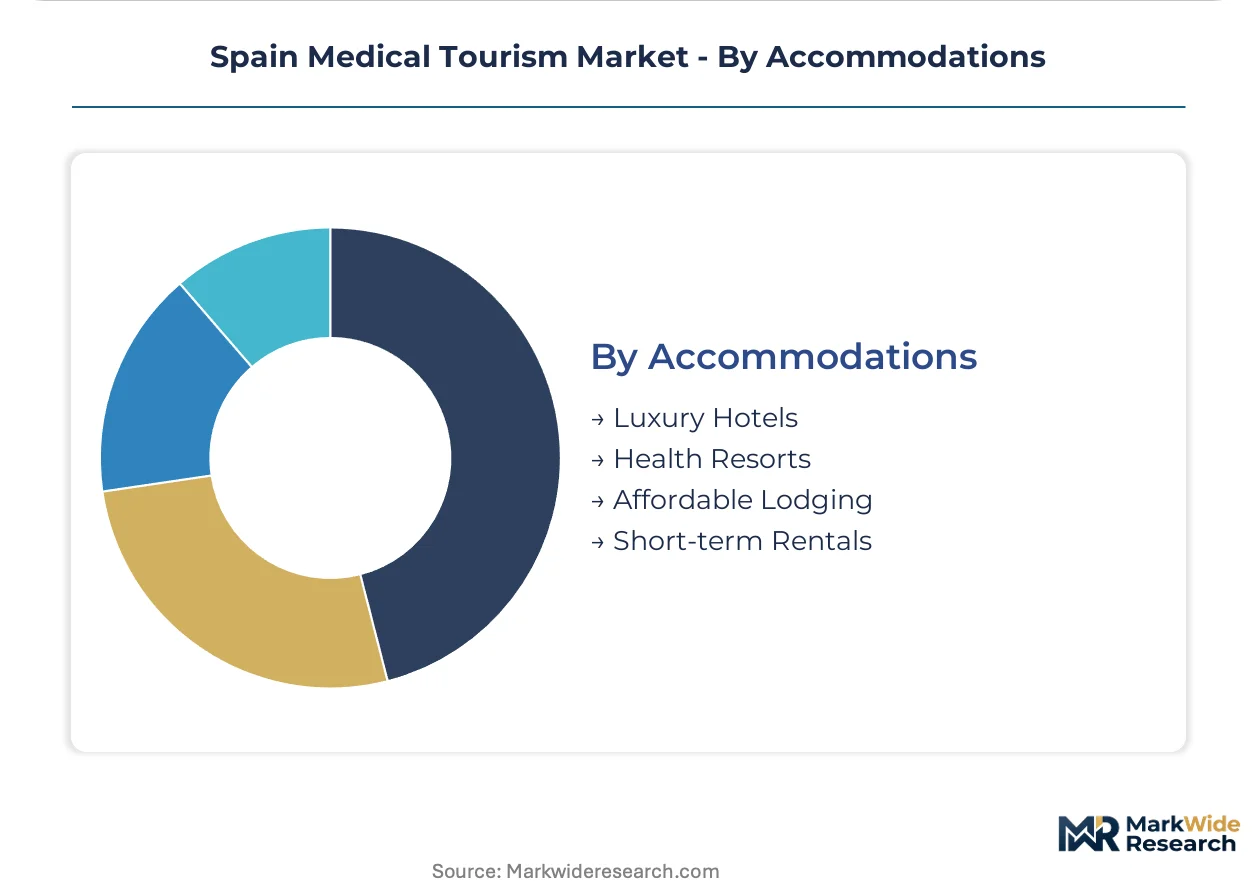
Accommodations:
Recovery environment tiering shapes patient dispersal patterns and aftercare service revenue capture across Spain's urban and coastal geographies.
- Luxury Hotels:Five-star properties adjacent to Barcelona and Madrid hospital clusters cater to high-net-worth patients seeking concierge-level privacy and dedicated nursing support. Premium pricing captures post-discharge monitoring before international travel clearance.
- Health Resorts:Medicalized wellness facilities on the Costa del Sol and Balearic Islands integrate rehabilitation services with thermal therapies and nutritional programming. German retirement-community demand drives occupancy for orthopedic recovery packages.
- Affordable Lodging:Mid-range hotels and serviced apartments near public transport corridors serve cost-sensitive dental and cosmetic patients with minimal aftercare requirements. Valencia's underpenetrated market offers first-mover advantages in budget-tier accommodation partnerships.
- Short-term Rentals:Apartment platforms unbundle accommodation from clinical pricing as British and Irish patients increasingly book procedures through hospital-direct channels. Barcelona operators face pressure to develop in-house concierge capabilities or cede margin to specialized booking platforms.
Luxury hotels hold installed capacity. Health resorts are rotating up the share rankings as extended-stay rehabilitation demand outpaces urban core capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
British and Irish patients consume Spanish medical tourism through direct digital booking channels, while German and French demand concentrates on robotic orthopedic interventions with compressed recovery timelines. This consumption-mix differential shapes how autonomous communities configure international patient units across Spain's seventeen regions.
Madrid
Corporate wellness contracts and complex cardiac procedures drive Madrid's medical tourism volume through employer-sponsored executive health programs. The regional health authority maintains stricter facility certification standards than southern autonomous communities, forcing operators to maintain dedicated compliance protocols. Hospital clusters in the capital attract Eastern European cardiac patients through Joint Commission International-accredited centers.
Catalonia
Barcelona anchors pediatric medical travel and fertility tourism through specialized clinical infrastructure unavailable in neighboring jurisdictions. Catalan health laws regulate private facilities under autonomous community frameworks that exceed national minimum standards. The city's hospital clusters capture recurring post-surgical visits from European urology patients through dedicated aftercare programs.
Andalusia
Costa del Sol dental clinics and orthopedic rehabilitation packages capture German and Scandinavian retirement-community demand through bundled accommodation pricing. Andalusian licensing requirements for international patient units remain less stringent than Madrid or Catalonia, reducing entry barriers for new operators. Health resorts in Málaga province integrate thermal therapies with post-surgical recovery programming.
Valencia
Regional health authority incentives for international patient units are attracting first-mover investment in an underpenetrated Mediterranean hub. Valencia's emerging medical travel infrastructure targets oncology volume through proton therapy capacity expansion. The city's mid-range accommodation partnerships serve cost-sensitive dental and cosmetic patients with minimal aftercare requirements.
Basque Country
Specialized neurosurgical centers in Bilbao and San Sebastián leverage research partnerships with Northern European referral networks for complex spine interventions. Basque health regulations coordinate with Spain's Ministry of Health on autonomous community licensing harmonization initiatives. The region's academic medical centers attract German patients seeking experimental immunotherapy protocols unavailable domestically.
Spain Medical Tourism Market Competitive Landscape
Capability concentration sits with specialized single-site institutions; scale advantage sits with multi-regional hospital groups operating across autonomous communities. The market structures around three tiers: boutique surgical centers capturing premium cosmetic volumes, academic medical centers anchoring complex pediatric and neurological care, and diversified hospital groups spreading compliance costs across multiple regional licenses. Dominant competitive moves include telemedicine platform integration for pre-arrival consultation compression and dedicated international patient unit accreditation pursuit.
Within the specialized-institution tier, Fundació Puigvert and Sant Joan de Déu-Barcelona Children's Hospital exemplify archetype positioning through concentrated clinical focus. Fundació Puigvert occupies a position in urology specialization that generates recurring European patient flows. Sant Joan de Déu-Barcelona Children's Hospital anchors pediatric medical travel through dedicated family accommodation infrastructure. Barnaclínic represents the boutique surgical center archetype with concentrated cosmetic and orthopedic offerings.
| Leading Market Players |
|---|
| Fundació Puigvert |
| Sant Joan de Déu-Barcelona Children's Hospital |
| Barnaclínic |
| Centro de Oftalmología Barraquer |
| Dexeus |
| Centro Médico Teknon |
| Hospital Quirón Barcelona |
| Vithas Xanit International Hospital |
| HM Hospitals |
| Others |
Pricing and Supply Chain Analysis
Robotic surgical equipment concentration in Germany and the United States determines margin distribution across Spanish private hospital networks, with da Vinci system leasing costs compressing orthopedic procedure profitability while fertility clinics retain fuller pricing autonomy through lower capital intensity.
Pricing Analysis
Project-based bundled pricing dominates cosmetic and dental segments, while orthopedic interventions command long-term offtake structures tied to rehabilitation package duration. Price differentiation rests on Joint Commission International accreditation tier and robotic infrastructure availability, with Madrid hospitals capturing premium positioning. Cost compression in dental implantology intensifies as Costa del Sol clinics compete for German retirement-community volume. Individual travelers booking direct digital channels exhibit highest price sensitivity; corporate wellness contracts show lowest.
Supply Chain Analysis
Tariff exposure between the United States and European Union dominates medical device procurement risk for Spanish hospital networks sourcing implantable materials and robotic surgical components. Supply draws from Germany, Switzerland, and the United States for precision instrumentation, with consumables anchored in domestic Spanish manufacturing. Single-source vulnerability concentrates in da Vinci system maintenance contracts. Distribution runs through regional hospital procurement consortia coordinating across autonomous communities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's medical tourism market exhibits cyclical recovery characteristics as post-pandemic deferred elective procedures resurface and Northern European patients resume cross-border travel for cost-differentiated care.
For Market Incumbents: Insulate orthopedic revenue streams against German hospital cost-competitiveness improvements by deepening rehabilitation service bundling and securing exclusive health resort partnerships in Andalusia. Accelerate telemedicine platform integration to compress pre-arrival consultation cycles before competitors replicate Madrid hospital direct-to-consumer channels. Joint Commission International accreditation investment remains critical for premium tier defense. For New Entrants and Emerging Players: Valencia's underpenetrated Mediterranean hub offers first-mover positioning through regional health authority incentive programs for international patient unit licensing. Target oncology volume with proton therapy capacity expansion, leveraging less stringent facility certification timelines than Barcelona or Madrid. Corporate wellness contract acquisition through German occupational health brokers provides lower patient acquisition cost than individual cosmetic surgery marketing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed multi-regional hospital groups holding Madrid-Catalonia-Andalusia footprints and fragmented compliance cost structures. Long-term viability centers on autonomous community licensing harmonization reducing operational redundancy. Watch for Spanish Ministry of Health national framework guideline implementation as inflection signal for scaled platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Madrid hospitals compress pre-arrival diagnostics before German insurer mandates virtual consultation requirements. |
| Joint Commission International Accreditation | Barcelona operators secure premium orthopedic pricing through eighteen-month certification timeline navigation. |
| Health Resort Partnership Development | Andalusian Costa del Sol facilities capture extended-stay rehabilitation revenue from German retirement communities. |
| Corporate Wellness Contract Acquisition | Occupational health budgets expand cross-border coverage faster than individual cosmetic surgery volume. |
| Autonomous Community Licensing Harmonization | Multi-regional operators reduce compliance redundancy as Madrid adjusts first to emerging national framework guidelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with international patient unit directors, fertility clinic operations managers, and autonomous community health authority licensing officers; and secondary validation through hospital accreditation databases, EU cross-border healthcare directive implementation reports, and Spanish regional health expenditure disclosures. Bottom-up procedure volume estimates triangulated against top-down private healthcare revenue benchmarks across Catalonia, Madrid, Andalusia, and Valencia.
Forecast inputs span service type segmentation by clinical complexity tier, end user categorization by booking channel preference, treatment type differentiation by robotic infrastructure dependency, and accommodation tiering by recovery duration requirements. CAGRs derived from regression analysis against Northern European patient origin market economic indicators and Spanish regulatory implementation timelines. Modeled variables include EHIC replacement scheme coverage evolution and autonomous community licensing standardization pace.
The forecast holds incumbent behavior within observed patterns; aggressive telemedicine platform investment by German hospital networks or accelerated fertility tourism regulatory liberalization in France would shift outcomes. Material shifts in Spanish autonomous community licensing harmonization timelines or post-Brexit reimbursement scheme structural changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Outbound Medical Tourism Services Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market