
 Frozen Mushroom Market | 2026-2036
Frozen Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Mushroom Market Foresight
Multi-source procurement from certified cold chain suppliers is hardening as the dominant sourcing pattern across European and North American frozen mushroom buyers. Bonduelle Fresh Europe leverages its integrated cultivation and blast-freezing footprint to sustain year-round supply consistency for retail private labels. Monaghan Mushrooms anchors its competitive position through geographic dominance in Ireland and the UK, controlling distribution into British supermarkets and foodservice channels. Scelta Mushrooms differentiates through specialization in value-added frozen mushroom ingredients for industrial food manufacturers.
Frozen mushrooms comprise fresh fungi subjected to rapid blast freezing at temperatures below minus thirty degrees Celsius, a process that arrests enzymatic degradation and preserves cellular structure for extended shelf stability in commercial and institutional kitchens. The primary purpose centers on delivering consistent, labor-reduced ingredient inputs to food manufacturers and hospitality operators without seasonal supply volatility. Button mushroom and shiitake varieties occupy the mature volume core of the product type segmentation, while oyster mushrooms represent the fastest-growing category driven by vegan and umami-forward menu development across foodservice. Within application segmentation, ready-to-eat meals and institutional catering concentrate margin pools as these channels prioritize procurement efficiency and standardized portion control over per-unit cost minimization.
The EU F-Gas Regulation and FDA Hazard Analysis Critical Control Point framework govern refrigerant selection and pathogen control protocols across frozen mushroom processing and distribution networks, directly elevating compliance costs for facilities serving transatlantic markets. BIS cold chain standards in India and GB standards under SAMR oversight in China impose additional testing and labeling requirements that shape market access for exporters targeting Asian retail channels. Stakeholders must monitor evolving refrigerant phase-down schedules and emerging mycotoxin testing thresholds as these regulatory vectors increasingly determine facility investment priorities and geographic sourcing strategies.
Market Dynamics
Blast-freezing infrastructure consolidation across Central European processing clusters is compressing supplier margins while locking in procurement relationships with retail private-label programs. The EU F-Gas refrigerant phase-down is forcing capital redeployment toward ammonia-CO2 cascade systems, reshaping facility economics and geographic sourcing priorities.
Growth Catalysts
- Plant-based protein formulation demand:Food manufacturers are substituting frozen mushrooms for textured vegetable proteins in vegan ready-meal applications, pulling volume through industrial ingredient channels.
- EU F-Gas Regulation:Cold chain infrastructure upgrades are accelerating facility consolidation, favoring scaled processors with capital reserves for refrigerant system conversions.
- Shiitake cultivation expansion:Dutch and Polish growing operations are extending harvest windows through climate-controlled indoor systems, reducing seasonal supply volatility for frozen processors.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings in Germany and Poland directly compress blast-freezing margins, forcing pass-through pricing that weakens competitive position against ambient-stable alternatives.
- Input concentration risk:Fresh mushroom supply clusters heavily in Ireland and the Netherlands, creating geographic vulnerability to weather-driven crop failures and transport disruptions.
- Refrigerant transition timelines:The EU F-Gas phase-down schedule compresses payback periods for new freezing equipment, deterring mid-scale facility investments.
Strategic Opportunities
- Umami ingredient positioning:Frozen mushroom extracts are penetrating savory flavoring applications for snack and sauce manufacturers, opening industrial channels beyond whole-product sales.
- Indian cold chain development:BIS standards compliance investments by exporters are creating first-mover advantages in organized retail expansion across Mumbai and Delhi NCR.
- Ammonia-CO2 hybrid systems:Converging refrigeration technologies are enabling smaller processors to meet EU F-Gas requirements without full facility replacement, democratizing market access.
Industry Challenges
- Skilled refrigeration technician scarcity:EU F-Gas certification requirements are narrowing the available labor pool for system maintenance, extending equipment downtime during peak harvest windows.
- Mycotoxin testing protocol complexity:EFSA threshold updates are forcing processors to integrate rapid-detection laboratory capacity, stretching quality-control budgets.
- Legacy ERP integration friction:Cold chain traceability mandates are clashing with decades-old inventory management systems at family-owned processing facilities, delaying compliance certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Mushroom Market |
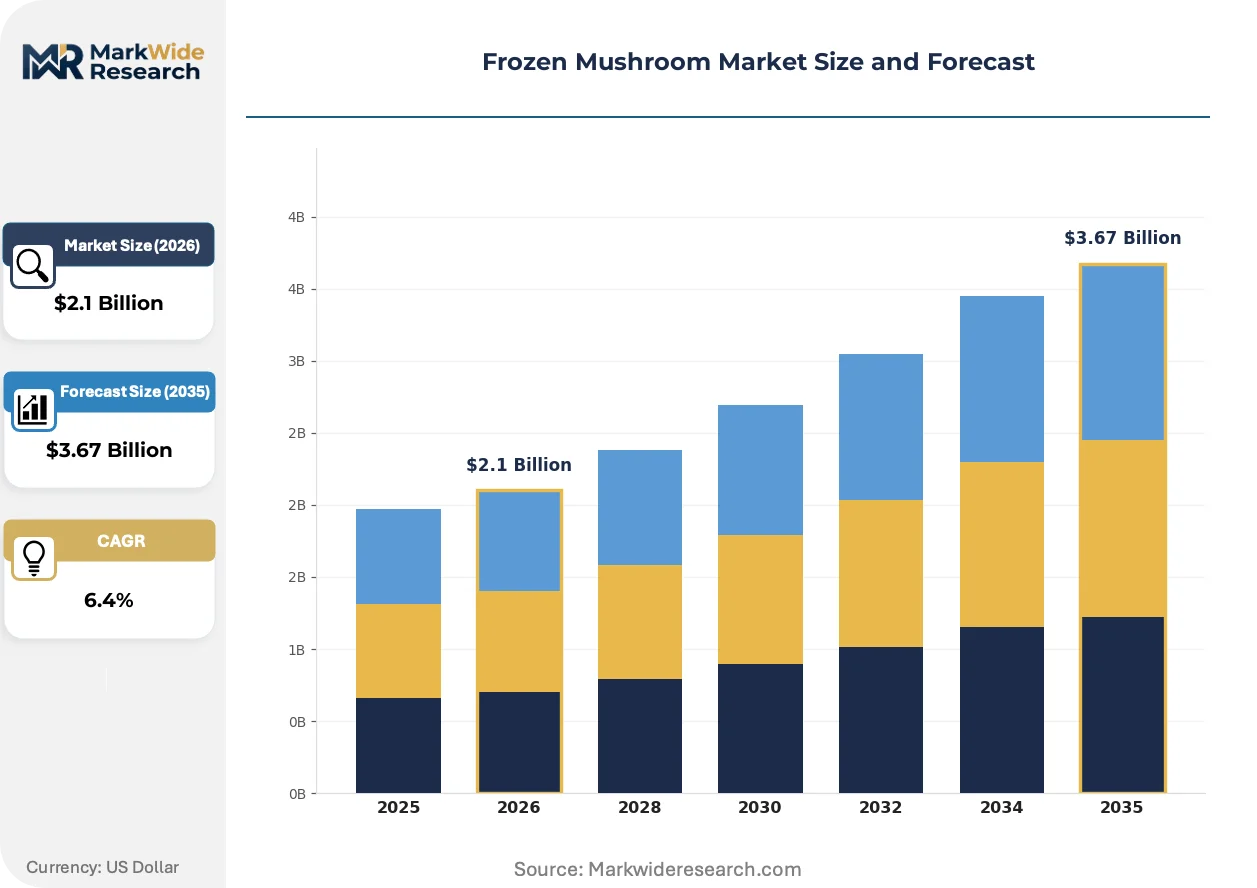
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Button Mushroom, Portobello, Shiitake, Oyster, Enoki, Morel Packaging Type: Vacuum Pack, Cryogenic Box, Plastic Tray, Modified Atmosphere, Paper Carton Application: Foodservice, Retail, Institutional Catering, Ready-to-Eat Meals, Hospitality End User: Supermarkets, Food Manufacturers, Restaurants, Catering Companies, Specialty Stores |
| Companies Covered | Bonduelle Fresh Europe, OKECHAMP S.A., Monaghan Mushrooms, Costa Group, Monterey Mushrooms, McCain Foods Limited, Scelta Mushrooms, Phillips Mushroom Farms, Big Mountain Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Mushroom Market Shifts & Advancements
Processing technology and regulatory compliance are converging to redefine competitive advantage in frozen mushroom supply chains. Three developments are actively restructuring how value is captured across cultivation, freezing, and distribution stages.
Individual quick freezing (IQF) tunnel technology with fluidized bed design is expanding into mid-scale European processors seeking to match multinational throughput without full automation investment. Ready-meal manufacturers in Germany and France are adopting IQF shiitake and oyster mushrooms at accelerating rates to reduce kitchen labor and standardize portion weights. The technology is expanding into private-label supply contracts previously reserved for blast-frozen bulk products, compressing price premiums for conventional freezing methods.
EU F-Gas Regulation phase-down schedules are mandating refrigerant conversions across processing facilities serving transatlantic markets. Industrial consequence includes accelerated capital deployment toward ammonia-CO2 cascade systems and the retirement of hydrofluorocarbon-dependent blast freezers. German and Dutch processors face the most compressed compliance timelines, driving facility consolidation and partnership structures with specialized refrigeration engineering firms.
Buyer consolidation among Central European retail private-label programs is concentrating procurement leverage and compressing supplier margins. Discounters in Poland and the Czech Republic are displacing traditional wholesale channels with direct processor relationships, extracting volume commitments in exchange for shelf access. This pattern is most visible in Germany, where Aldi and Lidl sourcing offices are standardizing frozen mushroom specifications across national and regional product lines.
Frozen Mushroom Market Segmentation
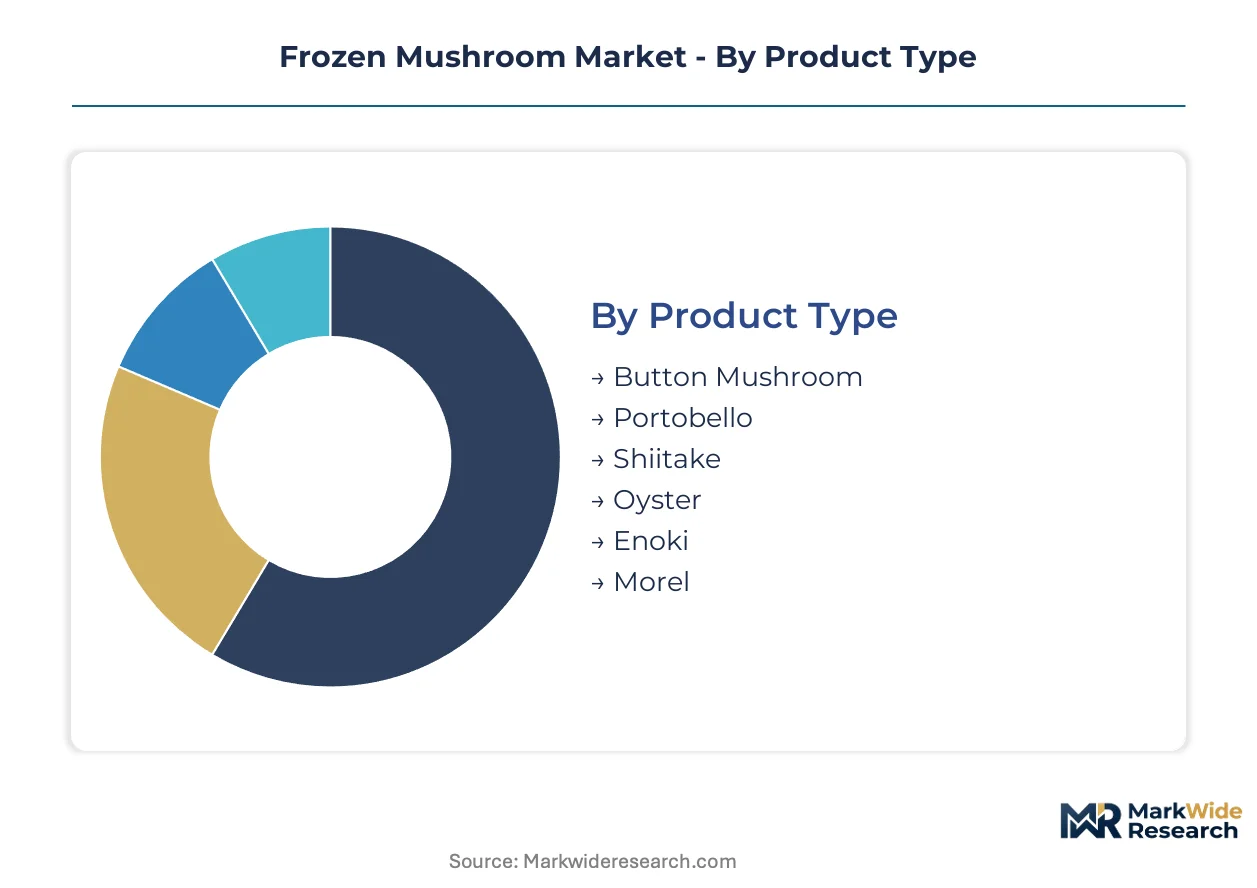
Segmentation in frozen mushrooms reveals how processing technology and distribution channels fragment value capture across the supply chain. Product type determines freezing protocol investment, while packaging and end-user configurations shape margin structures and geographic sourcing priorities.
Product Type:
Upgrade cycles in blast-freezing equipment are concentrating procurement leverage around varieties with the highest throughput and most stable year-round supply.
- Button Mushroom:Standard white and brown varieties dominate industrial freezing lines due to consistent sizing and high solids content that resists cell rupture during rapid temperature drop. German and Polish retail private-label programs anchor volume demand for standardized button mushroom cuts in 10kg bulk formats.
- Shiitake:Climate-controlled Dutch cultivation systems now deliver 12-month harvest windows, eliminating the seasonal supply volatility that previously constrained frozen shiitake availability. Umami-forward positioning in vegan ready-meal formulations is accelerating shiitake procurement by industrial food manufacturers in France and Germany.
- Portobello:Mature button variants with dense flesh structure suit grilling applications in foodservice channels.
- Oyster:Fast-growing Pleurotus varieties gain traction in plant-based protein formulations for their fibrous texture.
- Enoki:Delicate, long-stemmed Asian varieties require specialized gentle-freezing protocols.
- Morel:Wild-harvested Morchella species command premium positioning in specialty retail and hospitality.
Button mushroom sits at the top of the volume ranking, with shiitake climbing the fastest.
Packaging Type:
Cost tier stratification separates capital-intensive cryogenic systems from commodity formats serving price-sensitive channels.
- Vacuum Pack:Oxygen-exclusion films extend shelf stability 40% beyond conventional methods, justifying unit premiums in supermarket frozen vegetable aisles. German discounters Aldi and Lidl have standardized vacuum-packed private-label specifications across national networks, locking in processor volume commitments.
- Modified Atmosphere:Gas-flushed barrier films balance preservation performance against material cost, occupying the mid-tier in retail positioning. French ready-meal manufacturers specify modified atmosphere pouches for IQF mushroom blends to maintain color stability through distribution.
- Cryogenic Box:Insulated containers with liquid nitrogen injection serve bulk foodservice and institutional procurement.
- Plastic Tray:Standard polyethylene formats dominate economy-tier retail and catering channels.
- Paper Carton:Fiber-based alternatives respond to sustainability mandates in Nordic retail networks.
Vacuum pack holds the volume leadership position, while modified atmosphere gains share fastest in premium retail channels.
Application:
Margin concentration follows customer scale, with largest buyers extracting standardization commitments that reshape processor equipment decisions.
- Ready-to-Eat Meals:Industrial food manufacturers in Germany and France specify IQF mushroom components to eliminate kitchen labor and guarantee portion weight consistency. Blast-freezing infrastructure at Dutch processors now dedicates separate production lines to RTE meal supply contracts with 52-week volume guarantees.
- Foodservice:Restaurant chains and contract caterers prioritize procurement efficiency over per-unit cost, accepting premiums for pre-portioned frozen products that reduce waste. Polish and Czech hospitality operators are displacing fresh mushroom procurement with frozen alternatives to stabilize food cost percentages.
- Retail:Supermarket private-label programs concentrate leverage through direct processor relationships.
- Institutional Catering:Hospital and school feeding programs demand lowest-unit-cost formats with extended shelf stability.
- Hospitality:Hotels and independent restaurants source specialty varieties for menu differentiation.
Ready-to-eat meals command the highest margin pool, with foodservice expanding most quickly across Central European markets.
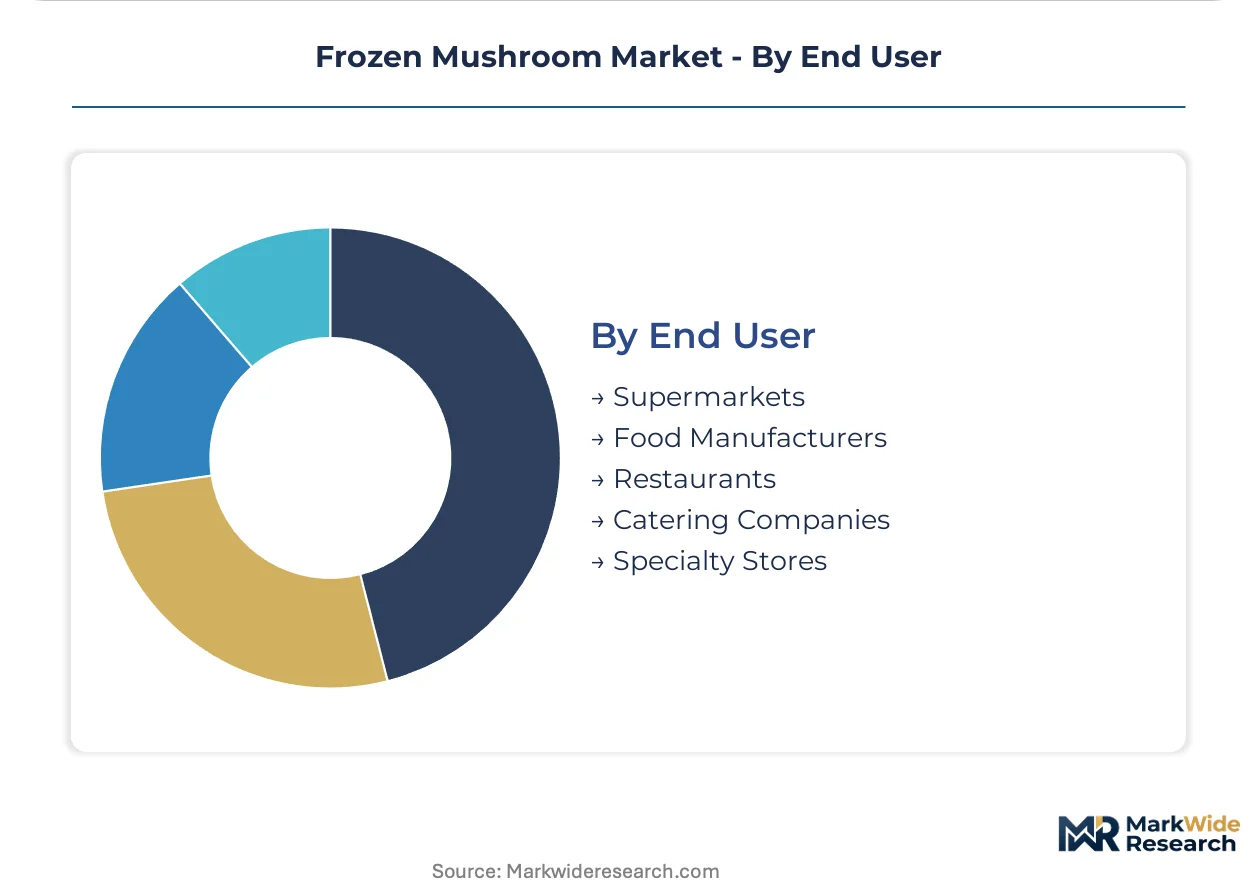
End User:
Customer type determines order frequency, specification complexity, and the degree of supply chain integration required for contract retention.
- Food Manufacturers:Industrial buyers of savory flavor extracts and textured protein ingredients specify mycotoxin testing protocols and lot-level traceability that only scaled processors can deliver. EU F-Gas compliance certification has become a mandatory qualification criterion for frozen mushroom suppliers to German ready-meal producers.
- Supermarkets:Retail private-label programs concentrate procurement through direct processor relationships, extracting volume discounts in exchange for shelf access commitments. Discounter sourcing offices in Poland and the Czech Republic now standardize frozen mushroom specifications across national product lines.
- Restaurants:Independent and chain operators prioritize labor reduction through pre-processed frozen inputs.
- Catering Companies:Contract foodservice providers demand consistent supply for large-scale event feeding.
- Specialty Stores:Gourmet retailers source premium and exotic varieties for discerning consumer segments.
Food manufacturers anchor the highest-value procurement relationships, with supermarkets driving the steepest volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping frozen mushroom production geography as processors migrate toward jurisdictions with compressed compliance timelines and subsidized cold chain infrastructure. The EU F-Gas phase-down has accelerated facility consolidation in Germany and Poland while pushing marginal capacity toward alternative markets.
Germany
Retail private-label procurement from Aldi and Lidl drives volume concentration in frozen mushroom demand. The EU F-Gas Regulation mandates ammonia-CO2 cascade system conversions with the steepest compliance deadlines in Europe. The Lower Saxony processing corridor hosts blast-freezing clusters serving Central European distribution networks.
Poland
Discounter sourcing offices in Warsaw and Poznań are extracting direct processor relationships from traditional wholesale channels. BIS cold chain standards compliance investments by exporters targeting India create certification capacity spillovers for domestic facilities. The Mazovia region concentrates frozen vegetable processing infrastructure with expanding shiitake cultivation integration.
Netherlands
Climate-controlled indoor mushroom cultivation systems deliver twelve-month harvest windows eliminating seasonal supply volatility. EFSA mycotoxin threshold updates force rapid-detection laboratory integration across quality-control operations. The Noord-Brabant growing belt anchors year-round supply consistency for frozen processors serving French and German industrial buyers.
United States
FDA Hazard Analysis Critical Control Point frameworks govern pathogen control protocols elevating compliance costs for transatlantic market access. Food manufacturers specify frozen mushroom inputs for plant-based protein formulations in vegan ready-meal applications. The Pennsylvania-Delaware-Maryland mushroom cultivation corridor supplies processing facilities with standardized button and specialty varieties.
India
Organized retail expansion across Mumbai and Delhi NCR creates first-mover advantages for exporters investing in BIS cold chain standards compliance. The country's national food safety regulator enforces testing and labeling requirements shaping market access protocols. Maharashtra and Karnataka host emerging cold chain infrastructure clusters targeting frozen vegetable distribution network integration.
Frozen Mushroom Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue umami extract specialization and ammonia-CO2 refrigeration technology licensing. The market exhibits moderate consolidation around integrated cultivation-freezing operations and geographic proximity to retail private-label programs. Three archetypes dominate: multinational frozen vegetable conglomerates with captive mushroom supply, regional specialists controlling distribution into specific supermarket channels, and industrial ingredient processors supplying food manufacturers with value-added frozen inputs. Competitive moves center on facility consolidation partnerships with refrigeration engineering firms and backward integration into climate-controlled cultivation systems.
Within the integrated conglomerate tier, Bonduelle Fresh Europe and McCain Foods Limited represent archetypes of scale-driven procurement leverage and multinational distribution network access. Among regional specialists, Monaghan Mushrooms occupies a position exemplifying geographic dominance in Ireland and UK supermarket channels. Scelta Mushrooms sits within the industrial ingredient processor archetype, specializing in value-added frozen mushroom inputs for food manufacturers rather than retail whole-product distribution.
| Leading Market Players |
|---|
| Bonduelle Fresh Europe |
| OKECHAMP S.A. |
| Monaghan Mushrooms |
| Costa Group |
| Monterey Mushrooms |
| McCain Foods Limited |
| Scelta Mushrooms |
| Phillips Mushroom Farms |
| Big Mountain Foods |
| Others |
Supply & Pricing Matrix
Retail private-label procurement offices at Aldi and Lidl anchor pricing power in frozen mushroom markets, compressing supplier margins through volume-commitment contracts that standardize specifications across Central European networks. This buyer concentration enforces three-tier pricing stratification across premium vacuum-pack, standard modified-atmosphere, and economy bulk formats.
Pricing Analysis
Retailer markup layers dominate frozen mushroom pricing, with discounters extracting direct-processor relationships that eliminate traditional wholesale margins. Price differentiation rests on certification grade and volume scale, where EU F-Gas compliance certification commands tier premiums from German ready-meal manufacturers. Cost compression in energy-intensive blast-freezing operations is intensifying because natural gas price volatility in Poland and Germany erodes processor margins. Food manufacturers show least price sensitivity due to formulation lock-ins, while institutional catering programs demand lowest-unit-cost procurement.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-excursion returns remains underdeveloped across frozen mushroom distribution, creating write-off exposure for retailers managing cold-chain breaks. Geographic supply concentration centers on Ireland, the Netherlands, and Poland, where climate-controlled cultivation clusters feed Central European processing hubs. Raw material dependencies span fresh mushroom feedstock, refrigerant gases, and cryogenic packaging films. Single-source vulnerability in Dutch shiitake cultivation creates crop-failure exposure. Distribution runs through retail private-label direct contracts and foodservice procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in frozen mushroom markets hinges on ammonia-CO2 refrigeration technology adoption reducing energy cost exposure, while umami extract positioning opens premium industrial channels beyond commodity whole-product sales.
For Market Incumbents: Deepen backward integration into climate-controlled cultivation systems to secure year-round supply consistency against weather-driven crop failures in Ireland and the Netherlands. Prioritize EU F-Gas compliance certification as a mandatory qualification criterion for German ready-meal manufacturer contracts. Expand ammonia-CO2 cascade system partnerships with specialized refrigeration engineering firms to lock in facility economics before phase-down deadlines compress payback periods. For New Entrants and Emerging Players: Enter via umami extract specialization for savory flavoring applications in snack and sauce manufacturing, where industrial ingredient channels remain less penetrated than retail whole-product markets. Target Indian organized retail expansion across Mumbai and Delhi NCR with BIS cold chain standards compliance investments that create first-mover advantages. Pursue licensing arrangements for ammonia-CO2 hybrid refrigeration technologies enabling smaller-scale facility entry without full capital replacement. For Investors and Strategic Acquirers: Food manufacturers with captive ready-meal formulation pipelines are the most active acquirer in this space, seeking backward integration into frozen mushroom supply security. Long-term viability over the next decade rests on processors with demonstrated EU F-Gas compliance and established retail private-label relationships. Monitor EFSA mycotoxin threshold update announcements as signals for quality-control infrastructure investment requirements that will reshape processor capital allocation priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-CO2 Cascade System Conversion | EU F-Gas phase-down mandates retrofit investments that consolidate market share around capital-reserved processors. |
| IQF Tunnel Technology Deployment | Fluidized bed freezing expands private-label contract access previously reserved for bulk blast-frozen products. |
| Umami Extract Specialization | Savory flavoring applications for snack manufacturers open industrial channels beyond commodity whole-mushroom sales. |
| BIS Cold Chain Compliance Investment | Certification capacity creates first-mover positioning in Indian organized retail expansion across Mumbai and Delhi NCR. |
| Climate-Controlled Cultivation Integration | Dutch and Polish indoor growing systems eliminate seasonal supply volatility constraining frozen shiitake availability. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blast-freezing facility managers, retail private-label procurement directors, food manufacturer R&D leads, and cold chain logistics operators with secondary validation against EU F-Gas regulatory filings, EFSA mycotoxin threshold documentation, BIS standards publications, and trade customs data for frozen vegetable categories. Bottom-up processor capacity assessments and top-down retail demand modeling were triangulated against cultivation volume estimates.
Comparable-period anchoring linked projection models to historical reference intervals spanning pre and post EU F-Gas Regulation implementation phases across the analysis window. Segmentation dimensions modeled include product type, packaging format, application channel, and end-user procurement scale, with CAGRs derived from trend extrapolation of cultivation expansion rates and processing capacity utilization. Forecast inputs incorporated refrigerant transition timelines and mycotoxin testing protocol adoption curves.
Inputs from regulatory filings and processor interviews were available through the study window; gaps in real-time energy cost pass-through data and private-label contract renewal schedules introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions about compliance timeline adherence and technology adoption rates. Practitioners should monitor EFSA mycotoxin threshold announcements and EU F-Gas phase-down schedule revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
US Frozen Dessert Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Kimchi Market