
 Asia-Pacific Medical Robots Market | 2026-2036
Asia-Pacific Medical Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Robots Market Outlook
Orthopedic surgery is hardening as the dominant end-use vertical across Asia-Pacific hospital procurement cycles. Johnson & Johnson leverages its DePuy Synthes integration to sustain instrument-and-robot bundled contracts in Australian and South Korean health systems. Intuitive Surgical anchors da Vinci installed base growth through dedicated training academies in Singapore and Japan.
Asia-Pacific medical robots encompass electromechanical systems with sub-millimeter positional accuracy, haptic feedback loops, and sterilizable tool interfaces designed to execute or assist precision interventions in clinical environments. Surgical robots command the largest revenue share, while telepresence robots represent the fastest-expanding category as rural health networks in India and Indonesia deploy remote consultation platforms. Rehabilitation robots occupy a mature niche with stable replacement cycles across Japanese eldercare facilities.
Japan's PMDA, Australia's TGA, and South Korea's MFDS each enforce distinct software validation and biocompatibility standards that shape product registration timelines and localization requirements. China's NMPA introduced accelerated review channels for innovative medical devices, compressing market entry intervals for foreign manufacturers. Stakeholders must monitor evolving data-localization mandates and cross-border service restrictions that could fragment after-sales support architectures.
Market Dynamics
Japan's PMDA accelerated Class IV device pathways are compressing commercialization timelines for surgical robot manufacturers while China's NMPA innovation channels pull foreign platforms into tier-one hospital clusters faster than legacy regulatory cycles permitted.
Growth Catalysts
- Orthopedic surgery expansion:Tertiary hospitals across South Korea and Australia are scaling robotic-assisted joint replacement volumes as provincial health commissions prioritize minimally invasive infrastructure investments.
- Telepresence network deployment:Rural health systems in Indonesia and India are installing remote consultation platforms to bridge specialist access gaps, creating hardware pull-through for mobile robotic systems.
- PMDA streamlined review:Japan's regulator reduced software validation documentation requirements for predicate-approved surgical platforms, cutting registration intervals for iterative hardware upgrades.
Market Restraints
- Precision actuator supply concentration:Sub-millimeter servo motor production clusters in specific East Asian manufacturing zones create single-source vulnerability for haptic feedback system assembly.
- Biocompatibility testing cost structure:Sterilizable tool interface validation against PMDA, TGA, and MFDS distinct standards multiplies pre-market expenditure for multi-country registration strategies.
- Technical limitation in tactile feedback:Current haptic loop latency thresholds fail to replicate tissue resistance fidelity for complex soft-tissue procedures, constraining application expansion beyond orthopedic and urological domains.
Strategic Opportunities
- Vietnam and Philippines hospital buildouts:Greenfield medical infrastructure in Southeast Asian secondary cities lacks legacy equipment lock-in, enabling direct robotic platform installation versus retrofit competition.
- Rehabilitation-telepresence convergence:Elder care facilities in Japan are piloting combined mobility assistance and remote physician access systems, opening hybrid product categories.
- China NMPA innovation channel:Foreign manufacturers leveraging accelerated review pathways gain first-mover positioning in tier-one hospital procurement cycles before domestic competitors complete equivalent certifications.
Industry Challenges
- Surgeon training pipeline compression:Da Vinci and competing platform certification programs require 50-100 supervised procedures, creating bottlenecks as installed base expands faster than credentialed operator supply.
- After-sales service architecture fragmentation:Data-localization mandates in China and cross-border service restrictions force manufacturers to build country-specific technical support networks rather than centralized regional hubs.
- Legacy EMR integration complexity:Robotic surgical platforms must interface with heterogeneous hospital information systems across Japanese, Australian, and South Korean provider networks, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Robots Market |
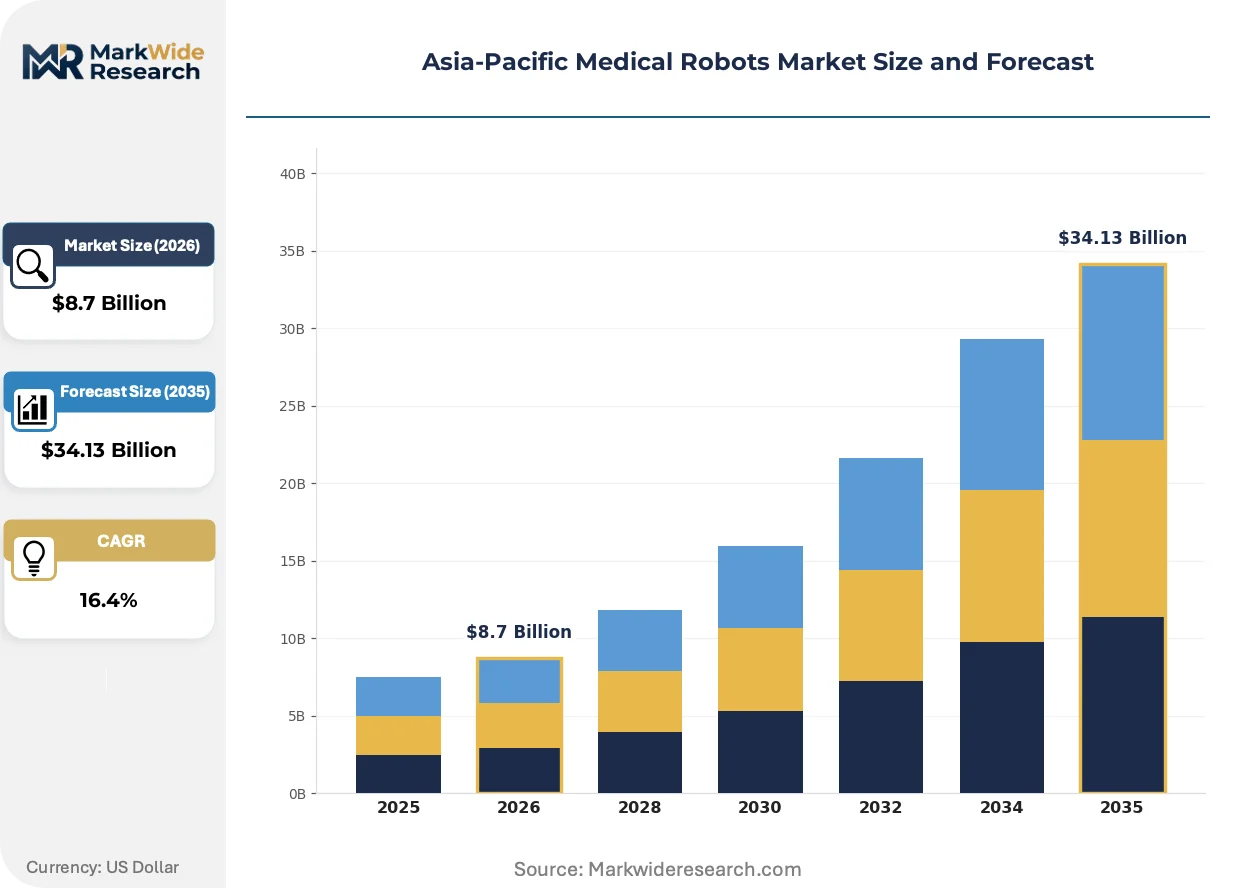
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Robots, Rehabilitation Robots, Hospital Robots, Telepresence Robots Technology: Artificial Intelligence, Machine Learning, Computer Vision, Sensor Technology Application: Orthopedic Surgery, Neurosurgery, Urology, Cardiothoracic Surgery End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Facilities, Home Care Providers |
| Companies Covered | Johnson & Johnson, Zimmer Biomet, Intuitive Surgical, Globus Medical, Smith & Nephew, Medtronic, Siemens Healthineers, Accuray Incorporated, Stryker Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Robots Market Strategic Shifts
Electromechanical precision boundaries are dissolving as haptic feedback loops achieve sub-millimeter accuracy thresholds, while regulatory acceleration and procurement model evolution reshape competitive access to hospital capital budgets.
Autonomous suturing algorithms are rewriting surgical workflow economics. These software modules interpret real-time tissue visualization to execute closure sequences without continuous surgeon manipulation. Tertiary hospitals in Singapore and Japan are piloting supervised autonomous modes for routine anastomosis procedures. The technology is compressing operative time per case while extending robot utilization rates beyond current human-operator constrained schedules.
China's NMPA introduced conditional approval pathways for AI-integrated surgical devices, permitting limited commercial deployment during pivotal clinical data collection. This regulatory innovation reduces time-to-revenue for computer vision-enabled platforms. Manufacturers are responding by prioritizing NMPA submissions over legacy sequential FDA-PMDA registration strategies, redirecting clinical trial investment toward Chinese patient populations and investigator sites.
Hospital procurement committees in Australia's public health system are unbundling capital equipment from disposable instrument contracts, reversing historical bundled pricing structures. This purchasing behavior shift forces robot manufacturers to compete on platform hardware margins separately from recurring instrument revenue streams. The change is most visible in Victorian and New South Wales hospital network tenders, where finance departments now mandate three-year total cost of ownership comparisons across competing surgical robot ecosystems.
Asia-Pacific Medical Robots Market Segmentation
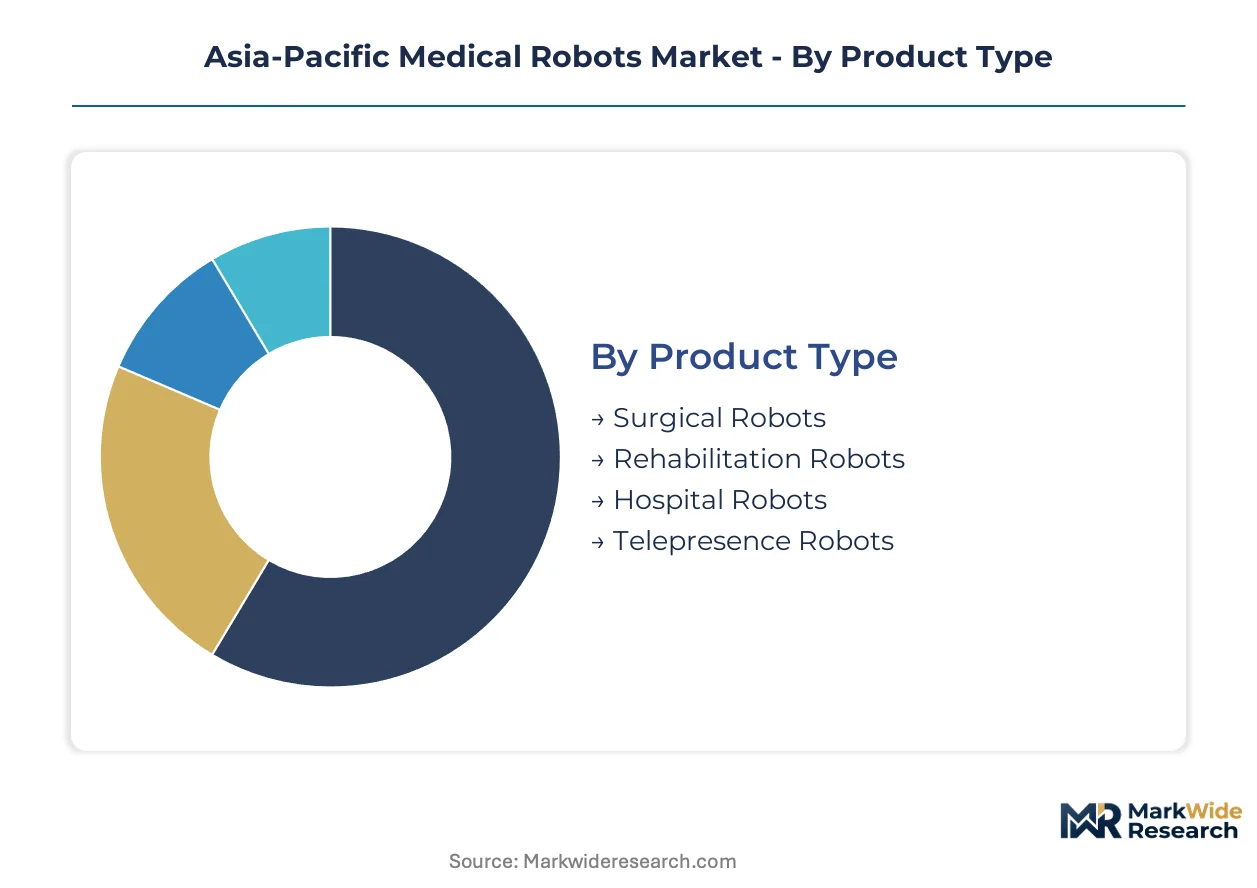
Asia-Pacific hospital procurement committees evaluate medical robots through multiple lenses: capital budget cycles favor certain product categories, regulatory pathways vary by technology sophistication, and clinical utility determines application prioritization across surgical departments.
Product Type:
Capital allocation decisions in Chinese tier-one hospitals and Japanese tertiary centers concentrate procurement authority on platforms with proven reimbursement pathways and training infrastructure.
- Surgical Robots:Electromechanical systems with sub-millimeter positional accuracy and haptic feedback loops dominate capital expenditure in South Korean and Australian orthopedic departments. Bundled instrument contracts and dedicated training academies sustain installed base expansion across tertiary hospital networks.
- Telepresence Robots:Mobile consultation platforms with integrated diagnostic peripherals are expanding most quickly as Indonesia and India deploy rural health network infrastructure. Provincial health commissions in secondary cities prioritize remote specialist access over capital-intensive surgical platform acquisition.
- Rehabilitation Robots:Gait training and mobility assistance systems occupy mature replacement cycles across Japanese eldercare facilities.
- Hospital Robots:Automated logistics and sterilization units serve supply chain efficiency mandates in Singaporean and Australian hospital networks.
Volume sits with surgical robots; growth tilts toward telepresence robots.
Technology:
Software validation requirements under PMDA, NMPA, and MFDS regimes create divergent commercialization timelines for algorithm-dependent platforms versus hardware-centric systems.
- Computer Vision:Real-time tissue recognition and anatomical mapping algorithms enable autonomous suturing pilots in Singaporean tertiary centers. NMPA conditional approval pathways for AI-integrated devices accelerate deployment timelines for manufacturers prioritizing Chinese regulatory submissions.
- Artificial Intelligence:Predictive analytics modules for surgical workflow optimization concentrate development investment from platforms seeking differentiation in crowded orthopedic segments.
- Machine Learning:Iterative performance improvement from procedure datasets drives post-market surveillance obligations under Japanese software validation standards.
- Sensor Technology:Force and torque feedback arrays with sterilizable interfaces face biocompatibility testing multiplication across PMDA, TGA, and MFDS distinct requirements.
Commercial traction clusters around computer vision; regulatory headwinds weigh heaviest on sensor technology.
Application:
Surgeon training pipeline capacity and reimbursement adequacy shape departmental rollout sequencing across Asia-Pacific health systems.
- Orthopedic Surgery:Robotic-assisted joint replacement procedures leverage established instrument-and-robot bundled contracts in Australian and South Korean public health networks. Provincial health commissions explicitly prioritize minimally invasive infrastructure investments in capital planning cycles.
- Urology:Da Vinci platform penetration in prostatectomy creates credentialing infrastructure that competing surgical robot manufacturers must replicate for market entry.
- Neurosurgery:Sub-millimeter accuracy requirements and tactile feedback latency constraints limit current platform applicability beyond specialized academic medical centers.
- Cardiothoracic Surgery:Complex soft-tissue resistance fidelity demands exceed current haptic loop performance thresholds, constraining near-term adoption.
Procurement volume concentrates in orthopedic surgery; neurosurgery awaits technical maturation.
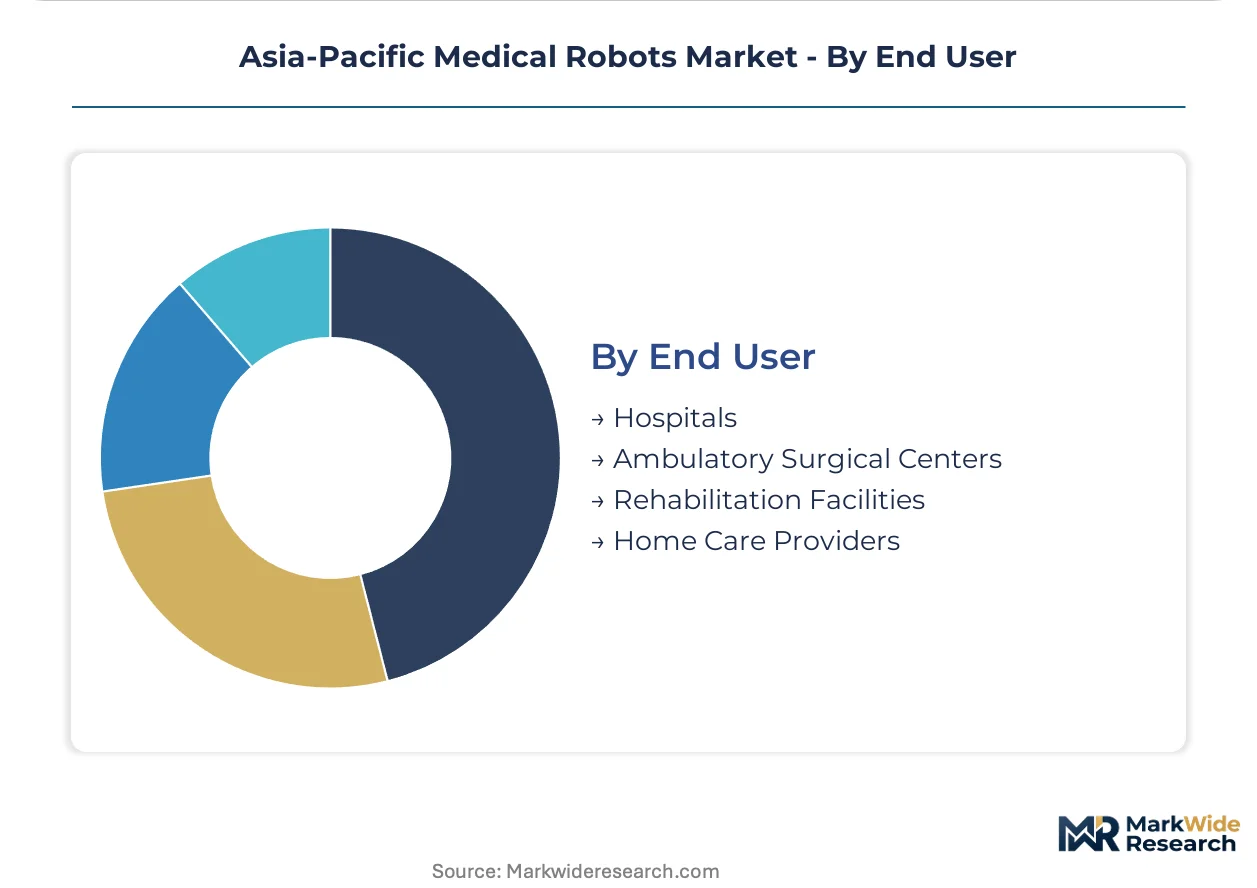
End User:
Facility type determines capital intensity tolerance, reimbursement model compatibility, and technical support architecture requirements.
- Hospitals:Tertiary centers in China's tier-one clusters and Japan's urban corridors command procurement authority for multi-million dollar surgical platform installations. EMR integration complexity with heterogeneous hospital information systems extends deployment timelines across Japanese, Australian, and South Korean networks.
- Ambulatory Surgical Centers:Procedure volume economics and space constraints favor compact telepresence and limited surgical robot configurations in Australian and South Korean outpatient settings.
- Rehabilitation Facilities:Japanese eldercare operators pilot combined mobility assistance and remote physician access systems, opening hybrid product categories.
- Home Care Providers:Cost thresholds and technical support reach limit current penetration to premium segments in urban Japanese and Australian markets.
Capital deployment concentrates in hospitals; ambulatory surgical centers present margin-compressed volume opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax incentives and preferential policies for innovative medical devices are concentrating foreign manufacturer headquarters and R&D facilities in the zone. This policy architecture accelerates commercialization timelines for surgical robot platforms targeting tier-one hospital clusters.
China
Tier-one hospital clusters in Beijing, Shanghai, and Guangzhou drive procurement volumes for orthopedic surgical robots as provincial health commissions prioritize minimally invasive infrastructure. NMPA's innovation channel compresses registration intervals for foreign platforms through conditional approval pathways. The Yangtze River Delta concentration hosts pilot deployments of AI-integrated surgical devices under real-world data collection protocols.
Japan
Tertiary centers in Tokyo and Osaka sustain installed base expansion for da Vinci platforms through dedicated training academies and credentialing infrastructure. PMDA's streamlined Class IV device pathways reduced software validation documentation for predicate-approved surgical systems. Kanto region academic medical centers pilot supervised autonomous suturing modes for routine anastomosis procedures.
South Korea
Public health networks in Seoul and Busan scale robotic-assisted joint replacement volumes through instrument-and-robot bundled contracts. MFDS enforces distinct biocompatibility standards for sterilizable tool interfaces that shape multi-country registration strategies. Seoul Capital Area orthopedic departments command procurement authority for multi-million dollar platform installations.
Australia
Victorian and New South Wales hospital networks unbundle capital equipment from disposable instrument contracts, mandating three-year total cost of ownership comparisons. TGA's software validation requirements for AI-integrated devices create divergent commercialization timelines versus hardware-centric systems. Sydney and Melbourne tertiary centers concentrate EMR integration complexity with heterogeneous hospital information systems.
Singapore
Telepresence robot deployment accelerates across rural health networks in neighboring Indonesia and Malaysia, with Singapore serving as regional distribution hub. The city-state's training academies anchor da Vinci operator certification programs for Southeast Asian surgeons. Biopolis research cluster hosts pilot programs for computer vision-enabled surgical platforms seeking NMPA conditional approval.
Asia-Pacific Medical Robots Market Competitive Environment
Top-tier vendors anchor the premium surgical robot segment, while mid-scale specialists occupy rehabilitation and telepresence niches. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with bundled instrument contracts, pure-play surgical robot manufacturers with dedicated training infrastructure, and emerging AI-integrated platform developers seeking regulatory fast-tracks. Competitive moves center on M&A for orthopedic specialization and geographic expansion through localized service networks.
Among diversified medtech conglomerates, Johnson & Johnson and Medtronic occupy positions exemplifying instrument-and-robot bundled contract strategies across Australian and South Korean health systems. Intuitive Surgical represents the pure-play archetype with training academy infrastructure. Zimmer Biomet anchors the orthopedic specialization tier. These three entities illustrate the competitive spectrum from diversified bundling to focused surgical platform development.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Zimmer Biomet |
| Intuitive Surgical |
| Globus Medical |
| Smith & Nephew |
| Medtronic |
| Siemens Healthineers |
| Accuray Incorporated |
| Stryker Corporation |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet price indices cascade through surgical robot manufacturing tiers, compressing margins on haptic feedback actuator assemblies while amplifying cost premiums for platforms with guaranteed sub-millimeter precision. This commodity pressure stratifies final system pricing across Chinese tier-one hospitals, Japanese tertiary centers, and Australian public networks.
Pricing Analysis
Lead-time premiums dominate Asia-Pacific medical robot procurement, with 90-day guaranteed delivery commanding hardware margins 15-20 points above spot-market inventory. Pricing stratifies across premium, standard, and economy tiers based on NMPA/PMDA certification status and bundled instrument contract depth. Cost compression in the standard tier intensifies as domestic Chinese manufacturers accelerate predicate-device approvals. Australian public health networks exhibit highest price sensitivity through unbundled TCO evaluations, while Japanese academic medical centers prioritize precision specifications over unit economics.
Supply Chain Analysis
China's NMPA domestic-content mandates for Class III device components are reshaping sourcing patterns, forcing foreign manufacturers to localize sub-millimeter servo motor assembly. Precision actuator production draws from Japan, Germany, and South Korea, with sterilizable tool interface biocompatibility testing tethered to PMDA/MFDS validation protocols. Single-source vulnerability concentrates in rare earth magnet supply from Chinese processing facilities. Distribution runs through hospital GPO contracts in Australia and South Korea, direct provincial commission tenders in China, and academic medical center procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific medical robots occupy a technology-transition phase where computer vision-enabled autonomous suturing displaces conventional teleoperated platforms, compressing the window for legacy system manufacturers to secure installed base positions.
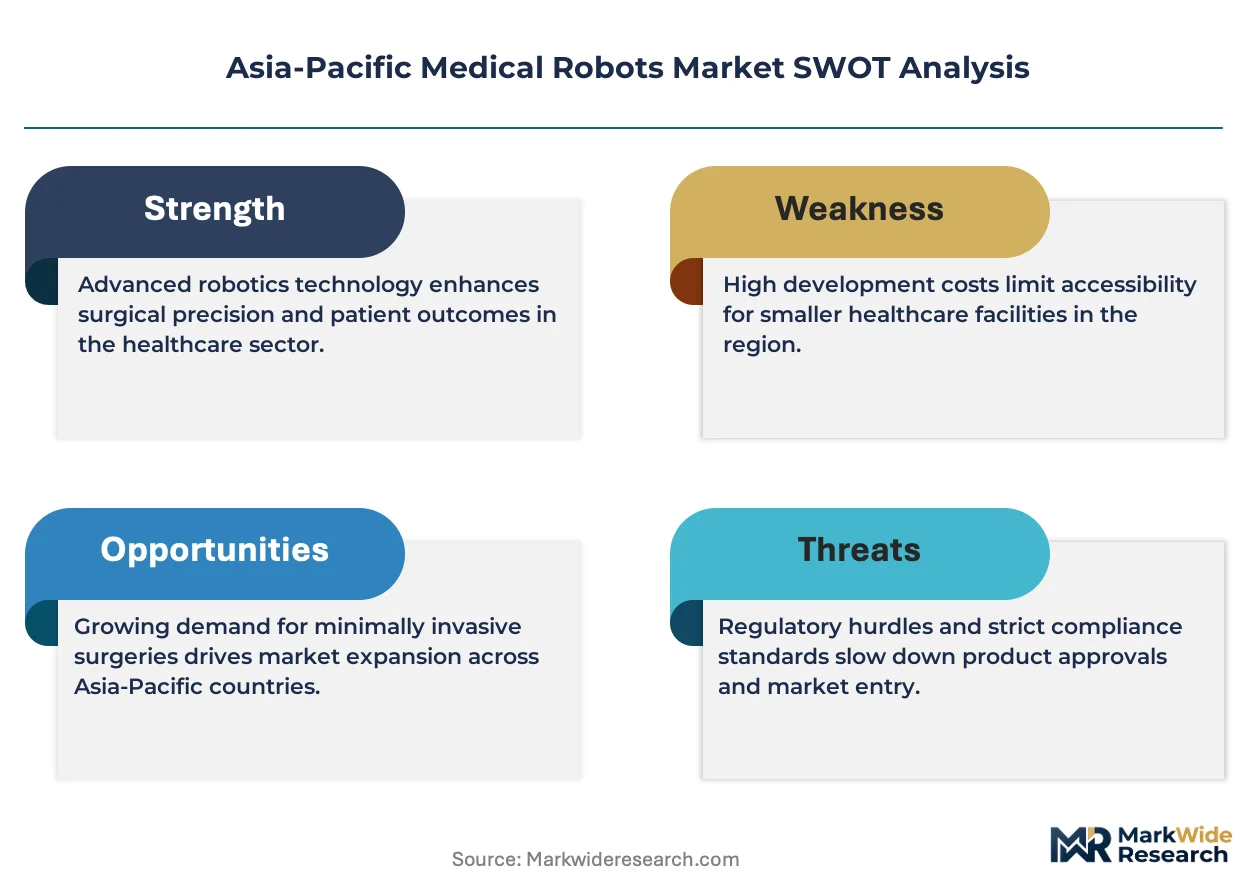
For Market Incumbents: Acquire orthopedic-specialized instrument portfolios to defend bundled contract positions against pure-play surgical robot entrants threatening Australian and South Korean public health networks. Deepen backward integration into haptic feedback actuator manufacturing to offset rare earth magnet cost volatility and preserve margin structure on precision hardware tiers. For New Entrants and Emerging Players: Begin with telepresence deployment in Indonesian and Philippine secondary cities where greenfield hospital infrastructure lacks legacy equipment lock-in. Target Vietnam's provincial health commission procurement cycles with mobile consultation platforms bundled with remote physician access services, leveraging Singapore as regional technical support hub. For Investors and Strategic Acquirers: The window for entry favors AI-integrated surgical platform developers with NMPA conditional approval pathways already initiated. Long-term viability hinges on software validation capabilities spanning PMDA, MFDS, and TGA regimes. Monitor NMPA innovation channel submission volumes as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Innovation Channel Submission | Accelerates market entry timelines for foreign manufacturers targeting Chinese tier-one hospital clusters. |
| PMDA Streamlined Class IV Pathway Utilization | Compresses software validation intervals for iterative surgical platform upgrades in Japanese tertiary centers. |
| Orthopedic Instrument Portfolio Acquisition | Secures bundled contract positions in Australian and South Korean public health procurement cycles. |
| Telepresence Rural Network Deployment | Captures hardware pull-through in Indonesian and Indian provincial health infrastructure buildouts. |
| Autonomous Suturing Algorithm Development | Enables supervised operative modes that extend robot utilization beyond human-operator constrained schedules. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at surgical robot manufacturers. PMDA submission databases, NMPA innovation channel disclosures, and Australian TGA approval registers provided device-specific commercialization timelines. Bottom-up installed base modeling triangulated against top-down health system capital expenditure projections.
Granularity-level modeling operated at product-type, application, technology, and end-user dimensions, with additional country-regulatory-cluster segmentation capturing PMDA, NMPA, MFDS, and TGA pathway differences. CAGRs derived from procedure volume elasticity to installed base expansion, incorporating surgeon training pipeline constraints and reimbursement adequacy variations across orthopedic, urological, and emerging application segments.
Regulatory approval delays, surgeon credentialing bottlenecks, and rare earth supply disruptions are the dominant revision risks to surgical robot deployment forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Underwater Robot Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Italy Cloud Robotics Market