
 Latin America Automated Guided Vehicle (AGV) Market | 2026-2036
Latin America Automated Guided Vehicle (AGV) Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Automated Guided Vehicle (AGV) Market Foresight
ISO 3691-4 compliance tier is redrawing competitive requirements for AGV safety and navigation reliability across Latin American industrial sites. KUKA Group leverages its Stuttgart-engineered control architectures to anchor premium positioning in Brazilian automotive plants. Daifuku Co Ltd sustains dominance in airport baggage handling extensions across Mexico City and Guadalajara hubs. ABB Ltd differentiates through its Ability digital platform integration, competing on predictive maintenance uptime guarantees rather than hardware margins alone.
Automated Guided Vehicles are self-propelled mobile robots engineered to transport materials along defined paths using laser, magnetic, or vision-based guidance systems with payload capacities typically spanning 500 kg to 50,000 kg depending on chassis configuration. These systems execute repetitive horizontal transport tasks in manufacturing floors and distribution centers, replacing forklift-dependent workflows with programmable route optimization and collision-avoidance sensor arrays. Tow Vehicles occupy the mature volume tier across Latin American automotive assembly plants where tugging heavy component trains remains the dominant use case. Vision Guided technology represents the fastest-expanding segment as Brazilian and Mexican facilities retrofit existing aisles without embedded magnetic tape infrastructure. Warehouse & Distribution end users command the deepest margin pools, driven by e-commerce fulfillment pressures in São Paulo and Monterrey metropolitan zones.
Brazil's NR-12 workplace safety regulator and Mexico's NOM standards enforce mandatory risk assessments for autonomous equipment deployment, directly shaping vendor certification timelines and installation protocols. ANVISA in Brazil and Argentina's national industrial safety frameworks impose additional electromagnetic compatibility requirements for healthcare facility AGV deployments, narrowing the supplier base for pharmaceutical logistics applications. Stakeholders must weigh fixed versus flexible installation architectures against the regulatory lag between Mercosur and Pacific Alliance harmonization schedules.
Market Dynamics
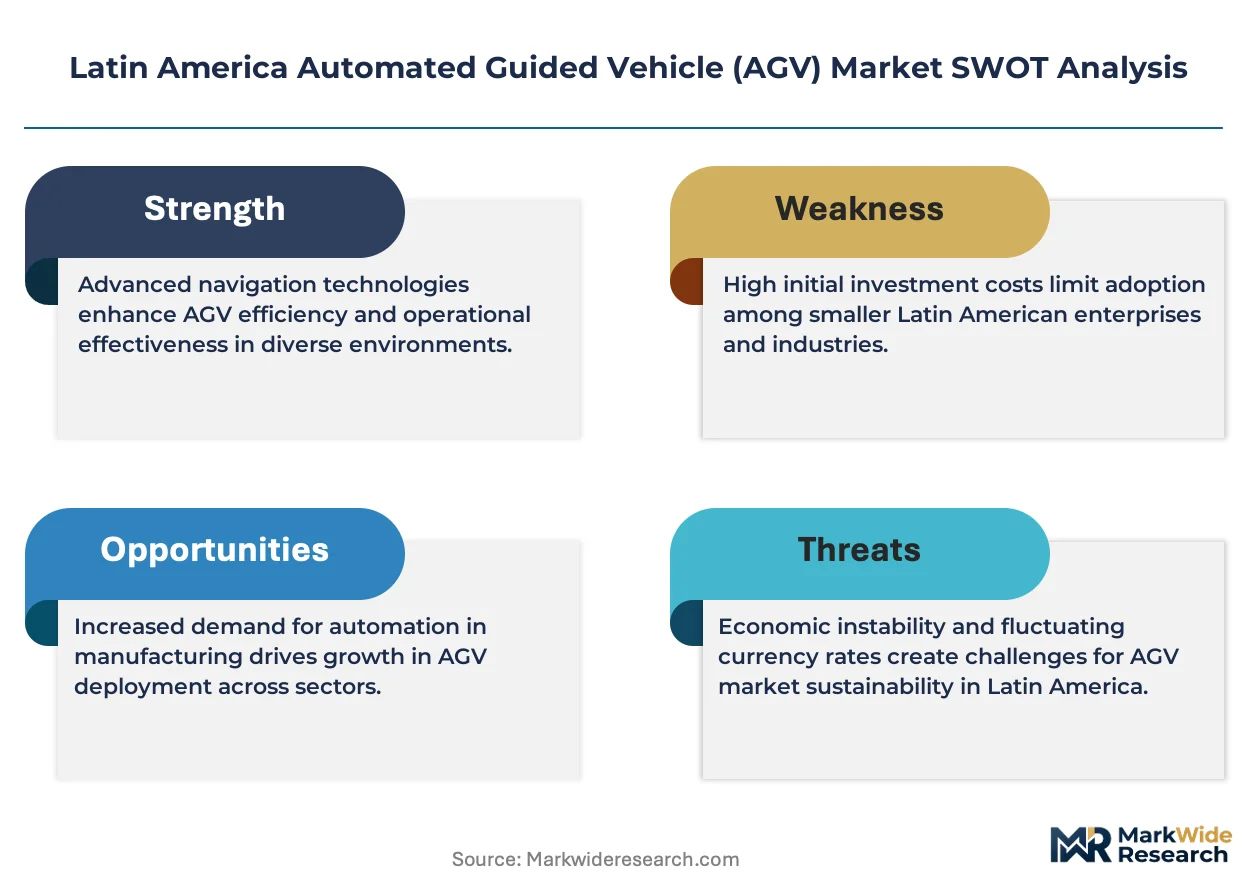
ISO 3691-4 compliance tier is compressing vendor margins as Brazilian and Mexican facilities retrofit legacy magnetic tape infrastructure toward vision-guided architectures with certified safety integrity levels.
Growth Catalysts
- NR-12 workplace safety mandates:Brazil's regulator enforces mandatory risk assessments for autonomous equipment deployment, accelerating replacement of manually operated forklifts in São Paulo's automotive corridor.
- E-commerce fulfillment density:Warehouse operators in Monterrey metropolitan zones deploy automated pallet movement systems to offset labor cost inflation in high-turnover picking environments.
- Vision-based navigation:Laser-guided retrofit kits eliminate embedded floor infrastructure requirements, enabling rapid deployment in existing Brazilian distribution centers without concrete cutting.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing depends heavily on East Asian cell manufacturers, exposing Latin American integrators to freight cost volatility and extended lead times.
- Mercosur-Pacific Alliance regulatory lag:Divergent electromagnetic compatibility certification timelines between Brazilian ANVISA and Mexican NOM frameworks fragment vendor compliance roadmaps.
- Magnetic tape path dependency:Legacy installed base in Argentine automotive plants locks facilities into maintenance-intensive guidance infrastructure with limited upgrade pathways.
Strategic Opportunities
- Colombian pharmaceutical logistics:Bogotá's cold-chain distribution hubs remain underpenetrated by autonomous material handling, offering first-mover positioning for temperature-certified AGV platforms.
- Outcome-based fleet contracts:São Paulo warehousing operators increasingly demand uptime-guaranteed service models rather than capital equipment purchases, shifting vendor revenue toward performance-linked subscriptions.
- 5G private network convergence:Ultra-reliable low-latency connectivity enables real-time fleet coordination in Mexican automotive plants previously limited by Wi-Fi handoff dead zones.
Industry Challenges
- Safety systems integration:Collision-avoidance sensor arrays require specialized calibration expertise scarce across Latin American system integrator networks, extending commissioning timelines.
- Legacy WMS interoperability:Proprietary middleware layers complicate integration with decade-old warehouse management software prevalent in Brazilian third-party logistics providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Automated Guided Vehicle (AGV) Market |
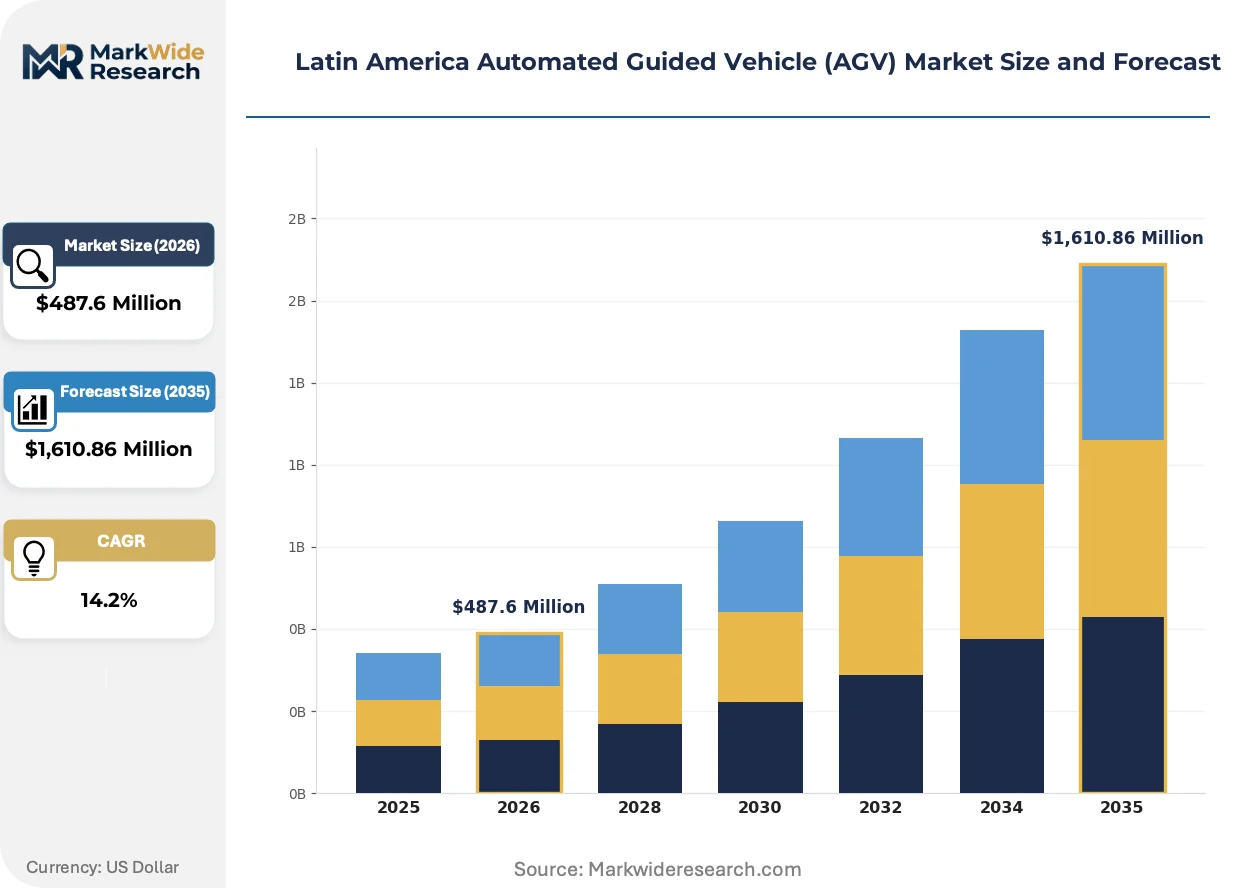
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tow Vehicles, Unit Load Carriers, Pallet Trucks, Assembly Line Vehicles Technology: Laser Guided, Magnetic Guided, Vision Guided, Indoors, Outdoors End User: Manufacturing, Warehouse & Distribution, Healthcare, Retail Installation: Fixed, Flexible, Modular, Customized |
| Companies Covered | KUKA Group, ABB Ltd, Schaefer Systems International Pvt Ltd, Jungheinrich Group, Dematic Group (KION), Daifuku Co Ltd, Toyota Material Handling International AB, Bastian Solutions LLC, Hyster-Yale Materials Handling, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Automated Guided Vehicle (AGV) Market Shifts & Advancements
Navigation autonomy is shifting from infrastructure-dependent guidance toward infrastructure-agnostic perception systems, while regulatory pressure on safety certification accelerates vendor consolidation around proven control architectures.
Vision-guided localization is decomposing the traditional magnetic tape installation value chain by eliminating floor-embedded infrastructure requirements. Brazilian automotive plants adopt camera-based simultaneous localization and mapping for retrofitted assembly lines at compressed deployment schedules. This technology is decomposing incumbent laser-reflector business models by collapsing the cost differential between greenfield and brownfield automation projects.
Mexico's NOM-001-SCFI electrical safety standards now mandate electromagnetic compatibility testing for autonomous mobile robots in industrial environments. The regulation forces vendors to establish in-country certification laboratories or partner with domestic testing facilities. Airport baggage handling extensions at Mexico City and Guadalajara hubs face the steepest compliance timelines due to continuous-operation uptime requirements.
Third-party logistics operators in São Paulo's industrial corridor now unbundle fleet management from equipment ownership, contracting specialized AGV-as-a-service providers for seasonal volume spikes. The model displaces traditional forklift rental channels in e-commerce fulfillment centers. Chilean retail distribution networks show nascent adoption of similar consumption patterns, though contract sophistication lags Brazilian market maturity.
Latin America Automated Guided Vehicle (AGV) Market Segmentation
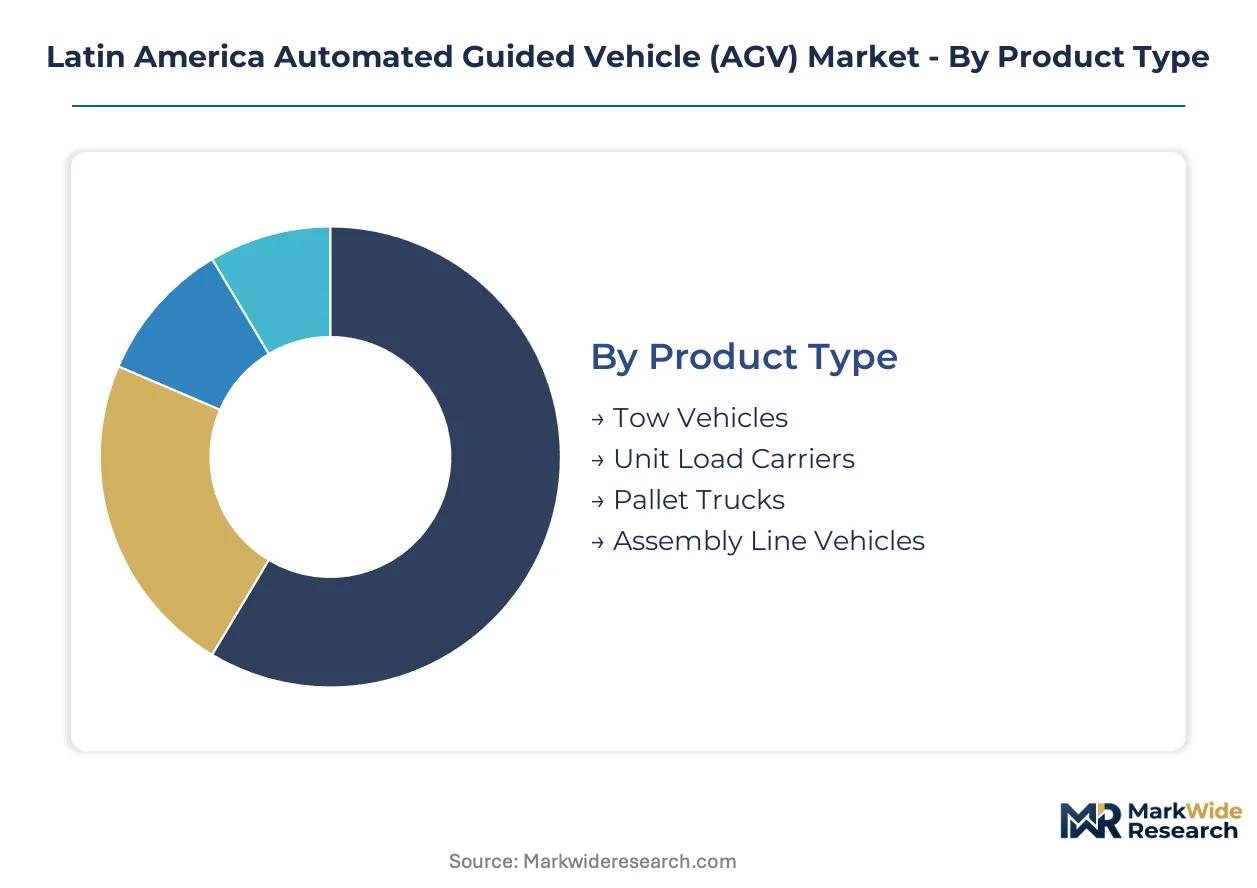
Latin American AGV procurement patterns diverge sharply between automotive assembly floors demanding heavy-load traction and e-commerce fulfillment centers optimizing pallet velocity. Segmentation reveals how infrastructure legacy, regulatory compliance tiers, and facility retrofit economics reshape vendor prioritization across Brazilian, Mexican, and Argentine industrial corridors.
Product Type:
Margin pools concentrate in vehicles engineered for high-frequency pallet movement rather than intermittent heavy-load towing, reflecting warehouse automation's premium pricing power over automotive line-fit applications.
- Tow Vehicles:Heavy-duty chassis configurations pull component trains up to 50,000 kg across automotive assembly plants. São Paulo's OEM corridors deploy these for engine-block sequencing where magnetic tape guidance remains entrenched despite retrofit costs.
- Unit Load Carriers:Self-loading platforms handle standardized totes and bins without external equipment. Monterrey electronics manufacturers favor these for cleanroom component delivery where vision-guided navigation eliminates floor contamination risks.
- Pallet Trucks:Fork-equipped variants execute vertical lifting alongside horizontal transport. Brazilian cold-chain distributors specify lithium-powered models for temperature-controlled pharmaceutical vaults.
- Assembly Line Vehicles:Skewed-deck designs position components at ergonomic heights for line-side operators. Mexican NOM-001-SCFI electrical certification timelines slow deployment in greenfield automotive plants.
Tow Vehicles hold installed capacity across Latin American automotive corridors. Unit Load Carriers are rotating up the share rankings in electronics and pharmaceutical verticals.
Technology:
Navigation architecture selection drives total cost divergence between greenfield vision systems and legacy magnetic infrastructure requiring concrete cutting for upgrades.
- Laser Guided:Reflector-based triangulation delivers sub-centimeter positioning accuracy in controlled environments. Argentine automotive plants retain these installations despite higher maintenance burdens versus camera-based alternatives.
- Magnetic Guided:Floor-embedded tape or wire infrastructure provides interference-resistant path following. Brazilian facilities face sunk-cost pressure to maintain these systems despite ISO 3691-4 compliance retrofit requirements.
- Vision Guided:Camera-based simultaneous localization and mapping eliminates embedded infrastructure. Mexico City airport baggage handlers deploy these for rapid lane reconfiguration without operational downtime.
- Indoors:Climate-controlled navigation optimized for warehouse and manufacturing environments. São Paulo's third-party logistics sector concentrates procurement here.
- Outdoors:All-weather chassis with enhanced localization robustness for yard and cross-dock applications. Chilean mining logistics operators test limited deployments for ore concentrate movement.
Magnetic Guided retains legacy footprint across Argentine and southern Brazilian facilities. Vision Guided is climbing the fastest as retrofit economics favor camera-based brownfield automation.
End User:
Customer procurement sophistication varies sharply between automotive OEMs with dedicated automation engineering teams and retail distributors outsourcing fleet management to specialized service providers.
- Manufacturing:Automotive and electronics producers dominate with high-volume, low-mix transport requirements. Brazilian NR-12 workplace safety mandates accelerate forklift replacement programs in component sequencing operations.
- Warehouse & Distribution:E-commerce fulfillment pressures drive fastest adoption velocity. Monterrey and São Paulo metropolitan zones concentrate demand for seasonal elasticity through AGV-as-a-service contracting models.
- Healthcare:Pharmaceutical logistics and hospital supply chains require ANVISA electromagnetic compatibility certification. Bogotá's cold-chain hubs remain underpenetrated relative to manufacturing verticals.
- Retail:Back-of-store replenishment and distribution center consolidation applications. Chilean supermarket chains pilot limited deployments behind Brazilian market maturity.
Manufacturing holds installed capacity from decade-long automotive automation programs. Warehouse & Distribution is rotating up the share rankings as e-commerce fulfillment density intensifies.
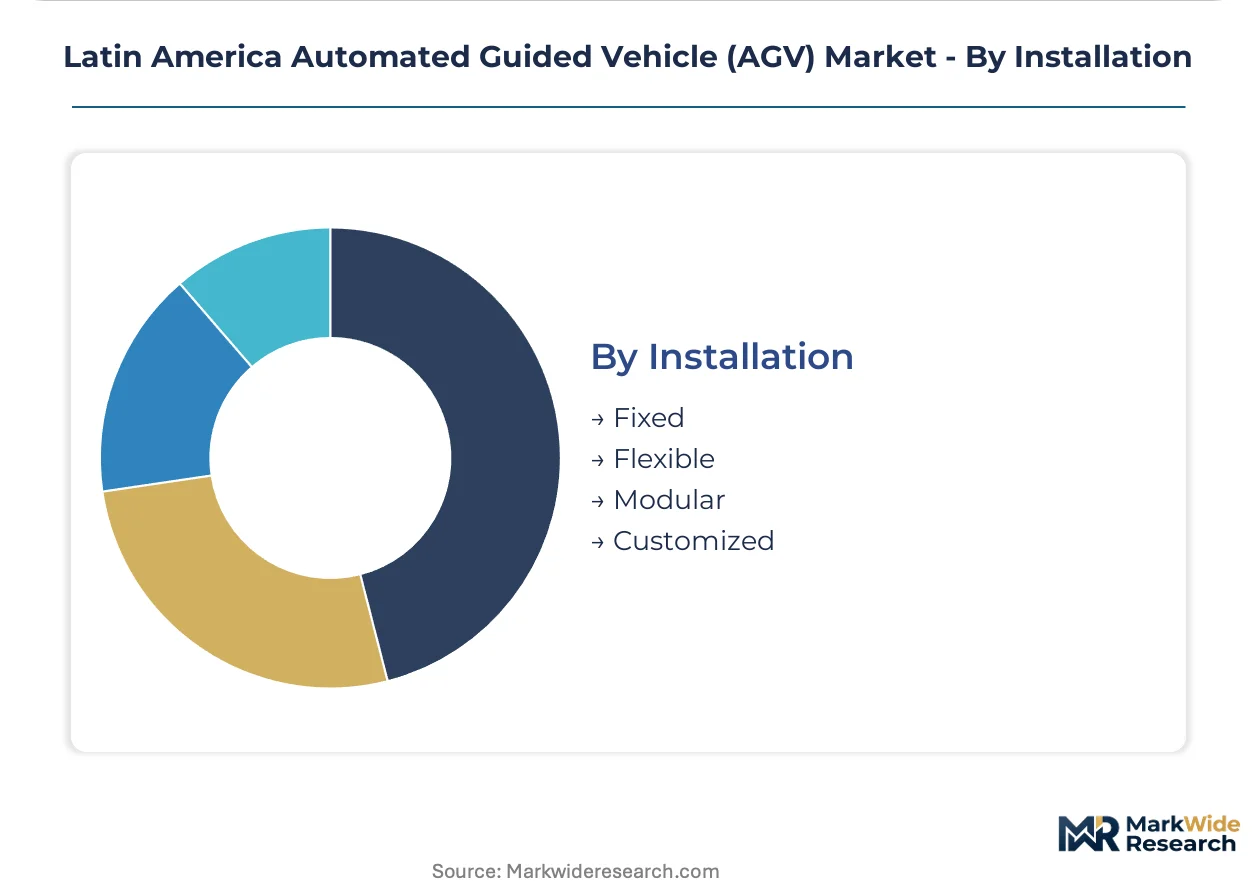
Installation:
Capital deployment flexibility separates facilities with dedicated automation budgets from operators demanding payback periods under three years through scalable entry points.
- Fixed:Permanent infrastructure with dedicated paths and charging stations. Argentine automotive plants with magnetic tape legacy exemplify this locked-in architecture.
- Flexible:Rapidly reconfigurable routes without floor modifications. Brazilian distribution centers favor these for seasonal volume spikes and SKU proliferation.
- Modular:Scalable fleet expansion through standardized vehicle platforms. Mexican third-party logistics operators deploy these for contract-specific capacity additions.
- Customized:Application-specific chassis and payload configurations. Healthcare and cleanroom environments specify these for contamination control and temperature certification.
Fixed installation holds installed capacity across legacy automotive corridors. Flexible is rotating up the share rankings as vision-guided technology collapses brownfield deployment economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin American AGV procurement tilts toward import-dependent supply chains, with European and East Asian manufacturers capturing premium automotive contracts while local integrators dominate retrofit services. Trade flows concentrate through Brazilian and Mexican ports, reflecting regional manufacturing gravity.
Brazil
NR-12 workplace safety mandates from the national regulator accelerate forklift replacement in São Paulo's automotive corridor. ANVISA electromagnetic compatibility requirements narrow supplier pools for pharmaceutical logistics. Campinas and ABC Paulista industrial zones deploy vision-guided fleets for brownfield distribution centers.
Mexico
NOM-001-SCFI electrical safety standards mandate in-country certification testing for autonomous mobile robots. Mexico City and Guadalajara airport baggage systems face compressed compliance timelines under continuous-operation requirements. Nuevo León's electronics manufacturers favor unit load carriers for cleanroom component delivery.
Argentina
Magnetic tape legacy infrastructure locks automotive plants into maintenance-intensive guidance systems with limited upgrade pathways. National industrial safety frameworks impose additional certification layers for healthcare facility deployments. Córdoba's automotive suppliers retain laser-reflector installations despite higher maintenance burdens.
Colombia
Bogotá's cold-chain pharmaceutical hubs remain underpenetrated by autonomous material handling, offering first-mover positioning for temperature-certified platforms. The national pharmaceutical regulator enforces contamination control standards that favor customized chassis specifications. Medellín's logistics operators test limited flexible-installation pilots for seasonal volume elasticity.
Chile
Retail distribution networks show nascent adoption of AGV-as-a-service contracting, though contract sophistication lags Brazilian market maturity. Mining logistics operators test outdoor chassis configurations for ore concentrate movement in northern extraction zones. Santiago's warehousing sector concentrates procurement in climate-controlled indoor navigation systems.
Latin America Automated Guided Vehicle (AGV) Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and retrofit service density. The vendor base stratifies into three tiers: Stuttgart-engineered control architecture providers, airport baggage handling specialists, and digital platform integrators competing on predictive maintenance guarantees. Strategic moves center on ISO 3691-4 compliance retrofit partnerships and outcome-based fleet contracting models that shift revenue toward performance-linked subscriptions.
Within the premium-tier vector, KUKA Group and ABB Ltd anchor European-origin positioning in Brazilian automotive automation. Daifuku Co Ltd occupies a distinct position in Mexican airport logistics. These three exemplify how control architecture ownership and certification laboratory partnerships determine competitive access across NR-12 and NOM regulatory jurisdictions.
| Leading Market Players |
|---|
| KUKA Group |
| ABB Ltd |
| Schaefer Systems International Pvt Ltd |
| Jungheinrich Group |
| Dematic Group (KION) |
| Daifuku Co Ltd |
| Toyota Material Handling International AB |
| Bastian Solutions LLC |
| Hyster-Yale Materials Handling |
| Others |
Supply & Pricing Matrix
Long-term fleet service contracts anchor supply access and price visibility for Latin American warehousing operators, locking in lithium-ion battery sourcing corridors and certified maintenance technician pools across multi-year performance agreements. São Paulo's third-party logistics sector favors these arrangements to buffer against East Asian cell manufacturer lead time volatility and ISO 3691-4 compliance retrofit cost uncertainty.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structures across premium vision-guided platforms, standard laser-reflector systems, and economy magnetic-tape configurations. Price differentiation hinges on ISO 3691-4 safety integrity certification tier and after-sales uptime guarantee scope, with Brazilian automotive plants showing lowest price sensitivity due to NR-12 mandate-driven replacement urgency. Cost compression in the economy tier intensifies as Argentine facilities defer magnetic-tape infrastructure upgrades, while subscription-based fleet management models displace capital purchase pricing in Monterrey distribution centers.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production for Latin American AGV battery packs, with Japanese control system manufacturers supplying servo motors and programmable logic controllers. Raw material dependencies span cobalt cathode chemistries, rare-earth permanent magnets, and precision-machined aluminum extrusions. Single-source vulnerability concentrates in East Asian battery management system firmware, exposing Brazilian integrators to freight cost volatility and semiconductor foundry allocation constraints. Distribution runs through São Paulo and Mexico City port complexes, with Campinas and Nuevo León emerging as regional assembly and certification hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized calibration expertise for collision-avoidance sensor arrays remains scarce across Latin American system integrator networks, creating a persistent bottleneck that extends commissioning timelines and inflates project risk premiums for complex deployments.
For Market Incumbents: Consolidate certification laboratory partnerships across Brazilian ANVISA and Mexican NOM jurisdictions to compress compliance timelines for pharmaceutical and airport baggage handling verticals. Deepen backward integration into lithium-ion battery pack assembly to offset East Asian cell manufacturer allocation volatility and capture margin pools currently flowing to third-party powertrain integrators. For New Entrants and Emerging Players: Anchor in Bogotá's underpenetrated cold-chain pharmaceutical hubs, where temperature-certified AGV platforms face limited incumbent competition and ANVISA electromagnetic compatibility requirements narrow the supplier field. Pursue outcome-based fleet contracting models with São Paulo warehousing operators to bypass capital equipment purchase barriers and establish recurring revenue traction. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap system integrators possessing ISO 3691-4 retrofit expertise and established relationships with Brazilian automotive OEMs, positioning for consolidation as compliance mandates accelerate vendor rationalization. Monitor 5G private network deployment timelines in Mexican automotive corridors as an inflection signal for real-time fleet coordination capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 3691-4 Certification Partnership | Brazilian ANVISA and Mexican NOM compliance timelines compress competitive access for uncertified vendors. |
| Outcome-Based Fleet Contracting | São Paulo warehousing operators shift procurement from capital purchase to uptime-guaranteed subscription models. |
| Vision-Guided Navigation Retrofit | |
| Lithium-Ion Battery Backward Integration | In-house pack assembly reduces East Asian cell manufacturer dependency and freight cost exposure. |
| 5G Private Network Deployment | Ultra-reliable low-latency connectivity enables real-time fleet coordination in Mexican automotive plants. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at Brazilian automotive OEMs, warehouse operations directors in São Paulo and Monterrey, AGV system integrators, aftermarket service heads, and regulatory compliance officers at ANVISA and NOM certification bodies, then refined through secondary validation against customs trade data, SEC filings of listed automation vendors, ISO certification registries, and airport authority procurement records. Bottom-up fleet deployment estimates triangulated with top-down manufacturing automation spending forecasts across the analysis window.
Variance decomposition across navigation technology type, installation architecture flexibility, and end-use vertical penetration shaped the analytical framework over the projection horizon. CAGRs derived from segment-level unit economics and replacement cycle modeling incorporated lithium-ion battery cost curves, NR-12 and NOM regulatory enforcement intensity, and e-commerce fulfillment density indices for metropolitan São Paulo and Monterrey zones.
Material uncertainties — Mercosur-Pacific Alliance regulatory harmonization delays, East Asian semiconductor foundry allocation shocks, and Brazilian real exchange rate volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions on compliance timeline convergence and cell manufacturer capacity expansion. Recalibration cycles align with material shifts in NR-12 enforcement patterns and 5G private network deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Asia Pacific Automated Guided Vehicle (AGV) Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Telepresence Robotics Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Robotics-Ready Fulfillment Center Design and Integration Services Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Robot Pedestal Market
Robotics and Automation
Autonomous Mobile Robots for Logistics and Warehousing Market