
 Cognitive Robotic Process Automation Market | 2026-2036
Cognitive Robotic Process Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Robotic Process Automation Market Analysis
Buyer concentration in financial services is pivoting toward mid-market enterprises as cloud-based deployment lowers entry barriers. UiPath leverages extensive partner networks to sustain geographic reach across North America and Europe. Automation Anywhere anchors its position through R&D intensity in machine learning integration. Blue Prism specializes in regulated industries where governance requirements favor on-premises architectures.
Cognitive Robotic Process Automation fuses artificial intelligence with rule-based task automation, using natural language processing and computer vision to handle unstructured data inputs that traditional RPA cannot process. The technology automates judgment-intensive workflows in customer onboarding, claims adjudication, and procurement analysis. Cloud-based deployment leads segment growth as enterprises prioritize scalable infrastructure over capital-intensive data center builds. Machine learning capabilities within the technology segment command premium positioning due to their role in continuous process optimization. Financial services end users represent the deepest margin pool, though healthcare providers are gaining traction as clinical documentation automation matures.
The EU AI Act imposes risk-tiered compliance obligations on automated systems, forcing vendors to embed explainability features into cognitive automation platforms. FDA scrutiny of clinical decision support tools shapes healthcare adoption pathways in the United States. ISO standards for artificial intelligence management systems are emerging as baseline procurement criteria across regulated industries. Stakeholders must weigh algorithmic transparency investments against speed-to-deployment trade-offs as procurement criteria harden.
Market Dynamics
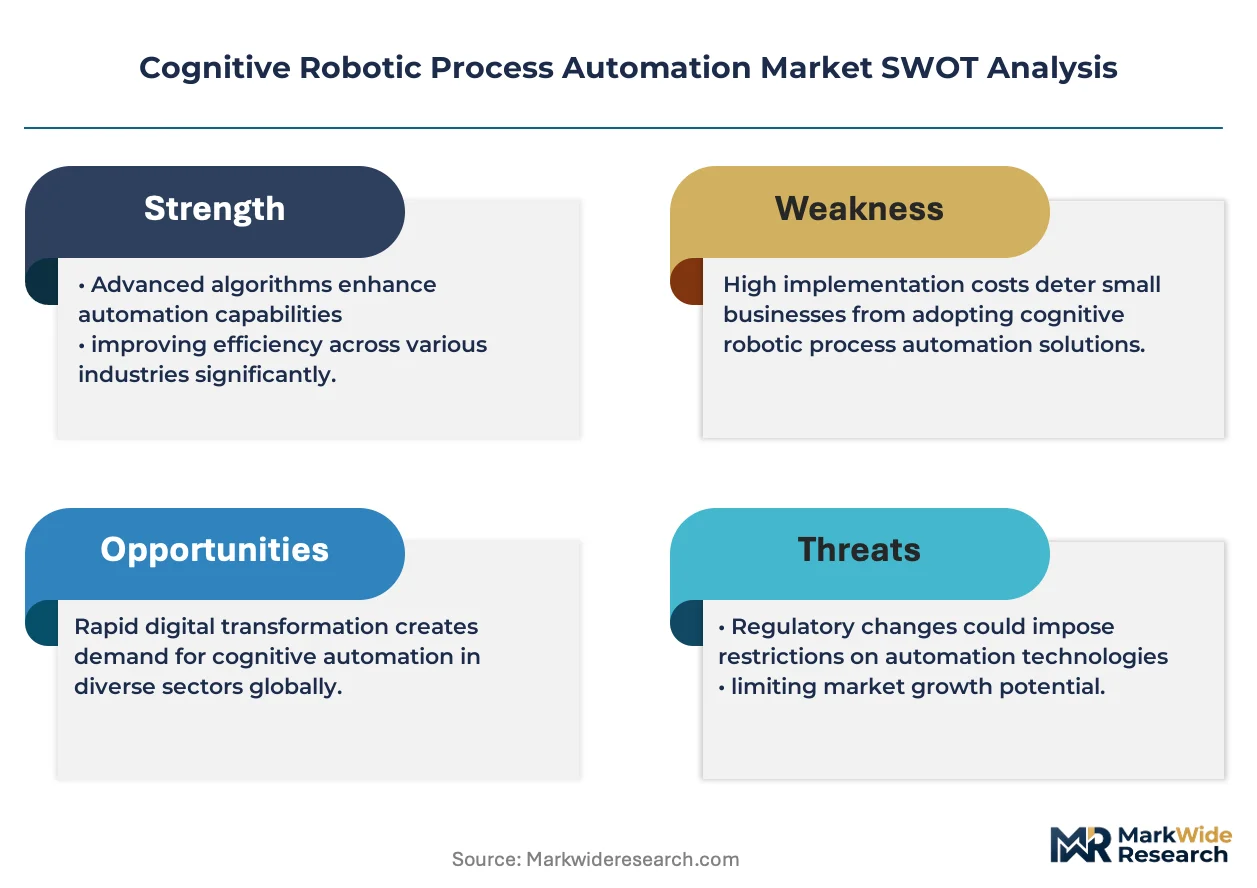
The EU AI Act's risk-tiered compliance framework is forcing vendors to embed explainability features directly into cognitive automation platforms, reshaping product architecture roadmaps across financial services and healthcare verticals.
Growth Catalysts
- Cloud-based deployment scalability:Mid-market enterprises in financial services are adopting subscription models that eliminate capital-intensive data center requirements.
- ISO/IEC 42001 artificial intelligence management systems:Standardized procurement criteria across regulated industries are accelerating vendor qualification cycles.
- Clinical documentation automation:Healthcare providers are deploying natural language processing for unstructured clinical data, expanding addressable workflow volume.
Market Restraints
- Algorithmic transparency investment costs:Explainability feature development consumes R&D budgets without immediate revenue offset.
- On-premises infrastructure lock-in:Regulated industries in Germany and Switzerland maintain legacy governance architectures that resist cloud migration.
- Technical debt in legacy ERP integration:Cognitive automation requires API connectivity to systems lacking modern interoperability layers.
Strategic Opportunities
- India's PLI scheme for IT hardware:Localized cloud infrastructure investment is reducing latency for Asia-Pacific deployment.
- Convergence of computer vision with process mining:Real-time workflow visualization is opening predictive maintenance applications in manufacturing.
- FDA 21st Century Cures Act digital health pathways:Streamlined clinical decision support tool approval is compressing healthcare go-to-market timelines.
Industry Challenges
- Machine learning operations (MLOps) talent scarcity:Model deployment and monitoring functions face recruitment bottlenecks in competitive labor markets.
- EU AI Act conformity assessment timelines:High-risk system certification delays product launches by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Robotic Process Automation Market |
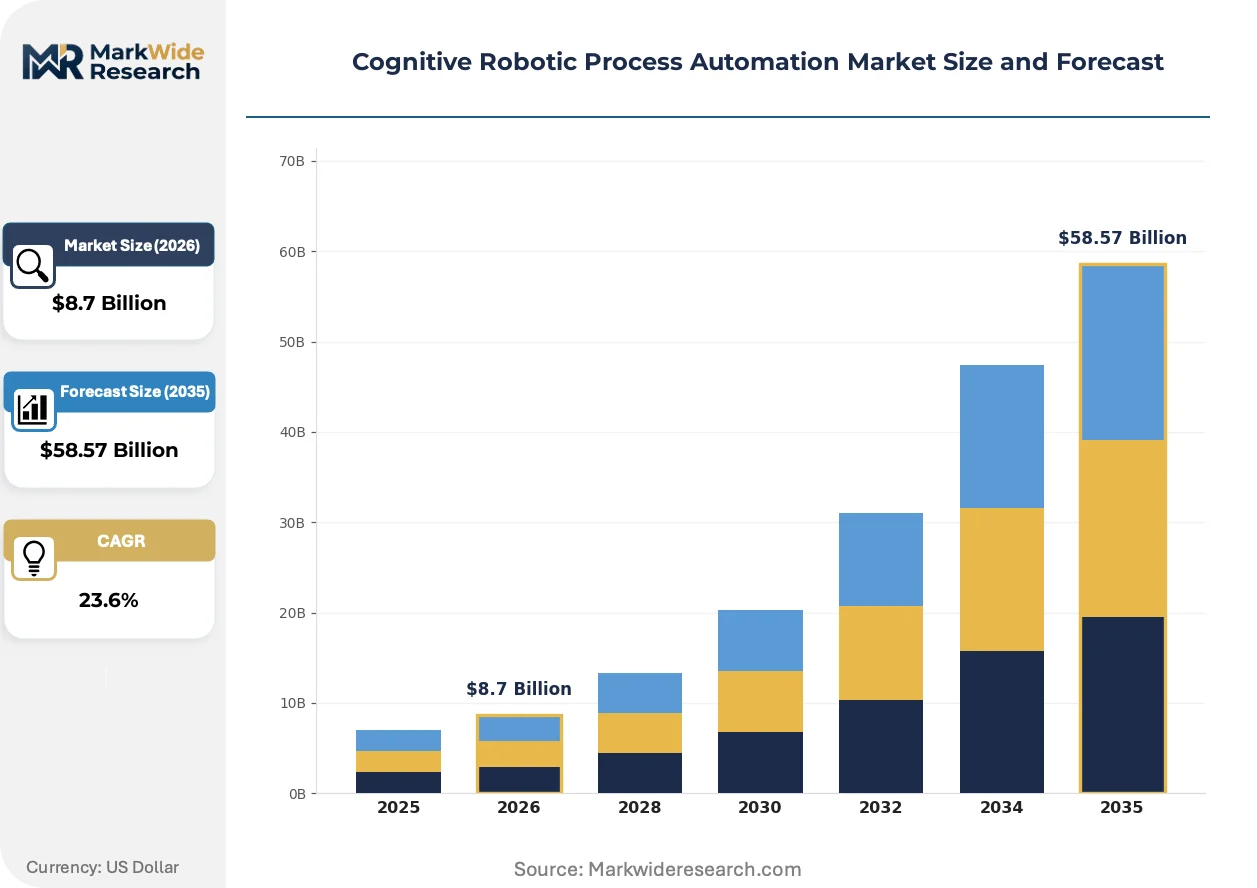
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
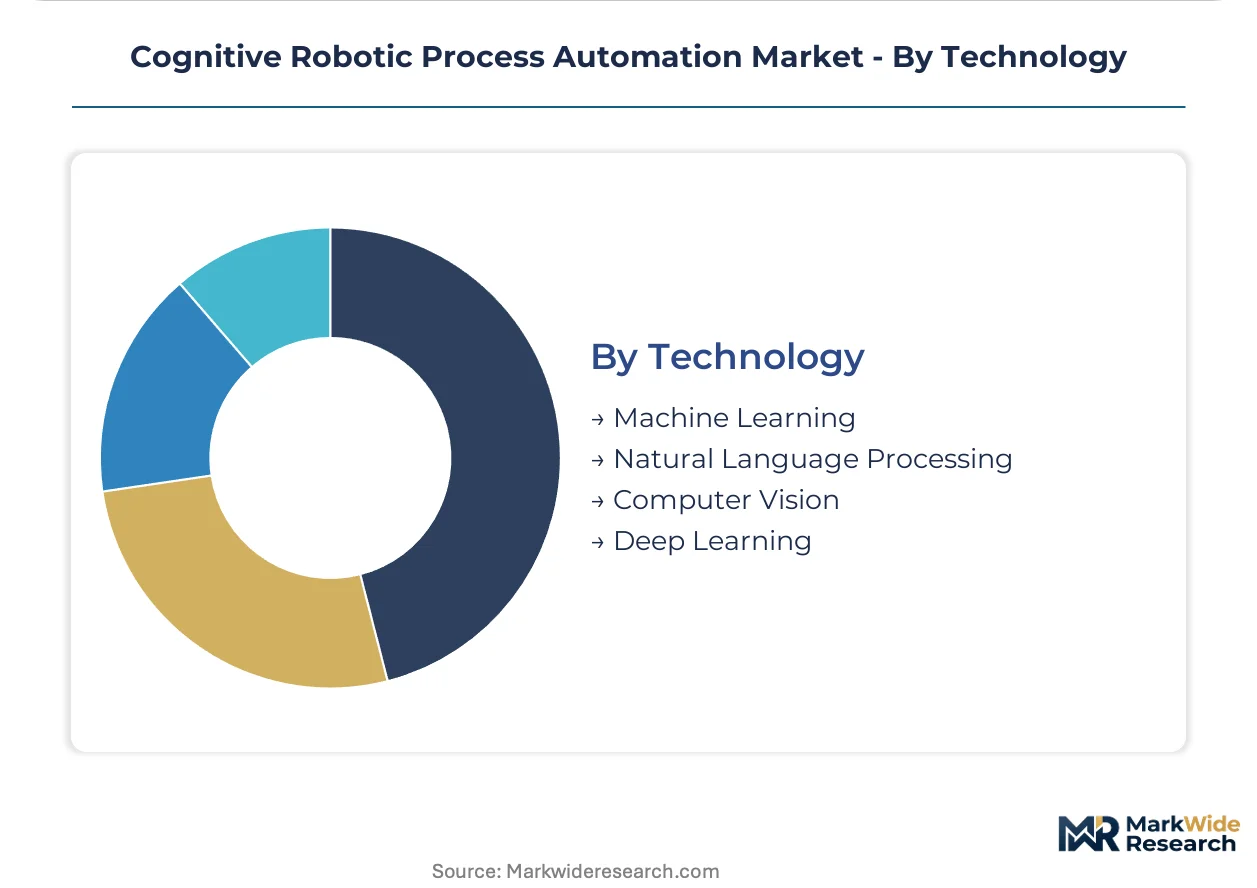
| Segmentation | Application: Data Entry, Customer Support, Invoice Processing, Document Management Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Financial Services, Retail Sector, Healthcare Providers, Manufacturing Firms Technology: Machine Learning, Natural Language Processing, Computer Vision, Deep Learning |
| Companies Covered | UiPath, Automation Anywhere, Blue Prism, NICE Systems, Pegasystems, IPsoft, Verint Systems, Kofax, WorkFusion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Robotic Process Automation Market Emerging Trajectories
Foundation model architectures are compressing development cycles for cognitive automation vendors, enabling smaller teams to deploy sophisticated natural language understanding without proprietary training infrastructure.
Large language models are integrating retrieval-augmented generation capabilities to ground automated decisions in verifiable enterprise knowledge bases. Financial services compliance teams are adopting these systems for real-time regulatory interpretation. The technology is integrating structured and unstructured data sources into unified workflow automation, collapsing previously separate RPA and AI procurement decisions.
The EU AI Act's high-risk system classification is mandating human-in-the-loop architectures for automated credit decisions and insurance underwriting. Vendors must now maintain audit trails demonstrating meaningful human oversight. Financial institutions in France and Germany are responding by restructuring governance committees to satisfy national regulator interpretations of the delegated acts.
Enterprise buyers are consolidating vendor relationships from point-solution RPA contracts toward platform-wide cognitive automation subscriptions. Systems integrators are displacing direct vendor relationships as primary procurement channels. This concentration is most visible in the United States, where Fortune 500 enterprises are reducing supplier counts from eight to three strategic automation partners.
Cognitive Robotic Process Automation Market Segmentation

Cognitive RPA vendors configure product architectures around four intersecting dimensions that determine pricing power and implementation complexity. Deployment mode and technology stack choices exert the strongest influence on margin structure, while application focus shapes customer acquisition costs.
Application:
Volume-heavy use cases dominate early adoption, though premium-margin workflows are gaining share as AI capabilities mature.
- Data Entry:Structured field population and validation across ERP systems, CRM platforms, and legacy databases. Manufacturing firms in the United States deploy this for production record digitization, constrained by brittle legacy system interfaces that resist API connectivity.
- Customer Support:Intent classification, response generation, and escalation routing for omnichannel service operations. Financial services contact centers in Germany concentrate demand here, driven by EU AI Act requirements for explainable decision trails in automated interactions.
- Invoice Processing:Extract-transform-load pipelines for accounts payable automation.
- Document Management:Classification, indexing, and retrieval for unstructured content repositories.
Mature deployment sits with Data Entry. Newer deployment is concentrated in Customer Support.
Deployment:
Cost tier separation runs from capital-intensive ownership to operational expenditure models that trade control for speed.
- Cloud-Based:Multi-tenant SaaS architectures with elastic compute scaling and vendor-managed infrastructure updates. Mid-market financial services enterprises in the United States favor this model, prioritizing rapid provisioning over data sovereignty.
- On-Premises:Air-gapped installations on customer-controlled hardware with full audit trail custody. Healthcare providers in Switzerland and Germany maintain this architecture, responding to national data residency laws and FDA-equivalent clinical system validation requirements.
- Hybrid:Sensitive processing on local infrastructure with burst capacity to public cloud.
- Managed Services:Vendor-operated private cloud with dedicated tenancy and SLA guarantees.
Cloud-Based deployment captures the steepest expansion trajectory. On-Premises retains the highest contract values per seat.
End User:
Customer type segmentation reveals divergent procurement sophistication and compliance burden intensity.
- Financial Services:Risk-weighted asset calculation, anti-money laundering screening, and regulatory reporting automation. Institutions in France and Germany anchor demand here, restructuring governance committees to satisfy national regulator interpretations of EU AI Act delegated acts.
- Healthcare Providers:Clinical documentation capture, prior authorization processing, and revenue cycle management. United States hospital systems drive adoption, navigating FDA 21st Century Cures Act digital health pathways for clinical decision support tools.
- Retail Sector:Supply chain visibility and demand forecasting automation.
- Manufacturing Firms:Quality inspection integration and predictive maintenance orchestration.
Financial Services commands the deepest margin pool. Healthcare Providers are climbing the fastest as NLP clinical documentation matures.
Technology:
Supply concentration in foundation model development is compressing differentiation timelines for proprietary cognitive engines.
- Machine Learning:Supervised and unsupervised model training on enterprise-specific process data for continuous optimization. Financial services compliance teams in the United States deploy this for real-time regulatory interpretation, embedding retrieval-augmented generation to ground decisions in verifiable knowledge bases.
- Natural Language Processing:Named entity recognition, sentiment analysis, and document understanding for unstructured text. Healthcare providers concentrate demand here, automating clinical narrative capture to reduce physician administrative burden.
- Computer Vision:Image classification, object detection, and optical character recognition for visual inputs.
- Deep Learning:Neural network architectures for pattern recognition in high-dimensional data.
Machine Learning represents the most defensible platform layer. Natural Language Processing is expanding most quickly as large language model integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise IT modernization budgets in the United States attract the deepest concentration of cognitive RPA deployment, though regulatory complexity in France and Germany is accelerating vendor qualification cycles. Cloud infrastructure investment in India and clinical automation demand in Switzerland are expanding addressable market boundaries.
United States
Fortune 500 enterprises are consolidating vendor relationships from eight to three strategic automation partners, compressing procurement channels. FDA 21st Century Cures Act digital health pathways streamline clinical decision support tool approvals for healthcare providers. Hospital systems in Boston and the San Francisco Bay Area deploy natural language processing for clinical documentation capture.
Germany
Financial institutions restructure governance committees to satisfy national regulator interpretations of EU AI Act delegated acts. The Federal Financial Supervisory Authority enforces risk-tiered compliance obligations on automated credit decision systems. Frankfurt-based banking clusters maintain on-premises architectures for audit trail custody requirements.
France
Insurance underwriting automation faces mandatory human-in-the-loop architectures under EU AI Act high-risk system classifications. The Commission Nationale de l'Informatique et des Libertés scrutinizes algorithmic accountability in automated customer interactions. Parisian financial services contact centers concentrate demand for explainable decision trail capabilities.
Switzerland
Healthcare providers maintain air-gapped installations responding to national data residency laws and Swissmedic clinical system validation requirements. The Swiss Agency for Therapeutic Products shapes adoption pathways for prior authorization processing automation. Zurich hospital systems anchor demand for revenue cycle management solutions.
India
The Production Linked Incentive scheme for IT hardware reduces latency for Asia-Pacific cloud infrastructure deployment. Mid-market enterprises adopt subscription models eliminating capital-intensive data center requirements. Bengaluru technology clusters support machine learning operations talent pipelines for model deployment functions.
Cognitive Robotic Process Automation Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue retrieval-augmented generation integration for regulatory interpretation workflows. The vendor base separates into three concentration tiers: platform-wide cognitive automation subscriptions, point-solution RPA contracts, and systems integrator channels displacing direct relationships. Strategic archetypes include cloud-native SaaS architects, on-premises governance specialists, and hybrid deployment orchestrators. Competitive moves center on partner network expansion and explainability feature embedding.
Within the platform-tier segment, UiPath leverages extensive geographic reach across North America and Europe through partner ecosystems. Automation Anywhere anchors machine learning integration intensity in product roadmaps. Blue Prism exemplifies regulated industry specialization where governance requirements favor on-premises architectures.
| Leading Market Players |
|---|
| UiPath |
| Automation Anywhere |
| Blue Prism |
| NICE Systems |
| Pegasystems |
| IPsoft |
| Verint Systems |
| Kofax |
| WorkFusion |
| Others |
Supply Flow & Price Mechanics
Machine learning operations talent concentration in Bengaluru and the San Francisco Bay Area drives labor-cost differentials that widen pricing-tier spreads between premium cognitive automation platforms and economy-tier rule-based alternatives.
Pricing Analysis
Volume-heavy data entry automation competes on per-seat economics while machine learning-enabled compliance workflows command subscription premiums. Pricing stratifies across premium, standard, and economy tiers based on explainability certification level and customization depth. Cost compression in the economy tier intensifies because foundation model APIs commoditize basic natural language processing capabilities. Mid-market financial services enterprises exhibit highest price sensitivity; healthcare providers in Switzerland and Germany show lowest sensitivity due to regulatory-mandated on-premises requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries supplying GPU clusters for model training infrastructure. Hardware dependencies draw from NVIDIA accelerator supply, cloud hyperscaler compute allocation, and specialized optical interconnect components. Tariff exposure on Chinese-manufactured server hardware compounds logistics chokepoints through Singapore and Rotterdam port congestion. Distribution runs through systems integrator channels that displace direct vendor relationships in Fortune 500 procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cognitive RPA market occupies a technology-transition phase where retrieval-augmented generation architectures displace legacy rule-based automation engines.
For Market Incumbents: Extend explainability feature roadmaps to satisfy EU AI Act conformity assessment timelines before high-risk system certification delays erode competitive position. Anchor machine learning integration intensity through backward integration into proprietary training data pipelines. Consolidate partner networks in France and Germany where national regulator interpretations of delegated acts favor established governance frameworks.
For New Entrants and Emerging Players: Enter via clinical documentation automation for mid-market United States hospital systems navigating FDA 21st Century Cures Act digital health pathways. Target Switzerland and Germany healthcare providers with air-gapped deployment expertise that incumbent cloud-native vendors underinvest in. Pursue systems integrator co-development agreements rather than direct enterprise sales.
For Investors and Strategic Acquirers: Re-rating potential sits with hybrid deployment orchestrators given EU AI Act risk-tiered compliance obligations forcing architectural complexity. Long-term viability favors vendors with sustainable MLOps talent pipelines and ISO/IEC 42001 certification momentum. Monitor FDA 21st Century Cures Act enforcement patterns as inflection indicator for healthcare automation addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies RPA and AI procurement decisions collapsing previously separate vendor relationships. |
| Strategic Partnership | Systems integrator alliances displace direct channels in Fortune 500 consolidation from eight to three partners. |
| Acquisition of Specialist Firm | Targets computer vision expertise for manufacturing predictive maintenance applications. |
| Geographic Expansion | India PLI scheme localization reduces Asia-Pacific cloud infrastructure latency. |
| Product Launch | Human-in-the-loop architectures satisfy EU AI Act high-risk system audit trail mandates. |
Methodological Framework
Document review covered SEC filings from automation platform vendors, EU AI Act delegated act drafts, and FDA 21st Century Cures Act guidance documents, complemented by interviews with CTOs at financial services institutions, IT procurement officers at German healthcare providers, platform engineers at cloud hyperscalers, and integration specialists at systems integrators. Secondary validation drew from ISO/IEC 42001 certification databases, hospital procurement contract registries, and customs records for IT hardware trade flows. Bottom-up deployment estimates triangulated against top-down enterprise IT modernization budget allocations.
Market size outputs reflect segmentation across deployment mode, technology stack, end-user vertical, and application workflow complexity throughout the forecast period. CAGRs derived from elasticity modeling of cloud infrastructure investment cycles and regulatory compliance spending patterns. Industry-specific inputs included EU AI Act conformity assessment timeline distributions and FDA digital health pathway approval velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act delegated act implementation delays or foundation model supply disruptions. Projections assume continued cloud migration momentum in mid-market enterprises and stable hyperscaler capex allocation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Global Indoor Robots Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Robot Fleet Management Software Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
AGV Intelligent Management Systems Market
Robotics and Automation
Autonomous Security Robots Market
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
Global Molecular Robotics Market