
 Europe AUV Market | 2026-2036
Europe AUV Market Size, Share, and Industry Trends Forecast 2026-2036
Europe AUV Market Foresight
The EU Green Deal is realigning offshore survey procurement toward low-carbon autonomous platforms across European waters. Kongsberg Maritime leverages its integrated sonar manufacturing to dominate Norway's offshore energy corridor. Exail Technologies anchors French defence and scientific demand through specialized navigation systems. Fugro competes on global service scale while sustaining strong North Sea operational density.
An autonomous underwater vehicle (AUV) is a self-propelled, untethered submersible operating on pre-programmed missions without real-time human control, typically rated to depths from 100 to 6,000 meters depending on hull construction and pressure vessel design; its primary purpose is to execute seabed mapping, infrastructure inspection, and environmental data collection in areas where tethered systems face operational constraints or where human divers cannot operate safely. Among product types, hybrid AUVs that combine autonomous transit with remote intervention capability capture expanding margin pools as offshore operators seek dual-mode flexibility. On the application dimension, hydrographic surveying retains volume leadership while underwater inspection gains fastest growth as ageing North Sea pipelines require accelerated integrity assessment.
EMA's maritime equipment standards, the EU Green Deal's emissions benchmarks, and REACH chemical compliance for pressure-resistant coatings collectively shape product certification timelines and market access conditions for AUV manufacturers serving European buyers. ECHA restrictions on specific antifouling compounds are forcing hull material redesigns that add development cost but create regulatory moats for compliant suppliers. Stakeholders must monitor how CSRD disclosure requirements reshape procurement criteria for publicly listed energy and defence contractors across the continent.
Market Dynamics
North Sea offshore energy operators are accelerating AUV fleet expansion to address ageing pipeline integrity mandates, while REACH chemical compliance and ECHA antifouling restrictions are compressing product development timelines for hull manufacturers across European supply chains.
Growth Catalysts
- EU Green Deal procurement realignment:Publicly listed energy contractors face CSRD disclosure requirements that favor low-emission survey platforms, redirecting capital toward battery-electric AUV systems.
- Subsea infrastructure age profile:North Sea pipeline networks installed during the 1970s-1980s offshore boom require systematic integrity assessment that tethered ROVs cannot deliver cost-effectively.
- Stavanger-Bergen technology cluster:Concentrated subsea engineering expertise in Norway's western fjord region enables rapid prototype-to-deployment cycles for autonomous inspection systems.
Market Restraints
- Lithium-ion battery supply concentration:European AUV manufacturers remain dependent on East Asian cell suppliers, exposing production schedules to maritime shipping volatility and raw material price swings.
- Pressure vessel steel alloy costs:High-grade titanium and aluminum alloys rated for 3,000+ meter depths face aerospace and defense demand competition, squeezing hull fabrication margins.
- REACH coating compliance friction:ECHA restrictions on specific biocide compounds force reformulation of pressure-resistant antifouling layers, extending certification timelines by 12-18 months.
Strategic Opportunities
- Portuguese and Spanish Atlantic offshore wind:Pre-construction seabed survey demand along the Iberian continental shelf remains underserved by established North Sea service providers.
- Hybrid AUV-ROV convergence:Dual-mode platforms combining autonomous transit with intervention capability command premium positioning in decommissioning contracts.
- EMA maritime equipment harmonization:Standardized certification pathways across EU member states reduce market entry costs for specialized navigation system suppliers.
Industry Challenges
- Subsea autonomy software talent scarcity:Machine learning engineers with marine robotics experience concentrate in Norway and France, constraining development capacity elsewhere in Europe.
- Legacy ROV fleet integration complexity:Offshore operators face technical debt from decades of tethered system investment that resists rapid autonomous platform substitution.
- Extended pressure testing protocols:Deep-rated hull validation requires specialized North Atlantic test facilities with limited slots, bottlenecking new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe AUV Market |
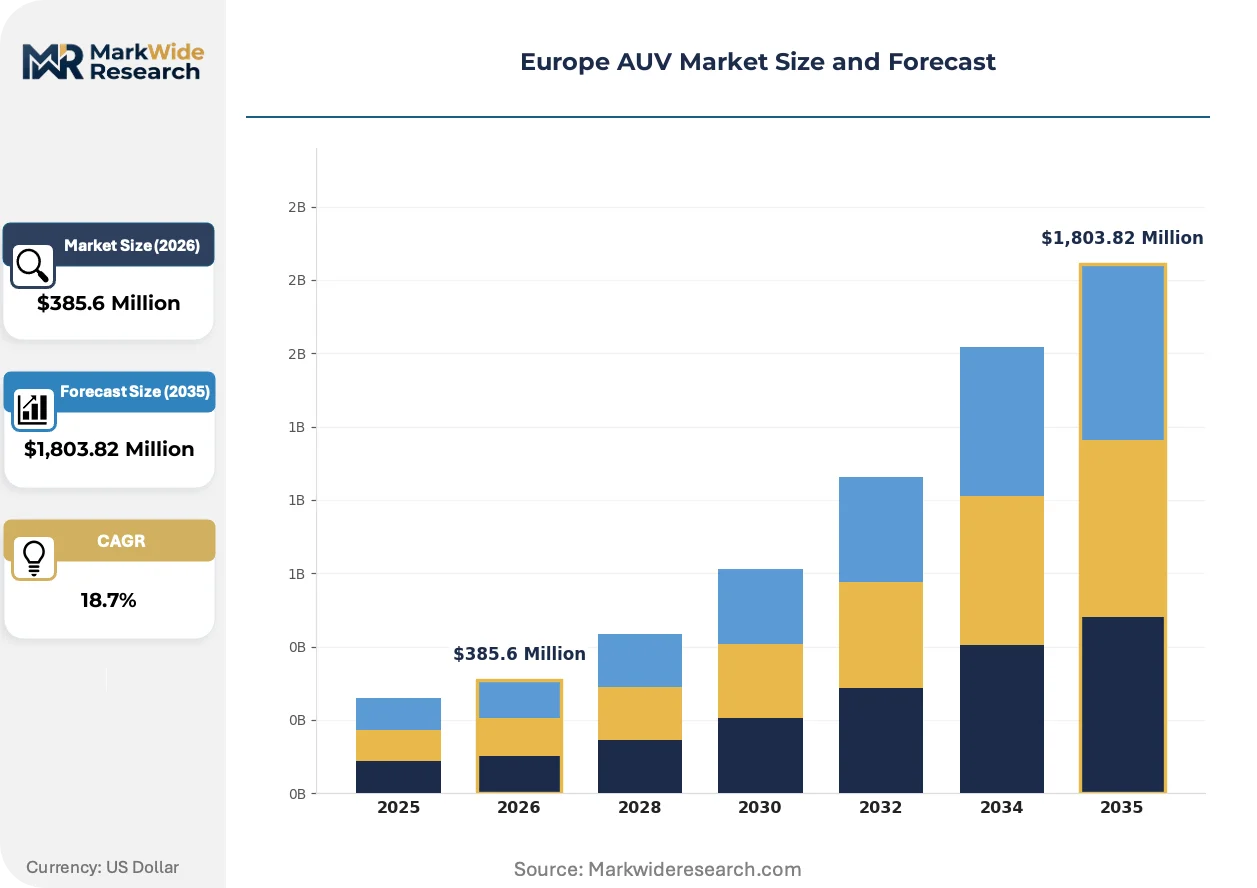
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Surface Vehicles, Remotely Operated Vehicles, Hybrid AUVs, Natural Environment AUVs End User: Research Institutions, Oil & Gas Companies, Defence Agencies, Environmental Monitoring Services Application: Marine Research, Hydrographic Surveying, Underwater Inspection, Fisheries Management Technology: GPS Navigation, Sonar Imaging, Artificial Intelligence, Communication Systems |
| Companies Covered | Exail Technologies, Fugro, Kongsberg Maritime, SeaRobotics, Atlas Elektronik, Saab AB, Saipem S.p.A., ECA Group, BAE Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe AUV Market Shifts & Advancements
Autonomous underwater vehicle architecture is pivoting toward modular payload systems that accommodate mission-specific sensor swaps without dry-dock intervention, compressing deployment timelines for multi-contract operators.
Synthetic aperture sonar is converging with real-time edge computing architectures to deliver centimetric seabed resolution during autonomous transit, eliminating post-mission data processing delays that previously required shore-based supercomputing. Norwegian offshore energy contractors are adopting these integrated systems for live pipeline anomaly detection, collapsing the inspection-to-decision cycle from weeks to hours. This capability compression is reshaping contract structures toward continuous monitoring subscriptions rather than discrete survey procurement.
CSRD disclosure requirements are mandating granular emissions reporting from publicly listed energy and defense contractors, forcing procurement departments to document carbon intensity across subsea service supply chains. AUV operators with battery-electric platforms and renewable-powered support vessels gain preferential positioning in tender evaluations. French and German utilities are advancing this screening fastest, with Scandinavian state energy enterprises following through national climate plan procurement directives.
Energy majors are unbundling integrated survey contracts into discrete data-as-a-service agreements that transfer ownership of raw sensor outputs to the contractor while retaining interpretation rights. This decoupling shifts capital burden toward AUV fleet operators and rewards platforms with standardized data formats compatible with cloud-based analytics pipelines. The model is consolidating fastest in UK and Dutch North Sea operations where joint venture structures complicate traditional asset-based contracting.
Europe AUV Market Segmentation
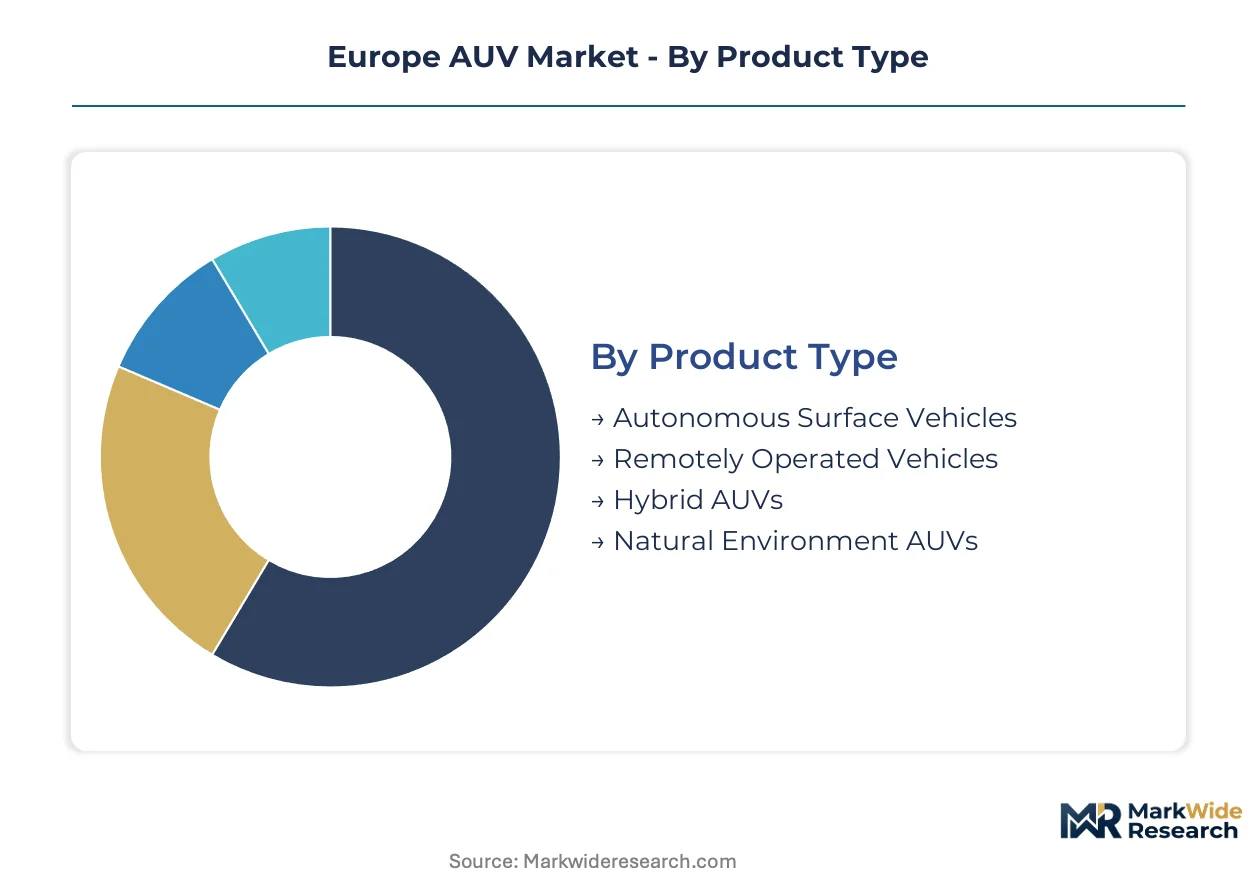
Segmentation in the Europe AUV Market reveals how procurement criteria diverge across buyer types, from defence agencies prioritizing navigation precision to offshore energy operators seeking dual-mode operational flexibility. Understanding these fault lines enables suppliers to align pressure vessel specifications and payload architectures with contract-specific performance thresholds.
Product Type:
Buyers in this category separate by operational depth requirements and tether dependency tolerance, with North Sea energy contractors favouring platforms that eliminate surface vessel constraints.
- Hybrid AUVs:These platforms combine autonomous transit with remote intervention capability through detachable tether modules. Offshore decommissioning contractors in the UK and Norwegian sectors are consolidating procurement around these systems to collapse mobilisation costs between inspection and intervention tasks.
- Natural Environment AUVs:Biomimetic hull designs optimised for low acoustic signature and adaptive buoyancy control. Research institutions in France and Germany are deploying these for long-duration ecosystem monitoring where conventional propulsion disturbs sensitive benthic habitats.
- Autonomous Surface Vehicles:Surface-tethered sensor platforms with limited subsea endurance, primarily serving coastal bathymetry contracts in the Baltic and Mediterranean.
- Remotely Operated Vehicles:Tether-dependent systems retaining dominance in heavy intervention work where real-time operator control outweighs mobility advantages.
Hybrid AUVs lead volumes today; Natural Environment AUVs are gaining share fastest.
End User:
Procurement scale and certification stringency diverge sharply across this dimension, with defence and energy buyers driving divergent technology roadmaps.
- Oil & Gas Companies:Integrated majors and independents operating North Sea assets. These buyers are shifting from owned-fleet models to contracted survey services, pressuring suppliers to demonstrate CSRD-aligned emissions credentials alongside technical performance.
- Defence Agencies:Naval procurement authorities in France, Norway, and the UK. Mine countermeasures and seabed warfare applications are displacing legacy sonar systems, with specifications mandating interoperability with NATO underwater communication protocols.
- Research Institutions:Oceanographic institutes and university consortia. Funding cycles tied to EU Horizon programmes and national research councils create lumpy demand concentrated in French, German, and Spanish coastal facilities.
- Environmental Monitoring Services:Emerging contractors serving offshore wind developers and marine protected area authorities. REACH compliance for hull coatings and ECHA biocide restrictions are extending their vendor qualification timelines.
Oil & Gas Companies anchor current procurement volumes; Environmental Monitoring Services show the steepest expansion trajectory.
Application:
Data latency requirements and regulatory inspection frequencies determine platform selection here, with real-time decision-making needs reshaping sensor integration priorities.
- Underwater Inspection:Pipeline integrity assessment, subsea structure survey, and decommissioning site characterisation. Norwegian operators are deploying synthetic aperture sonar with edge computing to compress anomaly detection from weeks to hours.
- Hydrographic Surveying:Seabed mapping for nautical charting and offshore wind site preparation. UK and Dutch authorities are consolidating contracts around continuous monitoring subscriptions rather than discrete survey procurement.
- Marine Research:Deep-ocean sampling and benthic ecosystem studies. Pressure vessel ratings for 3,000+ metre depths concentrate demand with specialised fabricators in Norway and France.
- Fisheries Management:Stock assessment and habitat mapping for quota-setting authorities. Mediterranean and Celtic Sea applications are expanding as national agencies automate acoustic survey programmes.
Hydrographic Surveying retains volume leadership; Underwater Inspection is climbing the fastest.
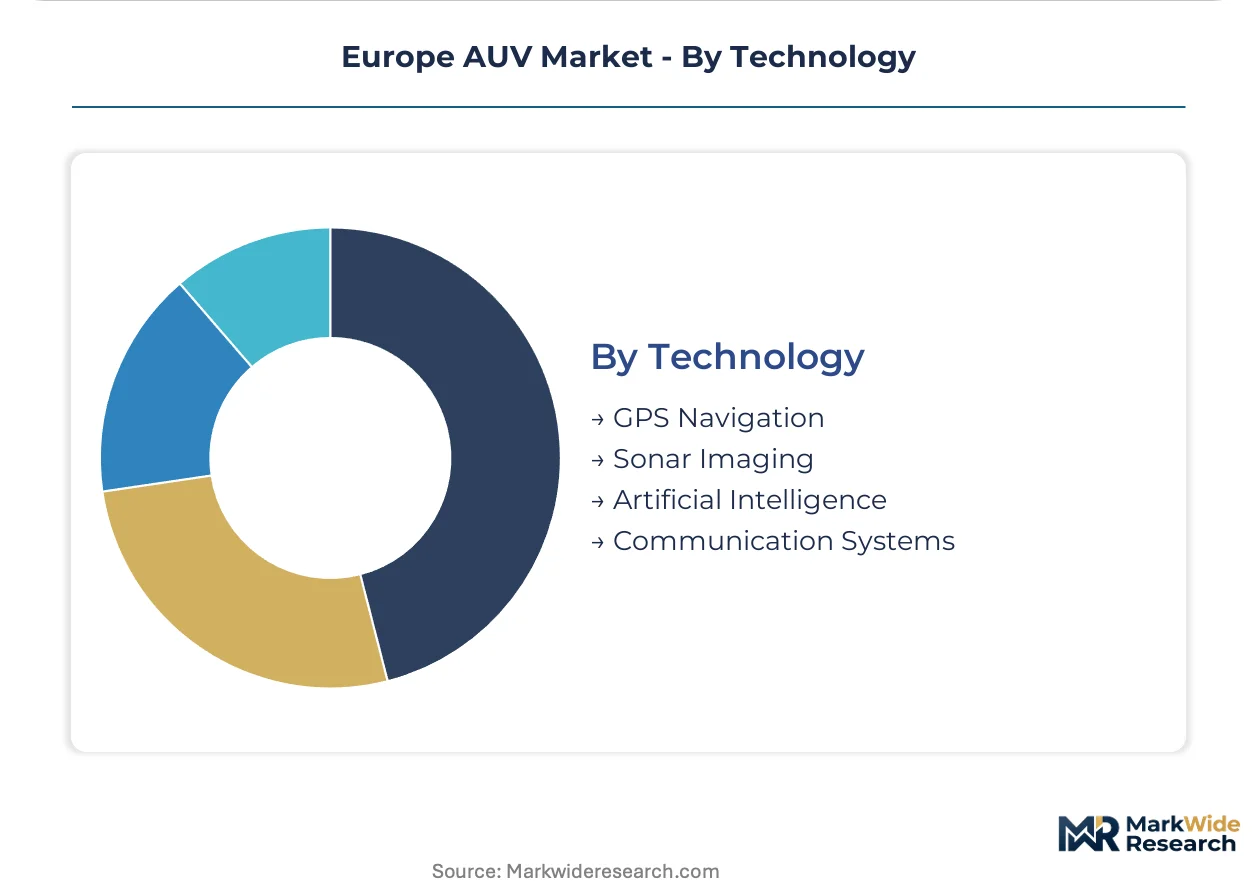
Technology:
Integration maturity and supply chain control differentiate technology choices, with European suppliers seeking to reduce dependency on non-EU component sources.
- Sonar Imaging:Synthetic aperture and multibeam systems for centimetric seabed resolution. Kongsberg Maritime's integrated manufacturing in Norway dominates supply to North Sea energy contractors.
- Artificial Intelligence:Autonomous navigation, anomaly detection, and mission replanning algorithms. Talent scarcity in marine robotics machine learning concentrates development capacity in Stavanger-Bergen and Toulon clusters.
- GPS Navigation:Surface-localised positioning with underwater acoustic relay. Limited to shallow-water applications where satellite signal penetration supports hybrid tracking.
- Communication Systems:Acoustic modem and optical data link architectures. Standardisation under EMA maritime equipment directives is reducing certification friction across EU member states.
Sonar Imaging commands the largest installed base; Artificial Intelligence is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Autonomous underwater vehicle development traces its commercial roots to Norwegian North Sea oil exploration in the 1980s, when Statoil and Kongsberg collaborated to reduce diver-dependent inspection costs. This heritage continues to concentrate European AUV manufacturing and service expertise along a narrow coastal corridor from Stavanger to Toulon.
Norway
North Sea decommissioning mandates and offshore wind site preparation drive fleet expansion among Stavanger-based energy contractors. The Norwegian Maritime Authority enforces strict pressure vessel certification protocols that extend product development timelines but create regulatory barriers for non-compliant imports. Bergen's subsea technology cluster hosts concentrated synthetic aperture sonar integration facilities serving both oil majors and emerging wind developers.
United Kingdom
Ageing pipeline networks in the UK Continental Shelf require accelerated integrity assessment that autonomous platforms deliver more cost-effectively than tethered alternatives. The North Sea Transition Authority's decommissioning timelines compress procurement cycles for inspection contractors. Aberdeen maintains operational density through decades of ROV service heritage now converting toward autonomous fleet models.
France
Naval mine countermeasures procurement and scientific oceanography funding sustain dual demand tracks for Toulon-based manufacturers. The Direction Générale de l'Armement specifies interoperability requirements with NATO underwater communication standards that shape product architecture decisions. Brest's Ifremer consortium anchors deep-ocean research applications requiring 6,000-meter rated pressure vessels.
Germany
Offshore wind seabed survey demand in the Baltic and North Sea accelerates as auction rounds expand lease areas. The Federal Maritime and Hydrographic Agency consolidates hydrographic contracting around continuous monitoring service models rather than discrete survey procurement. Kiel's GEOMAR Helmholtz Centre concentrates deep-sea research platform development with EU Horizon programme funding.
Netherlands
Port of Rotterdam subsea infrastructure maintenance and North Sea wind farm interconnection cable surveys sustain steady platform utilization. The Netherlands Enterprise Agency coordinates cross-border procurement with German and Danish counterparts under EU Green Deal alignment frameworks. Delft's maritime robotics research cluster feeds engineering talent into commercialization pipelines at nearby North Sea service hubs.
Europe AUV Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth ratings and integrated sensor manufacturing capabilities. The vendor base stratifies between full-stack platform builders and specialized component suppliers, with the former capturing recurring service revenue and the latter facing price pressure from Asian electronics imports. Three archetypes dominate: integrated sonar manufacturers with captive hull production, autonomous navigation specialists licensing software stacks, and global survey contractors operating mixed ROV-AUV fleets. Competitive moves concentrate on backward integration into pressure vessel fabrication and strategic partnerships with offshore wind developers securing multi-year site characterization contracts.
Among Norway-based integrated manufacturers, Kongsberg Maritime anchors the premium tier through combined sensor and platform production. Exail Technologies occupies a specialist position in navigation and acoustic systems serving both defence and scientific end users. Fugro exemplifies the global service contractor archetype with dense North Sea operational presence and expanding autonomous fleet deployment.
| Leading Market Players |
|---|
| Exail Technologies |
| Fugro |
| Kongsberg Maritime |
| SeaRobotics |
| Atlas Elektronik |
| Saab AB |
| Saipem S.p.A. |
| ECA Group |
| BAE Systems |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in subsea services have consolidated inspection fleets across the North Sea, compressing procurement timelines while anchoring pricing discipline to CSRD-aligned emissions credentials rather than hourly rates alone. This ownership pattern concentrates bargaining power with Stavanger-Bergen contractors who bundle platform provision with data interpretation, squeezing margins for standalone hull manufacturers dependent on spot orders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates deep-rated titanium-hull platforms certified to 6,000 meters from aluminum-hull systems rated to 3,000 meters and coastal bathymetry units. Price differentiation rests on pressure vessel certification depth and integrated sonar manufacturing rather than hull fabrication alone. Cost compression in the standard tier is intensifying because REACH-compliant coating reformulations add 12-18 months to qualification timelines. Environmental Monitoring Services exhibit the highest price sensitivity as EU-funded research cycles constrain capital flexibility, while Defence Agencies accept premium positioning for NATO-interoperable navigation systems.
Supply Chain Analysis
Dual-sourcing requirements from Norwegian Maritime Authority pressure vessel protocols and EU Green Deal procurement mandates force hull fabricators to qualify secondary titanium and aluminum alloy suppliers beyond their primary East Asian channels. Geographic supply concentration centers on China and South Korea for lithium-ion battery cells, Norway and France for high-grade titanium alloys, and Germany for precision navigation components. Single-source vulnerability in East Asian cell supply exposes production schedules to maritime shipping volatility. Distribution runs through Stavanger-Bergen technology clusters for platform integration, with final deployment managed by Aberdeen and Rotterdam service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on synthetic aperture sonar integration with edge computing architectures, collapsing inspection-to-decision cycles from weeks to hours and enabling subscription-based revenue capture.
For Market Incumbents: Acquire synthetic aperture sonar integration facilities to defend against pure-play navigation specialists encroaching on data interpretation revenue. Secure backward integration into REACH-compliant pressure vessel fabrication before ECHA coating restrictions extend competitor lead times. Stavanger-Bergen cluster proximity remains the critical lever for rapid prototype-to-deployment cycles. For New Entrants and Emerging Players: Autonomous navigation software with marine robotics machine learning expertise offers the most penetrable wedge against talent-scarce incumbents. Target Portuguese and Spanish Atlantic offshore wind pre-construction surveys where established North Sea service providers maintain limited presence. Lead with standardized data formats compatible with cloud-based analytics pipelines to accelerate utility procurement cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among natural environment AUV specialists with biomimetic hull patents and EU Horizon programme funding visibility. Long-term viability favors platforms serving decommissioning mandates and continuous monitoring subscriptions over discrete survey contractors. Watch for CSRD disclosure enforcement accelerating procurement realignment toward battery-electric fleets as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Aperture Sonar Integration | Norwegian operators compress anomaly detection timelines from weeks to hours through edge computing convergence. |
| REACH-Compliant Coating Investment | ECHA biocide restrictions create regulatory moats for suppliers with pre-qualified pressure-resistant formulations. |
| Hybrid AUV-ROV Platform Development | UK and Norwegian decommissioning contractors consolidate procurement around dual-mode operational flexibility. |
| Portuguese-Spanish Atlantic Expansion | Iberian offshore wind site preparation remains underserved by established North Sea service providers. |
| Continuous Monitoring Subscription Model | UK and Dutch authorities unbundle integrated contracts into data-as-a-service agreements transferring capital burden to operators. |
Research Methodology
Coverage spans Norway, the United Kingdom, France, Germany, and the Netherlands, with primary inputs from each national offshore energy corridor. The analysis combines structured interviews with subsea engineering directors, offshore wind procurement leads, naval mine countermeasures programme managers, and maritime robotics R&D heads with secondary validation through EMA maritime equipment directives, ECHA restriction dossiers, EU Green Deal procurement frameworks, and national decommissioning authority timelines. Bottom-up fleet deployment counts and top-down energy contractor expenditure patterns undergo triangulation against CSRD disclosure filings.
Rate-of-change decomposition separates volume growth in platform deployments from value expansion in integrated sensor and software content across the analysis window. Segmentation dimensions modelled include product type depth ratings, end-user procurement stringency, application data latency requirements, and technology integration maturity. CAGRs derive from scenario-weighted projections of North Sea pipeline integrity mandates, Baltic and North Sea offshore wind auction rounds, and naval modernisation programme allocations. Industry-specific inputs incorporate pressure vessel certification queue lengths and synthetic aperture sonar adoption curves.
The model holds under sustained EU Green Deal enforcement and REACH compliance timelines; deviation in lithium-ion battery supply disruption or EMA harmonisation delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
Global Delivery Robots Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
Underwater Jetpack Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
Latin America Warehouse Robotics Market