
 Asia Pacific Automotive Navigation System Market | 2026-2036
Asia Pacific Automotive Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive Navigation System Market Outlook
The OEM-direct supply channel is narrowing as Japanese and Korean automakers consolidate Tier-1 vendor panels for embedded navigation modules. Denso Corporation anchors production scale through its Nagoya-centered manufacturing network. Pioneer Corporation differentiates through aftermarket channel control across Indonesia and Thailand. Harman International competes on software-defined cockpit integration for premium vehicle programs.
An automotive navigation system integrates satellite receivers, digital map databases, route computation engines, and human-machine interfaces to deliver real-time positioning and guidance to vehicle operators; core specifications include multi-constellation GNSS reception with sub-meter accuracy and offline map caching for connectivity gaps. Embedded Systems dominate factory-installed revenue pools across Japanese and Korean OEM lines, while Connected Systems represent the fastest-expanding segment as over-the-air map updates and cloud-based routing displace static storage. BeiDou technology leads technology adoption within China due to regulatory mandates, whereas GPS-GLONASS dual-mode architectures sustain aftermarket demand in Australia and Southeast Asia.
Japan's METI enforces JIS standards for in-vehicle electromagnetic compatibility, while China's MIIT mandates BeiDou chipset integration for domestic type approval. Australia's ACMA regulates spectrum allocation for GNSS augmentation services affecting aftermarket device certification. Stakeholders must weigh localization requirements against module standardization when configuring regional product portfolios.
Market Dynamics
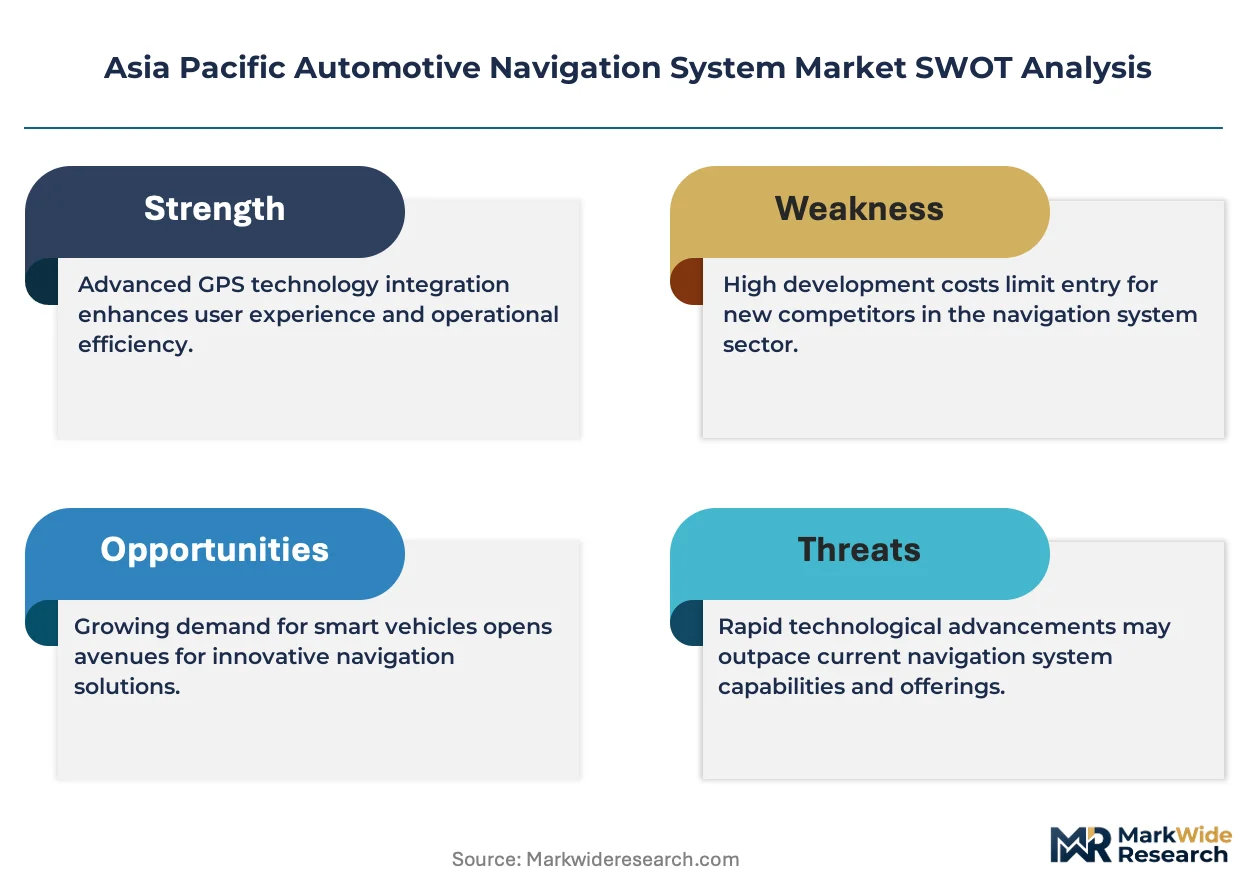
The automotive navigation market in Asia Pacific is restructuring around China's MIIT mandates for BeiDou integration, which force module redesigns across Japanese and Korean supply chains serving domestic OEMs.
Growth Catalysts
- BeiDou Mandates:China's MIIT requires domestic vehicles to integrate BeiDou chipsets for type approval, compelling foreign suppliers to reconfigure hardware architectures for the world's largest automotive market.
- Fleet Digitization:Southeast Asian logistics operators are deploying embedded navigation systems to optimize route efficiency and fuel consumption across archipelago geography.
- Cloud-Based Routing:Connected navigation platforms are displacing static map storage, enabling real-time traffic integration and over-the-air feature updates for premium vehicle programs.
Market Restraints
- Semiconductor Supply Concentration:GNSS chipset fabrication concentrates in Taiwan and South Korea, exposing module assemblers to single-source risk during demand surges.
- Regulatory Fragmentation:Japan's METI enforces JIS electromagnetic compatibility standards that diverge from China's GB certification requirements, forcing dual-SKU production strategies.
- Map Database Costs:High-resolution vector mapping for autonomous-grade positioning requires expensive licensing from HERE Technologies and TomTom, compressing margins for mid-tier system integrators.
Strategic Opportunities
- Indonesia Aftermarket Penetration:Low embedded navigation installation rates in Indonesian passenger vehicles create white space for smartphone-integrated head units with offline caching.
- Software-Defined Cockpit Convergence:Navigation functions are virtualizing into centralized compute platforms, allowing Tier-1 suppliers to bundle ADAS visualization and infotainment through single hardware stacks.
- Australian Mining Fleet Automation:Resource extraction operators in Western Australia are procuring centimeter-accuracy GNSS systems for autonomous haul truck corridors.
Industry Challenges
- Multi-Constellation Integration Complexity:Engineering teams must validate simultaneous GPS, GLONASS, BeiDou, and Galileo reception without signal interference, extending firmware development cycles.
- Over-the-Air Security Certification:Connected navigation systems require cybersecurity type approval under evolving national standards, delaying product launches in multiple Asia Pacific jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive Navigation System Market |
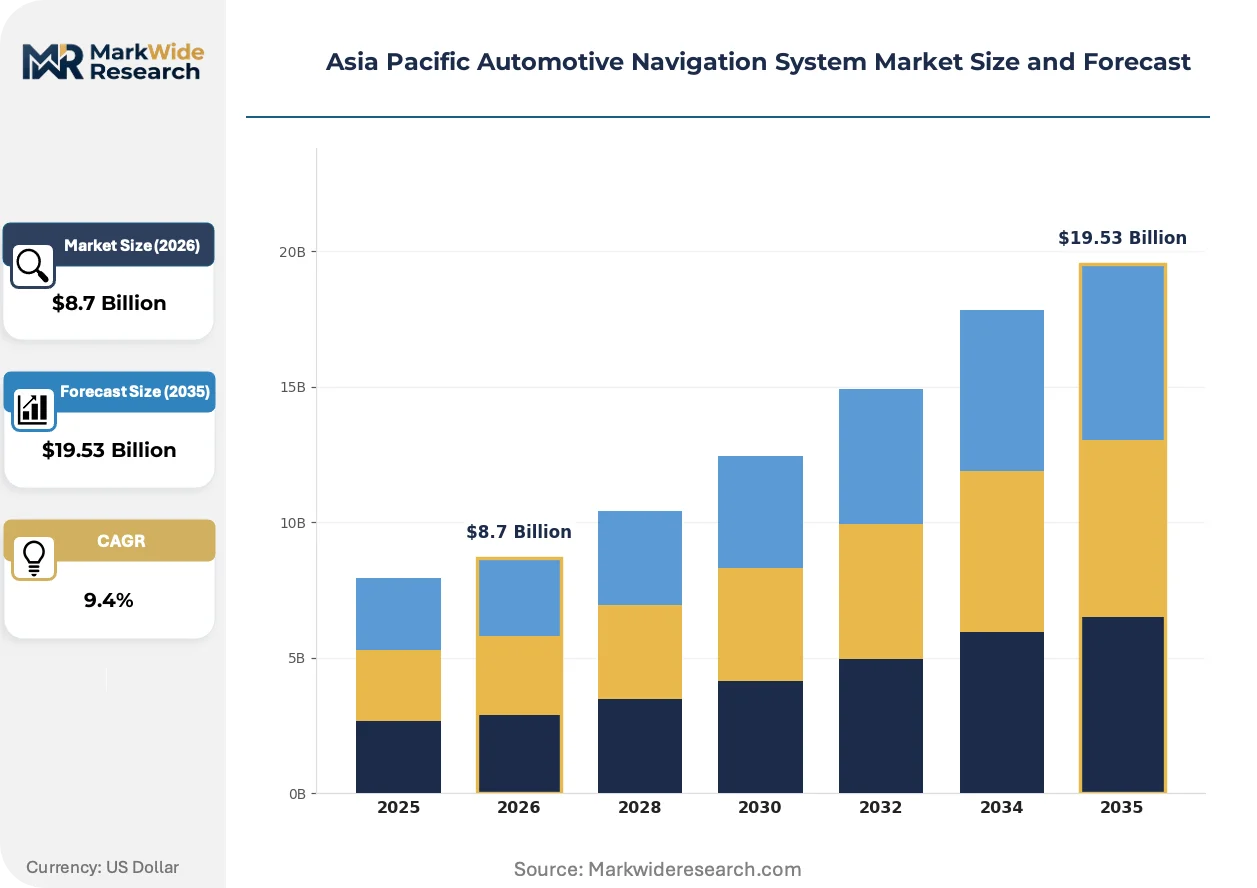
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Portable Devices, Smartphone Apps, Connected Systems Technology: GPS, GLONASS, Galileo, BeiDou End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Installation: Factory Installed, Aftermarket Integration, Mobile Installation, Retrofitting |
| Companies Covered | Alpine Electronics, Denso Corporation, Pioneer Corporation, Aisin AW Co. Ltd, Continental AG, Clarion, Harman International, Robert Bosch GmbH, Mitsubishi Electric Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive Navigation System Market Strategic Shifts
Navigation system architecture is virtualizing away from dedicated hardware modules toward software layers running on centralized vehicle computers, compressing supplier value capture and rewriting procurement specifications.
High-definition map streaming is virtualizing the traditional onboard database model. Premium OEMs in Japan and South Korea are adopting cloud-rendered navigation layers that reduce local storage requirements by eighty percent. This shift is virtualizing the competitive boundary between map providers and cockpit software integrators, forcing HERE and TomTom to reposition as platform services rather than data licensors.
China's MIIT is tightening cybersecurity review requirements for connected vehicle systems, including navigation modules with cellular uplinks. Foreign suppliers must submit source code and encryption protocols for domestic type approval, extending certification timelines by six to nine months. Korean Tier-1s are responding by establishing localized engineering centers in Shanghai to accelerate regulatory compliance.
Fleet procurement in Southeast Asia is consolidating around telematics-integrated navigation bundles. Logistics operators in Thailand and Vietnam are rejecting standalone GPS units in favor of combined routing, driver monitoring, and fuel management platforms sold through commercial vehicle dealerships. This channel migration is most visible in Bangkok's commercial district, where distributor networks are retraining sales staff on enterprise software pitching rather than hardware installation.
Asia Pacific Automotive Navigation System Market Segmentation
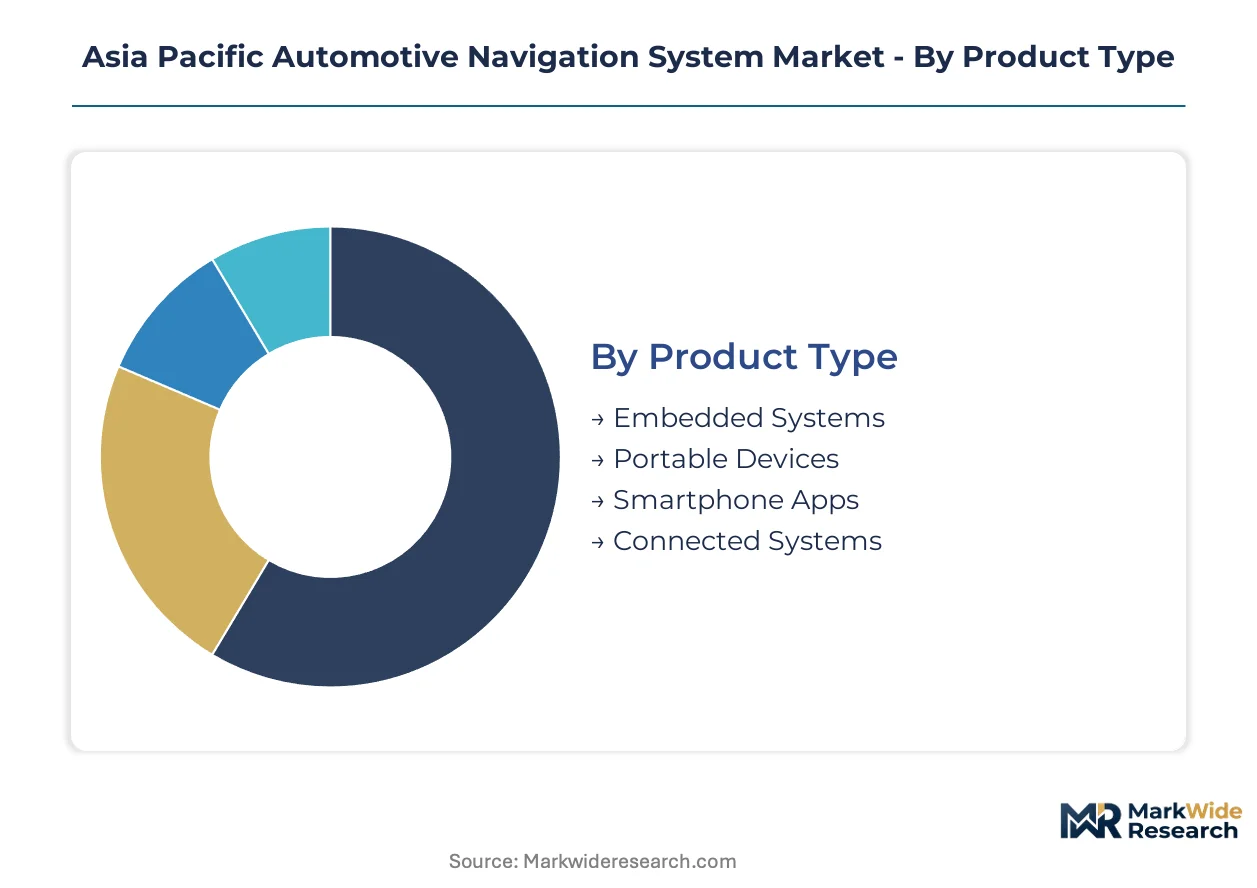
Navigation system procurement cycles vary dramatically across Asia Pacific, from multi-year OEM platform commitments to annual smartphone app refresh cycles. Understanding segment turnover rates helps suppliers align R&D cadences with revenue visibility and inventory risk profiles.
Product Type:
Embedded Systems turn over on 5-7 year vehicle platform cycles, while smartphone-connected solutions refresh annually, creating divergent cash flow profiles for component suppliers.
- Embedded Systems:Factory-integrated hardware with dedicated GNSS chipsets and hardened automotive-grade displays. Japanese OEMs in Nagoya and Toyota City concentrate procurement here, driven by durability requirements for precision manufacturing corridors where downtime costs exceed hardware premiums.
- Connected Systems:Cloud-dependent architectures streaming map tiles and traffic data through cellular modems. Korean automakers and Chinese EV startups are concentrating demand in this segment, compelled by over-the-air update capabilities that extend functional lifespans without hardware replacement.
- Portable Devices:Aftermarket GPS units with suction-mount displays and SD card map storage. Remains relevant in Indonesian and Philippine rural markets where vehicle turnover exceeds embedded system amortization periods.
- Smartphone Apps:Mirrored navigation through Apple CarPlay and Android Auto protocols. Australian consumers and Southeast Asian ride-hail drivers favor this zero-incremental-cost option, though cellular dead zones in archipelago geography limit reliability.
Embedded Systems anchor the volume base while Connected Systems gains share at the steepest rate.
Technology:
Cost tiers separate sovereign constellation mandates from multi-constellation redundancy premiums, with single-system architectures dominating economy deployments and quad-mode receivers commanding premium positioning.
- BeiDou:China's indigenous GNSS constellation with domestic ground segment control. MIIT mandates this technology for type approval, forcing module redesigns across Japanese and Korean supply chains serving the world's largest automotive market.
- GPS:The original US Navstar constellation with mature chipset availability and minimal licensing friction. Remains baseline for Australian aftermarket and Southeast Asian fleet retrofitting where regulatory neutrality matters.
- GLONASS:Russian constellation providing high-latitude coverage advantages. Dual GPS-GLONASS architectures sustain demand in northern Japan and South Korean border regions where geometry improves signal acquisition.
- Galileo:European civilian constellation with commercial authentication services. Premium OEMs in Japan adopt this for high-integrity positioning in automated lane-keeping applications.
BeiDou captures the regulatory-mandated volume base while Galileo climbs the fastest among premium positioning tiers.
End User:
Customer type determines specification rigor, with OEM-direct channels demanding automotive-grade validation and fleet operators prioritizing telematics integration over standalone navigation performance.
- OEMs:Vehicle manufacturers specifying navigation as standard or optional equipment. Toyota, Hyundai, and BYD consolidate vendor panels, compressing supplier margins through multi-year platform commitments.
- Fleet Operators:Logistics and ride-hail companies procuring at commercial vehicle scale. Bangkok and Jakarta operators reject standalone units, instead demanding telematics bundles combining routing with driver monitoring and fuel management.
- Tier-1 Suppliers:Denso, Hyundai Mobis, and Bosch integrating navigation into cockpit modules. These intermediaries control specification translation between OEM requirements and chipset vendors.
- Aftermarket Providers:Electronics retailers and installer networks serving vehicle parc beyond factory warranty. Pioneer Corporation dominates channel control across Indonesia and Thailand through distributor relationships.
OEMs anchor the volume base while Fleet Operators gains share at the steepest rate.
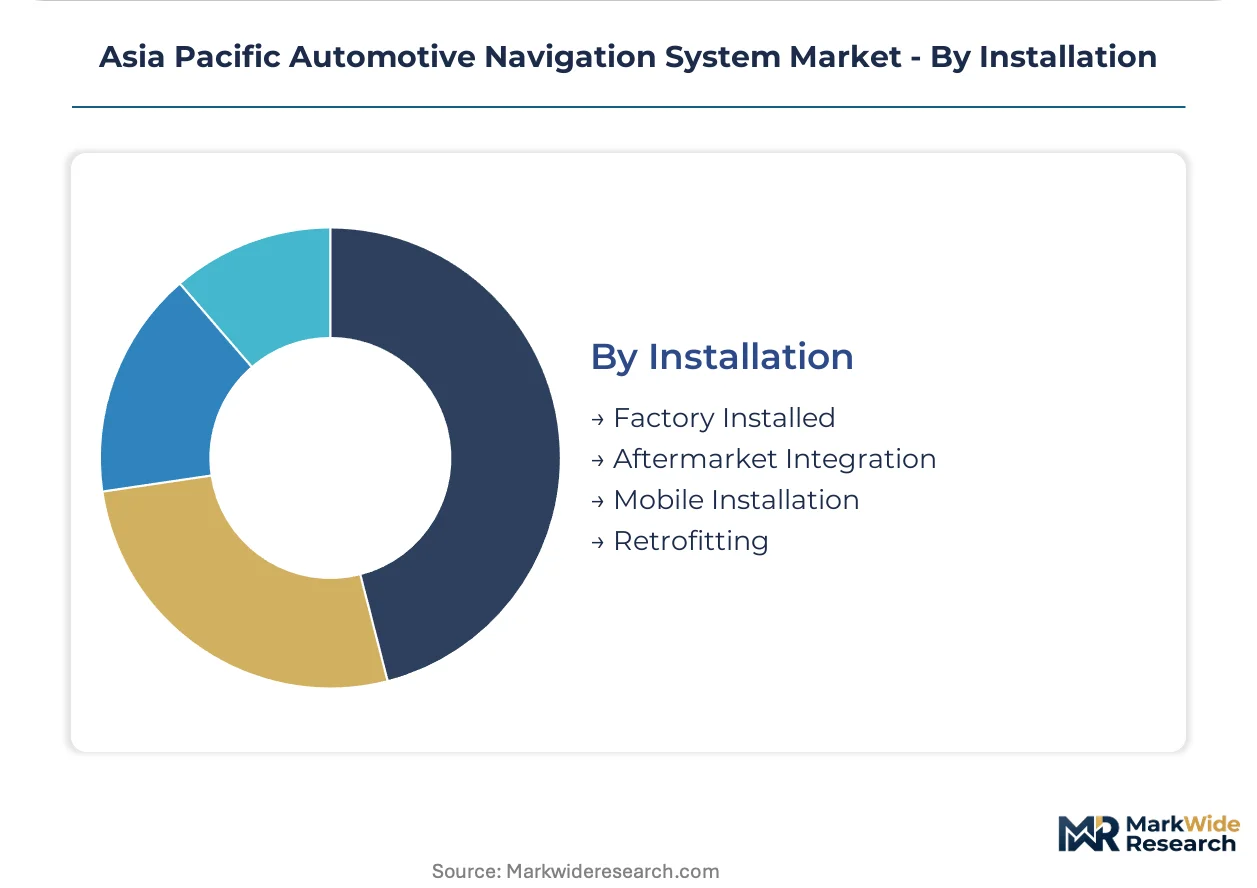
Installation:
Supply concentration in Japan and Korea for factory-installed systems contrasts with fragmented mobile installation networks across Southeast Asian archipelago markets.
- Factory Installed:Line-fit integration during vehicle assembly. Japanese and Korean automakers concentrate this capability in Nagoya, Toyota City, and Ulsan, where Tier-1 supplier clusters enable just-in-sequence delivery.
- Aftermarket Integration:Dealer or specialist installation of replacement head units. Indonesian passenger vehicles show low embedded penetration, creating white space for smartphone-integrated systems with offline caching.
- Mobile Installation:Portable device mounting without vehicle modification. Dominates Australian consumer preference for flexibility across multiple vehicle ownership.
- Retrofitting:Legacy vehicle upgrades with modern GNSS capabilities. Western Australian mining fleets procure centimeter-accuracy systems for autonomous haul truck corridors, bypassing factory-installed limitations.
Factory Installed anchors the volume base while Aftermarket Integration gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in automotive electronics supply chains, while Japan's Chubu Centrair International Airport anchors just-in-time component flows to Nagoya's manufacturing corridor.
China
BeiDou mandates from MIIT force module redesigns across foreign supply chains serving domestic OEMs. The GB certification regime requires cybersecurity source code review for connected navigation systems. Yangtze River Delta clusters around Shanghai and Suzhou concentrate chipset fabrication and system integration capacity.
Japan
Precision manufacturing corridors demand automotive-grade durability where downtime costs exceed hardware premiums. METI enforces JIS electromagnetic compatibility standards diverging from Chinese requirements. Nagoya and Toyota City host dense Tier-1 supplier networks delivering just-in-sequence to assembly plants.
South Korea
Cloud-based routing architectures dominate Korean OEM programs driven by over-the-air update capabilities. MFDS cybersecurity frameworks apply to connected vehicle systems including navigation modules. Ulsan and Seoul Capital Area concentrate cockpit module integration and software development.
Australia
Aftermarket preference for portable flexibility persists across consumer segments despite factory-installed penetration gains. ACMA regulates GNSS augmentation spectrum affecting device certification timelines. Western Australian mining corridors procure centimeter-accuracy retrofit systems for autonomous haul truck operations.
Indonesia
Low embedded navigation installation rates in passenger vehicles create aftermarket white space for smartphone-integrated head units. National infrastructure investment prioritizes logistics digitization across archipelago geography. Jakarta and Surabaya distributor networks retrain toward enterprise software pitching over hardware installation.
Asia Pacific Automotive Navigation System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying chipsets and map databases. The vendor structure concentrates around Japanese and Korean Tier-1s with established OEM relationships, while aftermarket channels fragment across distributor networks. Three archetypes dominate: cockpit module integrators bundling navigation into centralized compute platforms; aftermarket channel controllers leveraging distributor relationships in Southeast Asia; and software-defined specialists competing on over-the-air capability. Competitive moves center on geographic expansion into Chinese engineering centers and portfolio diversification toward telematics-integrated bundles.
Within the cockpit integration tier, Denso Corporation and Harman International occupy positions exemplifying divergent strategic approaches to software-defined vehicle architectures. Pioneer Corporation represents aftermarket channel control archetypes through distributor network leverage across Indonesia and Thailand. These three anchors illustrate how supplier positioning splits between factory-direct platform commitments and fragmented retail channel penetration.
| Leading Market Players |
|---|
| Alpine Electronics |
| Denso Corporation |
| Pioneer Corporation |
| Aisin AW Co. Ltd |
| Continental AG |
| Clarion |
| Harman International |
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Taiwanese and South Korean foundry concentration for GNSS chipsets concentrates margin capture upstream, forcing module assemblers in Japan and China to compete on assembly efficiency rather than semiconductor value-add.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with BeiDou-certified modules commanding certification premiums and volume discounts compressing margins for fleet-scale orders. Price differentiation hinges on constellation reception capability and automotive-grade temperature certification. Pricing pressure stems from Chinese EV startups demanding connected-system cost parity with embedded alternatives. Fleet operators in Southeast Asia exhibit highest price sensitivity, while Japanese precision manufacturing corridors absorb durability premiums.
Supply Chain Analysis
Hon Hai Precision Industry, Jabil Circuit, and Pegatron hold contract manufacturing capacity for cockpit module integration, anchoring production in Taiwan, Thailand, and Vietnam. Raw material dependencies include silicon wafers from TSMC foundries, high-precision ceramic antenna substrates from Japanese suppliers, and rare-earth magnets for BeiDou receivers from Chinese processors. Single-source vulnerability concentrates in Taiwan Strait logistics corridors. Distribution runs through Tier-1 supplier direct channels for OEM programs and fragmented electronics distributor networks for aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific automotive navigation market is recovering from platform consolidation cyclicality, with OEM vehicle production schedules and semiconductor availability serving as the primary cyclical driver.
For Market Incumbents: Build switching-cost moats through software-defined cockpit integration that virtualizes navigation into centralized compute platforms. Denso Corporation and Harman International should deepen firmware customization relationships with Toyota and Hyundai to raise replacement costs. Threat from Chinese EV startups demanding open-architecture APIs necessitates accelerated R&D in over-the-air security certification to maintain platform control.
For New Entrants and Emerging Players: Indonesian aftermarket underpenetration offers the most accessible white space, with embedded navigation installation rates below regional averages creating demand for smartphone-integrated head units with offline caching. Target Thailand's fleet telematics bundling trend through commercial vehicle dealership channels rather than consumer electronics retail. Go-to-market angle should emphasize fuel management integration over standalone routing performance.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics specialists holding regional distributor networks but lacking software-defined vehicle capabilities. Five-to-ten-year viability favors platform integrators over component suppliers as navigation virtualizes into centralized compute. Signal to watch is MIIT cybersecurity review timeline extensions, which would compress valuations for foreign suppliers lacking localized engineering centers.
| Strategic Initiative | Industry Significance |
|---|---|
| BeiDou Chipset Localization | MIIT mandates force module redesigns, rewarding suppliers with Shanghai engineering centers. |
| Software-Defined Cockpit Integration | Virtualized navigation compresses hardware value capture toward platform integrators like Harman. |
| Fleet Telematics Bundling | Thai and Vietnamese logistics operators demand combined routing, driver monitoring, and fuel management. |
| Aftermarket Channel Control | Pioneer Corporation's distributor relationships across Indonesia and Thailand defend retail positioning. |
| Centimeter-Accuracy Mining Systems | Western Australian autonomous haul corridors procure retrofit GNSS bypassing factory-installed limitations. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributor operations heads, and fleet telematics managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, MIIT type approval filings, and METI electromagnetic compatibility standards. Bottom-up module shipment estimates triangulated against top-down OEM navigation content-per-vehicle assumptions.
Calibration anchored historical shipment volumes to observed platform commitments and semiconductor supply constraints, then projected forward across the analysis window. Segmentation dimensions modeled include embedded versus connected system architecture, BeiDou versus multi-constellation technology tiers, OEM-direct versus fleet versus aftermarket channels, and regional production clusters. CAGRs derived from fitted growth curves incorporating regulatory mandate timelines and EV adoption penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed semiconductor foundries or accelerated cybersecurity unilateralism would shift outcomes. Quarterly review of MIIT certification queue lengths, Taiwan Strait logistics indices, and OEM platform engineering change notices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Automotive Navigation & Infotainment Systems Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Dashboard Camera Market