
 Chlorinated Isocyanurates Market | 2026-2036
Chlorinated Isocyanurates Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorinated Isocyanurates Market Analysis
Food-grade and NSF-certified specification tiers is bifurcating the competitive landscape into premium-validated suppliers and commodity producers. Occidental Chemical Corporation leverages integrated chlor-alkali feedstock access to sustain cost leadership in North American tablet production. Lonza Group AG differentiates through pharmaceutical-grade manufacturing protocols that anchor its position in European municipal tenders. Shikoku Chemicals Corporation specializes in high-purity granular formulations for Japanese industrial cleaning applications.
Chlorinated isocyanurates are cyclic nitrogen-chlorine compounds derived from cyanuric acid, typically containing 50-90% available chlorine by weight and manufactured through gas-phase or aqueous chlorination of cyanuric acid salts. These compounds serve as stabilized chlorine donors that release hypochlorous acid slowly, making them essential for continuous disinfection in swimming pools and drinking water systems. Trichloroisocyanuric acid dominates value pools due to its highest available chlorine content and tablet-form convenience for residential pool maintenance. Sodium dichloroisocyanurate is expanding fastest among municipal end users seeking lower pH impact than calcium hypochlorite alternatives. Tablet form commands premium positioning through dosing precision and reduced handling risk compared to granular or powder equivalents.
EPA registration requirements under FIFRA constrain market entry for new chlorinated isocyanurate formulations in the United States, while REACH compliance in Europe mandates extensive toxicological dossiers for cyanuric acid derivatives. China's MEE enforces wastewater discharge standards that raise production costs for Shandong-based manufacturers. Japan's PMDA and METI coordinate on chemical substance notifications that filter import competition. Stakeholders must monitor evolving per- and polyfluoroalkyl substance scrutiny that could redirect regulatory attention toward all halogenated water treatment chemistries.
Market Dynamics
The Chlorinated Isocyanurates Market is experiencing structural pressure from EPA's Stage 2 Disinfectants and Disinfection Byproducts Rule, which tightens trihalomethane limits and redirects municipal procurement toward stabilized chlorine donors with lower byproduct formation.
Growth Catalysts
- Secondary Disinfection Mandates:Municipal water treatment utilities across the United States are expanding procurement of stabilized chlorine donors to maintain residual disinfection throughout distribution networks. EPA's tightening trihalomethane limits under the Stage 2 DBP Rule accelerate this transition.
- Pool Maintenance Standardization:Residential pool service operators are consolidating around tablet-form chlorinated isocyanurates for dosing precision and reduced handling risk compared to granular alternatives.
- REACH Compliance Dossiers:European manufacturers completing extensive toxicological registrations for cyanuric acid derivatives are securing preferential access to municipal tenders in Germany, France, and the Netherlands.
Market Restraints
- Chlor-Alkali Feedstock Volatility:Electrolytic chlorine and caustic soda price swings directly compress margins for tablet producers dependent on merchant chlorine supply.
- Shandong Supply Concentration:Integrated cyanuric acid-to-chlorinated derivative operations in China's Shandong province create geographic single-point vulnerability for global granular supply.
- Calcium Hypochlorite Substitution:Lower-cost unstabilized alternatives retain share in price-sensitive municipal segments, particularly in developing water utilities prioritizing upfront chemical cost over long-term stabilization benefits.
Strategic Opportunities
- NSF-Certified Premium Tier:Food-grade specification tiers create pricing separation from commodity producers in North American drinking water applications.
- Industrial Cleaning Formulations:High-purity granular grades for Japanese electronics and pharmaceutical manufacturing facilities represent underpenetrated demand outside traditional pool and municipal segments.
- Perimeter Security Applications:Stabilized chlorine donors for agricultural irrigation and food processing wash water are emerging as regulatory scrutiny intensifies on microbial contamination in supply chains.
Industry Challenges
- FIFRA Registration Timelines:EPA pesticide registration requirements impose multi-year approval cycles for new chlorinated isocyanurate formulations, freezing product innovation pipelines.
- Pharmaceutical-Grade Protocol Migration:Municipal tender specifications in European markets increasingly demand manufacturing standards historically reserved for active pharmaceutical ingredients, requiring capital-intensive facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorinated Isocyanurates Market |
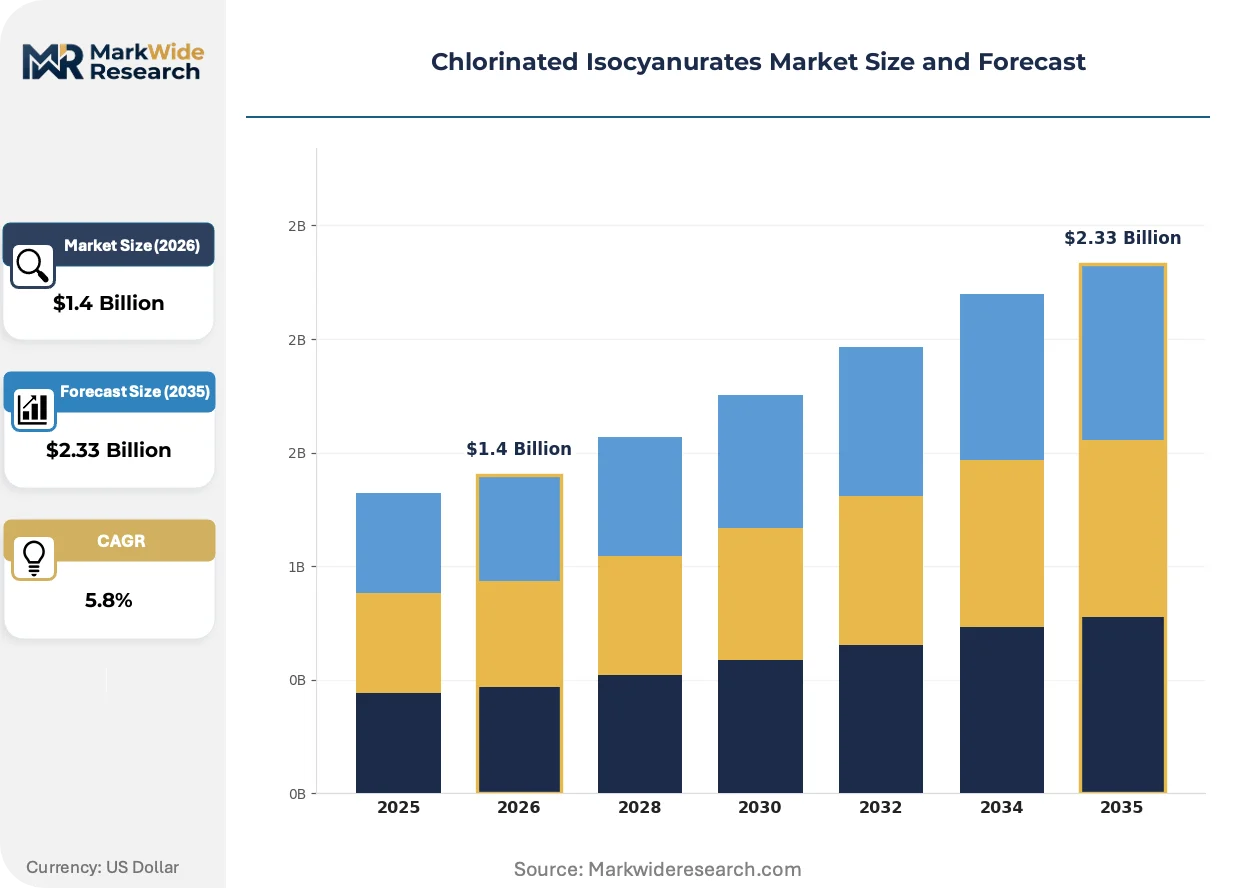
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trichloroisocyanuric Acid, Sodium Dichloroisocyanurate, Calcium Hypochlorite, Others Application: Disinfection, Water Treatment, Swimming Pools, Industrial Cleaning Form: Granular, Powder, Tablet, Liquid End User: Household, Commercial, Industrial, Municipal |
| Companies Covered | Occidental Chemical Corporation, Heze Huayi Chemical Co., Ltd., Jiheng Chemical Co., Ltd., Juancheng Kangtai Chemical Co., Ltd., Nanjing Jiangbei New Area Biosciences, Olin Corporation, Lonza Group AG, Shikoku Chemicals Corporation, Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorinated Isocyanurates Market Emerging Trajectories
Stabilized chlorine donor chemistry is undergoing refinement as regulatory pressure on disinfection byproducts intensifies and end-users demand precision dosing formats. Three developments are restructuring competitive positioning.
Slow-dissolving tablet formulations with engineered erosion rates are displacing conventional compressed tablets in commercial pool operations. Facility managers at hotels, fitness centers, and municipal aquatic centers are adopting these precision-release formats to reduce maintenance labor and stabilize free chlorine residuals. The shift is compressing demand for traditional granular products in high-volume automated feeder installations.
REACH authorization requirements for cyanuric acid derivatives are forcing reformulation strategies among European suppliers. ECHA's evolving dossier demands for toxicological endpoints are extending registration timelines and raising compliance expenditures. German and Dutch municipal water utilities are responding by consolidating procurement around established registrants with complete substance portfolios.
Certification-driven specification tiers are fragmenting buyer segments across premium-validated and commodity supply pools. North American utilities with NSF/ANSI 60 certification requirements are diverting procurement toward audited manufacturing facilities. This behavioral shift is most visible in California and Texas municipal tenders, where documentation of Good Manufacturing Practice compliance now filters supplier eligibility before technical evaluation.
Chlorinated Isocyanurates Market Segmentation
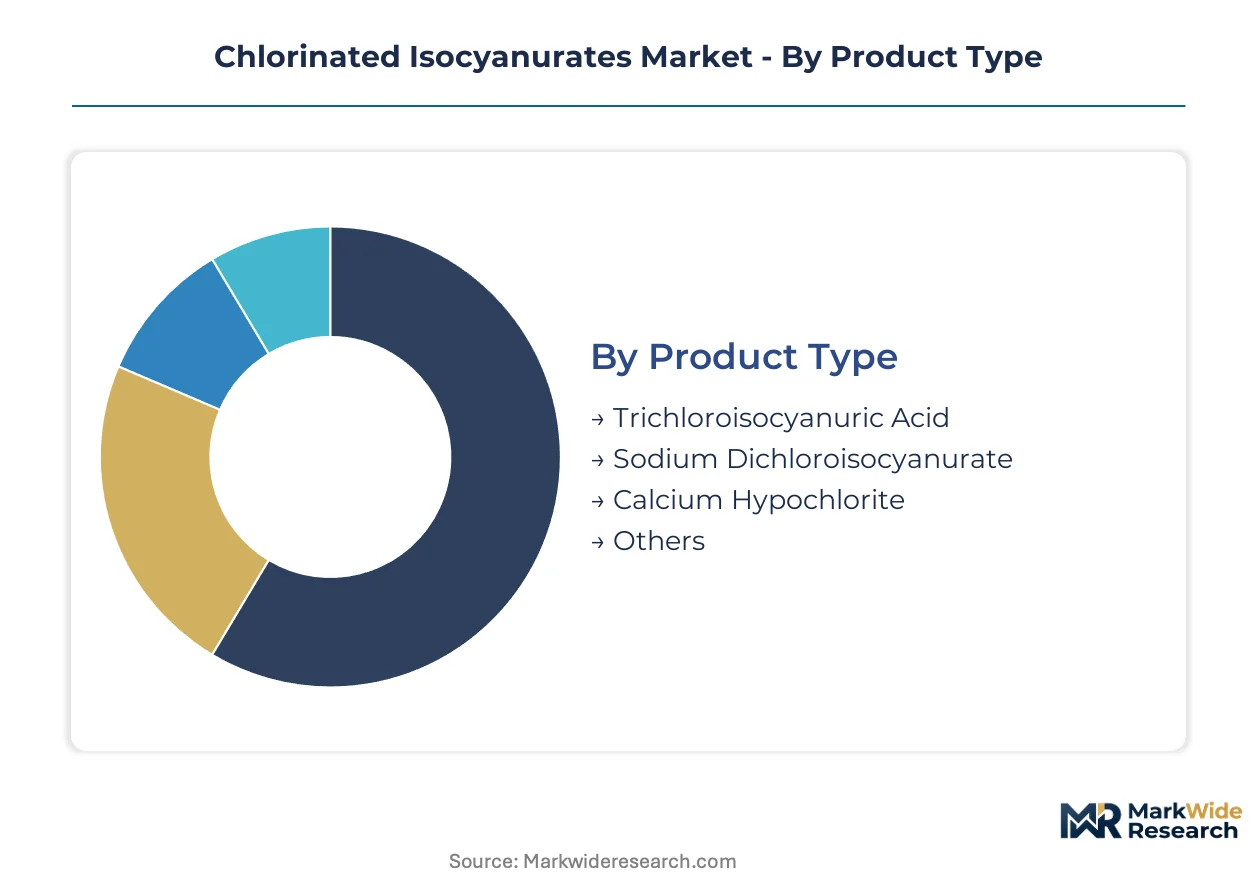
Chlorinated isocyanurates serve divergent end-use requirements through chemically distinct product grades and physical formats. Segmentation reveals where specification premiums command pricing power versus commodity competition.
Product Type:
Margin pools concentrate in high-available-chlorine grades where manufacturing complexity creates supply scarcity.
- Trichloroisocyanuric Acid:Contains 90% available chlorine by weight, the highest concentration among stabilized donors. Tablet-form demand from residential pool service operators in Florida and Arizona sustains premium positioning through dosing precision.
- Sodium Dichloroisocyanurate:Delivers 56-62% available chlorine with near-neutral pH dissolution. Municipal utilities in Germany and the Netherlands are expanding procurement for secondary disinfection to meet tightening trihalomethane limits under ECHA-monitored protocols.
- Calcium Hypochlorite:Unstabilized alternative with lower upfront cost but higher byproduct formation, retaining share in price-sensitive developing markets.
- Others:Specialty blends and stabilized chlorine donors for niche agricultural and food processing applications.
The dominant share belongs to Trichloroisocyanuric Acid, while Sodium Dichloroisocyanurate is closing the gap fastest.
Application:
Regulatory pressure on disinfection byproducts is redirecting procurement volumes across end-use categories.
- Disinfection:Surface and equipment sanitization in healthcare and food processing facilities. Japanese electronics manufacturers specify high-purity granular grades for cleanroom protocols.
- Water Treatment:Municipal drinking water secondary disinfection. EPA Stage 2 DBP Rule enforcement is accelerating stabilized chlorine donor adoption across Texas and California utilities.
- Swimming Pools:Residential and commercial aquatic facility maintenance. Tablet formats dominate automated feeder installations at hotels and fitness centers.
- Industrial Cleaning:Process equipment and pipeline sanitation. Pharmaceutical-grade protocols from Swiss and German manufacturers anchor premium supply tiers.
Swimming Pools commands the largest volume position, though Water Treatment is expanding most quickly on regulatory tailwinds.
Form:
Physical format determines handling economics and dosing precision in automated versus manual applications.
- Tablet:Compressed slow-dissolving formats for automated feeders. Commercial pool operators in Spain and Italy consolidate procurement around erosion-engineered tablets to reduce labor costs.
- Granular:Rapid-dissolving crystalline product for shock treatment and industrial applications. Shandong province integrated producers supply global granular demand.
- Powder:Fine particle size for bulk dissolution in large-scale municipal treatment.
- Liquid:Pre-dissolved solutions for specialized dosing equipment and emergency response protocols.
Tablet formats capture premium pricing, while Granular maintains volume leadership through manufacturing scale.
End User:
Procurement sophistication varies sharply across customer types, fragmenting supplier qualification requirements.
- Municipal:Water treatment utilities with NSF/ANSI 60 or equivalent certification mandates. Documentation of Good Manufacturing Practice compliance filters supplier eligibility in North American tenders.
- Commercial:Hotels, fitness centers, and aquatic facilities prioritizing labor reduction through automated dosing. Consolidated procurement by national pool service chains is compressing supplier margins.
- Industrial:Electronics, pharmaceutical, and food processing facilities with purity specifications. Japanese METI-coordinated substance notifications constrain import competition.
- Household:Residential pool owners through retail and e-commerce channels. Price sensitivity sustains commodity tablet and granular competition.
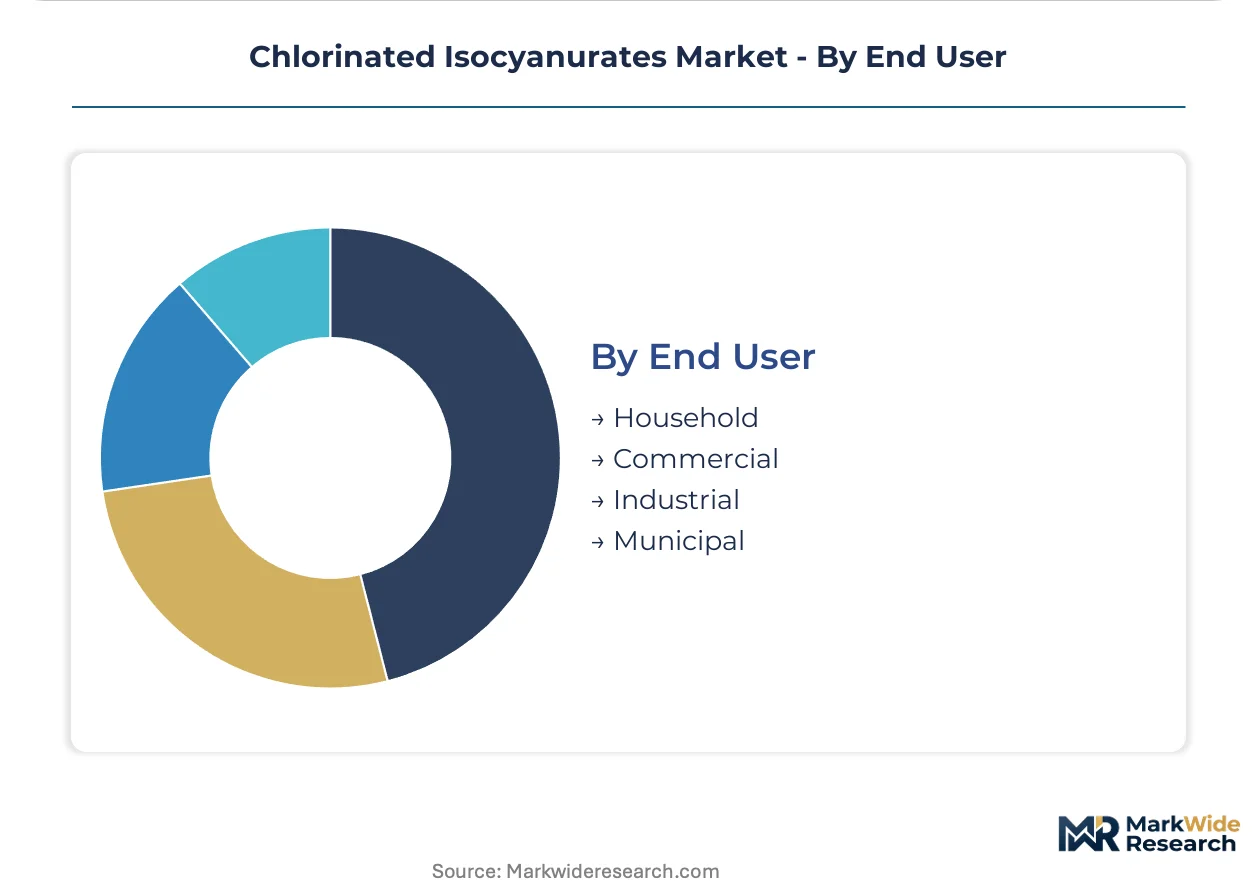
Municipal end users generate the highest specification premiums, with Industrial segments climbing fastest on purity-driven demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province cyanuric acid producers supply granular chlorinated isocyanurates to North American municipal utilities and European industrial compounders. This trade corridor shapes regional competitive dynamics across three continents.
United States
Texas and California municipal utilities are expanding procurement of stabilized chlorine donors for secondary disinfection networks. EPA's Stage 2 Disinfectants and Disinfection Byproducts Rule tightens trihalomethane limits and redirects procurement toward alternative chemistries. Florida's residential pool service operators concentrate demand for tablet-form products in the Orlando-Tampa corridor.
Germany
Municipal water utilities in North Rhine-Westphalia and Bavaria prioritize REACH-registered cyanuric acid derivatives for distribution network disinfection. ECHA's evolving toxicological dossier requirements extend registration timelines and raise compliance expenditures. The Rhine-Ruhr industrial cluster anchors pharmaceutical-grade manufacturing protocols for European tender specifications.
China
Shandong province integrated producers Heze Huayi and Juancheng Kangtai maintain captive cyanuric acid-to-chlorinated derivative operations. MEE wastewater discharge standards raise production costs for coastal manufacturers. The Heze-Juancheng corridor supplies global granular demand while facing environmental compliance pressure.
Japan
Electronics manufacturers in the Kanto and Kansai regions specify high-purity granular grades for cleanroom sanitation protocols. METI and PMDA coordinate on chemical substance notifications that filter import competition. Shikoku-based specialists serve pharmaceutical and precision industrial applications with validated manufacturing standards.
Chlorinated Isocyanurates Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and geographic reach. The vendor base fragments across three strategic layers: integrated chlor-alkali operators, cyanuric acid-derivative specialists, and pharmaceutical-grade protocol adherents. Consolidation pressure operates through backward integration into feedstock supply and forward positioning in NSF-certified premium segments.
Within the integrated chemical operator tier, Occidental Chemical Corporation and Olin Corporation represent North American scale-driven positioning with captive chlor-alkali feedstock access. Among Asian cyanuric acid specialists, Heze Huayi Chemical Co., Ltd. and Juancheng Kangtai Chemical Co., Ltd. exemplify Shandong-based vertical integration from acid precursor to finished derivative. Lonza Group AG and Shikoku Chemicals Corporation occupy the pharmaceutical-grade manufacturing archetype serving European and Japanese specification-intensive tenders.
| Leading Market Players |
|---|
| Occidental Chemical Corporation |
| Heze Huayi Chemical Co., Ltd. |
| Jiheng Chemical Co., Ltd. |
| Juancheng Kangtai Chemical Co., Ltd. |
| Nanjing Jiangbei New Area Biosciences |
| Olin Corporation |
| Lonza Group AG |
| Shikoku Chemicals Corporation |
| Tosoh Corporation |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles for Shandong-origin cyanuric acid derivatives concentrate pricing power with integrated producers while exposing tablet formulators to chlorine feedstock volatility. This lead-time band shapes how municipal procurement officers negotiate contract terms against spot-market granular suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the chlorinated isocyanurates market. NSF/ANSI 60 certification and pharmaceutical-grade manufacturing protocols command 15-30% premiums over commodity tablet and granular grades. Cost compression in standard-tier tablet production is intensifying because merchant chlor-alkali supply contracts reprice quarterly. Municipal water utilities exhibit the lowest price sensitivity due to regulatory compliance mandates, while residential pool service operators consolidate procurement around volume-scaled contract tiers.
Supply Chain Analysis
Sixty-to-ninety-day inventory cycles reflect deep geographic concentration in China's Shandong province, where Heze Huayi and Juancheng Kangtai control upstream cyanuric acid supply. Tablet production in the United States and Europe draws from electrolytic chlorine, caustic soda, and compressed salt inputs. Single-source vulnerability in Shandong-origin granular supply creates exposure to MEE wastewater enforcement actions. Distribution runs through regional chemical distributors serving municipal utilities, national pool service chains, and industrial compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where EPA FIFRA registration requirements create regulatory entrenchment that freezes new formulation entry for multi-year cycles. Switching costs for municipal utilities are reinforced by NSF certification audit requirements and validated manufacturing documentation.
For Market Incumbents: Consolidate backward integration into captive chlor-alkali supply or cyanuric acid precursor production to defend against merchant feedstock volatility. Secure long-term offtake agreements with Texas and California municipal utilities before REACH-registered European suppliers expand transatlantic tender participation. Prioritize NSF/ANSI 60 certification maintenance as the primary lever for premium-tier pricing separation. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade manufacturing protocols to access European municipal tenders where ECHA dossier completeness filters competition. Target Japanese electronics and pharmaceutical cleanroom sanitation as the most penetrable white-space segment outside traditional pool and municipal applications. Pursue METI-coordinated substance notification completion as the essential go-to-market prerequisite. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because FIFRA and REACH compliance timelines extend competitive moats beyond typical chemical industry cycles. Acquisition targets should display integrated cyanuric acid-to-derivative operations or established pharmaceutical-grade protocol infrastructure. Monitor EPA enforcement intensity on Stage 2 DBP Rule trihalomethane limits as the signal for accelerated municipal procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive cyanuric acid supply insulates Occidental Chemical from Shandong price volatility. |
| NSF Certification Investment | Audited manufacturing documentation unlocks California and Texas municipal tender eligibility. |
| REACH Dossier Completion | Full toxicological registration secures preferential access to German and Dutch utility procurement. |
| Pharmaceutical-Grade Protocol Migration | API-standard manufacturing anchors premium positioning in Japanese electronics sanitation. |
| Long-term Supply Agreement | Contracted offtake with municipal utilities reduces exposure to spot granular price swings. |
Methodological Framework
Operator-level perspectives from municipal water treatment plant managers, pool service chain procurement directors, chemical distribution channel partners, and Shandong-based manufacturing plant supervisors anchored the qualitative base for this analysis. Secondary validation drew from EPA enforcement databases, ECHA registration dossiers, ACC chemical trade statistics, and SEC 10-K filings from listed chlor-alkali operators. Bottom-up volume estimates triangulated against top-down value projections derived from trade flow analysis.
Sensitivity analysis across feedstock price scenarios, regulatory enforcement intensity variations, and substitution elasticity assumptions shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, physical form factor, and regional production hub clustering. CAGRs were derived from curve-fitting historical trade volumes against projected regulatory-driven demand shifts, with specific inputs for chlorine feedstock contract repricing cycles and municipal capital expenditure patterns.
The analysis sits within stated boundaries; outcomes outside sustained EPA Stage 2 DBP Rule enforcement or accelerated REACH authorization timelines would require recalibration. Forecasts reflect documented assumptions about Shandong supply continuity and chlor-alkali merchant market structure. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Global Pseudocumene Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
North America Humic Acid Market
Organic Chemicals
Asia-Pacific Organic Acid Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
Long-Chain Dicarboxylic Acid Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
Global Benzoic Acid Market