
 North America Biphenyl Market | 2026-2036
North America Biphenyl Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biphenyl Market Insights
EPA TSCA Section 6 risk evaluations is rebalancing the cost-of-entry calculus for biphenyl producers serving North American industrial buyers. Eastman Chemical Company leverages its integrated aromatic hydrocarbon platform to sustain captive supply advantages across the region. Lanxess AG anchors its position through specialized biphenyl derivative grades targeting pharmaceutical and agrochemical intermediates. Dow Inc. competes on manufacturing scale, operating large-volume biphenyl production assets tied to downstream heat transfer fluid applications.
Biphenyl consists of two phenyl rings joined by a single carbon-carbon bond, exhibiting a melting point near 69°C and boiling point approximately 255°C, which makes it effective as a high-temperature heat transfer medium and chemical synthesis precursor. The application landscape shows heat transfer fluids commanding established volume positions due to thermal stability requirements in chemical processing and power generation installations, while biphenyl derivatives represent the fastest-expanding category as pharmaceutical manufacturers demand increasingly specialized aromatic intermediates for active ingredient synthesis. Material additives applications occupy a mature niche with stable demand from polymer and resin formulators seeking thermal oxidation inhibitors.
The EPA enforces TSCA chemical control regulations affecting biphenyl manufacturing and importation, while OSHA sets workplace exposure limits that influence handling protocols and protective equipment specifications across production facilities. Health Canada and PMRA coordinate cross-border chemical assessments under the US-Canada Regulatory Cooperation Council framework, creating aligned compliance obligations for suppliers operating in both jurisdictions. Stakeholders must monitor evolving state-level chemical disclosure requirements in California and New Jersey, as these programs frequently precede broader federal rulemaking on aromatic compound classifications.
Market Dynamics
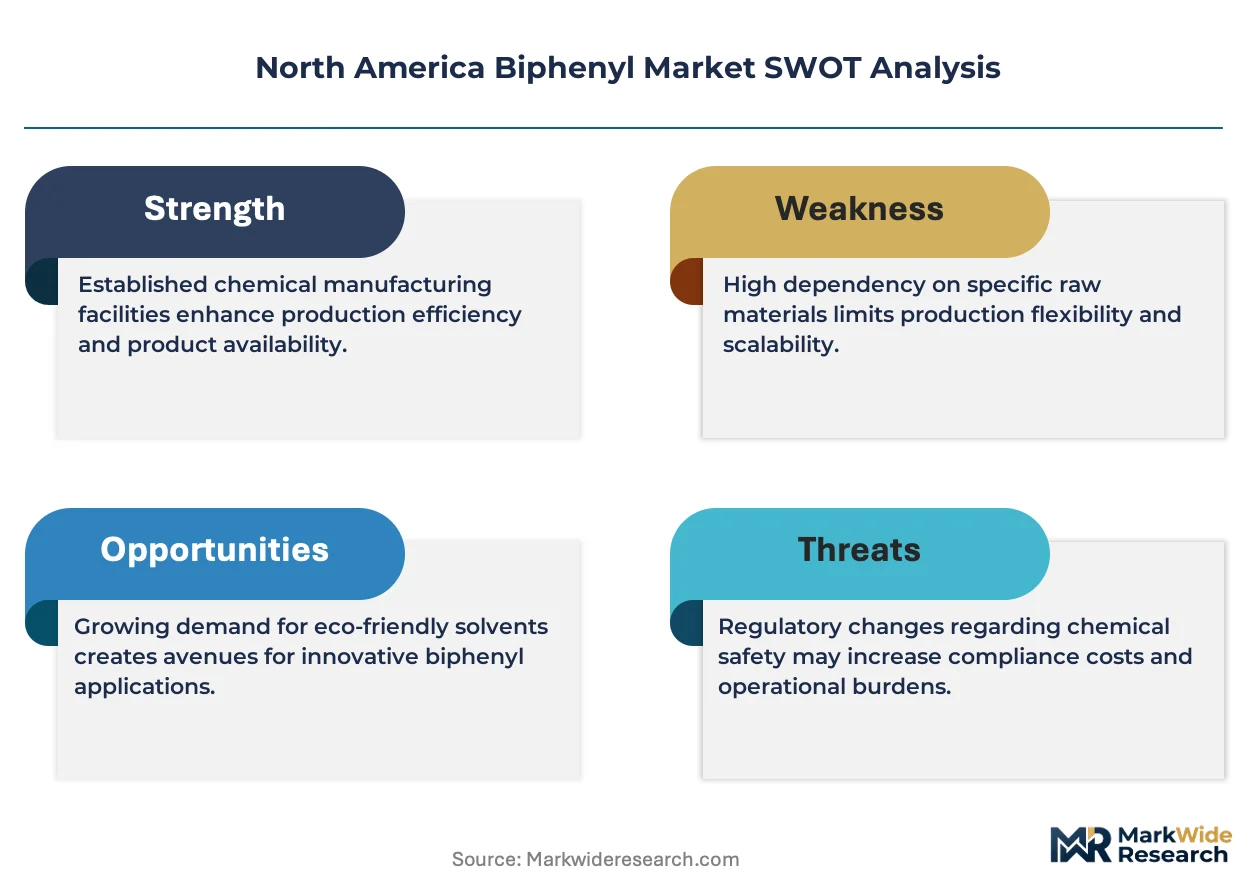
EPA TSCA Section 6 risk evaluations are compressing the supplier base for industrial aromatic compounds, forcing producers to absorb higher compliance costs or exit the North American market entirely. Chemical manufacturers are consolidating biphenyl procurement around fewer qualified suppliers capable of meeting tightened purity specifications.
Growth Catalysts
- Gulf Coast petrochemical corridor concentration:Integrated refining and chemical processing complexes in Texas and Louisiana generate captive demand for heat transfer fluids, reducing logistics costs for biphenyl suppliers co-located within this cluster.
- OSHA workplace exposure rule tightening:Revised permissible exposure limits are accelerating replacement of legacy heat transfer media with higher-purity biphenyl formulations that reduce occupational health liabilities.
- Pharmaceutical intermediate specialization:Agrochemical and active pharmaceutical ingredient manufacturers are demanding customized biphenyl derivative grades with precise isomer ratios for complex synthesis pathways.
Market Restraints
- Crude oil feedstock volatility:Biphenyl production economics remain tethered to benzene pricing, with naphtha cracking margins transmitting volatility directly to aromatic compound cost structures.
- Single-source supply risk:The domestic supplier base has contracted to a handful of integrated producers, creating vulnerability to unplanned outages at any major Gulf Coast facility.
- EPA TSCA evaluation timeline uncertainty:Pending chemical substance designations under Section 6 risk management are freezing capital allocation decisions as manufacturers await final rulemaking.
Strategic Opportunities
- Canadian cross-border chemical trade alignment:Health Canada and PMRA regulatory cooperation under the US-Canada RCC framework creates streamlined market access for US producers meeting harmonized standards.
- Biobased aromatic precursor development:Pyrolysis oil upgrading technologies are converging with conventional petrochemical routes, potentially enabling renewable-content biphenyl grades for sustainability-sensitive buyers.
- Specialty chemical distributor channel expansion:Independent distributors with technical service capabilities are capturing mid-size pharmaceutical and agrochemical accounts underserved by direct mill relationships.
Industry Challenges
- Analytical chemistry talent scarcity:The specialized skills required for EPA-compliant purity testing and TSCA documentation are concentrating at a small number of contract laboratories, extending qualification timelines.
- Legacy heat transfer fluid system retrofit complexity:Industrial facilities operating decades-old infrastructure face integration challenges when upgrading to higher-purity biphenyl formulations, requiring costly flushing and compatibility verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biphenyl Market |
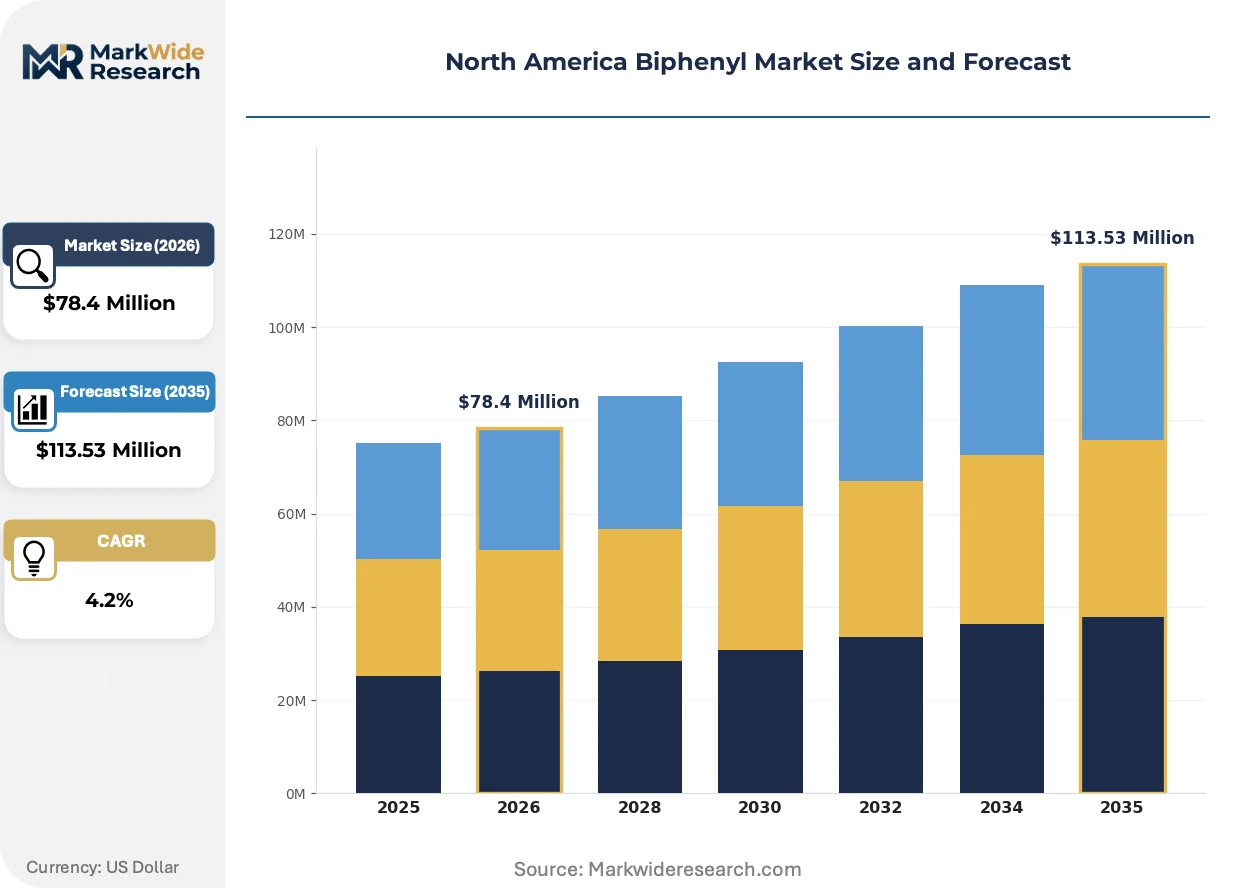
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $113.53 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biphenyl, Solid Biphenyl, Biphenyl Derivatives, Biphenyl Blend Application: Chemical Intermediates, Solvent, Heat Transfer Fluids, Material Additives End User: Chemicals, Pharmaceuticals, Electronics, Agriculture Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Eastman Chemical Company, Merck KGaA, Lanxess AG, TCI America, Alfa Aesar, Dow Inc., BASF SE, ABacipharm Corporation, Oakwood Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biphenyl Market Trends and Innovations
Process intensification and regulatory precision are reshaping how biphenyl is manufactured, specified, and procured across North American industrial markets. Technical differentiation now centers on purity assurance and supply security rather than commodity volume.
Continuous catalytic dehydrogenation technology is consolidating production economics for high-purity biphenyl. Mid-size chemical processors in the Gulf Coast corridor are adopting this approach to reduce batch-to-batch variability and meet pharmaceutical-grade specifications. The technology is consolidating competitive advantage around producers with integrated hydrogen management and catalyst regeneration capabilities.
EPA's TSCA Section 6 risk evaluation framework is mandating expanded chemical substance testing and reporting for industrial aromatics. Manufacturers must now generate chronic exposure data and environmental fate studies that previously fell outside compliance obligations. Heat transfer fluid formulators are responding by qualifying alternative purity grades and documenting supply chain provenance to preempt regulatory restrictions.
Specification-driven procurement is compressing supplier qualification cycles as end-users consolidate approved vendor lists. Pharmaceutical and agrochemical manufacturers are replacing spot-market purchasing with multi-year framework agreements tied to audit-ready quality systems. This pattern is most pronounced in New Jersey and California, where state-level chemical disclosure requirements are accelerating documentation demands beyond federal baselines.
North America Biphenyl Market Segmentation
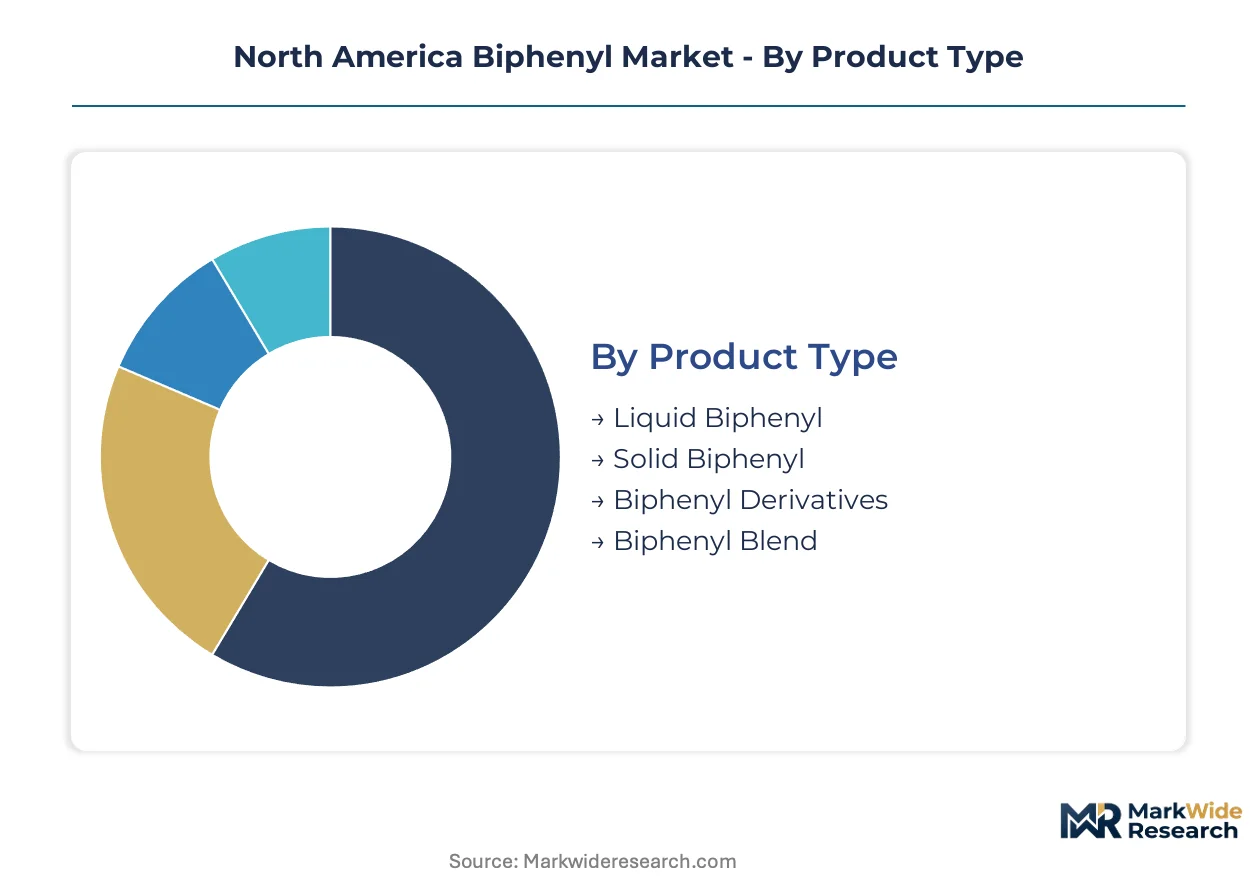
Biphenyl market segmentation reveals how capital requirements, regulatory compliance burdens, and technical specifications reshape competitive positioning across distinct product tiers. Chemical manufacturers align procurement strategies with segment-specific purity thresholds and supply security needs.
Product Type:
Capital intensity varies sharply across product categories, with derivative synthesis and high-purity liquid grades demanding specialized hydrogenation infrastructure and continuous catalytic systems that smaller producers cannot finance.
- Liquid Biphenyl:Maintains molten state above 69°C for direct injection into heat transfer fluid systems. Gulf Coast petrochemical complexes in Texas and Louisiana absorb the largest volumes for integrated refining operations requiring thermal stability above 300°C. EPA TSCA purity documentation now mandates batch-level analytical certificates.
- Biphenyl Derivatives:Encompass halogenated, nitrated, and alkylated variants serving pharmaceutical and agrochemical synthesis pathways. Custom isomer ratios require dedicated reactor trains and catalyst regeneration capabilities that concentrate production among integrated aromatic hydrocarbon platforms. Health Canada PMRA cross-border alignment creates streamlined qualification for US producers.
- Solid Biphenyl:Flaked or crystalline grades ship in temperature-controlled containers for laboratory and small-batch chemical processing.
- Biphenyl Blend:Eutectic mixtures with diphenyl oxide and other aromatics optimize freezing point depression for climate-variable installations.
Most installed capacity flows through Liquid Biphenyl. Expansion is steepest in Biphenyl Derivatives.
Application:
Application segmentation tracks how thermal performance requirements and regulatory exposure reshape procurement patterns across industrial end-uses.
- Heat Transfer Fluids:Command established volume positions due to thermal stability requirements in chemical processing and power generation installations. OSHA workplace exposure rule tightening accelerates replacement of legacy media with higher-purity formulations that reduce occupational health liabilities in Texas and Louisiana corridor facilities.
- Chemical Intermediates:Feed pharmaceutical active ingredient synthesis and agrochemical manufacturing with precisely specified aromatic building blocks. Multi-year framework agreements now dominate procurement as manufacturers consolidate approved vendor lists for audit-ready quality systems.
- Solvent:Serves specialized extraction and crystallization applications in laboratory and pilot-scale chemical processing.
- Material Additives:Functions as thermal oxidation inhibitor in polymer and resin formulations with stable, mature demand patterns.
Volume concentrates in Heat Transfer Fluids. Chemical Intermediates gain share fastest.
End User:
End user segmentation reflects divergent specification stringency, with pharmaceutical and electronics sectors imposing purity thresholds that exclude commodity-grade suppliers.
- Chemicals:Integrated petrochemical producers and specialty chemical manufacturers constitute the foundational demand base for standard-grade biphenyl in heat transfer and intermediate applications.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers demand customized derivative grades with precise isomer ratios and comprehensive impurity profiling. New Jersey and California state-level chemical disclosure requirements accelerate documentation demands beyond federal EPA baselines.
- Electronics:Semiconductor and display material producers utilize ultra-high purity grades for photoresist and electronic chemical applications.
- Agriculture:Agrochemical intermediate synthesis drives seasonal procurement patterns tied to planting cycle chemical manufacturing.
Largest volume flows to Chemicals. Steepest specification escalation occurs in Pharmaceuticals.
Distribution Channel:
Channel segmentation tracks how technical service requirements and order scale reshape intermediary economics across customer tiers.
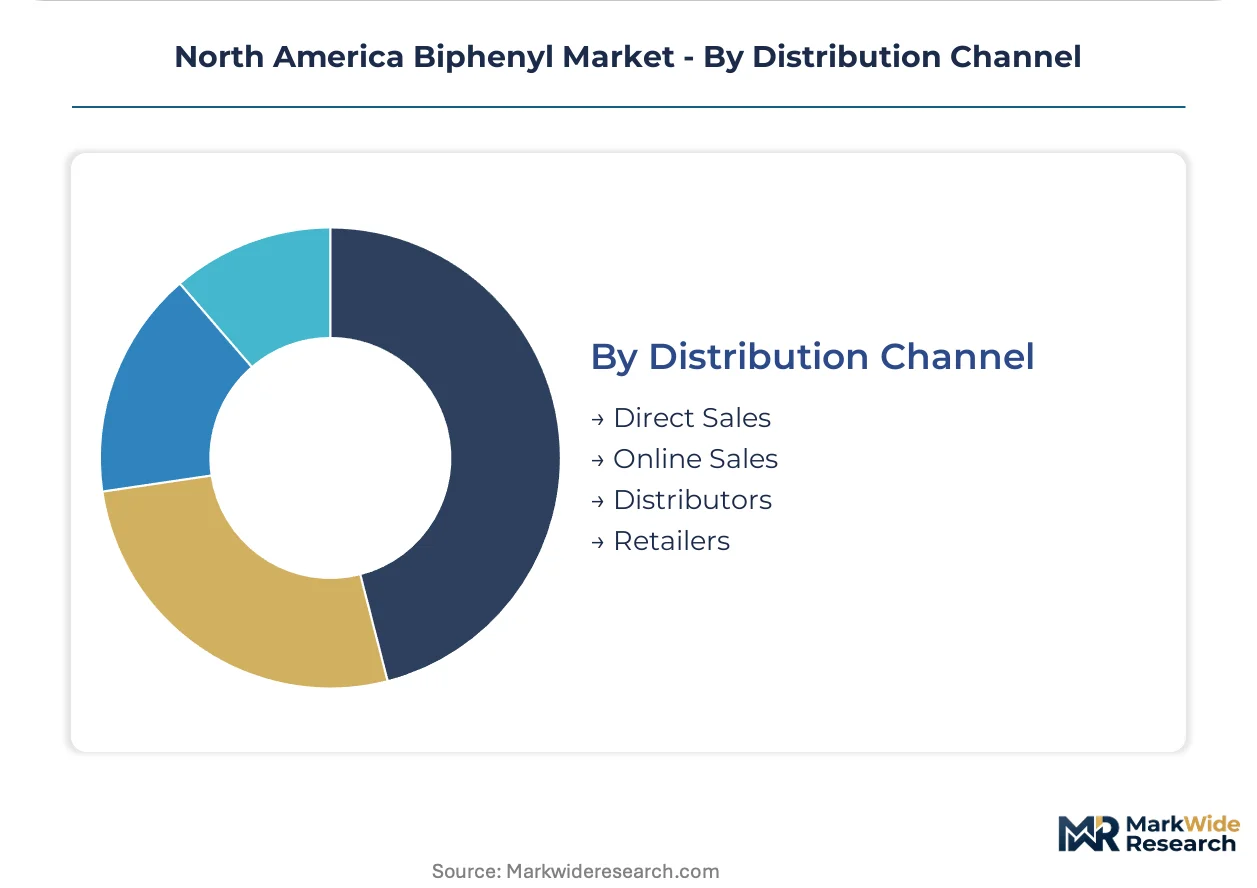
- Direct Sales:Large-volume heat transfer fluid formulators and integrated chemical processors negotiate multi-year supply agreements with producers. Captive logistics and dedicated account management justify bypassing intermediaries for Gulf Coast corridor customers.
- Distributors:Independent technical distributors capture mid-size pharmaceutical and agrochemical accounts with formulation support and smaller lot flexibility. Channel expansion accelerates as distributors invest in TSCA-compliant documentation and analytical capabilities.
- Online Sales:Laboratory and research-scale quantities move through specialized chemical supply platforms with expedited handling.
- Retailers:Limited to consumer-adjacent applications with minimal presence in industrial biphenyl commerce.
Direct Sales channels handle the largest volume tonnage. Distributor channel expansion is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American biphenyl industry traces its commercial scale to post-war petrochemical expansion along the United States Gulf Coast, where integrated refineries first deployed biphenyl-based heat transfer fluids for high-temperature process operations.
United States
Texas and Louisiana host the continent's densest concentration of biphenyl consumption, with Gulf Coast petrochemical complexes absorbing volumes for integrated refining and chemical processing. EPA TSCA Section 6 risk evaluations are tightening purity documentation requirements for industrial aromatic compounds. The Houston Ship Channel corridor sustains captive demand from heat transfer fluid formulators co-located with downstream users.
Canada
Ontario and Quebec chemical manufacturers import biphenyl derivatives for pharmaceutical intermediate synthesis under Health Canada PMRA coordination frameworks. The US-Canada Regulatory Cooperation Council aligns chemical assessment protocols, streamlining cross-border qualification for American producers. Sarnia's petrochemical cluster maintains specialized storage and handling infrastructure for temperature-controlled aromatic shipments.
Mexico
Nuevo León and the Bajío Region are attracting specialty chemical manufacturing investments that source biphenyl for heat transfer and synthesis applications. Mexican environmental regulators are adopting hazard communication standards convergent with OSHA workplace exposure protocols. Querétaro's aerospace and automotive supplier parks generate emerging demand for high-purity thermal management fluids.
North America Biphenyl Market Competitive Landscape
The competitive structure tilts toward integrated aromatic hydrocarbon platforms with captive hydrogenation and catalyst regeneration capabilities. Three producer archetypes dominate: Gulf Coast petrochemical majors with backward integration into benzene feedstocks; European-headquartered specialty chemical multinationals with dedicated derivative synthesis trains; and technical distributors investing in TSCA-compliant documentation infrastructure. Consolidation pressures are accelerating as EPA purity mandates raise fixed compliance costs, while strategic partnerships between formulators and analytical laboratories extend qualification timelines.
Within the integrated producer tier, Eastman Chemical Company and Dow Inc. exemplify scale-driven positions anchored to Gulf Coast manufacturing corridors. Lanxess AG represents the specialty derivative archetype, with AG-suffix corporate structure indicating German-domiciled parentage and pharmaceutical-grade purification capabilities. Among technical distributors, TCI America occupies a documentation-intensive position serving mid-scale pharmaceutical and agrochemical accounts with smaller lot flexibility and audit-ready quality systems.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Merck KGaA |
| Lanxess AG |
| TCI America |
| Alfa Aesar |
| Dow Inc. |
| BASF SE |
| ABacipharm Corporation |
| Oakwood Products, Inc. |
| Others |
Pricing and Supply Chain Analysis
Integrated petrochemical majors with captive benzene-to-biphenyl conversion assets command supply-side discipline that translates directly into pricing power for high-purity grades serving pharmaceutical and heat transfer fluid formulators. Their Gulf Coast manufacturing concentration insulates margin structures from logistics cost volatility that erodes independent distributors competing on spot-market benzene exposure.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity-grade levels segments the market by purity certification and documentation burden. Price differentiation hinges on EPA TSCA batch-level analytical certificates and ISO 17025 laboratory accreditation status, with pharmaceutical buyers absorbing premiums for audit-ready quality systems. Cost compression in industrial-grade tiers is intensifying because OSHA workplace exposure rule tightening forces legacy system retrofits that compete for procurement budgets. Chemical processors in Texas and Louisiana exhibit lowest price sensitivity due to captive logistics advantages, while mid-size agrochemical formulators face highest budget constraints.
Supply Chain Analysis
Regional distribution centers along the Houston Ship Channel and Lake Charles corridor maintain temperature-controlled storage infrastructure for molten biphenyl transfer to downstream formulators. Geographic supply concentration centers on the United States, with Canadian import flows through Sarnia and emerging Mexican demand from Querétaro aerospace suppliers. Raw material dependencies draw from benzene feedstocks, hydrogen supply for catalytic dehydrogenation, and specialized catalyst regeneration services. Single-source vulnerability concentrates at Gulf Coast hydrogenation facilities with limited redundancy. Distribution runs through direct mill relationships for large-volume heat transfer fluid accounts and technical distributors for pharmaceutical intermediate lots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-grade purification investments that capture pharmaceutical specification escalation outpacing industrial-grade commoditization pressures.
For Market Incumbents: Deepen backward integration into benzene feedstock security and catalyst regeneration capabilities to defend against emerging biobased aromatic competitors. EPA TSCA Section 6 compliance cost concentration favors producers with in-house analytical chemistry infrastructure over outsourced documentation. Capacity addition in the Gulf Coast corridor reinforces captive supply positioning for heat transfer fluid formulators consolidating vendor lists. For New Entrants and Emerging Players: Health Canada PMRA regulatory alignment under the US-Canada RCC framework opens a window for US-based derivative specialists to capture Ontario and Quebec pharmaceutical intermediate demand without redundant qualification costs. Target mid-size agrochemical accounts in the Midwest with customized isomer ratio capabilities underserved by commodity producers. Technical distributor partnerships with TSCA-compliant documentation infrastructure offer the fastest go-to-market path. For Investors and Strategic Acquirers: Valuations sit cheapest among independent technical distributors investing in analytical laboratory capabilities ahead of EPA purity mandate enforcement. Long-term viability favors assets with pharmaceutical-grade certification infrastructure over commodity-grade commodity exposure. Watch for Health Canada PMRA designation harmonization announcements as inflection indicators for cross-border trade volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzene Feedstock | Captive supply security insulates margin structures from naphtha cracking volatility in Gulf Coast corridors. |
| Pharmaceutical-Grade Purification Investment | EPA TSCA batch-level documentation capabilities capture specification escalation in New Jersey and California markets. |
| Health Canada PMRA Qualification | Cross-border regulatory alignment streamlines market access for US producers serving Ontario and Quebec chemical manufacturers. |
| Technical Distributor Channel Expansion | Mid-size pharmaceutical and agrochemical accounts with smaller lot requirements generate higher service-margin economics. |
| Catalyst Regeneration Capability Buildout | Continuous catalytic dehydrogenation reliability reduces batch-to-batch variability for heat transfer fluid formulators. |
Research Methodology
Direct dialogue with plant managers at Gulf Coast petrochemical complexes, procurement leads at downstream heat transfer fluid formulators, distribution channel partners with TSCA documentation capabilities, and technical R&D directors at pharmaceutical intermediate manufacturers grounded qualitative findings. Secondary validation drew from EPA chemical substance evaluations, OSHA permissible exposure limit rulemakings, SEC 10-K filings from integrated aromatic hydrocarbon producers, and customs trade data tracking cross-border flows. Bottom-up and top-down triangulation reconciled volume estimates against capacity utilization disclosures and end-use consumption patterns.
Segment-level outputs across the projection horizon reflect modeled interactions between product type tiers, application specifications, end-user purity requirements, and distribution channel economics. Grade tier, end-use industry, and regional production hub dimensions structured the analytical framework. CAGRs were derived from regression analysis of historical benzene price transmission, regulatory compliance cost trajectories, and pharmaceutical intermediate demand elasticity. Forecast inputs incorporated EPA TSCA evaluation timeline scenarios and OSHA workplace exposure rule implementation pacing.
Revisions become necessary when EPA finalizes Section 6 risk management designations, benzene feedstock volatility exceeds historical bands, or major Gulf Coast production facilities experience unplanned outages. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Oryzenin Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Phenol Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
Chlorinated Isocyanurates Market
Organic Chemicals
Pentachlorophenol Market