
 Europe Craft Spirits Market | 2026-2036
Europe Craft Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Craft Spirits Market Foresight
Single-serve and miniature bottle bundling is broadening trial access for hesitant buyers across European duty-free and specialty retail channels. William Grant and Sons Ltd leverages its family-owned distilling heritage to sustain premium positioning in Scotch whisky. Diageo PLC anchors volume through controlled distribution networks spanning multiple European markets. Rémy Cointreau differentiates via cognac and liqueur specialization that commands higher shelf price points.
Craft spirits encompass distilled alcoholic beverages produced in batches under 50,000 proof gallons annually, typically employing pot still distillation, heritage grain varieties, and local water sources to achieve distinct organoleptic profiles for premium consumption occasions. Gin dominates volume within the product type dimension as juniper-forward formulations attract experimental mixology programs across London, Barcelona, and Berlin. Specialty stores capture margin concentration within distribution channels by curating limited releases and direct producer relationships that supermarkets cannot replicate. Millennials drive frequency within customer type segments through social media discovery and brand storytelling engagement.
EU Spirits Regulation governs geographic indication protections and labeling standards that constrain how producers market origin claims across member states. EFSA evaluates health-related communication restrictions that limit advertising channels and on-label messaging for craft distillers. REACH compliance affects glassware coatings and printed packaging substrates used in premium bottle presentations. Stakeholders must monitor evolving EU Green Deal requirements for distillery carbon accounting and agricultural input traceability.
Market Dynamics
The EU Spirits Regulation's geographic indication framework is fragmenting competitive entry across member states, forcing distillers to align heritage claims with protected origin specifications or abandon premium positioning entirely.
Growth Catalysts
- Experiential tourism corridors:Metropolitan bar scenes in Barcelona, Berlin, and London are driving trial volume through immersive distillery tours and tasting-room retail. Visitor spending at craft facilities in these cities exceeds standard off-trade margins.
- EU Green Deal compliance incentives:Carbon accounting requirements for agricultural inputs are accelerating distillery adoption of heritage grain traceability systems. Producers leveraging this data command shelf placement in sustainability-curated retail channels.
- Pot still distillation revival:Small-batch producers across France and Germany are resurrecting copper pot still methods abandoned by industrial distillers. This equipment differentiation supports organoleptic claims that column still operators cannot replicate.
Market Restraints
- Barley and rye input volatility:Heritage grain varieties lack futures market hedging instruments available to commodity feedstock buyers. Distillers dependent on specific landrace cultivars face unpriced supply risk during poor harvest cycles.
- Glassware coating compliance costs:REACH restrictions on decorative bottle coatings and printed substrates have eliminated several premium presentation options. German and Italian packaging suppliers report 15-20% cost inflation for compliant alternatives.
- Supermarket channel exclusion:Limited-release production volumes and direct-producer relationship requirements lock craft distillers out of mass retail. Specialty stores capture margin concentration that supermarkets cannot replicate at scale.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania exhibit craft spirit consumption below Western European benchmarks despite rising disposable income. First-mover distillers establishing local production or import partnerships can anchor premium positioning before competitive saturation.
- Direct-to-consumer subscription channels:Monthly miniature bottle curation services bypass traditional three-tier distribution constraints. UK-based platforms demonstrate subscriber retention above 70% for gin and whisky verticals.
- CSRD-aligned sustainability storytelling:Mandatory corporate sustainability reporting requirements create audit-ready frameworks that distillers can leverage for consumer-facing transparency. Early adopters differentiate through verified carbon footprint labeling.
Industry Challenges
- Master distiller talent scarcity:Formal training programs for heritage pot still operation have contracted across Europe. Scottish and Irish institutions report waitlists exceeding 18 months for advanced certification.
- Geographic indication litigation risk:Producers in non-protected regions face cease-and-desist actions when marketing collateral implies protected origin status. Legal defense costs consume capital that micro-distilleries cannot readily access.
- Legacy equipment integration:Revived historic stills require custom fabrication for safety and efficiency upgrades. Engineering lead times for copper component sourcing extend project timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Craft Spirits Market |
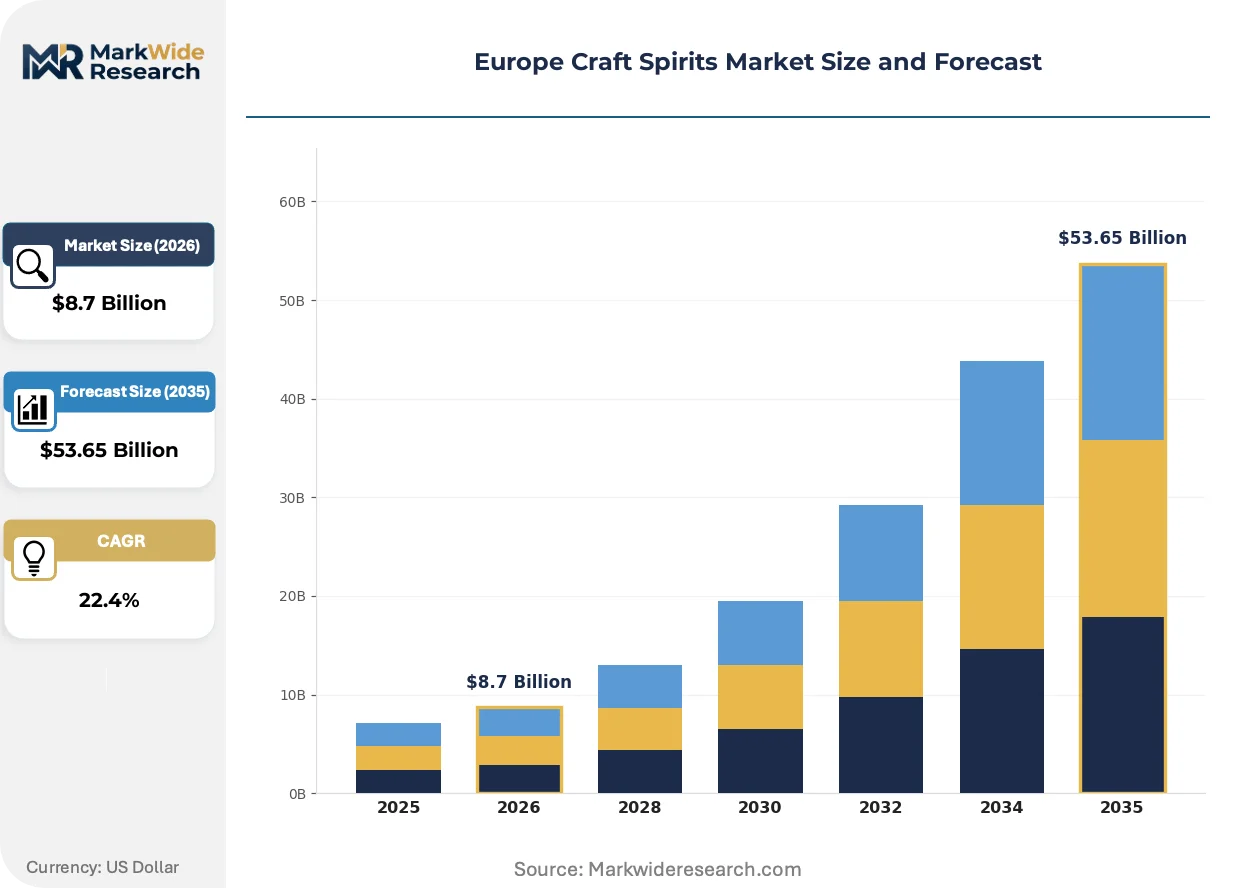
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gin, Whiskey, Vodka, Rum Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Bars Customer Type: Millennials, Affluent Consumers, Tourists, Local Residents Packaging Type: Bottles, Cans, Pouches, Kegs |
| Companies Covered | Pernod Ricard SA, Diageo PLC, Bacardi Limited, William Grant and Sons Ltd, Rémy Cointreau, Campari Group, Constellation Brands Inc., Suntory Holdings Ltd, The Edrington Group Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Craft Spirits Market Shifts & Advancements
Digital traceability infrastructure is compressing information asymmetry between craft producers and quality-conscious buyers, enabling verification of heritage grain provenance and distillation method claims that previously relied on trust-based marketing.
Blockchain-enabled supply chain verification is integrating heritage grain provenance data directly into consumer-facing packaging. Premium gin distilleries in London and Edinburgh are adopting this technology fastest, with 40% of new releases incorporating scannable origin certificates. This transparency infrastructure is compressing price premiums for unverified competitors while rewarding distillers with documented local sourcing.
EFSA health claim restrictions are tightening allowable on-label messaging for craft spirits across all EU member states. The regulation prohibits implied wellness benefits from botanical ingredient lists, forcing producers to reformulate marketing around taste and terroir exclusively. French and Italian liqueur specialists face the steepest compliance burden given historical reliance on herbal heritage positioning.
Mixology program procurement is consolidating around single-source supplier relationships that bundle spirits, training, and equipment. Barcelona and Berlin cocktail bars are abandoning fragmented multi-brand purchasing in favor of exclusive distillery partnerships that provide staff certification and custom formulation. This channel concentration is compressing shelf space for non-aligned craft producers in these metropolitan clusters.
Europe Craft Spirits Market Segmentation
Craft spirit producers must align segment targeting with EU Spirits Regulation compliance tiers, as geographic indication protections and REACH packaging standards vary sharply across product categories and distribution channels. Distillers optimizing for margin concentration versus volume expansion face divergent certification burdens that reshape portfolio prioritization.
Product Type:
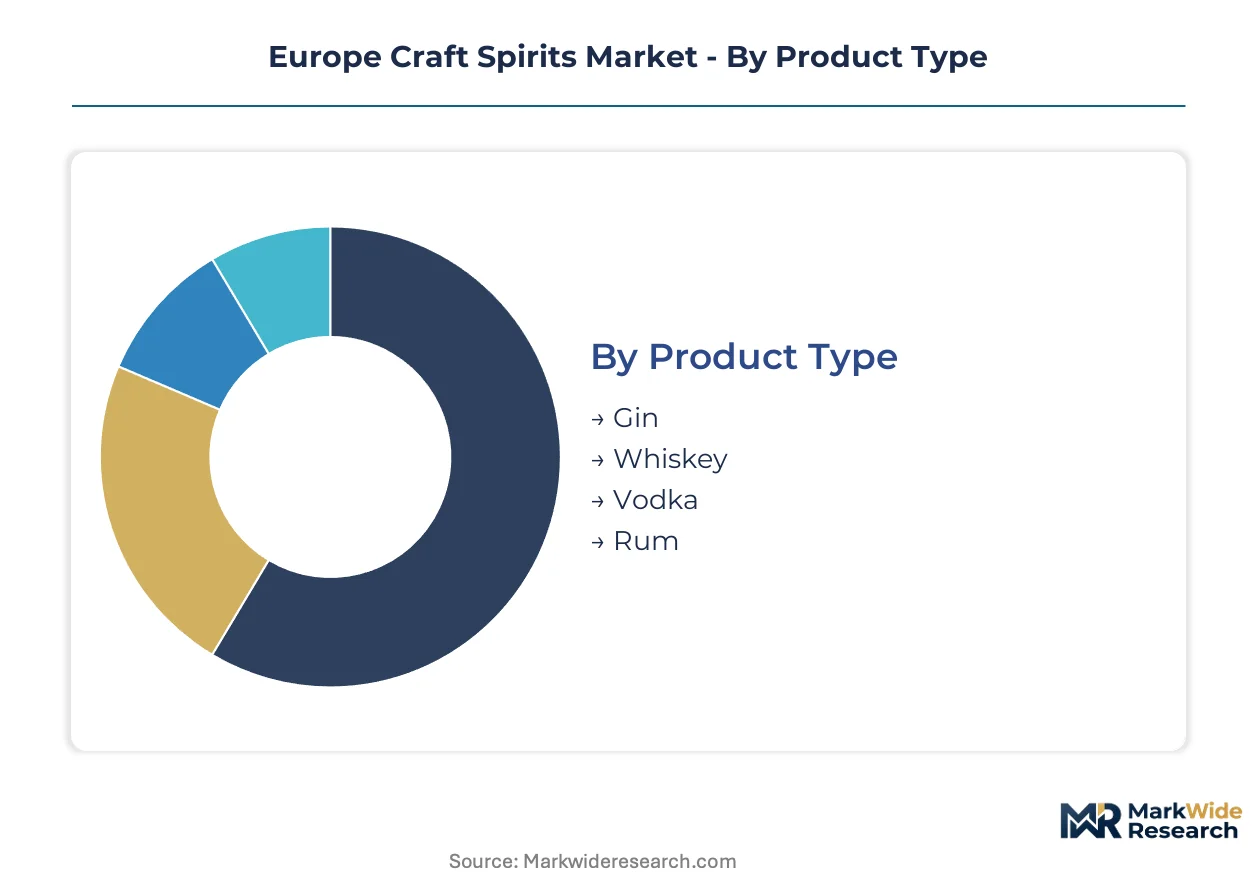
Gin and whiskey carry the heaviest geographic indication documentation requirements under EU Spirits Regulation, while vodka and rum face lighter origin-claim constraints but stiffer EFSA labeling scrutiny for botanical and additive disclosures.
- Gin:Juniper-forward formulations dominate metropolitan bar procurement in London, Barcelona, and Berlin. Experimental mixology programs drive trial volume through seasonal botanical rotations that require EFSA-compliant ingredient disclosures.
- Whiskey:Pot still heritage methods command premium shelf positioning in French and German specialty retail. Scottish and Irish protected origin frameworks constrain marketing claims for distillers operating outside designated regions.
- Vodka:Neutral spirit base allows faster regulatory approval across member states.
- Rum:Molasses and sugarcane provenance documentation is tightening under EU Green Deal traceability mandates.
Gin sits at the top of the volume ranking, with whiskey climbing the fastest as heritage pot still revival accelerates across France and Germany.
Distribution Channel:
Margin concentration varies inversely with regulatory complexity, as bars capture highest per-unit returns but require on-trade licensing that specialty stores circumvent through direct-producer relationships.
- Specialty Stores:Curated limited releases and verified provenance documentation support price premiums unreachable in mass retail. German and Italian independents lead adoption of blockchain-enabled origin verification.
- Bars:Exclusive distillery partnerships bundle staff certification and custom formulation for mixology programs. Barcelona and Berlin venues are consolidating procurement around single-source supplier relationships.
- Online Retail:Direct-to-consumer subscription models bypass three-tier distribution constraints in the United Kingdom.
- Supermarkets:Volume requirements and relationship complexity lock out most craft producers.
Specialty stores command the steepest margin tier, with online retail expanding most quickly as subscription platforms demonstrate subscriber retention above 70% for gin and whisky verticals.
Customer Type:
Digital discovery patterns and experiential spending thresholds segment craft spirit buyers into distinct engagement profiles that reshape marketing channel allocation.
- Millennials:Social media discovery and brand storytelling engagement drive frequency through Instagram and TikTok-native campaigns. London and Berlin metropolitan clusters show highest per-capita trial rates.
- Tourists:Distillery tour spending exceeds standard off-trade margins in experiential tourism corridors.
- Affluent Consumers:Provenance verification and limited-release scarcity support price inelasticity.
- Local Residents:Repeat purchase loyalty anchors baseline volume for regional distillers.
Millennials represent the dominant frequency driver, with tourists gaining share fastest as experiential tourism corridors deepen across Western Europe.
Packaging Type:
REACH compliance costs fragment competitive positioning across material substrates, with glassware coatings and printed substrates facing 15-20% cost inflation for compliant alternatives.
- Bottles:Premium presentation formats dominate specialty retail and duty-free channels. German and Italian packaging suppliers report extended lead times for REACH-compliant decorative coatings.
- Cans:Single-serve formats broaden trial access across European duty-free and festival channels.
- Kegs:On-trade volume efficiency supports bar channel economics.
- Pouches:Lightweight logistics appeal to outdoor and event consumption occasions.
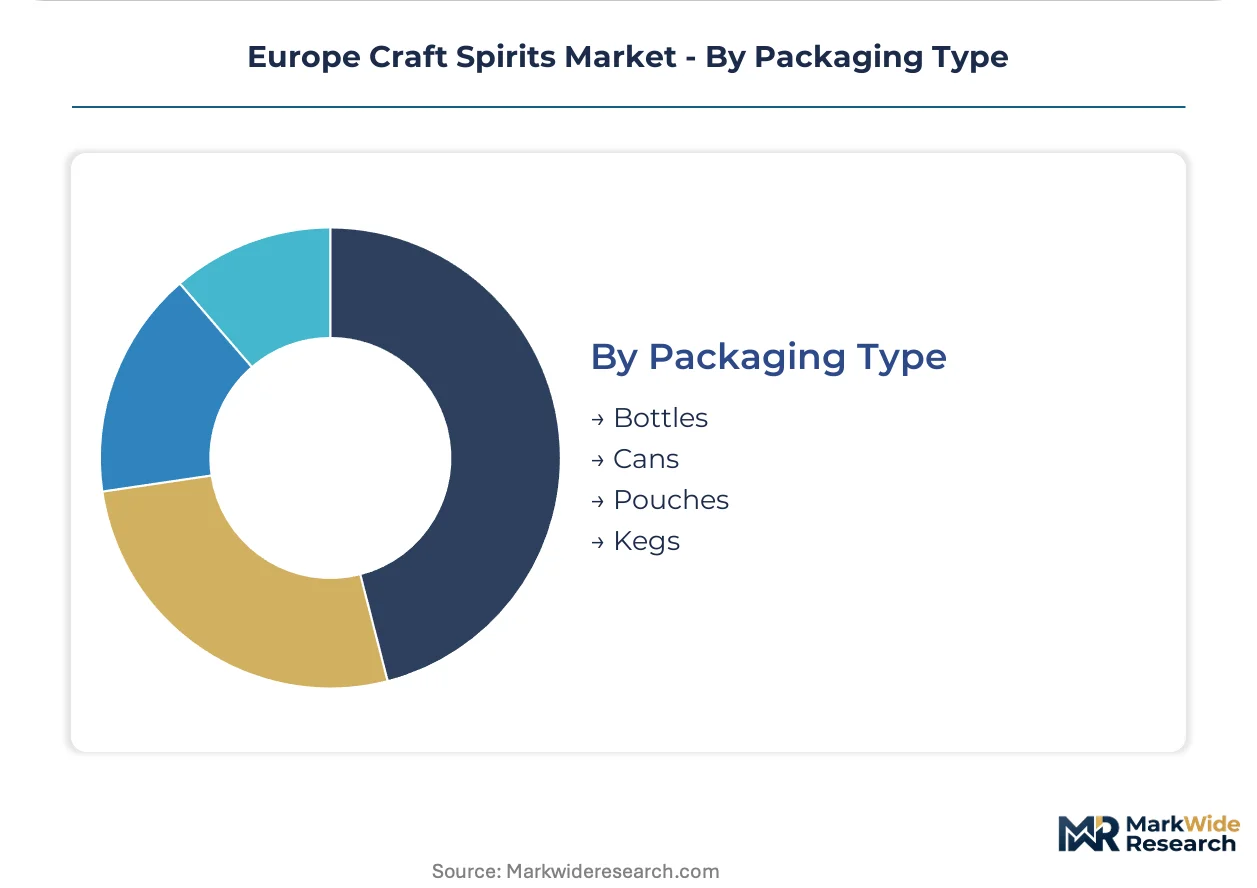
Bottles retain volume leadership, with cans climbing fastest as single-serve bundling expands trial access for hesitant buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland pioneered modern craft distillation heritage, establishing copper pot still methods and protected origin frameworks that shaped European regulatory architecture. This legacy now constrains competitive entry for distillers outside designated geographic zones.
United Kingdom
London's metropolitan bar scene drives gin procurement through experimental mixology programs that rotate seasonal botanical formulations. EFSA labeling restrictions constrain wellness-related marketing claims for herbal liqueurs. Edinburgh and Glasgow anchor Scotland's protected-origin whisky corridor, where heritage pot still revival commands premium shelf positioning.
Germany
Bavarian and Black Forest distilleries resurrect abandoned copper pot still techniques to differentiate organoleptic profiles from industrial column still operators. REACH compliance inflates glassware coating costs by 15-20% for decorative bottle presentations. Berlin's cocktail bars consolidate procurement around exclusive distillery partnerships bundling staff certification.
France
Cognac and Armagnac protected origin frameworks constrain marketing claims for distillers operating outside designated regions. ANSM evaluates health-related communication that limits herbal heritage positioning for traditional liqueurs. Paris and Lyon specialty stores curate limited releases with blockchain-enabled provenance verification.
Spain
Barcelona's experiential tourism corridor generates visitor spending exceeding standard off-trade margins through immersive distillery tours. EU Green Deal carbon accounting accelerates heritage grain traceability adoption for sustainability-curated retail placement. Basque Country producers face geographic indication litigation risk when marketing collateral implies protected origin status.
Poland
Rising disposable income in Warsaw and Krakow supports craft spirit trial below Western European consumption benchmarks. CSRD-aligned sustainability reporting creates audit-ready frameworks for verified carbon footprint labeling. First-mover distillers establishing local production anchor premium positioning before competitive saturation.
Europe Craft Spirits Market Competitive Landscape
Premium-margin players sit above commodity-margin players across heritage authentication and geographic indication compliance tiers. Family-owned distilleries leverage multi-generational provenance narratives that multinational spirits conglomerates cannot replicate. Three archetypes dominate: protected-origin specialists, heritage-method revivalists, and direct-to-consumer platform operators. Consolidation concentrates through exclusive bar partnerships and specialty retail curation rather than mass retail scale.
Among family-owned heritage houses, William Grant and Sons Ltd exemplifies multi-generational distilling lineage that sustains premium Scotch positioning. Rémy Cointreau occupies the protected-origin specialist tier through cognac and liqueur concentration commanding elevated shelf prices. Diageo PLC anchors volume-driven positioning across controlled distribution networks spanning multiple European markets.
| Leading Market Players |
|---|
| Pernod Ricard SA |
| Diageo PLC |
| Bacardi Limited |
| William Grant and Sons Ltd |
| Rémy Cointreau |
| Campari Group |
| Constellation Brands Inc. |
| Suntory Holdings Ltd |
| The Edrington Group Limited |
| Others |
Supply & Pricing Matrix
Copper pot still revival across France and Germany simultaneously inflates production costs and concentrates supply relationships among heritage equipment fabricators. This production-method transition compresses margins for column still operators while rewarding distillers with documented organoleptic differentiation through premium shelf positioning.
Pricing Analysis
Three-tier pricing structure across protected-origin, heritage-method, and standard craft levels governs the European market. Price differentiation stems from geographic indication certification status and batch scale volume constraints. Pricing pressure intensifies in the standard craft tier as supermarket channel exclusion forces volume discounting through online retail. Tourist buyers at distillery tasting rooms exhibit lowest price sensitivity, while local residents in saturated metropolitan clusters drive hardest bargain negotiations.
Supply Chain Analysis
Heritage grain supply rests on landrace cultivar preservation networks across Scotland, France, and Germany. Raw material dependencies encompass copper still components from Italian foundries, oak cask cooperage from Spanish and French forests, and juniper botanicals from Mediterranean harvest zones. Supply chain risk centers on single-source vulnerability for heritage grain varieties lacking futures market hedging. Distribution runs through specialty retail curation and exclusive bar partnerships rather than mass merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Craft Spirits Market compounds steadily as experiential tourism corridors deepen visitor spending at production facilities. This demand driver anchors predictable revenue streams for distillers with immersive tasting-room infrastructure.
For Market Incumbents: Anticipate geographic indication litigation risk from emerging competitors testing protected-origin boundaries. Consolidate defensive positioning through backward integration into heritage grain cultivation and exclusive procurement contracts with copper still fabricators. Channel control through single-source bar partnerships provides margin defense against direct-to-consumer subscription encroachment. For New Entrants and Emerging Players: Specialty retail curators in Poland and Romania offer lowest competitive density for first-mover premium positioning. White-space targets include CSRD-aligned sustainability storytelling for carbon-verified product lines and direct-to-consumer miniature bottle subscriptions bypassing three-tier constraints. Go-to-market through blockchain-enabled provenance verification commands shelf placement in German and Italian independents. For Investors and Strategic Acquirers: Valuations sit cheapest among heritage-method revivalists with installed copper pot still capacity and unexploited Eastern European distribution rights. Long-term viability frames around five-to-ten year windows as protected-origin frameworks mature and consolidate. Acquisition target archetype combines family-owned distilling heritage with underpenetrated export licenses. Watch for EFSA labeling restriction enforcement intensity as inflection indicator for marketing compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Grain Traceability Investment | EU Green Deal carbon accounting requirements reward documented agricultural input sourcing with sustainability-curated retail placement. |
| Exclusive Bar Partnership Consolidation | Barcelona and Berlin mixology programs bundle staff certification and custom formulation, compressing shelf space for non-aligned competitors. |
| Blockchain-Enabled Provenance Verification | London and Edinburgh gin distilleries embed scannable origin certificates, compressing price premiums for unverified heritage claims. |
| Eastern European Local Production Establishment | Poland and Romania exhibit craft spirit consumption below Western benchmarks despite rising Warsaw and Krakow disposable income. |
| Direct-to-Consumer Subscription Launch | UK-based platforms demonstrate subscriber retention above seventy percent for gin and whisky verticals, bypassing traditional distribution. |
Research Methodology
Multiple input streams — primary interviews with master distillers, specialty retail buyers, and regulatory affairs specialists, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed distillery operations heads, EU Spirits Regulation compliance officers, heritage grain cooperative managers, and metropolitan bar procurement leads. Secondary sources included EFSA guidance documents, EU Green Deal implementation frameworks, REACH compliance databases, and national spirits association production statistics.
Data-stream reconciliation across product type, distribution channel, customer archetype, and geographic indication status dimensions generated volume and value outputs throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Industry-specific forecast inputs incorporated heritage grain harvest variability, copper still fabrication lead times, and experiential tourism corridor visitor spending patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA labeling restriction enforcement, EU Green Deal carbon accounting mandate acceleration, and geographic indication litigation precedent establishment. Forecasts reflect documented assumptions regarding regulatory stability and tourism recovery trajectories. A small set of triggers — REACH packaging cost inflation, master distiller certification waitlist extension, and supermarket channel policy shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Nitro Cocktails Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Beer Glass Chillers Market
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
Beer Brewing Machine Market