
 Beer Brewing Machine Market | 2026-2036
Beer Brewing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Brewing Machine Market Outlook
Microbreweries are reorganizing procurement patterns across the beer brewing machine landscape, shifting investment from basic kettles toward integrated all-in-one systems. PicoBrew leverages digital control architecture to capture home brewer loyalty. Speidel Tank- und Behälterbau GmbH anchors its position through German-engineered fermenter reliability. WilliamsWarn competes on compact footprint design for urban microbrewery installations.
A beer brewing machine is a thermomechanical assembly that heats wort to controlled temperatures, typically managing mash cycles between 148°F and 162°F, to convert starched grains into fermentable sugars for beer production. All-in-one brew systems command the largest installed base by unit volume, though automated brewing technology captures disproportionate margin pools through software-enabled repeatability. Electric brew kettles remain the entry-level workhorse for home brewers, while 10-gallon capacity equipment represents the fastest-growing configuration as microbreweries scale beyond pilot batches without committing to industrial-scale infrastructure.
The US FDA and OSHA govern commercial brewing equipment sanitation and workplace safety standards, while the EU's CE marking and Machinery Directive establish conformity requirements for machines sold across European member states. Germany's BfR (Federal Institute for Risk Assessment) issues material-specific guidance on food-contact surfaces in brewing vessels, directly shaping stainless steel specification decisions by manufacturers. Stakeholders must monitor how energy-efficiency regulations in multiple jurisdictions recalibrate heating element design priorities and total cost-of-ownership calculations for buyers.
Market Dynamics
Automated brewing technology is compressing batch-to-batch variability while reshaping capital allocation decisions across microbrewery procurement desks. The shift from manual kettle operations toward software-controlled mash cycles is redrawing competitive boundaries between integrated system suppliers and component specialists.
Growth Catalysts
- EU Machinery Directive compliance:CE marking requirements for automated brewing systems are accelerating replacement cycles among European microbreweries seeking export-ready certification.
- Stainless steel fermentation vessels:Material specification upgrades driven by Germany's BfR food-contact guidance are expanding addressable equipment spend per installation.
- Home-to-microbrewery graduation:Scaling hobbyist brewers in the United States are purchasing 10-gallon capacity systems as stepping-stone infrastructure before industrial-scale commitments.
Market Restraints
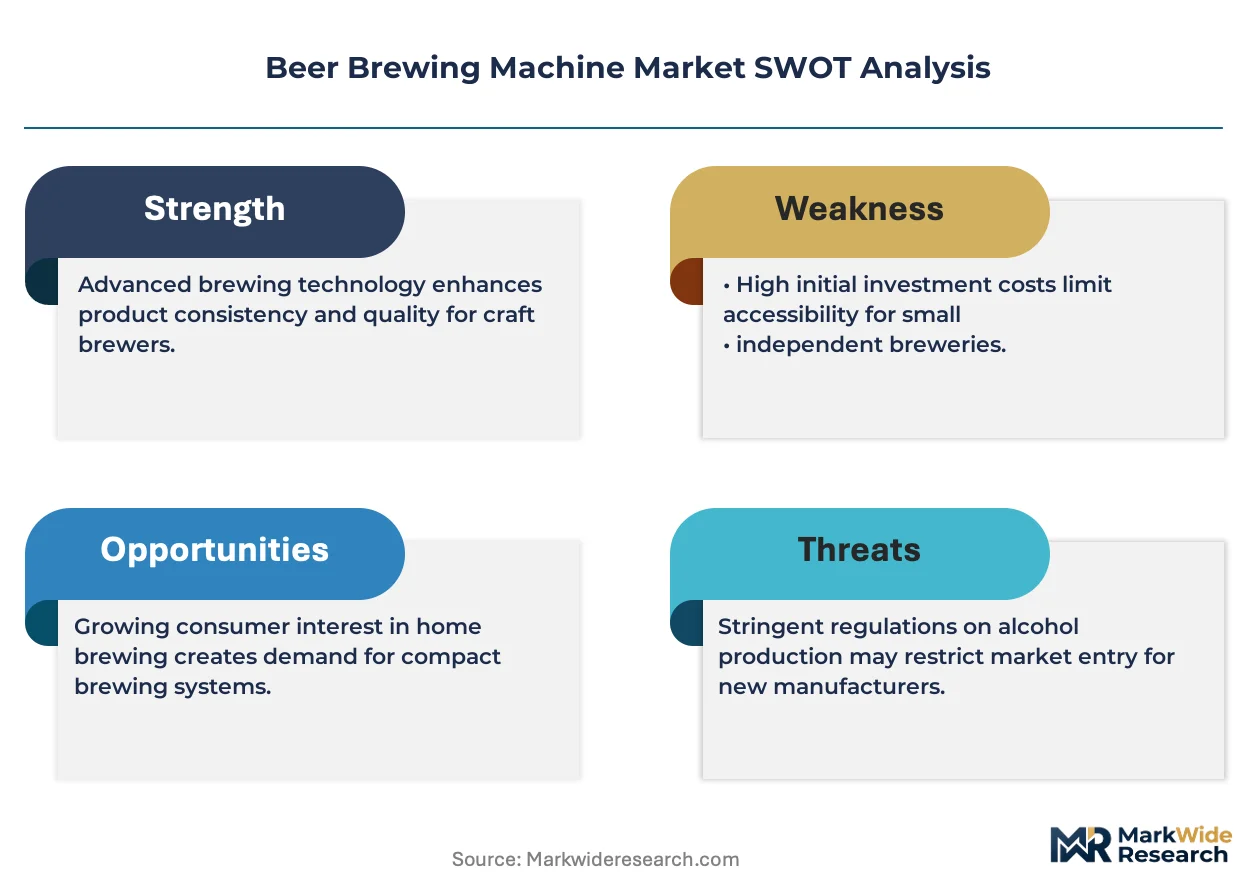
- Nickel price volatility:Stainless steel alloy input costs create margin pressure for fermenter manufacturers without long-term supply agreements.
- German component concentration:Precision heating element supply chains cluster in Baden-Württemberg, creating geographic single-point vulnerability.
- Manual brewing persistence:Traditional open-vessel methods retain preference among heritage-focused craft brewers resistant to automation standardization.
Strategic Opportunities
- India microbrewery licensing liberalization:State-level excise reforms in Karnataka and Maharashtra are opening first-mover equipment deployment corridors.
- IoT-enabled predictive maintenance:Sensor-embedded brewing systems create recurring revenue streams through remote diagnostics subscriptions.
- US Inflation Reduction Act efficiency credits:Electric heating element upgrades qualify for energy-transition incentives, accelerating electric kettle adoption.
Industry Challenges
- Certified brewing technician scarcity:Automated system operation requires cross-functional skills spanning thermodynamics and PLC programming that vocational programs have not scaled.
- Legacy equipment integration:Retrofitting digital control architecture onto existing kettle infrastructure demands custom engineering that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Brewing Machine Market |
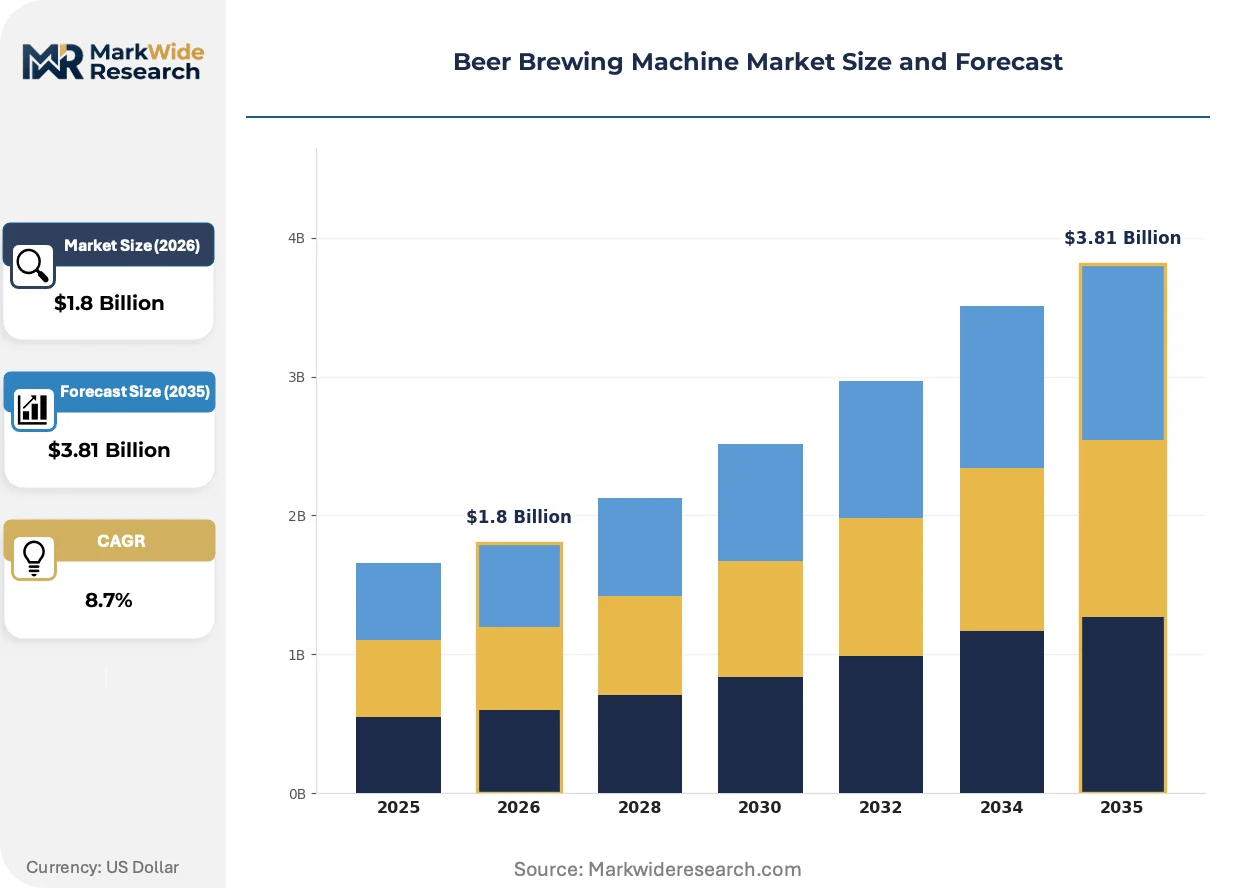
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Brew Kettles, All-in-One Brew Systems, Fermenters, Kegging Machines Capacity: 1 Gallon, 5 Gallon, 10 Gallon, 20 Gallon End User: Home Brewers, Microbreweries, Craft Breweries, Commercial Breweries Technology: Digital Control Systems, Analog Systems, Automated Brewing, Manual Brewing |
| Companies Covered | BEERMKR, MiniBrew B.V., PicoBrew, Spike Brewing, WilliamsWarn, Blichmann Engineering, Speidel Tank- und Behälterbau GmbH, BrewArt, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Brewing Machine Market Strategic Shifts
Digital control architectures are penetrating brewing equipment at accelerating rates, compressing the traditional gap between industrial automation and craft-scale operations. This convergence is generating new competitive axes around data ownership and recipe repeatability.
Touchscreen recipe management systems are displacing manual temperature logging and timer-based process control. Microbreweries in the United States and Germany are adopting these interfaces at twice the rate of home brewer segments. The technology is displacing paper-based batch records and reducing human error rates in mash cycle execution.
REACH substance restrictions on nickel alloy compositions are forcing stainless steel specification revisions across European supply chains. Manufacturers serving Germany and France are reformulating vessel metallurgy to maintain CE conformity. Fermenter fabricators with pre-certified material libraries are capturing specification-driven procurement from risk-averse buyers.
Direct-to-brewery equipment financing is eroding traditional distributor-credit relationships in North American markets. Regional banks and specialty lenders are underwriting brewing system leases that bypass legacy channel intermediaries. This pattern is most visible in Texas and Colorado, where microbrewery formation rates outpace conventional equipment vendor coverage.
Beer Brewing Machine Market Segmentation
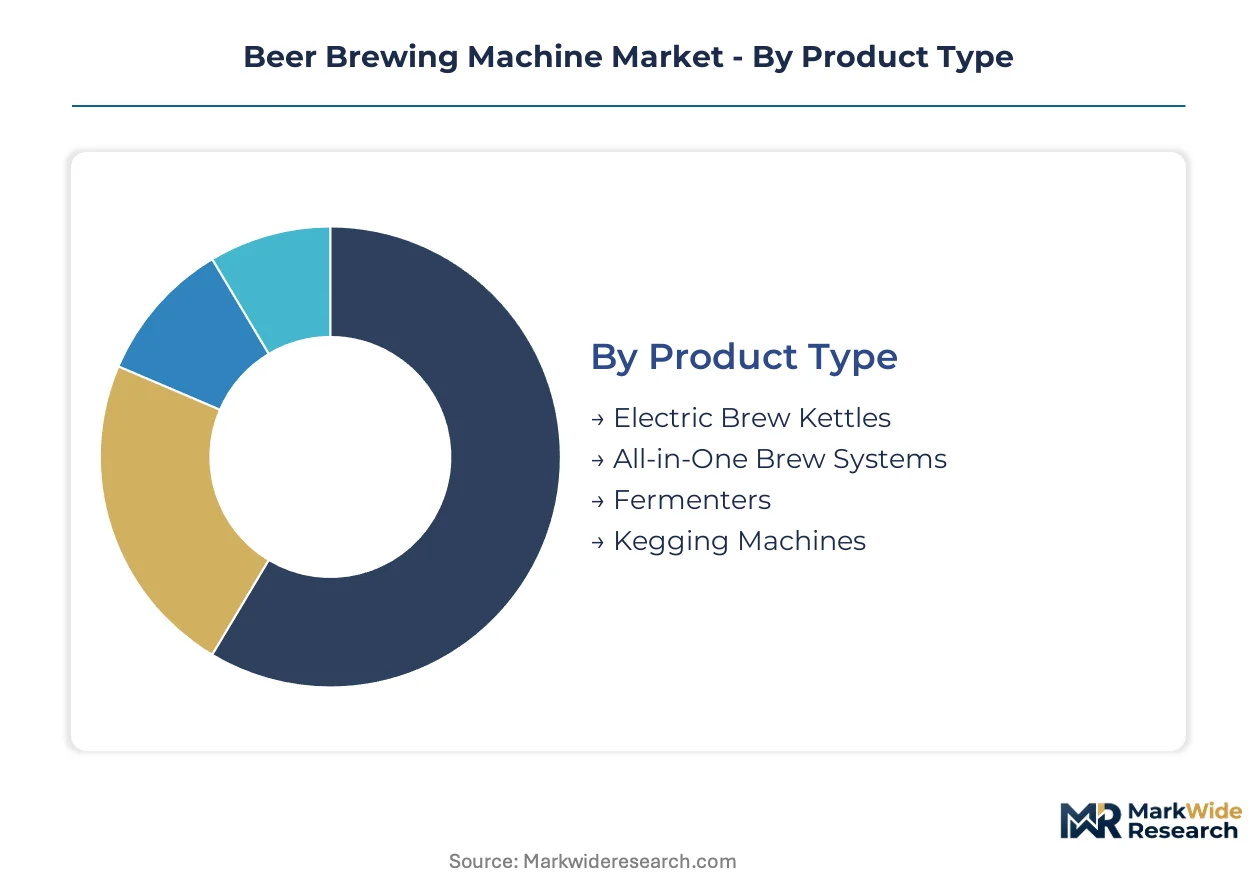
Equipment configuration choices in beer brewing machines cascade through distribution economics, after-service requirements, and buyer financing terms. Channel partners stock different segment mixes based on regional craft beer maturity and local technical support density.
Product Type:
Channel mix varies sharply by product complexity—specialty retailers dominate electric kettle sales while integrated system vendors capture all-in-one deployments through direct-to-brewery relationships.
- Electric Brew Kettles:Entry-level heating vessels with immersion elements rated between 1500W and 5500W, constructed from food-grade 304 stainless steel. Demand concentrates among United States home brewers in Texas and Colorado, where state-level energy efficiency credits reduce total cost-of-ownership for electric configurations. Distribution runs through homebrew specialty retailers and Amazon marketplace vendors with minimal technical support bundling.
- All-in-One Brew Systems:Integrated vessels combining mash tun, boil kettle, and recirculation pump in single-footprint units with digital temperature control. Microbreweries in Germany's Baden-Württemberg region are upgrading from component assemblies toward these systems to satisfy CE marking requirements under the EU Machinery Directive. Direct sales channels and equipment financing partnerships are displacing traditional distributor relationships for this segment.
- Fermenters:Pressure-rated vessels for primary and secondary fermentation with temperature control jackets. German-engineered units from Speidel Tank- und Behälterbau GmbH anchor commercial procurement through certified material libraries meeting BfR food-contact guidance.
- Kegging Machines:Counter-pressure filling and cleaning equipment for packaged beer distribution. Craft breweries in Karnataka and Maharashtra are deploying these as microbrewery licensing liberalization enables on-premise retail operations.
Electric Brew Kettles dominate installed base. All-in-One Brew Systems are where expansion concentrates.
Capacity:
Cost tier alignment separates hobbyist purchases from commercial infrastructure decisions, with financing availability stepping sharply at the 10-gallon threshold.
- 1 Gallon:Compact countertop units for experimental recipe development and ingredient testing. Home brewers in urban apartments favor these for space-constrained installations.
- 5 Gallon:Standard home brewing batch size producing approximately 50 bottles per cycle. United States hobbyist segment represents the core demand pool through specialty retail channels.
- 10 Gallon:Stepping-stone capacity enabling pilot-scale production without industrial facility requirements. Scaling hobbyists in Texas and Colorado are purchasing these systems as microbrewery formation accelerates ahead of permanent infrastructure commitments. Equipment lessors are underwriting 10-gallon system leases that bypass legacy distributor credit relationships.
- 20 Gallon:Entry commercial capacity for taproom-only microbreweries with limited distribution ambitions. German microbreweries favor this configuration for automated brewing technology trials before scaling to industrial volumes.
5 Gallon systems anchor hobbyist channel volume. 10 Gallon configurations are climbing the fastest as graduation patterns intensify.
End User:
Application maturity determines specification stringency—commercial breweries demand certified technician availability while home brewers prioritize plug-and-play simplicity.
- Home Brewers:Non-commercial enthusiasts producing batches for personal consumption. United States segment drives electric kettle volume through online marketplaces and specialty retailers with minimal service attachment.
- Microbreweries:Small-scale commercial operations with taproom-focused distribution models. German microbreweries are reorganizing procurement toward integrated systems with digital control architectures to reduce batch-to-batch variability and labor intensity.
- Craft Breweries:Regional producers with multi-state distribution and brand recognition. These buyers specify fermenters with pre-certified material libraries to manage REACH substance restriction compliance risk across European export markets.
- Commercial Breweries:Industrial-scale producers with automated process control and dedicated maintenance staff. Procurement concentrates through long-term supply agreements with heating element manufacturers in Baden-Württemberg.
Home Brewers represent the broadest installed base. Microbreweries are gaining share fastest as craft beer culture deepens in emerging markets.
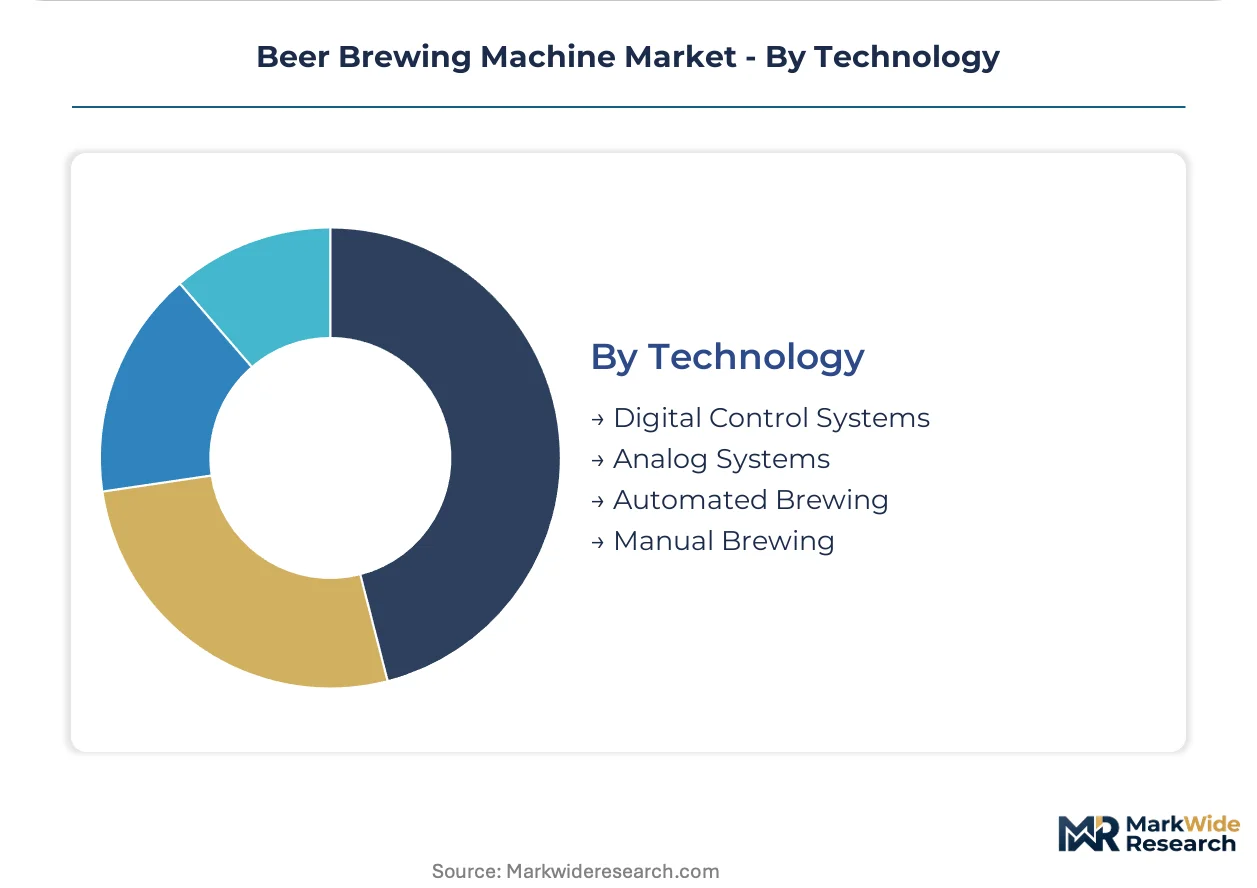
Technology:
Customer type stratification separates price-sensitive analog purchasers from margin-focused automation adopters seeking recipe repeatability and labor reduction.
- Digital Control Systems:Touchscreen interfaces with programmable mash profiles and automated temperature ramping. Microbreweries in the United States and Germany are adopting these at twice the rate of home brewer segments, displacing paper-based batch records and reducing human error in mash cycle execution between 148°F and 162°F setpoints.
- Analog Systems:Dial-based temperature control with manual timer dependency. Heritage-focused craft brewers resistant to standardization retain preference for these configurations despite higher labor requirements.
- Automated Brewing:Software-controlled systems with sensor feedback loops and remote monitoring capability. These systems capture disproportionate margin pools through subscription-enabled predictive maintenance revenue streams.
- Manual Brewing:Open-vessel methods with direct fire or steam heating and hand-managed process steps. Traditional German brewers maintain these techniques for heritage positioning despite efficiency disadvantages.
Analog Systems retain legacy installed base dominance. Automated Brewing is where technology investment concentrates as labor scarcity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in precision brewing equipment exports, connecting Baden-Württemberg manufacturing clusters to Atlantic and Pacific markets.
United States
Texas and Colorado microbrewery formations are accelerating 10-gallon system procurement as hobbyists graduate to commercial pilot operations. The US Inflation Reduction Act's energy efficiency credits reduce total cost-of-ownership for electric heating element configurations. Equipment lessors in Austin and Denver are underwriting direct-to-brewery leases that bypass legacy distributor credit relationships.
Germany
Baden-Württemberg's precision heating element supply chains anchor automated brewing technology manufacturing for European export markets. The EU Machinery Directive's CE marking requirements are accelerating replacement cycles among microbreweries seeking cross-border certification. Stuttgart-area fabricators are expanding fermenter production to meet BfR food-contact surface guidance compliance demand.
India
State-level excise reforms in Karnataka and Maharashtra are opening first-mover equipment deployment corridors for microbrewery licensing liberalization. The central bank's priority sector lending guidelines are expanding credit access for food and beverage processing infrastructure. Bangalore and Mumbai microbreweries are importing kegging machines to support on-premise retail operations.
Australia
New South Wales and Victoria home brewing communities are driving compact all-in-one system demand for space-constrained urban installations. The country's national food safety regulator enforces material-contact standards for brewing vessels that align with EU REACH substance restrictions. Sydney specialty retailers are expanding touchscreen-equipped digital control system inventories.
China
Pearl River Delta manufacturing clusters are scaling stainless steel fermenter production for Southeast Asian craft brewery export markets. The Ministry of Industry and Information Technology's equipment quality standards are reshaping supplier certification requirements for automated brewing systems. Shenzhen fabricators are integrating IoT sensor architectures into mid-capacity brewing equipment for regional microbrewery customers.
Beer Brewing Machine Market Competitive Environment
Concentration sits with integrated system specialists and precision component fabricators rather than diversified industrial conglomerates. The vendor base spans three tiers: German-engineered reliability anchors, North American digital-native disruptors, and Asian contract manufacturers serving price-sensitive segments. Strategic moves center on direct-to-brewery financing partnerships and material library pre-certification to manage REACH compliance risk.
Among German-engineered specialists, Speidel Tank- und Behälterbau GmbH anchors the precision fermenter archetype through certified material libraries. PicoBrew exemplifies the digital-native disruptor tier with software-enabled control architectures. WilliamsWarn occupies a position within the compact-footprint specialist segment targeting urban microbrewery installations.
| Leading Market Players |
|---|
| BEERMKR |
| MiniBrew B.V. |
| PicoBrew |
| Spike Brewing |
| WilliamsWarn |
| Blichmann Engineering |
| Speidel Tank- und Behälterbau GmbH |
| BrewArt |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
Fourteen-week lead times for precision heating elements sourced from Baden-Württemberg concentrate procurement leverage among German fabricators, compressing margin flexibility for North American assemblers while elevating pricing power for CE-certified system integrators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates German-engineered fermenters with BfR-certified material libraries from Asian contract-manufactured kettles and entry-level electric configurations. Price differentiation rests on CE marking compliance status and after-sales service bundling intensity. Cost compression in economy-tier electric kettles is intensifying because nickel alloy input volatility transmits directly to stainless steel vessel fabricators. Home brewers in Texas and Colorado exhibit highest price sensitivity, while German microbreweries prioritize specification certainty over unit cost.
Supply Chain Analysis
The Port of Hamburg's container throughput underwrites Atlantic-Pacific distribution for precision brewing equipment manufactured in Baden-Württemberg, creating a logistics chokepoint for North American microbrewery procurement cycles. Manufacturing concentrates in Germany, China, and the United States, with raw material dependencies spanning nickel alloys, food-grade 304 stainless steel, and silicon-controlled rectifier heating elements. Single-source vulnerability persists around Baden-Württemberg precision heating element clusters. Distribution runs through direct-to-brewery financing partnerships displacing legacy distributor-credit relationships in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with microbrewery formation acceleration in emerging markets, as state-level licensing liberalization in India and energy-transition incentives in the United States create addressable niches outside incumbent strongholds.
For Market Incumbents: Compound material library pre-certification advantages to capture specification-driven procurement from risk-averse craft breweries facing REACH substance restriction compliance deadlines. Expand fermenter production capacity in Stuttgart-area fabricators to meet BfR food-contact surface guidance demand. Defend against Asian contract manufacturer price pressure through certified technician training program scaling that locks in aftermarket service attachment.
For New Entrants and Emerging Players: Anchor in Karnataka and Maharashtra microbrewery licensing corridors where state-level excise reforms have outpaced established vendor coverage. Target 10-gallon capacity system deployment for scaling hobbyists seeking pilot-scale infrastructure before industrial commitments. Pursue equipment financing partnerships with regional banks in Austin and Denver that bypass legacy channel intermediaries.
For Investors and Strategic Acquirers: Long-term, this sits as a automation-subscription play because IoT-enabled predictive maintenance revenue streams recalibrate equipment economics toward recurring software margins. Acquisition target archetype: digital-native brewing system developers with sensor-embedded architectures and remote diagnostics capabilities. Watch for certified brewing technician scarcity inflection as vocational program scaling failures constrain automated system deployment timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Library Pre-Certification | BfR-compliant stainless steel specifications capture procurement from REACH-restricted European buyers. |
| Direct-to-Brewery Financing Partnerships | Regional bank leases in Texas and Colorado displace legacy distributor-credit relationships. |
| IoT Sensor Architecture Integration | Shenzhen fabricators embed predictive maintenance capabilities for Southeast Asian microbrewery customers. |
| Certified Technician Training Scaling | Cross-functional PLC programming and thermodynamics instruction addresses automated system operation scarcity. |
| CE Marking Compliance Acceleration | EU Machinery Directive conformity captures replacement cycles among export-ready European microbreweries. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, EU Machinery Directive filings, and SEC equipment manufacturer disclosures through structured interviews with microbrewery procurement managers, plant engineers at fermenter fabricators, homebrew specialty retailers, and aftermarket service technicians. Bottom-up unit shipment estimates triangulate against top-down addressable spend calculations across capacity tiers and technology configurations.
Segmentation dimensions modeled span product type, capacity configuration, end-user archetype, and control technology sophistication across the projection horizon. CAGRs derive from installed base growth rates adjusted for replacement cycle compression and technology upgrade intensity. Forecast inputs incorporate nickel price volatility transmission effects and state-level microbrewery licensing policy trajectories.
Material uncertainties — nickel alloy cost spikes, REACH substance restriction enforcement timing, and certified technician training program scaling — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as energy-efficiency credit eligibility criteria and India excise reform implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
Japan Alcohol E-Commerce Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Canada Wine Coolers Market