
 Apple Wine Market | 2026-2036
Apple Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Wine Market Outlook
Market Context
Capital-intensity divergence between estate-owned orchards and contract-fruit sourcing is bifurcating competitive returns across the Apple Wine Market. Jackson Family Wines leverages its vineyard real estate holdings to anchor integrated production from tree to bottle. E&J Gallo Winery competes through massive grape and fruit procurement networks that sustain volume scale across multiple price tiers. Ste. Michelle Wine Estates differentiates via Pacific Northwest orchard partnerships that control aromatic varietal supply for premium still expressions.
Product Definition and Segment Structure
Apple wine denotes a fermented alcoholic beverage produced from apple must, typically achieving alcohol content between 4.5% and 12% ABV through controlled yeast fermentation without grain distillation. The product serves both as a standalone table beverage and as a cocktail base in on-trade environments seeking lower-ABV alternatives to grape wine. Sparkling apple wine commands the strongest margin pool as consumers trade into celebratory formats, while organic certification across product lines is capturing shelf space in specialty stores and direct-to-consumer channels. Still variants dominate volume through supermarket and bag-in-box distribution, though canned formats are gaining velocity in bar and restaurant placements targeting single-serve consumption occasions.
Regulatory Environment and Outlook
EU regulations including EFSA labeling standards and REACH-compliant packaging mandates govern ingredient disclosure and material contact safety for apple wine sold across member states. The FDA oversees import tolerances and allergen declarations for European apple wine entering US commerce, while TTB labeling rules dictate alcohol content statement formatting and appellation terminology. Stakeholders must monitor evolving organic certification harmonization between USDA and EU equivalency agreements to preserve cross-border premium positioning.
Market Dynamics
Organic certification mandates under EU regulations are bifurcating the Apple Wine Market, forcing producers to restructure orchard input sourcing and segregate supply chains for certified versus conventional product lines.
Growth Catalysts
- EU Organic Regulation (EU) 2018/848:Mandatory certification harmonization across member states creates shelf-space premiums in German and French specialty retail channels.
- On-trade cocktail programs:Low-ABV mixology trends in Paris and Frankfurt venues are expanding apple wine placements as vermouth alternatives.
- Sparkling format innovation:Traditional method secondary fermentation is capturing celebratory occasion demand previously served by entry-level Champagne.
Market Restraints
- Apple concentrate price volatility:Weather-driven harvest fluctuations in Polish and Chinese supply basins compress margin predictability for contract-fruit sourcing models.
- TTB labeling friction:US import tolerance documentation requirements create 90-120 day clearance timelines that disadvantage small-batch European exporters.
- Hard cider substitution:Mass-market cider brands with lower price points and broader distribution capture casual consumption occasions in UK and US markets.
Strategic Opportunities
- Direct-to-consumer channels:Winery subscription models in Hesse and Rhineland-Palatinate bypass wholesale margin extraction and capture customer data.
- Bag-in-box format expansion:Three-liter packaging formats target German household daily consumption occasions with per-liter cost advantages over glass bottles.
- EU Green Deal agricultural incentives:Carbon farming payments for orchard biodiversity practices offset transition costs for organic certification.
Industry Challenges
- Master cider-maker talent scarcity:Traditional Apfelwein craftsmanship apprenticeship pipelines in Frankfurt and Wiesbaden face demographic contraction.
- Multi-standard compliance costs:Simultaneous USDA-NOP and EU organic audits impose duplicate documentation burdens on export-oriented estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Wine Market |
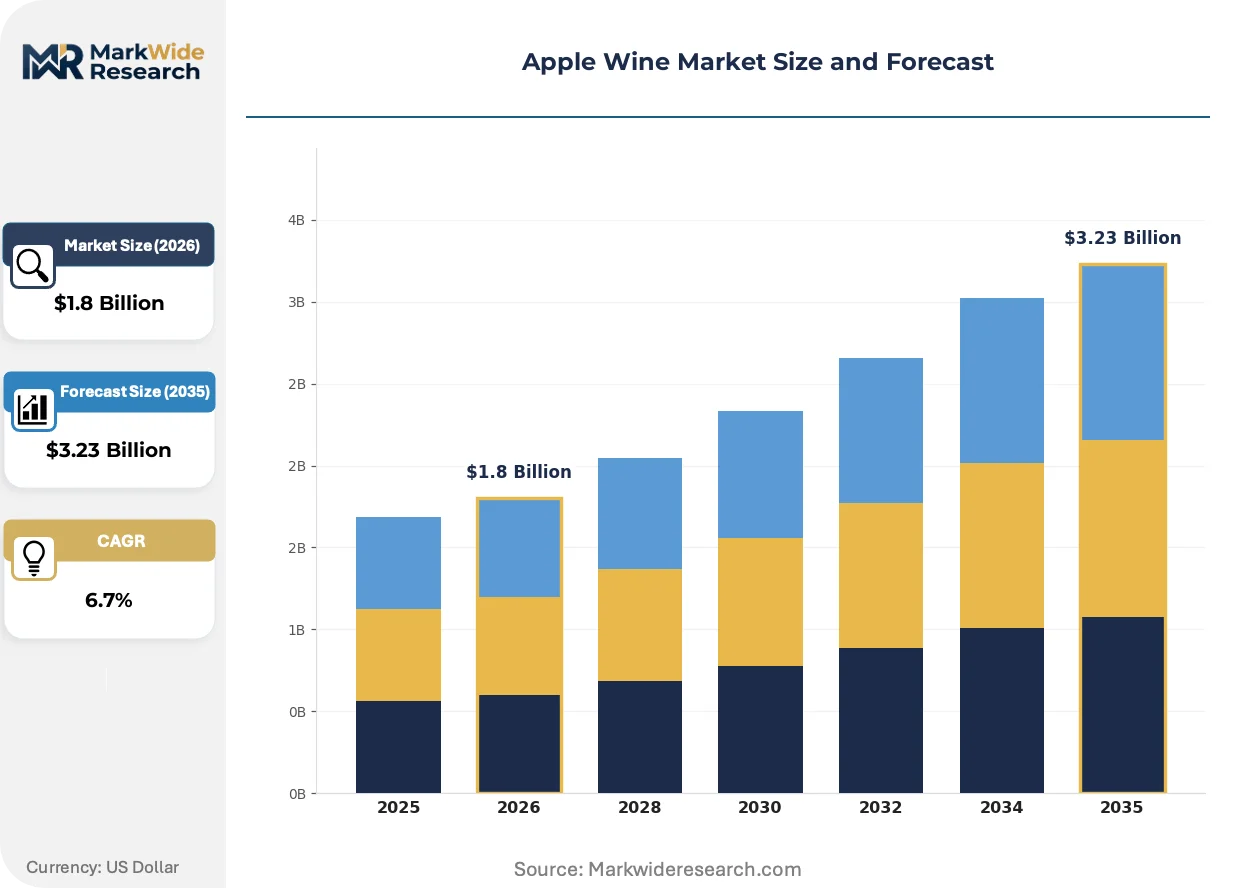
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sparkling, Still, Organic, Flavored Distribution Channel: Online, Supermarket, Specialty Store, Direct Sales Packaging Type: Bottle, Can, Bag-in-Box, Tetra Pak End User: Households, Restaurants, Bars, Retailers |
| Companies Covered | Delicato Family Wines, Jackson Family Wines, E&J Gallo Winery, Ste. Michelle Wine Estates, Treasury Wine Estates, The Wine Group, Deutsch Family Wine & Spirits, Bronco Wine Company, Trinchero Family Wine & Spirits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Wine Market Strategic Shifts
Controlled-atmosphere fermentation technology and packaging format diversification are compressing traditional production timelines while expanding consumption occasion coverage across on-trade and off-trade channels.
Pneumatic pressing with inert gas blanketing is displacing oxidative traditional rack-and-cloth methods in premium Hesse estates. Ste. Michelle Wine Estates and Jackson Family Wines affiliates have adopted closed-system pressing for aromatic preservation. This displacement is compressing vintage-to-release timelines from 18 months to 8 months for still expressions.
REACH-compliant packaging mandates under ECHA guidance are forcing substitution of conventional epoxy-based can linings for apple wine sold in EU commerce. Coated aluminum producers must certify bisphenol-A-free contact surfaces. German canning facilities in Bavaria and Baden-Württemberg are retrofitting lines to accommodate migration-tested alternatives.
Single-serve 250ml canned formats are capturing bar and restaurant placements previously dominated by draft cider systems. Parisian cocktail venues and Frankfurt Apfelwein taverns are adopting slim cans for by-the-glass pricing flexibility. This rotation is most visible in urban on-trade clusters where space constraints favor minimal footprint inventory.
Apple Wine Market Segmentation
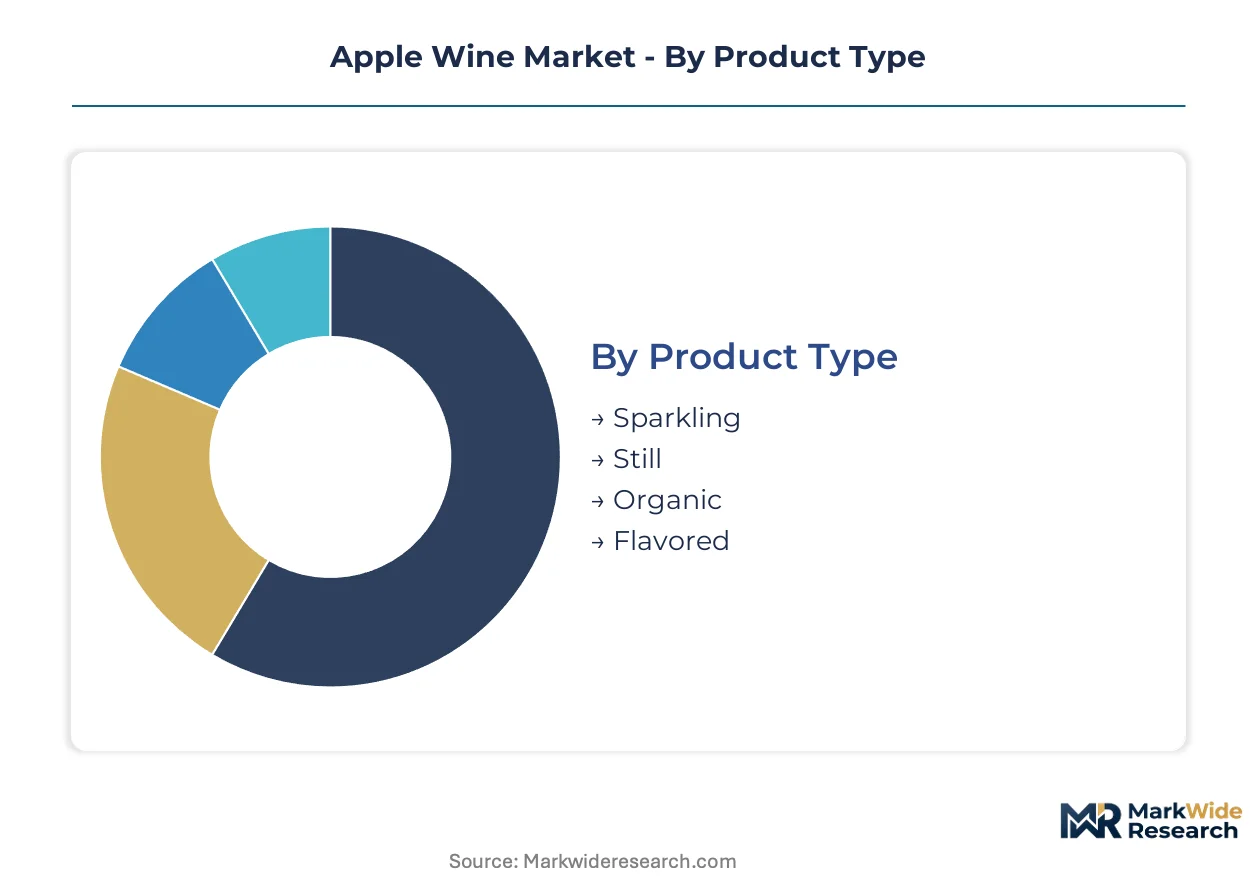
Apple wine segmentation reveals distinct demand profiles across consumption occasions and supply chain configurations. Format and channel choices directly determine margin capture and brand positioning in this traditionally regional beverage category.
Product Type:
Sparkling and still variants anchor domestic German consumption, while organic and flavored expressions increasingly serve export markets seeking differentiation.
- Sparkling:Traditional method secondary fermentation produces 4.5-7% ABV expressions with persistent mousse. Demand concentrates in Frankfurt and Wiesbaden Apfelwein taverns where celebratory occasions command per-bottle premiums over still alternatives. EFSA labeling requirements for residual sugar disclosure shape competitive positioning in EU specialty retail.
- Still:Un-carbonated fermented apple must typically achieves 7-12% ABV through ambient yeast fermentation. Daily consumption occasions in Hesse and Rhineland-Palatinate households sustain volume through bag-in-box and draft formats. Traditional rack-and-cloth pressing methods persist in estate production despite pneumatic displacement in premium tiers.
- Organic:Certified production under EU 2018/848 mandates segregated orchard management and input documentation. Export demand from US and Nordic markets absorbs premium pricing for certified expressions.
- Flavored:Botanical or fruit-infused variants targeting cocktail program specifications in Paris and Berlin on-trade venues.
Still holds the largest share; momentum sits with sparkling as celebratory occasion substitution accelerates.
Distribution Channel:
Channel selection determines margin extraction rates and customer data access, with direct and online formats capturing value previously absorbed by wholesale intermediaries.
- Online:Direct-to-consumer platforms and third-party marketplaces enable subscription models that bypass German wholesale margins. Data capture on consumption timing supports vintage release optimization for Hesse estates.
- Supermarket:Mass retail placement in REWE and Edeka chains concentrates volume for still and bag-in-box formats. Listing fees and promotional calendars compress net margins for producers without scale.
- Specialty Store:Curated selection in Berlin and Munich independent retailers supports premium positioning for organic and single-orchard expressions. Staff education investments drive conversion rates above mass channels.
- Direct Sales:Cellar door and tavern-attached retail in Frankfurt-Rhöndorf corridor captures tourist expenditure and local loyalty. Highest margin realization occurs here through tasting-room upselling.
Supermarket channels dominate volume throughput; direct sales are climbing the fastest as estates prioritize margin defense.
Packaging Type:
Format innovation is compressing traditional glass dominance as on-trade space constraints and sustainability mandates reshape material selection.
- Bottle:Standard 750ml and 1-liter glass remains default for restaurant wine lists and gift occasions. REACH-compliant label adhesives and closure materials face ECHA scrutiny for migration limits.
- Can:Aluminum 250ml and 330ml slim formats capture single-serve cocktail program placements in Paris bars and Frankfurt taverns. Bisphenol-A-free lining certification adds compliance cost but enables EU market access.
- Bag-in-Box:Three-liter formats dominate German household daily consumption with per-liter cost advantages and extended post-opening stability. Bavarian filling facilities are retrofitting for organic-certified production lines.
- Tetra Pak:Aseptic cartons serve price-sensitive export markets and institutional catering with lower logistics weight than glass alternatives.
Bottle retains category leadership; can formats are gaining share fastest in urban on-trade rotation.
End User:
User type dictates product specification, with household daily consumption requiring different ABV and packaging than professional beverage program integration.
- Households:Repeat purchase behavior in Rhineland-Palatinate and Hesse sustains bag-in-box and multi-bottle supermarket transactions. Seasonal harvest festival timing concentrates Q3-Q4 volume spikes.
- Restaurants:Fine dining and casual establishments in Frankfurt and Berlin specify lower-ABV expressions for food pairing and extended lunch service. Wine list placement requires TTB-compliant labeling for US-imported selections.
- Bars:Cocktail-forward venues in Paris and Munich adopt canned formats for by-the-glass pricing flexibility and minimal inventory footprint. Mixology program integration drives flavored variant trial.
- Retailers:Independent merchants and chain buyers negotiate exclusive vintage allocations and promotional calendar slots. Category management decisions determine shelf space allocation against hard cider and entry-level grape wine.
Households absorb the greatest volume; bars show the steepest expansion trajectory as low-ABV mixology trends mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German households consume apple wine as a daily table beverage, while US and French markets treat it as a specialty cocktail ingredient, creating divergent product specification demands across geographies.
Germany
Hesse and Rhineland-Palatinate sustain traditional Apfelwein tavern culture with draft consumption driving bag-in-box and keg format demand. EU 2018/848 organic certification mandates reshape orchard input sourcing across Frankfurt-Rhöndorf corridor estates. The Wiesbaden-Frankfurt urban cluster concentrates premium on-trade placements where celebratory sparkling variants command per-bottle premiums.
France
Paris cocktail venues integrate lower-ABV apple wine as vermouth alternatives in mixology programs, diverging from German daily consumption patterns. ANSM labeling requirements govern ingredient disclosure for specialty retail distribution. Île-de-France and Provence-Alpes-Côte d'Azur urban clusters drive flavored variant trial through bar and restaurant channel expansion.
United States
Pacific Northwest orchard partnerships supply aromatic varietals for premium still expressions targeting wine-list placement. FDA import tolerance documentation and TTB labeling rules create clearance timelines that disadvantage small-batch European exporters. California and Washington state distribution networks concentrate volume through supermarket and direct-to-consumer channels.
United Kingdom
Hard cider substitution pressure captures casual consumption occasions, compressing apple wine shelf space in mass retail. FSA allergen declaration requirements apply to imported European product lines. London and Southeast England urban clusters sustain specialty store demand for organic-certified expressions through independent merchant curation.
Poland
Weather-driven apple concentrate supply fluctuations from Polish orchards create margin volatility for contract-fruit sourcing models across EU production basins. National agricultural ministry orchard registration requirements apply to export-grade fruit certification. Masovian and Lesser Poland regions concentrate processing capacity for concentrate and must supply.
Apple Wine Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Apple Wine Market structure. Estate-owned orchard holdings differentiate capital intensity and margin capture from contract-fruit sourcing networks. Three archetypes dominate: integrated vineyard-estate producers, massive procurement-scale wineries, and Pacific Northwest orchard partnership specialists. Competitive moves concentrate on direct-to-consumer channel expansion and pneumatic pressing technology adoption for aromatic preservation.
Among US-based wine estate holding companies, Jackson Family Wines, E&J Gallo Winery, and Ste. Michelle Wine Estates occupy distinct structural positions. Jackson Family Wines exemplifies the integrated estate archetype through vineyard real estate anchoring tree-to-bottle production control. E&J Gallo Winery represents scale-driven procurement network competition sustaining volume across multiple price tiers. Ste. Michelle Wine Estates sits within the regional partnership specialist tier, controlling aromatic varietal supply through Pacific Northwest orchard relationships.
| Leading Market Players |
|---|
| Delicato Family Wines |
| Jackson Family Wines |
| E&J Gallo Winery |
| Ste. Michelle Wine Estates |
| Treasury Wine Estates |
| The Wine Group |
| Deutsch Family Wine & Spirits |
| Bronco Wine Company |
| Trinchero Family Wine & Spirits |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Hesse estates and Rhineland-Palatinate orchard cooperatives lock in both apple must supply access and price visibility across volatile harvest cycles. These contracts insulate premium sparkling producers from Polish concentrate price swings while committing buyers to minimum volume thresholds.
Pricing Analysis
After-sales revenue from direct-to-cellar-door tasting experiences and subscription renewals drives lifetime value for estate producers. Three-tier pricing structure across premium single-orchard, standard estate-bottled, and economy bag-in-box levels segments household and on-trade demand. Cost compression in economy tiers is intensifying because hard cider brands capture casual consumption occasions with lower price points. Mass supermarket buyers exhibit highest price sensitivity, while Frankfurt Apfelwein taverns accept premiums for celebratory sparkling formats.
Supply Chain Analysis
Inventory lead times for pneumatic pressing equipment and inert gas blanketing systems extend 16-24 weeks, constraining rapid capacity expansion among premium Hesse producers. Orchard supply concentrates in Germany, Poland, and China, with Polish concentrate exports feeding contract-fruit sourcing models. Production draws from specific apple varietals, yeast cultures, and filtration media vulnerable to climate-driven harvest volatility. Single-source vulnerability in Polish concentrate supply creates margin unpredictability. Distribution runs through German wholesale networks, direct estate sales, and expanding online subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Apple wine demand cycles with harvest quality and celebratory occasion recovery, positioning the market for expansion as on-trade cocktail programs normalize and organic certification premiums stabilize.
For Market Incumbents: Compound estate-owned orchard holdings through Rhineland-Palatinate land acquisition to secure backward integration into high-aromatic varietal supply. Deepen pneumatic pressing technology deployment to compress vintage-to-release timelines and defend margin position against hard cider substitution in bag-in-box tiers.
For New Entrants and Emerging Players: Differentiate on EU 2018/848 organic certification compliance to capture US and Nordic export premiums that incumbent estates serve inadequately. Target Paris cocktail venue placements with 250ml canned formats as the most penetrable white-space channel, leveraging slim-can inventory efficiency for by-the-glass pricing flexibility.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated estate producers with existing direct-to-consumer infrastructure and certified organic production lines. Long-term viability over a multi-year horizon favors operators controlling tree-to-bottle supply chains rather than contract-fruit dependent models. Watch EU Green Deal agricultural incentive disbursement rates as the inflection signal for organic transition cost offsets.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Bypasses German wholesale margin extraction while capturing customer data for vintage release optimization. |
| Pneumatic Pressing Technology Adoption | Compresses oxidative rack-and-cloth timelines from 18 months to 8 months for aromatic preservation. |
| EU Organic Certification Investment | Unlocks EFSA-compliant shelf space in specialty retail and USDA-equivalent US export positioning. |
| 250ml Slim-Can Format Launch | Captures Paris and Frankfurt on-trade placements with minimal inventory footprint for cocktail programs. |
| Pacific Northwest Orchard Partnership | Secures aromatic varietal supply for premium still expressions targeting US wine-list placement. |
Study Parameters
Operator-level perspectives from Hesse estate owners, Rhineland-Palatinate orchard cooperative managers, Frankfurt Apfelwein tavern operators, Paris cocktail bar beverage directors, and German supermarket category buyers anchored the qualitative base. Primary interview findings triangulated against secondary sources including EU agricultural ministry orchard registration databases, EFSA labeling guidance documents, TTB import tolerance filings, and German Federal Statistical Office beverage production records. Bottom-up volume modeling from estate-level production data converged with top-down market sizing from trade flow analysis.
Sensitivity analysis tested forecast robustness across Polish apple concentrate price volatility scenarios and EU organic certification adoption rate variations. Segmentation modeling incorporated product type, distribution channel, packaging format, and end-user dimensions across the projection horizon. CAGRs derived from vintage-to-vintage production trend extrapolation, adjusted for format mix shifts and channel migration patterns. Forecast inputs included pneumatic pressing adoption curves, REACH-compliant packaging retrofit timelines, and direct-to-consumer subscription growth trajectories.
The analysis sits within stated boundaries; outcomes outside sustained on-trade recovery conditions or EU-US organic equivalency agreement stability would require recalibration. Forecasts reflect documented assumptions regarding harvest yield normalization and regulatory harmonization progress. Revision becomes warranted when hard cider substitution rates or climate-driven Polish supply disruption cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Rhum Agricole Market