
 Europe Cigarette Lighter Market | 2026-2036
Europe Cigarette Lighter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cigarette Lighter Market Intelligence
The capital-intensity divergence between automated precision manufacturers and hand-finish ateliers is bifurcating competitive returns across the Europe cigarette lighter landscape. BIC Corporation leverages high-volume disposable production across French and Spanish facilities to sustain unmatched unit economics at the mass-market tier. S.T. Dupont anchors the super-premium segment through Paris-based metalworking craftsmanship that commands price multiples unreachable by commodity competitors. Swedish Match AB navigates regulatory complexity across Nordic markets with specialized compliance capabilities that smaller rivals struggle to replicate.
A cigarette lighter is a portable ignition device comprising a fuel reservoir, sparking mechanism, and flame control system, typically utilizing butane, piezoelectric crystals, or electric arc plasma to generate controlled combustion for tobacco, candle, or stove ignition. Metal-bodied refillable lighters dominate margin pools due to repair-service ecosystems and collector aftermarket value, while electric arc models represent the fastest-expanding product type as USB-rechargeable designs displace fuel-dependent units in German and Dutch retail channels. Convenience stores and specialty shops still control the majority of volume throughput, though online retail is capturing growing share among younger consumers seeking novelty and customization options.
REACH compliance through ECHA governs chemical composition of fuels and surface coatings, while EN 13869 child-resistance standards enforced by national market surveillance authorities in Germany, France, and Italy directly determine product access and redesign cycles. The EU Green Deal's plastics reduction targets are forcing material transitions away from virgin petroleum-based housings toward recycled polymers and durable metals. Stakeholders must monitor evolving battery transport regulations for electric lighters and anticipate stricter extended producer responsibility schemes that will reshape cost structures and competitive positioning across all distribution channels.
Market Dynamics
The EU Green Deal's plastics reduction mandates are forcing material transitions across European lighter manufacturing, compressing margins for disposable producers while rewarding durable metal and rechargeable electric alternatives with regulatory preference.
Growth Catalysts
- EN 13869 child-resistance standards:Mandatory redesign cycles in Germany, France, and Italy are filtering out low-compliance imports and consolidating shelf access for certified domestic manufacturers.
- USB-rechargeable electric arc technology:Dutch and German outdoor retailers are expanding dedicated display space for fuel-free ignition devices, capturing younger consumer preference.
- Collector aftermarket value:Paris and Milan-based repair-service ecosystems for metal-bodied refillable lighters are sustaining premium pricing power unavailable to disposable competitors.
Market Restraints
- Butane fuel cost volatility:Refillable lighter margins remain exposed to petrochemical feedstock swings, compressing working capital flexibility for mid-tier manufacturers.
- REACH compliance complexity:ECHA chemical composition rules for surface coatings and fuel additives impose multi-year reformulation timelines that delay product launches.
- Single-use plastics directive enforcement:Virgin petroleum-based housing bans are stranding existing injection-molding capacity and forcing premature asset retirement.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania convenience channels retain minimal premium refillable presence, offering first-mover positioning for metal-bodied brands.
- Extended producer responsibility schemes:Anticipated EU-wide take-back mandates will reward pre-positioned circular infrastructure investments by French and German producers.
- Electric-battery transport regulation convergence:Harmonized UN 38.3 lithium-cell shipping standards are displacing fragmented national rules, enabling centralized European distribution for USB-rechargeable models.
Industry Challenges
- Piezoelectric crystal sourcing concentration:Dependence on limited qualified suppliers for ignition components creates vulnerability to supply interruptions.
- Multi-jurisdiction market surveillance:Divergent enforcement intensity between German KBA-style authorities and southern European regulators complicates compliance budgeting.
- Legacy fuel-dependent retail inventory:Convenience store chains with deep butane lighter stock face write-down pressure during accelerated electric transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cigarette Lighter Market |
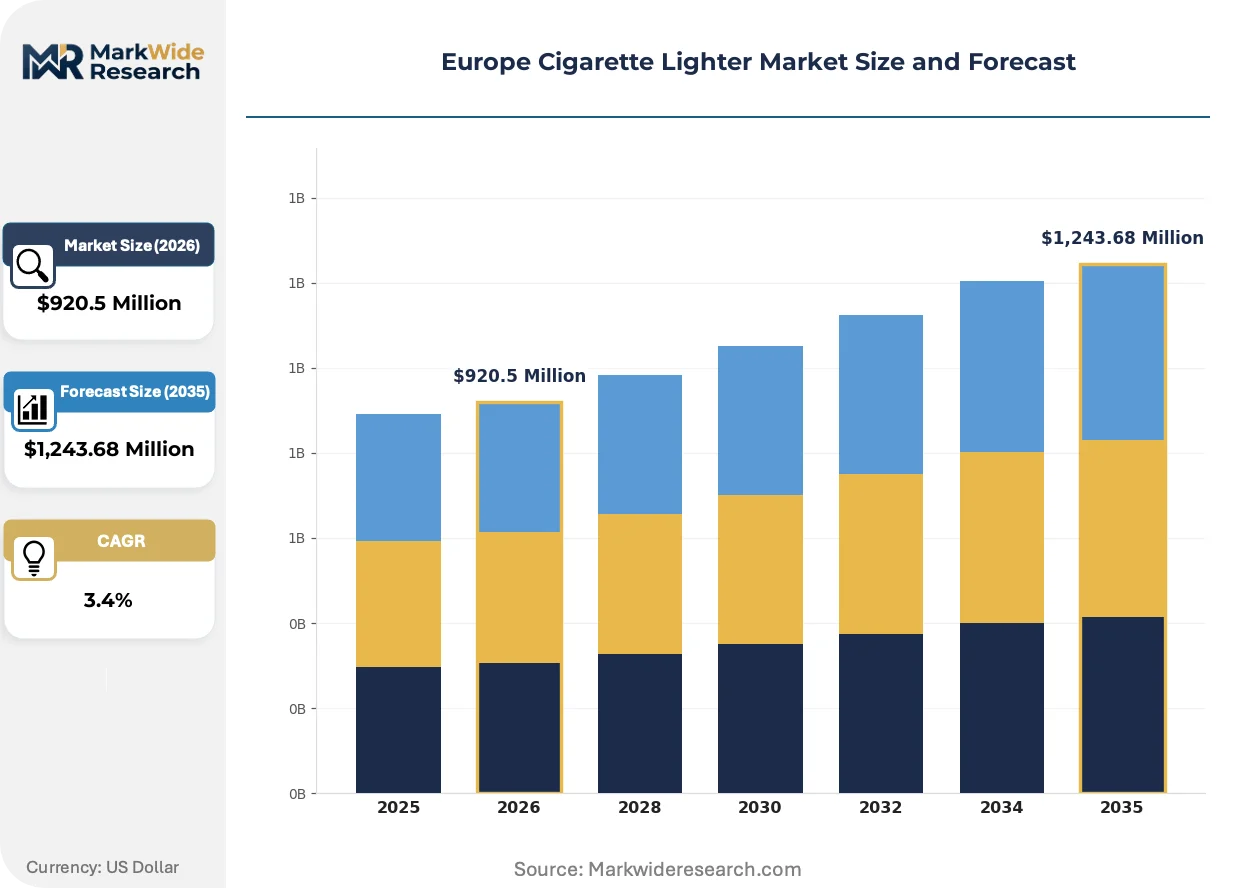
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,243.68 Million |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Lighters, Refillable Lighters, Electric Lighters, Novelty Lighters Material: Plastic, Metal, Glass, Wood Distribution Channel: Online Retail, Convenience Stores, Supermarkets, Specialty Shops Consumer Type: Cigarette Smokers, Campers, Grill Enthusiasts, General Public |
| Companies Covered | Zippo Manufacturing Co., CLIPPER, BIC Corporation, Kiwi Lighters, Visol Products, Swedish Match AB, Colibri, Ningbo Xinhai Electric Co. Ltd., S.T. Dupont, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cigarette Lighter Market Strategic Shifts & Innovations
Product electrification and material circularity are converging to redefine competitive advantage across European lighter manufacturing, with regulatory compliance becoming inseparable from design architecture rather than an afterthought.
USB-rechargeable plasma arc ignition is displacing piezoelectric butane mechanisms in German and Dutch outdoor specialty channels. German consumers aged 25-40 are adopting electric models at pace, viewing fuel-free operation as both convenience upgrade and environmental alignment. This displacement is compressing replacement frequency and shifting margin capture from fuel refill cycles toward initial hardware sale and warranty service.
REACH chemical restrictions through ECHA are tightening permissible substances in surface coatings and fuel additives. Industrial consequence includes mandatory multi-year reformulation programs and third-party certification costs that disproportionately burden smaller manufacturers. Italian metalworking specialists with in-house plating capabilities are responding fastest, integrating compliance into proprietary finishing processes.
Outdoor recreation retailers are unbundling after-sales repair from product sale, treating lighters as durable goods requiring service infrastructure. Specialty shops in France and Germany are replacing pure retail margins with recurring maintenance revenue streams. This behavioral shift is most visible in Alpine regions where extended product lifespan aligns with sustainability positioning and local repair craftsmanship retains cultural value.
Europe Cigarette Lighter Market Segmentation
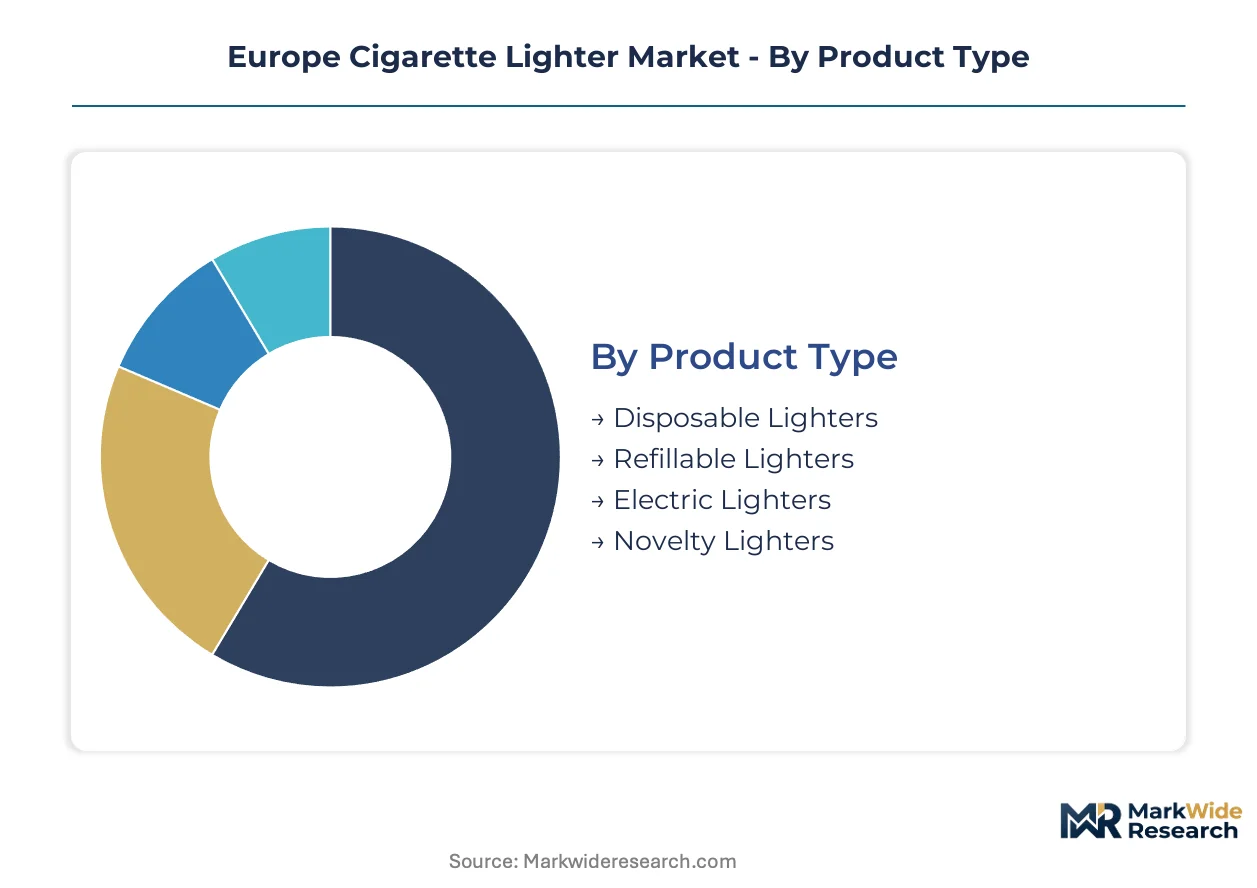
Channel dynamics across Europe dictate which lighter configurations reach end-users. German and French retailers maintain distinct merchandising rules that filter product types by material safety certifications and ignition mechanism compliance.
Product Type:
Convenience stores in Germany and France stock disposable and refillable units as impulse purchases near checkout counters, while specialty outdoor retailers in the Netherlands and Alpine regions dedicate shelf space to electric and novelty designs.
- Disposable Lighters:Single-use butane units with piezoelectric ignition dominate volume throughput at French and Spanish mass-market retail. The EU single-use plastics directive is forcing material transitions toward recycled polymer housings, compressing margins for manufacturers without circular supply partnerships.
- Refillable Lighters:Metal-bodied butane systems with serviceable valve mechanisms command premium positioning through Paris and Milan repair-service ecosystems. German consumers aged 35-55 sustain loyalty to heritage metalworking brands that offer lifetime maintenance programs.
- Electric Lighters:USB-rechargeable plasma arc devices are displacing fuel-dependent units in Dutch outdoor specialty channels.
- Novelty Lighters:Customized designs with aesthetic or functional differentiation capture younger consumer preference through online retail in France and Germany.
By volume, disposable lighters lead. By growth pace, electric lighters are gaining share fastest.
Material:
Cost tier stratification separates premium metal offerings from economy plastic alternatives, with mid-tier glass and wood occupying niche positioning.
- Plastic:Virgin petroleum-based housings face stranded asset risk under EU Green Deal plastics reduction mandates, forcing Italian and German manufacturers toward recycled polymer transitions.
- Metal:Brass, steel, and zinc alloy constructions sustain collector aftermarket value and repair-service revenue streams unavailable to disposable competitors.
- Glass:Specialized transparent fuel reservoirs appear in high-visibility refillable designs from French metalworking ateliers.
- Wood:Sustainable timber casings serve eco-positioned novelty segments in German and Austrian alpine retail.
Metal commands the highest unit margins. Plastic retains the steepest volume concentration.
Distribution Channel:
Customer type determines channel selection, with habitual tobacco users frequenting convenience infrastructure while recreational purchasers cluster in specialty and digital environments.
- Online Retail:E-commerce platforms capture customization-seeking demographics across Germany and France, with novelty and electric models dominating digital basket composition.
- Convenience Stores:High-frequency tobacco purchase occasions sustain disposable lighter velocity at German railway kiosks and French tabac outlets.
- Supermarkets:Mass-market retail in Italy and Spain bundles lighters with seasonal barbecue merchandise, concentrating grill enthusiast demand.
- Specialty Shops:Alpine region outdoor retailers unbundle repair service from product sale, treating metal refillable lighters as durable goods requiring maintenance infrastructure.
Convenience stores move the most units annually. Online channels show the steepest expansion trajectory.
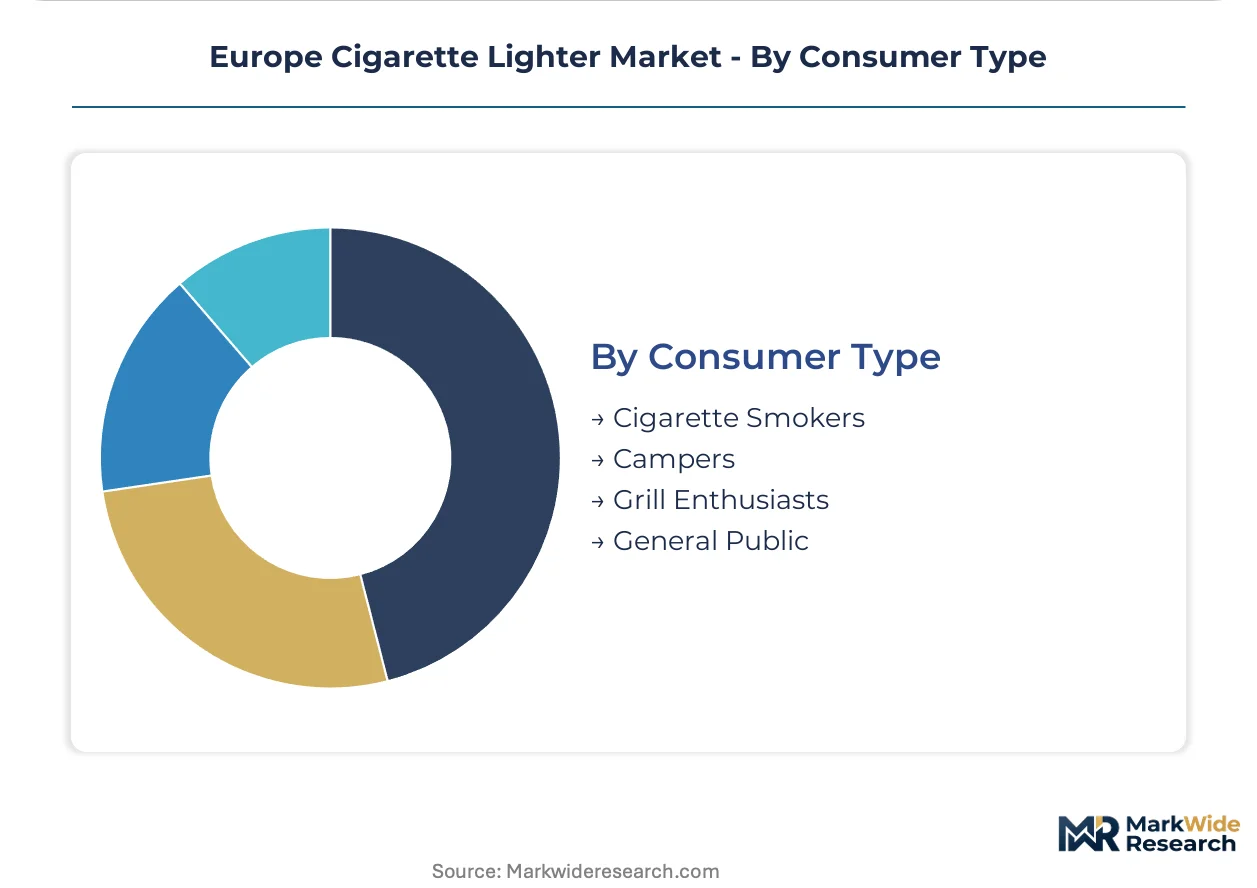
Consumer Type:
Application context shapes product requirements, with combustion reliability priorities varying across indoor tobacco use and exposed outdoor environments.
- Cigarette Smokers:Habitual tobacco users in France and Germany prioritize ignition reliability and pocket portability, sustaining demand for compact disposable and refillable formats.
- Campers:Wind-resistant flame systems and fuel-free electric options dominate Dutch and German outdoor equipment procurement for backcountry ignition reliability.
- Grill Enthusiasts:Extended flame duration and safety lock mechanisms characterize barbecue-specific lighter designs in Italian and Spanish seasonal retail.
- General Public:Occasional household use for candles and stoves drives impulse purchase behavior at supermarket checkout locations.
Cigarette smokers generate the largest addressable base. Campers are expanding most quickly as electric lighter adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows across European lighter manufacturing tilt toward intra-regional trade, with German and French producers supplying premium metal-bodied units to Nordic and Alpine markets while sourcing piezoelectric components from specialized Asian suppliers. The regional trade balance reflects a structural surplus in high-margin refillable segments offset by disposable lighter imports.
Germany
Outdoor equipment procurement from Dutch and German retailers is accelerating electric lighter adoption among campers aged 25-40. EN 13869 child-resistance standards enforced by KBA-style market surveillance authorities are filtering non-compliant imports from shelf access. The Rhine-Ruhr industrial corridor hosts precision metalworking facilities producing brass valve mechanisms for premium refillable brands.
France
Paris-based repair-service ecosystems sustain collector aftermarket value for heritage metalworking brands with lifetime maintenance programs. The EU single-use plastics directive is forcing material transitions toward recycled polymer housings at mass-market production facilities. Auvergne-Rhône-Alpes clusters concentrate specialized surface finishing capabilities responding fastest to REACH chemical restrictions.
Italy
Milan-based metalworking ateliers command premium positioning through proprietary plating processes integrated with ECHA compliance requirements. Italian consumers aged 35-55 generate sustained loyalty toward refillable formats with serviceable valve mechanisms. Emilia-Romagna manufacturing districts supply high-visibility glass reservoir designs to French luxury fabricators.
Netherlands
Dutch outdoor specialty channels are expanding dedicated display space for USB-rechargeable plasma arc devices displacing fuel-dependent alternatives. The country's central European distribution hub position enables efficient lithium-cell shipping under harmonized UN 38.3 standards. Rotterdam logistics clusters facilitate electric lighter import consolidation for redistribution across German and Belgian retail networks.
Spain
Spanish mass-market retail concentrates disposable lighter volume throughput at French-owned production facilities leveraging high-volume automation. Seasonal barbecue merchandise bundling at Italian and Spanish supermarkets concentrates grill enthusiast demand during summer months. Catalan injection-molding capacity faces stranded asset risk from virgin petroleum-based housing bans under EU Green Deal mandates.
Europe Cigarette Lighter Market Key Industry Players
Concentration sits with diversified conglomerates operating across multiple ignition product categories alongside specialized metalworking ateliers serving collector segments. The vendor base stratifies into three functional tiers: mass-market disposable producers sustaining unmatched unit economics, premium refillable specialists capturing repair-service revenue streams, and electric arc innovators displacing fuel-dependent mechanisms. Dominant competitive moves include geographic expansion into underpenetrated Eastern European convenience channels and backward integration into captive battery supply for rechargeable models.
Among heritage metalworking specialists, S.T. Dupont and Zippo Manufacturing Co. exemplify the super-premium archetype through Paris-based and Pennsylvania-origin craftsmanship commanding price multiples unreachable by commodity competitors. BIC Corporation represents the scale-driven mass-market tier with high-volume disposable production sustaining unmatched unit economics. Swedish Match AB occupies a compliance-specialist position navigating regulatory complexity across Nordic markets with capabilities smaller rivals struggle to replicate.
| Leading Market Players |
|---|
| Zippo Manufacturing Co. |
| CLIPPER |
| BIC Corporation |
| Kiwi Lighters |
| Visol Products |
| Swedish Match AB |
| Colibri |
| Ningbo Xinhai Electric Co. Ltd. |
| S.T. Dupont |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between German metalworking ateliers and French luxury fabricators lock in brass valve mechanism supply and stabilize unit cost visibility across premium refillable tiers. These arrangements insulate Paris-based repair-service ecosystems from petrochemical feedstock swings while compressing margin flexibility for spot-market dependent disposable producers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in European lighter procurement. Premium metal-bodied units from Milan ateliers command price multiples based on REACH-compliant plating certification and lifetime maintenance bundling, while mass-market disposable tiers face compression from recycled polymer transition costs under EU Green Deal mandates. Price erosion runs through virgin petroleum-based housing segments as stranded asset risk forces premature capacity retirement. Convenience store chains exhibit highest price sensitivity due to thin retail margins, whereas Alpine specialty retailers demonstrate lowest sensitivity given service-revenue attachment.
Supply Chain Analysis
Piezoelectric crystal sourcing concentration in qualified Asian component suppliers creates single-source vulnerability for ignition mechanism procurement. European manufacturing draws from Chinese ceramic substrate specialists, South Korean precision electronics houses, and domestic German brass foundries for valve mechanisms. REACH compliance through ECHA imposes multi-year reformulation timelines that delay product launches and fragment supplier qualification. Distribution runs through Rotterdam logistics clusters for electric lighter lithium-cell consolidation, with French and German facilities serving as downstream redistribution nodes for premium metal-bodied units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as USB-rechargeable plasma arc technology displaces fuel-dependent mechanisms among Dutch and German outdoor consumers aged 25-40.
For Market Incumbents: Compound repair-service revenue streams through Paris and Milan maintenance ecosystem expansion to offset compressed replacement frequency from electric lighter adoption. Deepen backward integration into captive battery supply chains for rechargeable models to secure component access under harmonized UN 38.3 transport standards. Prioritize EN 13869 certification maintenance as German KBA-style surveillance filters non-compliant imports from shelf access. For New Entrants and Emerging Players: Differentiate on circular infrastructure pre-positioning to capture extended producer responsibility scheme advantages as EU-wide take-back mandates materialize. Target Poland and Romania convenience channels where premium refillable presence remains minimal, leveraging first-mover positioning for metal-bodied brands. Deploy direct-to-specialty-retail go-to-market angles through Alpine outdoor equipment distributors seeking fuel-free ignition alternatives. For Investors and Strategic Acquirers: Heritage metalworking ateliers with integrated ECHA-compliant plating capabilities represent priority acquisition archetypes given compliance-speed advantages. Long-term viability frames around 5-10 year windows where repair-service ecosystems sustain premium pricing power unavailable to disposable competitors. Monitor electric lighter battery transport regulation convergence as inflection signal for centralized European distribution scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Captive lithium-cell sourcing secures UN 38.3 compliance for Dutch and German electric lighter distribution. |
| Repair-Service Ecosystem Expansion | Paris and Milan maintenance infrastructure sustains premium pricing multiples for metal-bodied refillable tiers. |
| Eastern European Channel Penetration | Poland and Romania convenience retail offers white-space positioning before incumbent consolidation accelerates. |
| Circular Infrastructure Pre-Positioning | Extended producer responsibility scheme readiness rewards French and German producers with compliance-first design. |
| REACH-Integrated Plating Capability | Auvergne-Rhône-Alpes surface finishing clusters respond fastest to ECHA chemical restriction tightening. |
Research Approach
Initial hypotheses were tested against primary input from brand managers at heritage metalworking ateliers, category buyers at German and French outdoor retailers, procurement leads at convenience store chains, and regulatory affairs specialists navigating ECHA compliance. These perspectives were refined through secondary validation against EU Green Deal policy documentation, EN 13869 certification databases, REACH restriction updates, customs trade flows for piezoelectric components, and SEC filings from diversified ignition product conglomerates. Bottom-up volume modeling across product type, material, distribution channel, and consumer type segments was triangulated with top-down market sizing from macroeconomic consumption indicators.
Variance-decomposition framing separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including ignition mechanism type, housing material compliance tier, retail channel format, and regional regulatory enforcement intensity. CAGRs were derived from regression-adjusted trend extrapolation incorporating electric lighter adoption curves, REACH reformulation timeline impacts, and single-use plastics directive phase-in schedules. Industry-specific forecast inputs include butane fuel cost volatility indices and lithium-cell shipping standard harmonization progress.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement intensity or accelerated electric substitution rates would require recalibration. Forecasts reflect documented assumptions regarding EN 13869 compliance filtration effectiveness and REACH chemical restriction implementation pace. Practitioners should keep alternative scenarios live as battery transport regulation convergence and extended producer responsibility scheme rollout timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Speaker Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
Vaporizer Market
Consumer Electronics
Notebook Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Pet Cameras Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Ultra-Portable Speakers Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Global 4K TV Market
Consumer Electronics
Camera Case Market
Consumer Electronics
UAE Consumer Electronics Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Speakerphones Market