
 Camera Case Market | 2026-2036
Camera Case Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Case Market Insights
A capital-intensity divergence between players is bifurcating competitive dynamics in protective camera enclosures. The Vitec Group plc leverages broadcast-sector relationships to sustain premium positioning in professional hard cases. Lap Shun Manufacturing Co Ltd. anchors high-volume OEM supply through integrated plastic-injection capacity in southern China. Crumpler Pty Ltd. differentiates via design-led soft-case specialization that commands direct-to-consumer loyalty.
A camera case constitutes a purpose-built protective enclosure engineered from leather, nylon, polycarbonate, or ABS to shield imaging equipment against impact, moisture, and abrasion during transport or field use. Wall thickness, foam density, and ingress-protection ratings determine functional performance across environmental conditions. Nylon and polycarbonate variants capture the dominant volume share due to weight-efficiency and moldability advantages. Leather segments retain concentrated margin pools among artisan-positioned brands serving professionals. Closure-type selection—zip, buckle, magnetic, or velcro—reflects trade-offs between access speed, security, and weather sealing that vary by end-user workflow.
REACH in Europe restricts phthalate content in synthetic fabrics and foam padding, while GB standards under China's SAMR govern structural integrity testing for hard-shell designs. The EU F-Gas Regulation indirectly shapes demand by accelerating mirrorless camera transitions that require redesigned case form factors. Stakeholders must monitor regulatory divergence between jurisdictions to avoid SKU fragmentation and certify unified product architectures.
Market Dynamics
The camera case market is bifurcating around Shenzhen's manufacturing gravity, where integrated injection-molding clusters compress unit economics for hard-shell enclosures while European REACH compliance forces material reformulation costs onto soft-padded suppliers.
Growth Catalysts
- Mirrorless camera proliferation:Compact full-frame bodies from Sony, Canon, and Nikon require redesigned internal foam geometries, driving replacement demand among existing owners upgrading from DSLR systems.
- REACH material mandates:Phthalate restrictions in synthetic fabrics and foam padding across the European Union are accelerating certified-supplier consolidation, favoring incumbents with pre-certified polymer supply chains.
- Content creator expansion:Independent filmmakers and YouTube producers now represent a discrete buyer segment with distinct workflow needs—rapid-access configurations and modular divider systems.
Market Restraints
- Petrochemical input volatility:Polycarbonate and ABS resin prices track crude oil benchmarks, compressing margin predictability for hard-shell manufacturers without long-term supply contracts.
- Shenzhen supplier concentration:Over 60 percent of global hard-case injection molding capacity sits within 50 kilometers of this single cluster, creating geographic risk exposure to regional power rationing or logistics disruption.
- Smartphone imaging substitution:Computational photography from Apple and Samsung devices satisfies casual capture needs, eroding entry-level point-and-shoot ownership and associated soft-case demand.
Strategic Opportunities
- India import substitution:BIS certification requirements and rising customs duties on finished goods create openings for domestic assembly operations serving South Asian professional photographers.
- Drone cinematography convergence:Dual-use enclosures protecting both handheld mirrorless rigs and compact cinema drones address the expanding owner-operator segment in commercial videography.
- SAMR structural testing alignment:China's GB standards for hard-shell integrity are migrating toward international harmonization, enabling unified SKU architectures that reduce certification duplication across export markets.
Industry Challenges
- Polymer chemist scarcity:Formulating REACH-compliant foam with equivalent impact absorption requires specialized compounding expertise concentrated among German and Japanese material suppliers.
- Multi-jurisdiction certification lag:Simultaneous ECHA registration, SAMR GB testing, and FDA indirect food-contact review for linings extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Case Market |
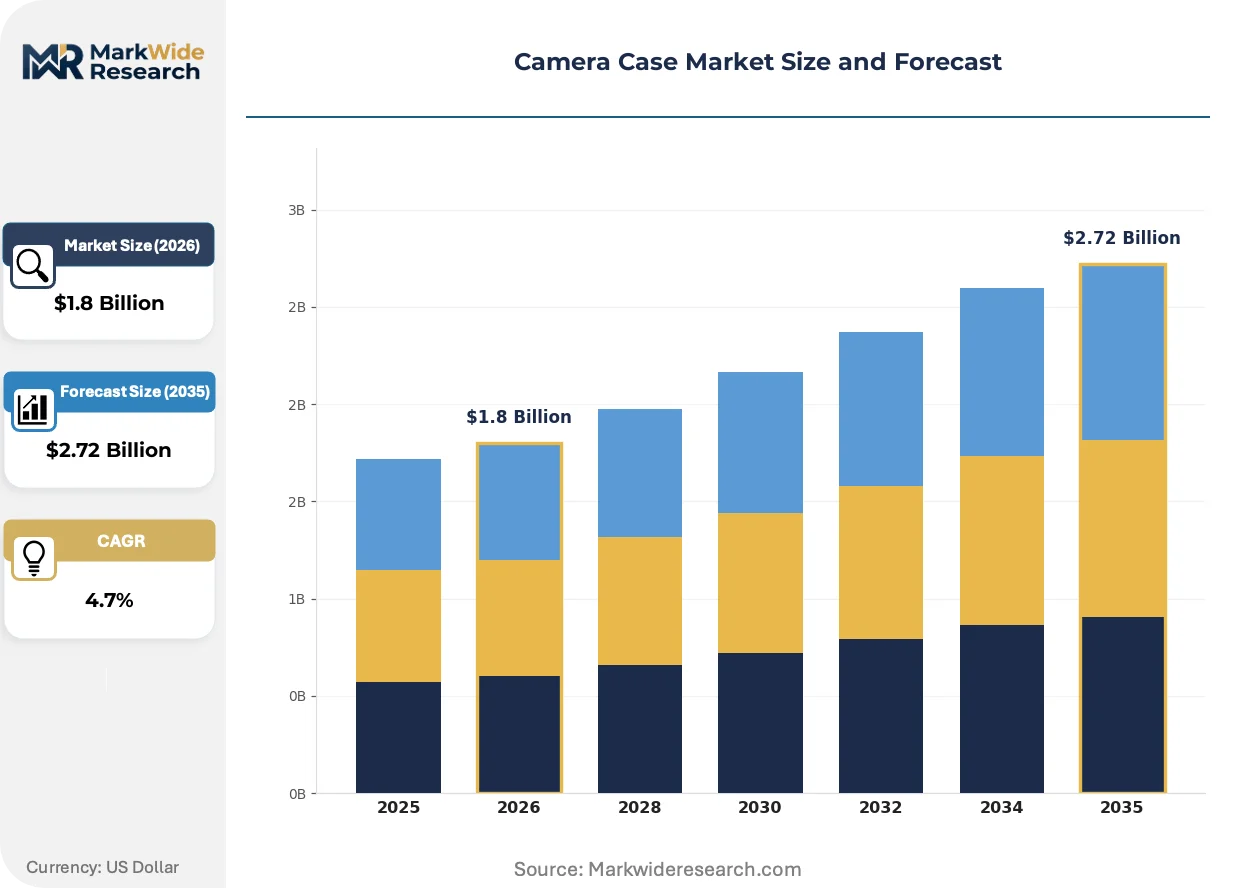
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Leather, Nylon, Polycarbonate, ABS Closure Type: Zip, Buckle, Magnetic, Velcro Size: Compact, Medium, Large, Extra Large End User: Professionals, Hobbyists, Students, Travelers |
| Companies Covered | Benro USA, Artantik LTD, Crumpler Pty Ltd., M Billingham & Co Limited, Gura Gear, The Vitec Group plc, Lap Shun Manufacturing Co Ltd., Case Logic Group, Cotton Carrier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Case Market Trends and Innovations
Active materials and smart enclosure technologies are redefining protective performance benchmarks, while regulatory fragmentation forces architectural compromises that favor modular over monolithic designs.
Thermoplastic polyurethane (TPU) co-molded shells with variable-density foam cores are supplanting traditional ABS hard cases in professional workflows. Wedding and documentary cinematographers prioritize these hybrid constructions for weight reduction during multi-location shoots. The structural consequence is compressing premium pricing power for legacy polycarbonate specialists unable to retool bonding equipment.
REACH Annex XVII phthalate restrictions now extend to plasticizers in zipper coatings and handle grips across European markets. Manufacturers reformulating with citrate-based alternatives face 15-20 percent raw material cost premiums that cascade through distributor markups. Soft-case suppliers serving German and French professional markets are absorbing these costs to maintain shelf positioning against hard-shell competitors.
Direct-to-brand purchasing via manufacturer-owned storefronts is displacing traditional camera retail channels for accessory categories. Content creators researching cases through YouTube reviews complete transactions on dedicated e-commerce platforms rather than B&H or local dealers. This pattern concentrates in North American and Australian markets where shipping logistics support 48-hour delivery expectations for protective gear.
Camera Case Market Segmentation
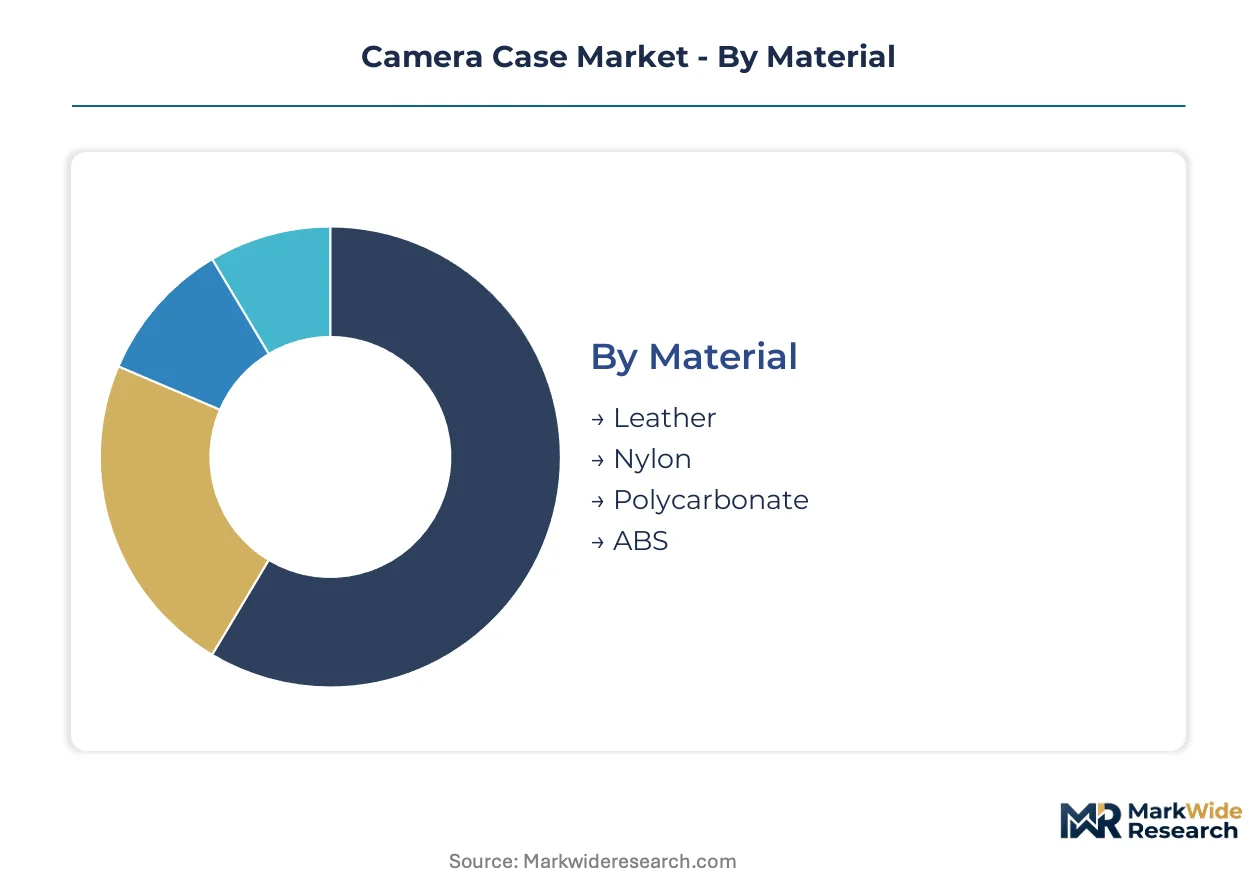
Camera case procurement decisions split across material chemistry, access mechanics, and dimensional fit. Each segmentation axis carries distinct regulatory exposure and margin architecture that shapes supplier positioning.
Material:
REACH Annex XVII phthalate restrictions and GB standard structural mandates create divergent compliance burdens across polymer classes.
- Nylon:Woven synthetic fabric dominates soft-case production for its tear resistance and dye compatibility. Wedding photographers across Germany and France prefer ballistic-grade weaves that withstand frequent transport cycles despite REACH-driven plasticizer cost premiums.
- Polycarbonate:Injection-molded thermoplastic delivers impact resistance for hard-shell enclosures at weight ratios superior to metal alternatives. Shenzhen's integrated molding clusters compress unit economics for this segment, though petrochemical price volatility threatens margin stability for suppliers without long-term resin contracts.
- Leather:Full-grain and top-grain hides retain artisan positioning among Italian and Japanese professional markets, with vegetable-tanned variants commanding certified-supplier premiums.
- ABS:Acrylonitrile butadiene styrene offers cost-efficient rigidity for entry-level hard cases, though TPU co-molding hybrids are displacing pure ABS in premium workflows.
Established volume favors polycarbonate; emerging adoption favors TPU-nylon hybrid constructions.
Closure Type:
Access speed requirements from content creator workflows are restructuring closure preferences away from security-first designs.
- Zip:Coil and toothed zipper systems enable rapid equipment access for documentary cinematographers. YKK and RiRi hardware suppliers face REACH coating reformulation costs that cascade through finished case pricing.
- Buckle:Side-release and cam-lock mechanisms secure hard-shell lids against pressure differentials during air travel. Professional wildlife photographers operating in Alaska and Patagonia prioritize buckle redundancy over zip convenience.
- Magnetic:Neodymium closure systems enable silent operation for ceremony videographers. Rare earth supply concentration in China's Jiangxi province creates procurement risk exposure for Western assemblers.
- Velcro:Hook-and-loop fastening retains utility in modular divider systems despite fiber degradation with field exposure.
Zip closures retain volume leadership; magnetic systems are climbing the fastest among wedding and event specialists.
Size:
Mirrorless form factor miniaturization is collapsing internal volume requirements across professional tiers.
- Compact:Single-body enclosures with fixed-lens or short-zoom accommodation. Sony A7C and Canon R8 owners drive replacement demand as full-frame sensors shrink housing dimensions.
- Medium:Two-body or body-plus-grip configurations with 2-3 lens slots. This tier captures the broadest cross-section of independent filmmaker spend.
- Large:Cinema camera rigs requiring matte box and battery plate clearance. RED and Blackmagic Design operators in Los Angeles and Mumbai anchor demand despite smartphone substitution pressure on adjacent segments.
- Extra Large:Multi-rig transport systems with lighting and audio integration. Commercial production houses in London and Sydney represent concentrated buyers.
Medium formats dominate current revenue; compact dimensions are gaining share fastest as mirrorless ownership broadens.
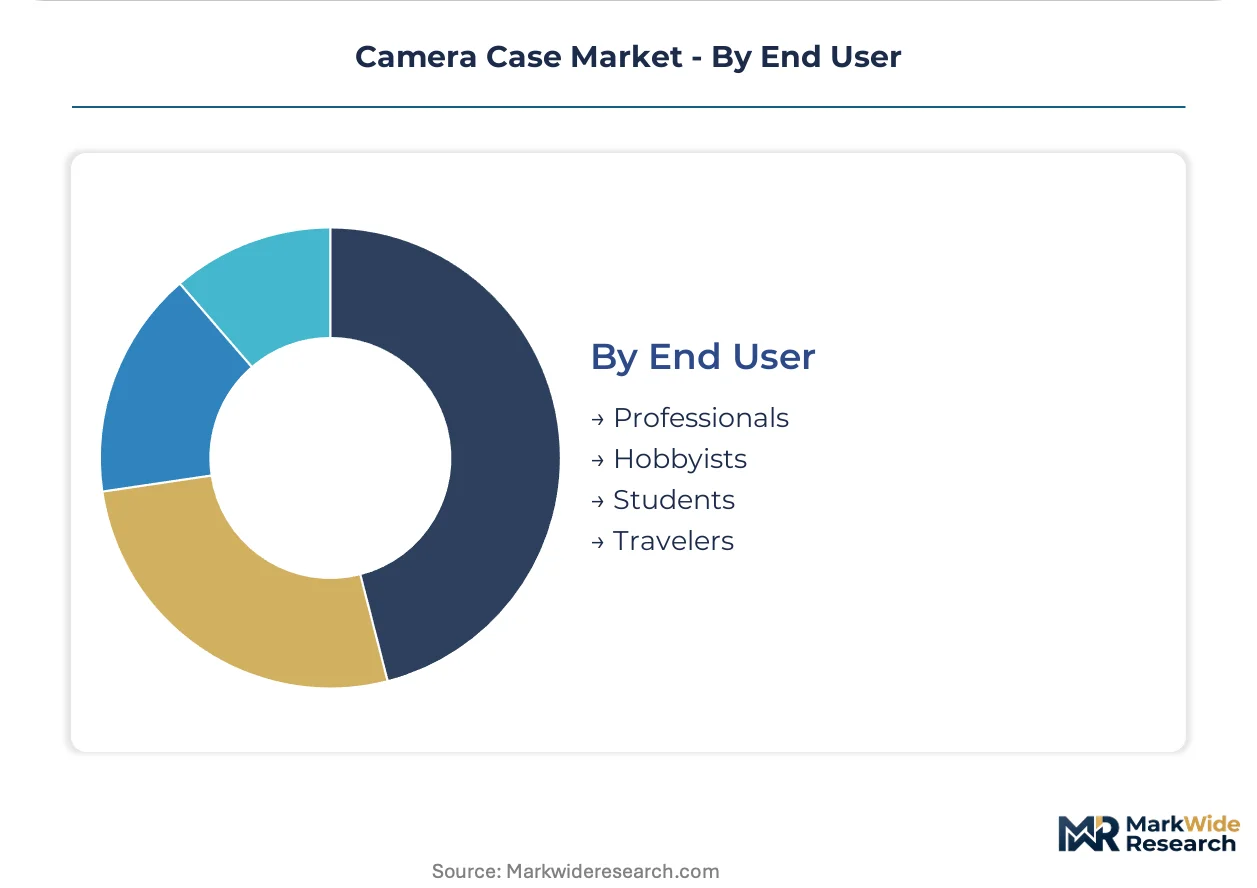
End User:
Workflow differentiation between commercial obligation and discretionary capture shapes feature prioritization across buyer tiers.
- Professionals:Commercial photographers and cinematographers require weather-sealing certification and modular divider systems. This segment absorbs premium pricing for REACH-compliant materials to avoid equipment loss liability.
- Hobbyists:Enthusiast owners with discretionary upgrade cycles prioritize aesthetic differentiation and brand signaling over technical specifications.
- Students:Educational program enrollees represent price-sensitive volume with high churn rates as program completion collapses replacement demand.
- Travelers:Hybrid users combining casual photography with general luggage needs favor dual-purpose designs that compromise pure protective performance.
Professional demand anchors margin pools; hobbyist expansion shows steepest volume trajectory as mirrorless ownership democratizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German and Japanese professionals absorb REACH-compliant material premiums without volume contraction, while Indian and Brazilian hobbyist segments exhibit acute price sensitivity that compresses distributor margins.
United States
Content creator proliferation in Los Angeles and New York drives rapid-access case configurations. FAA regulations on lithium-ion transport shape internal compartment designs for battery storage. Austin and Denver post-production hubs concentrate owner-operator demand for dual-use enclosures.
Germany
Wedding and documentary cinematographers in Berlin and Munich prioritize weather-sealed hard-shell systems. ECHA REACH Annex XVII enforcement tightens phthalate limits in foam padding and zipper coatings. Bavaria's broadcast equipment distributors anchor premium-tier procurement volumes.
China
Shenzhen's integrated injection-molding clusters supply over sixty percent of global hard-case capacity. SAMR GB standards govern structural integrity testing for export-bound enclosures. Pearl River Delta component vendors compress unit economics through captive resin supply chains.
India
BIS certification requirements and rising customs duties on finished goods accelerate domestic assembly investment. Professional photographers in Mumbai and Bengaluru drive medium-format case demand. Maharashtra's warehousing corridors concentrate import-substitution manufacturing trials.
Japan
Artisan-positioned leather case demand concentrates in Tokyo and Osaka professional markets. METI guidelines on product safety influence lining material specifications. Nagoya's precision-molding suppliers serve domestic mirrorless camera accessory ecosystems.
Camera Case Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a tiered competitive structure. Premium-positioned specialists command margin pools through broadcast-sector relationships and design-led differentiation, while scale-driven OEM suppliers anchor volume through integrated manufacturing clusters. Three archetypes dominate: vertically integrated molders, soft-case design specialists, and broadcast-equipment conglomerates. Capacity consolidation and direct-to-consumer channel expansion represent the dominant competitive moves across tiers.
Within the premium-tier vector, The Vitec Group plc occupies a position exemplifying broadcast-sector relationship leverage, while Crumpler Pty Ltd. represents design-led soft-case specialization. At the scale-driven end, Lap Shun Manufacturing Co Ltd. anchors high-volume OEM supply archetypes through southern China production integration.
| Leading Market Players |
|---|
| Benro USA |
| Artantik LTD |
| Crumpler Pty Ltd. |
| M Billingham & Co Limited |
| Gura Gear |
| The Vitec Group plc |
| Lap Shun Manufacturing Co Ltd. |
| Case Logic Group |
| Cotton Carrier |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's injection-molding clusters compress unit economics through 85-plus percent capacity utilization, anchoring global price floors for polycarbonate hard shells while forcing European soft-case suppliers to absorb REACH compliance premiums without matching scale.
Pricing Analysis
After-sales service bundling drives lifetime value through replacement foam inserts and warranty extensions. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-certified hard cases from OEM-supplied entry tiers. Price differentiation rests on REACH certification grade and volume scale commitments. Cost compression in the standard tier intensifies because petrochemical volatility erodes resin contract advantages. Hobbyist segments exhibit acute price sensitivity, while German and Japanese professionals absorb premium positioning without volume contraction.
Supply Chain Analysis
Container availability fluctuations on the Shenzhen-Rotterdam and Shenzhen-Los Angeles trade lanes compress inventory turns for Western distributors holding polycarbonate stock. Raw material flows draw from China's petrochemical corridor, Taiwan's precision-molding equipment suppliers, and Germany's compliant foam compounders. Single-source vulnerability concentrates in Jiangxi province's neodymium magnet output for silent-closure systems. Distribution runs through manufacturer-direct storefronts displacing traditional camera retail in North American and Australian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mirrorless camera proliferation represents a high-growth disruption as compact full-frame bodies force case redesign cycles, with ECHA REACH Annex XVII enforcement creating regulatory moats for pre-certified suppliers.
For Market Incumbents: Secure broadcast-sector relationships through extended service contracts and modular divider system patents. Defend against TPU-nylon hybrid displacement by retooling bonding equipment for co-molded construction. Backward integration into captive resin supply chains mitigates petrochemical price volatility exposure. For New Entrants and Emerging Players: Anchor in India's BIS certification gap for domestic assembly serving Mumbai and Bengaluru professional clusters. Target drone cinematography convergence as the most penetrable white-space, with dual-use enclosures protecting both mirrorless rigs and compact cinema drones. Deploy YouTube-native marketing to capture content creator procurement decisions outside traditional retail channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors design-led soft-case specialists with direct-to-consumer infrastructure over pure-play molders facing capital intensity divergence. Long-term viability hinges on regulatory compliance architecture spanning ECHA, SAMR, and FDA jurisdictions. Monitor SAMR GB standard harmonization progress as the inflection signal enabling unified SKU architectures and certification cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA Annex XVII alignment locks in shelf positioning across German and French professional markets. |
| TPU-Nylon Hybrid Platform Launch | Co-molded construction captures wedding and documentary cinematographer preference for weight reduction. |
| Direct-to-Consumer Channel Expansion | Manufacturer-owned storefronts bypass B&H and local dealers in North American and Australian markets. |
| India Domestic Assembly Investment | BIS certification and customs duty exposure favor Maharashtra warehousing corridor localization. |
| Drone Cinematography Dual-Use Design | Dual-rig enclosures address expanding owner-operator segment in commercial videography workflows. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with camera case manufacturers, polymer compounders, and broadcast equipment distributors; and secondary validation against ECHA registration databases, SAMR GB standard filings, and customs trade records. Stakeholder interviews captured procurement managers at European broadcast houses, Shenzhen injection-molding operators, and content creator equipment reviewers. Bottom-up volume triangulation from SKU-level production estimates converged with top-down market sizing from camera body shipment correlations.
Across the projection horizon, the analytical framework modeled segmentation dimensions including material chemistry, closure mechanism, dimensional tier, and end-user workflow archetype. CAGRs derived from historical replacement cycle analysis and mirrorless adoption curve projections. Industry-specific forecast inputs incorporated REACH compliance cost pass-through rates and Shenzhen cluster capacity utilization trends.
Underlying assumptions cover stable petrochemical pricing corridors and ECHA enforcement continuity, with deviation risk concentrated in single-source magnet supply disruption and smartphone substitution acceleration for entry-level segments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Ereader Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Portable Laptop Stands Market
Consumer Electronics
FMCG Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Phone Headsets Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market
Consumer Electronics
Global Hearable Devices Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Sleep Headphones Market