
 Notebook Market | 2026-2036
Notebook Market Size, Share, and Industry Trends Forecast 2026-2036
Notebook Market Outlook
The capital-intensity gap between integrated semiconductor fabricators and assembly-only OEMs is collapsing as in-house chip design becomes table stakes for performance differentiation. Lenovo leverages its vertically controlled supply chain to sustain margin resilience across price tiers. Dell anchors enterprise procurement through direct-channel relationships and configurable workstation portfolios. Apple competes by designing proprietary ARM-based silicon that extends battery life and thermal efficiency in thin-form devices.
A notebook is a portable personal computer integrating a clamshell display hinge, lithium-ion power cell, and x86 or ARM-based system-on-chip within a chassis typically weighing one to three kilograms, engineered for mobile productivity, content creation, and interactive entertainment away from fixed power sources. Ultrabooks and business notebooks occupy mature, high-margin procurement channels where enterprise IT departments prioritize manageability and security firmware, while gaming laptops represent the fastest-growing product type as discrete GPU thermal envelopes shrink and live-streaming workloads proliferate among creator-consumers. Processor-type segmentation reveals structural tension: Intel Core and AMD Ryzen architectures dominate volume, yet ARM-based designs are displacing legacy x86 positions in thin-and-light configurations where watt-per-watt performance governs purchasing decisions.
The FCC in the United States certifies electromagnetic emissions compliance, while the EU Ecodesign Directive and REACH frameworks impose substance restrictions and energy-consumption thresholds that reshape bill-of-materials choices and end-of-life obligations for brands selling into Europe. China's MIIT enforces wireless transmission standards and domestic encryption protocols that condition market access for foreign OEMs. Stakeholders must monitor how divergent repairability mandates across Washington, Brussels, and Beijing fragment product architecture roadmaps and service-network economics.
Market Dynamics
Enterprise refresh cycles across hybrid workforces sustain replacement demand while Ecodesign regulations in the European Union mandate repairability standards and recycled content thresholds that reshape product architecture roadmaps.
Growth Catalysts
- EU Ecodesign Directive:Mandatory repairability standards and recycled content thresholds create upgrade pull as enterprises retire non-compliant fleets ahead of enforcement deadlines.
- India PLI scheme:Local assembly incentives redirect procurement volumes toward domestic manufacturing, concentrating demand expansion in government digital-education programs.
- ARM-based silicon:Watt-per-watt performance gains in thin-form devices displace legacy x86 positions where battery life governs purchasing decisions.
Market Restraints
- Lithium-ion cell supply:Concentration of cathode precursor refining in China creates input cost volatility and geopolitical exposure for OEMs.
- MIIT encryption protocols:China's domestic wireless transmission standards condition market access friction for foreign OEMs seeking volume participation.
- Discrete GPU thermal envelopes:Technical limitations in mobile thermal management constrain performance scaling for creator-consumer workloads.
Strategic Opportunities
- India concentrated demand:Government digital-education procurement and local assembly incentives create white space for domestic manufacturing partnerships.
- Live-streaming workloads:Creator-consumer segment expansion opens premium positioning as GPU thermal solutions enable portable broadcast production.
- EU REACH substance restrictions:Regulatory tailwind favors OEMs with advanced recycling networks and circular design capabilities.
Industry Challenges
- Firmware security certification:Enterprise IT manageability requirements demand extended validation timelines that compress product launch windows.
- Supply chain reconfiguration:Divergent repairability mandates across Washington, Brussels, and Beijing fragment service-network economics and inventory planning.
- Legacy x86 software compatibility:ARM architecture migration creates integration complexity with enterprise application portfolios and virtualization stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Notebook Market |
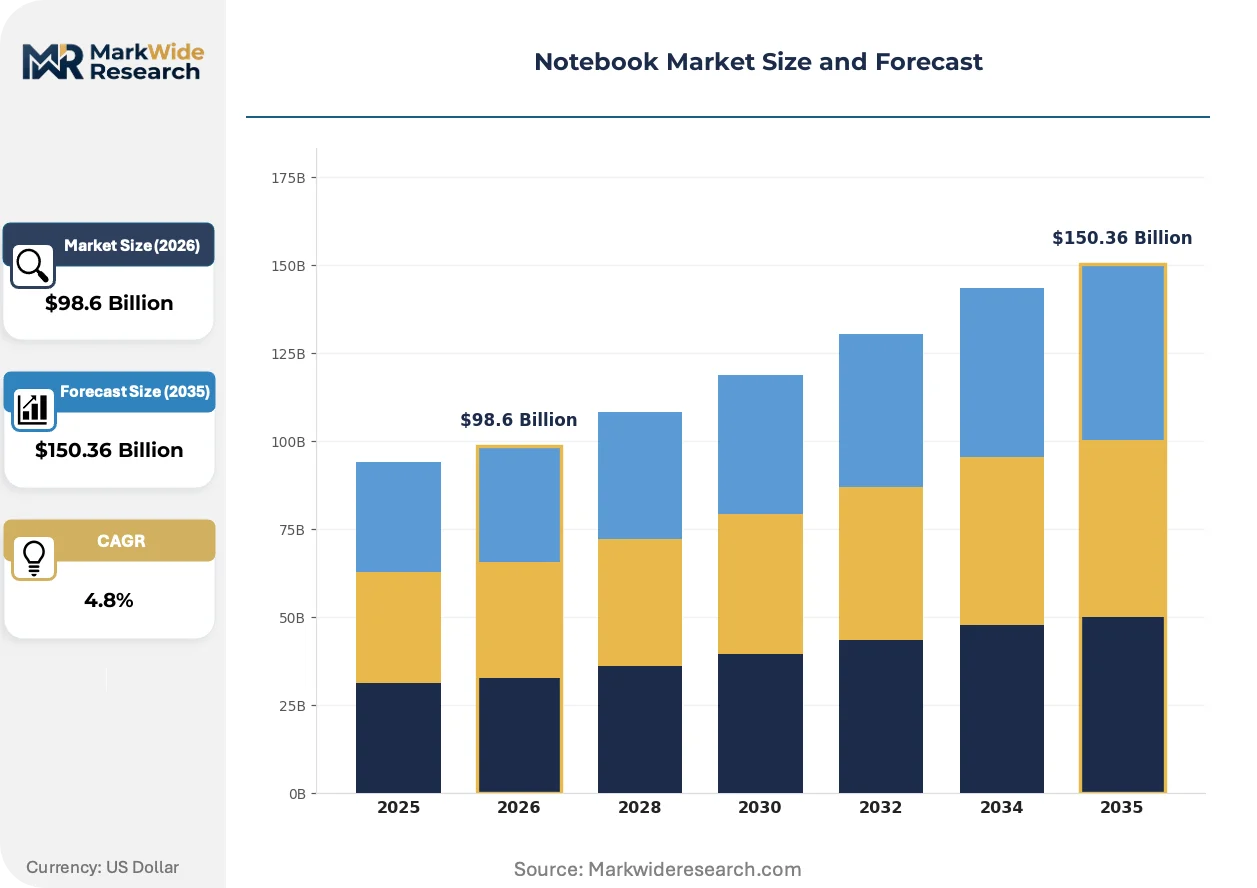
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $150.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrabooks, Gaming Laptops, Business Notebooks, 2-in-1 Devices Screen Size: 13 Inch, 15 Inch, 17 Inch, 14 Inch Processor Type: Intel Core, AMD Ryzen, ARM, Celeron Use Case: Education, Professional, Gaming, Casual Use |
| Companies Covered | Lenovo, HP, Dell, Apple, Asus, Acer, MSI, Samsung, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Notebook Market Strategic Shifts
Active reshaping in this market centers on thermal engineering breakthroughs, regulatory fragmentation across major economies, and procurement model evolution toward direct-channel configurability.
Chiplet-based processor architectures are decomposing monolithic die designs into modular compute, graphics, and I/O tiles that OEMs mix across product tiers. Enterprise workstation buyers now specify thermal and performance envelopes rather than fixed SKUs. This decomposition compresses time-to-market for differentiated configurations while fragmenting supplier qualification requirements.
REACH substance restrictions and the EU Ecodesign Directive impose substance restrictions and energy-consumption thresholds that reshape bill-of-materials choices. OEMs must document recycled content percentages and end-of-life take-back obligations for European market access. Thin-and-light product categories face the steepest compliance cost escalation as material substitution affects structural rigidity.
Direct-channel configurability is displacing distributor-led volume purchasing in enterprise segments. IT departments now specify security firmware, thermal envelopes, and manageability features through vendor portals rather than reseller catalogs. North American enterprise procurement exhibits the most pronounced shift, with hybrid workforce equipment refresh cycles favoring build-to-order fulfillment over pre-configured inventory.
Notebook Market Segmentation
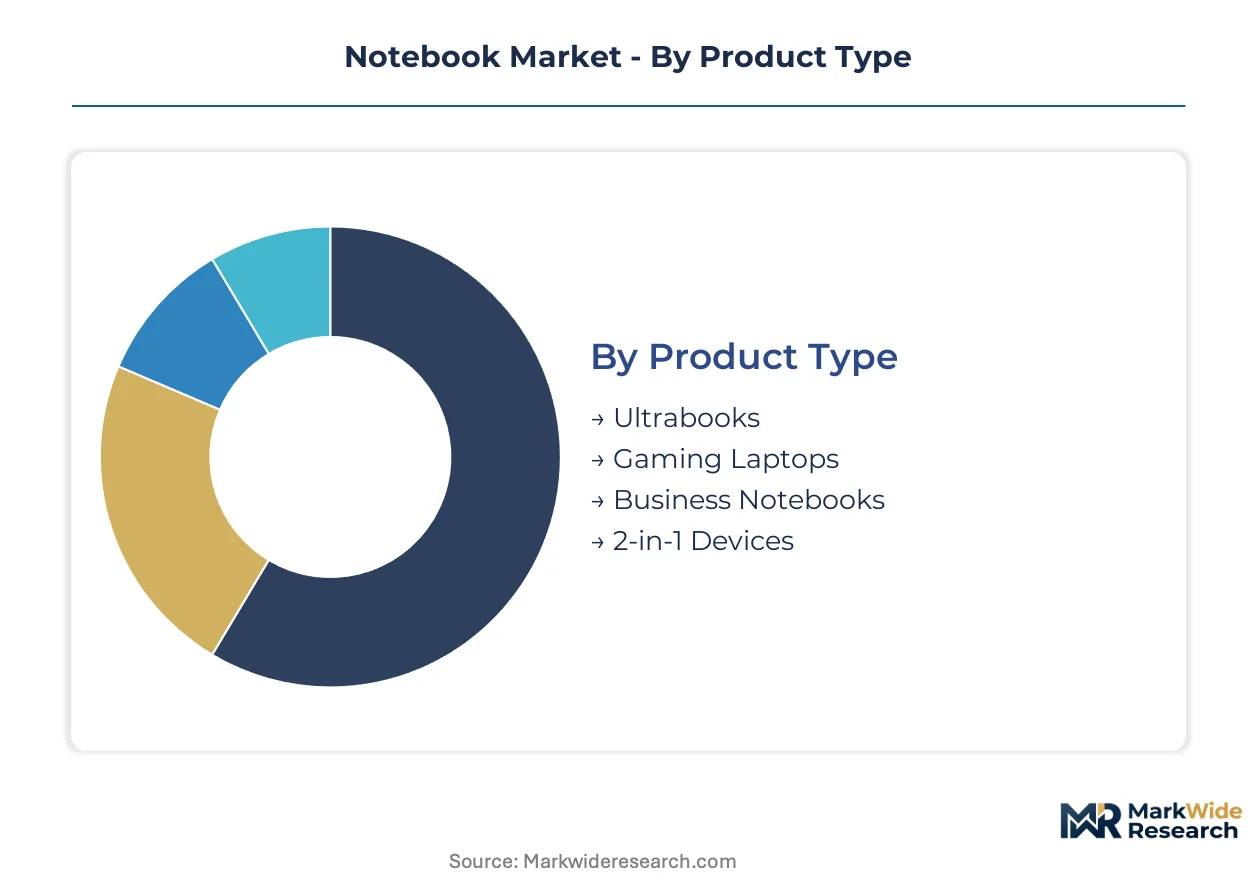
Notebook market segmentation reveals divergent procurement patterns across mobility requirements, thermal constraints, and software compatibility demands. Enterprise IT departments, educational institutions, and creator-consumers each impose distinct specification hierarchies that reshape vendor portfolio priorities. Understanding these segment boundaries clarifies where component innovation translates into pricing power versus commoditization pressure.
Product Type:
Domestic procurement concentrates in business notebooks and education-configured Ultrabooks, while gaming laptops and premium 2-in-1 devices flow through export channels into mature consumer markets.
- Ultrabooks:Thin-form clamshell designs prioritize sub-1.5kg chassis weights and extended battery endurance through low-wattage ARM or Intel Core-U processors. Procurement concentrates in corporate road-warrior fleets across Germany, Japan, and the United States where airline cabin compatibility and all-day untethered productivity govern purchasing decisions. Thermal constraints limit discrete GPU integration, pushing graphics workloads toward integrated solutions or cloud offload architectures.
- Gaming Laptops:Mobile chassis engineered for discrete GPU thermal envelopes above 100W TDP, incorporating vapor-chamber cooling and high-refresh-rate displays. Demand clusters in South Korea, China, and the United States where esports participation and live-streaming creator economies drive refresh cycles. NVIDIA and AMD GPU allocation scarcity creates supply rationing that favors direct-channel fulfillment over distributor inventory.
- Business Notebooks:Manageability-focused designs with vPro or equivalent enterprise security firmware, docking compatibility, and extended warranty terms.
- 2-in-1 Devices:Convertible hinge mechanisms enabling tablet-mode operation, targeting education and mobile professional segments with stylus input support.
Business notebooks command the established base. The steepest expansion runs through gaming laptops.
Screen Size:
Cost-tier stratification separates premium-margin large-format displays from high-volume mid-size configurations that dominate institutional procurement.
- 13 Inch:Compact panels optimizing portability for air travel and mobile fieldwork, typically paired with Ultrabook thermal envelopes and integrated graphics.
- 15 Inch:The volume anchor across education and mainstream professional segments, balancing screen real estate with chassis weight tolerable for daily commuting.
- 17 Inch:Desktop-replacement form factors prioritizing thermal headroom and display immersion, commanding premium pricing in gaming and workstation applications where mobility is secondary to performance.
- 14 Inch:Emerging compromise format gaining share in hybrid work configurations, offering incremental screen area over 13-inch designs without the bulk penalty of 15-inch chassis.
15-inch configurations anchor procurement volume. 14-inch formats are climbing the fastest as hybrid workforce equipment refresh cycles favor middle-ground specifications.
Processor Type:
Application-driven segmentation separates watt-per-watt efficiency priorities in thin-form mobility from raw compute scaling in workstation and gaming configurations.
- Intel Core:x86 architecture dominating enterprise compatibility and software certification pipelines, with vPro variants enabling remote manageability for IT departments. Procurement concentrates in North American and European Fortune 500 fleet refreshes where legacy application compatibility and virtualization stack validation create switching costs that delay ARM migration.
- ARM:RISC-based designs from Apple Silicon and Qualcomm Snapdragon platforms delivering superior performance-per-watt in fanless or thin-form chassis. Demand is accelerating in Japan, the United Kingdom, and Australia where battery endurance and thermal silence outweigh legacy software compatibility concerns for productivity-centric users.
- AMD Ryzen:x86 alternative gaining share in gaming and creator segments through competitive core-count pricing and integrated Radeon graphics performance.
- Celeron:Entry-level x86 processors targeting education price points and emerging market first-time buyers with basic productivity requirements.
Intel Core variants retain the installed base. ARM architectures are expanding most quickly as software emulation layers mature and thin-form priorities displace legacy compatibility requirements.
Use Case:
Customer-type segmentation separates institutional procurement cycles from discretionary consumer purchases with divergent replacement timing and specification flexibility.
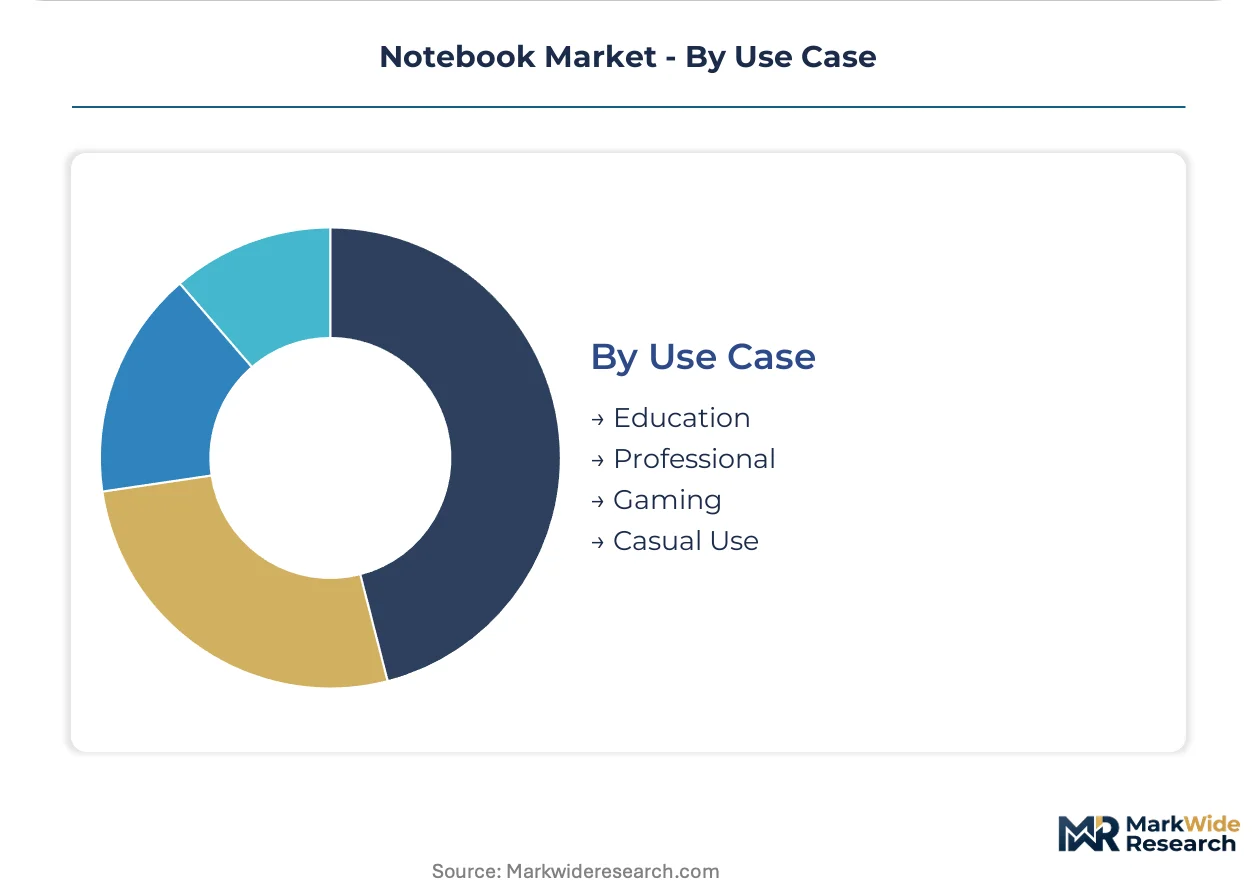
- Education:Price-optimized configurations with ruggedized chassis, spill-resistant keyboards, and fleet manageability tools. Procurement concentrates in India's government digital-education programs and United States K-12 district bulk purchases where total cost of ownership over 4-5 year lifecycles outweighs performance specifications. ChromeOS and Windows SE variants compete for operating system share in this segment.
- Professional:Workstation-grade mobile compute with ISV certifications for CAD, media production, and data science workloads. Demand clusters in Germany's engineering sector, California's media production corridors, and China's industrial design firms where software vendor support contracts mandate specific hardware configurations.
- Gaming:Performance-first configurations prioritizing GPU thermal capacity and display refresh rates over battery endurance or chassis weight.
- Casual Use:General-purpose browsing and media consumption, typically served through retail channels with minimal configuration flexibility.
Professional use cases command margin concentration. Education procurement is gaining share fastest as national digital literacy programs redirect public spending toward domestic assembly incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exhibits the steepest price elasticity among volume markets as government procurement dominates education-segment demand, while Japan and Germany sustain premium-tier inelasticity through enterprise workstation refresh cycles and engineering-sector specifications.
United States
Enterprise IT departments drive replacement demand through hybrid workforce equipment refreshes, prioritizing manageability firmware and security certifications. The FCC certifies electromagnetic emissions compliance for all devices entering commercial distribution. Austin and Seattle host engineering clusters where cloud-first enterprises specify ARM-based thin-form devices for untethered productivity.
Germany
Engineering-sector procurement concentrates in CAD and industrial design workstations requiring ISV-certified configurations. The EU Ecodesign Directive mandates repairability standards and recycled content thresholds that reshape product architecture for European market access. Munich and Stuttgart anchor demand clusters where automotive and machinery OEMs specify mobile workstations with extended thermal envelopes.
India
Government digital-education programs redirect procurement volumes toward domestic manufacturing under PLI scheme incentives. BIS standards enforce safety and interoperability requirements for devices sold into institutional channels. Tamil Nadu and Karnataka concentrate assembly operations where local production qualifies for public-sector tender preferences.
China
Creator-consumer segments drive gaming laptop demand as esports participation and live-streaming economies expand. MIIT enforces wireless transmission standards and domestic encryption protocols that condition market access for foreign OEMs. Shenzhen and Suzhou host supply chain clusters where vapor-chamber thermal engineering and high-refresh display integration concentrate.
Japan
Corporate road-warrior fleets prioritize sub-1.5kg Ultrabook configurations with extended battery endurance for airline cabin compatibility. METI standards govern energy efficiency labeling and circular economy obligations for electronics manufacturers. Tokyo and Osaka concentrate financial services and precision engineering procurement where thermal silence and watt-per-watt performance govern purchasing decisions.
Notebook Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding enterprise direct-channel relationships and captive silicon design capabilities. The middle tier fragments across gaming specialists, education-focused assemblers, and regional distributors serving price-sensitive emerging markets. Two strategic archetypes dominate: vertically integrated platforms controlling chip-to-chassis supply chains, and configuration specialists building modular workstation portfolios around standardized thermal and performance envelopes. Competitive moves concentrate on geographic diversification of assembly capacity and regulatory pre-certification of security firmware for enterprise procurement pipelines.
Among integrated platform operators, Lenovo and Dell exemplify the enterprise-direct archetype, while Apple occupies a distinct premium-tier position through proprietary ARM-based silicon design. These three anchors represent divergent responses to thermal engineering constraints and procurement model evolution, with each emphasizing different combinations of supply chain control, direct-channel configurability, and architecture differentiation in thin-form mobility segments.
| Leading Market Players |
|---|
| Lenovo |
| HP |
| Dell |
| Apple |
| Asus |
| Acer |
| MSI |
| Samsung |
| Microsoft |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for lithium-ion cathode precursors lock in supply access and price visibility for OEMs navigating volatile input costs from Chinese refining concentration. These contracts insulate assembly operations against spot-market swings while committing procurement volumes to specific supplier relationships.
Pricing Analysis
After-sales service revenue from extended warranty contracts and enterprise manageability subscriptions drives lifetime value beyond hardware margins. Three-tier pricing structure across premium workstation, standard business, and economy education levels segments procurement channels. Cost compression in entry-level configurations is intensifying because India's PLI scheme redirects public tenders toward locally assembled units with domestic content requirements. Education procurement exhibits highest price sensitivity as government digital-literacy programs optimize total cost of ownership over four-to-five-year replacement cycles.
Supply Chain Analysis
Strategic stockpile preferences for semiconductor inventory have displaced just-in-time norms following pandemic-induced allocation scarcity. Taiwan, South Korea, and the United States concentrate advanced logic fabrication capacity. Cathode precursor refining, display panel manufacturing, and vapor-chamber thermal components draw from Chinese supply clusters. Single-source vulnerability in GPU allocation from NVIDIA and AMD creates supply rationing that favors direct-channel fulfillment. Distribution runs through vendor portals for enterprise segments and retail channels for consumer purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-form thermal engineering expertise sits in scarce supply relative to proliferating ARM-based design pipelines, constraining how quickly OEMs can replicate Apple's silicon-to-chassis integration model.
For Market Incumbents: Compound enterprise direct-channel relationships by embedding security firmware pre-certification into procurement portals ahead of FCC and EU Ecodesign enforcement timelines. Extend captive ARM design capabilities through chiplet architecture investments that compress time-to-market for differentiated thermal envelopes. Defend against configuration specialists by anchoring workstation portfolios with ISV-certified GPU thermal solutions. For New Entrants and Emerging Players: Enterprise repairability compliance gaps in existing service networks present white-space entry points. Target India's government digital-education procurement under PLI scheme incentives where local assembly partnerships qualify for tender preferences. Pursue white-label education configurations with ruggedized chassis specifications and ChromeOS manageability stacks. For Investors and Strategic Acquirers: Thermal engineering boutiques with vapor-chamber and fanless design IP represent priority acquisition archetypes. Long-term viability hinges on regulatory pre-certification capabilities across divergent EU, US, and Chinese repairability mandates. Watch ARM-native software emulation maturity as inflection indicator for enterprise switching cost erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Architecture Investment | Modular processor designs enable faster thermal envelope customization across product tiers. |
| EU Ecodesign Pre-Certification | Repairability compliance secures market access ahead of recycled content threshold enforcement. |
| India PLI Assembly Partnership | Local production qualifies OEMs for government digital-education procurement preferences. |
| Direct-Channel Portal Expansion | Build-to-order fulfillment displaces distributor inventory in hybrid workforce refresh cycles. |
| Enterprise Security Firmware Embedding | vPro-equivalent manageability anchors Fortune 500 fleet replacement decisions. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs. OEM platform engineers, enterprise IT procurement officers, thermal engineering specialists, and education-sector tender administrators provided operational perspectives. Secondary validation drew from FCC equipment authorization databases, EU Ecodesign implementing measures, MIIT wireless transmission filings, and customs trade records for lithium-ion cell imports. Bottom-up shipment modeling and top-down value reconciliation triangulated market estimates.
Across the analysis window, forecasts segmented by product type, processor architecture, screen size, and use case application. CAGRs derived from replacement cycle timing, regulatory enforcement schedules, and procurement volume shifts across hybrid workforce and digital-education programs. ARM architecture penetration rates and GPU thermal envelope scaling constraints informed scenario-weighted projections.
Underlying assumptions cover enterprise refresh cycle continuity, PLI scheme incentive stability, and lithium-ion supply chain resiliency, with deviation risk concentrated in geopolitical trade restriction escalation and ARM software emulation maturity. Revision becomes warranted when ARM-native application portfolio coverage crosses enterprise IT validation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
4K Television Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Smart DJ Controller Market
Consumer Electronics
Baby Monitor Market
Consumer Electronics
Phone Headsets Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Portable Laptop Stands Market
Consumer Electronics
Gaming PC Market
Consumer Electronics
Portable Speaker Market
Consumer Electronics
Camera Case Market