
 Global Speaker Market | 2026-2036
Global Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Speaker Market Outlook
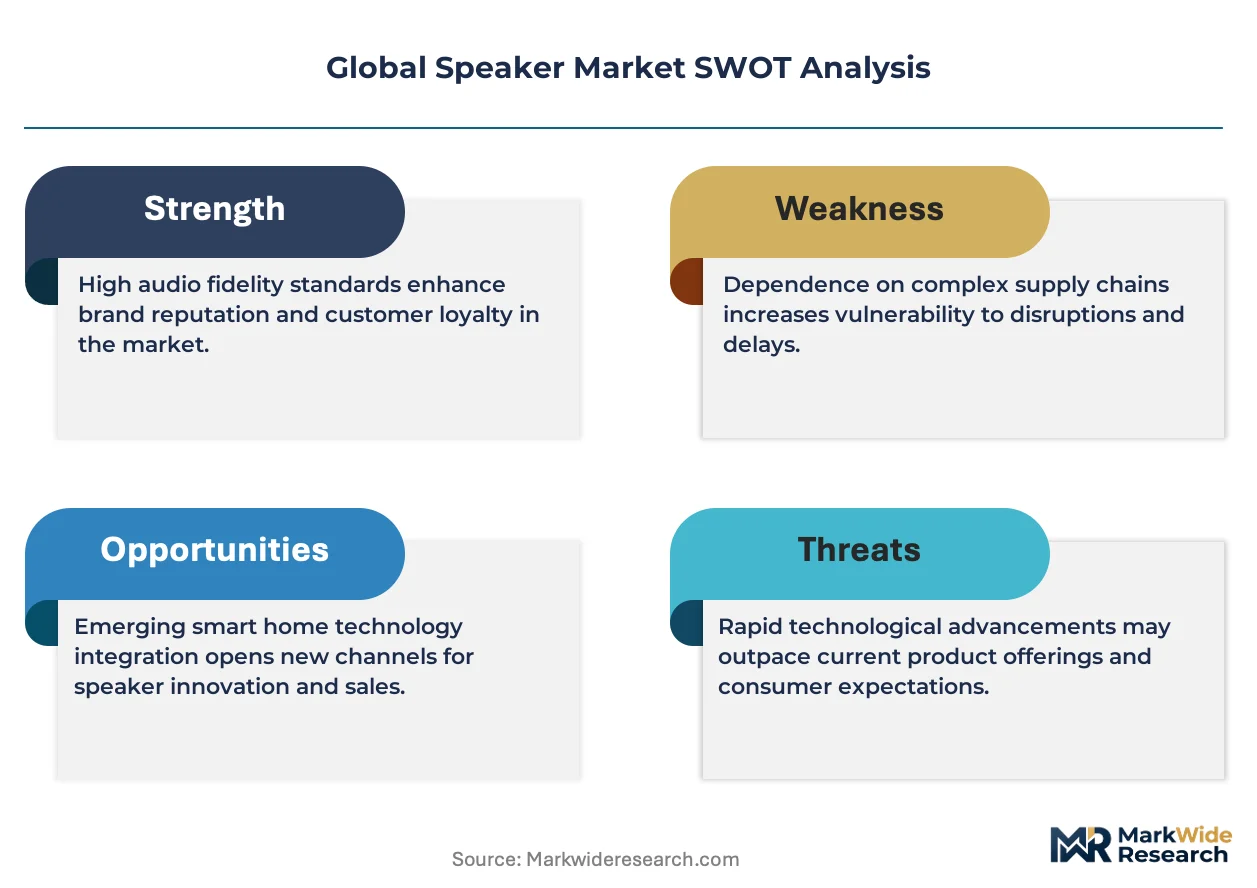
The premium speaker tier is repositioning around spatial audio and room-calibration software, while commodity segments compete on cost-optimized driver arrays and white-label manufacturing. Sony Group Corp. leverages its cinema-to-consumer audio pipeline to sustain technology leadership in immersive formats. Harman International Industries anchors automotive OEM contracts with embedded speaker systems. Samsung Electronics Co. Ltd. differentiates through vertical integration of display and soundbar ecosystems.
A speaker converts electrical audio signals into mechanical sound waves through electromagnetic voice coils, diaphragms, and acoustic enclosures, with performance measured by frequency response range, sensitivity in decibels, and total harmonic distortion. Portable Bluetooth products dominate unit volume but compress margins, while professional sound installations for live events command higher average selling prices due to weatherized enclosures and networked DSP control. Wi-Fi-connected home theater systems are capturing share from wired configurations as multi-room streaming protocols standardize.
The EU Ecodesign Directive and REACH chemical standards constrain driver magnet materials and enclosure finishes, while the FCC in the United States governs RF emissions for wireless speaker models. Japan's METI enforces energy labeling that shapes consumer purchasing patterns for active speaker systems. Stakeholders must monitor how regulatory divergence on recycled content mandates affects cross-border component sourcing and finished goods certification costs.
Market Dynamics
Voice-controlled smart home ecosystems are pulling speaker hardware toward integrated AI processing and low-latency wireless protocols, compressing development cycles for standalone audio components.
Growth Catalysts
- EU Ecodesign Directive:Energy-efficiency mandates for active speaker systems are accelerating R&D investment in Class-D amplifier architectures and neodymium-free driver magnets.
- Automotive embedded audio:Electric vehicle platforms are expanding cabin speaker counts to 15-20 units per vehicle, creating captive demand for weatherized coaxial and subwoofer assemblies.
- Multi-room streaming protocols:Wi-Fi 6E and Matter standardization is overtaking proprietary mesh networks, reducing interoperability friction for whole-home audio deployments.
Market Restraints
- Rare earth magnet dependency:China concentrates 87% of global neodymium processing capacity, exposing driver manufacturers to supply disruption and price volatility.
- REACH chemical compliance:ECHA restrictions on enclosure finishes and adhesive formulations are lengthening qualification timelines for European market entry.
- Smartphone speaker substitution:Improved onboard audio processing and spatial audio rendering in flagship handsets is compressing demand for entry-level portable Bluetooth units.
Strategic Opportunities
- India smart home penetration:Sub-5% household adoption of voice-controlled speakers creates whitespace for localized Hindi and regional language wake-word models.
- Live event DSP integration:Networked loudspeaker management with predictive thermal modeling is enabling premium rental fleet differentiation in professional audio services.
- Japan METI energy labeling:Top-tier efficiency ratings are shaping consumer preference hierarchies, rewarding manufacturers with captive amplifier and power supply design capabilities.
Industry Challenges
- Acoustic engineering talent scarcity:Finite pools of transducer designers with expertise in horn-loaded waveguides and line-array beam steering are concentrating at automotive OEMs and cinema equipment suppliers.
- RF certification fragmentation:Divergent FCC, CE, and Telec testing protocols for wireless speaker models are multiplying SKU complexity and inventory carrying costs.
- Legacy analog integration:Professional install bases with balanced XLR and Dante networked audio require backward-compatible signal path engineering that delays pure-IP product transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Speaker Market |
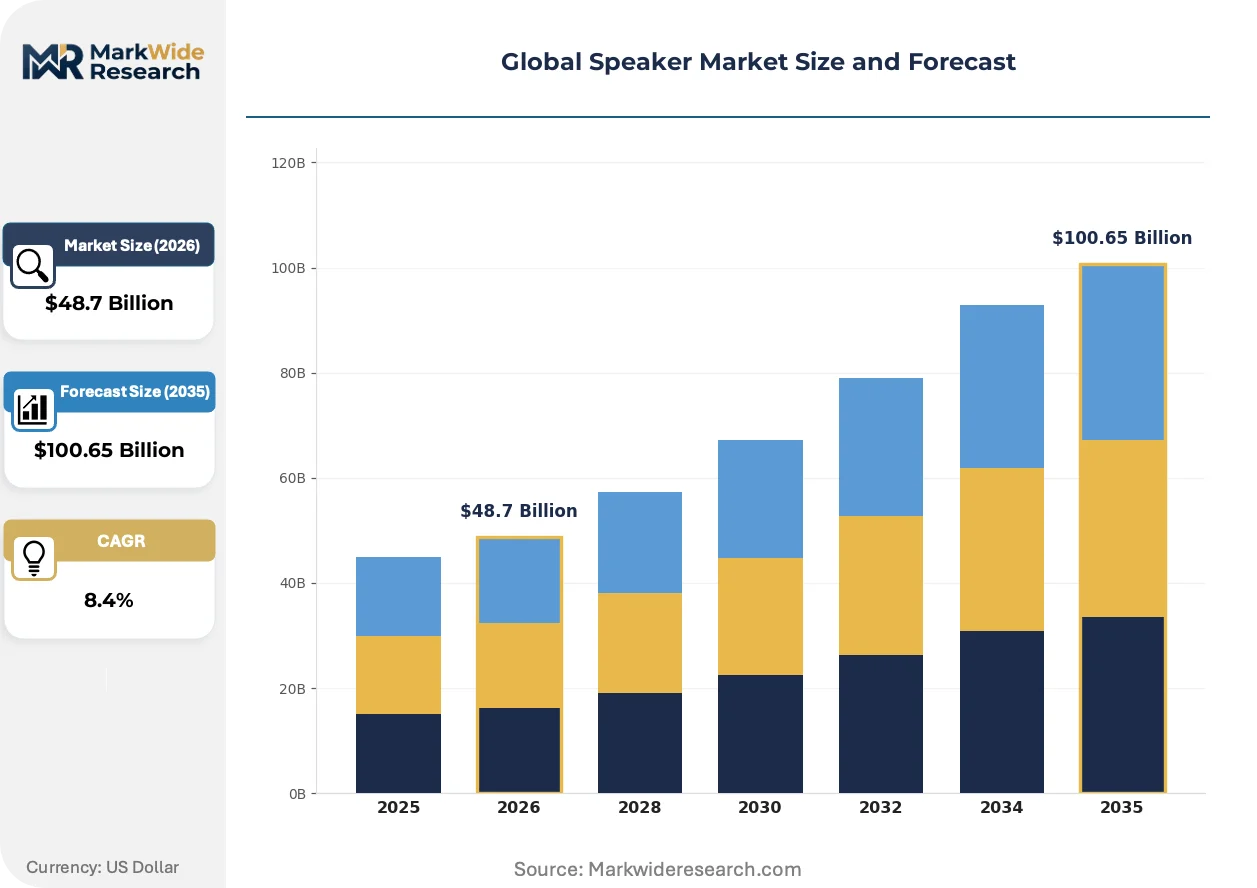
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Floor-standing, Bookshelf, In-wall Connectivity: Wired, Bluetooth, Wi-Fi, NFC Application: Home Theater, Professional Sound, Personal Use, Outdoor Events End User: Consumers, Corporates, Educational Institutions, Event Organizers |
| Companies Covered | Bose Corporation, Sony Group Corp., Samsung Electronics Co. Ltd., Apple Inc., Amazon.com Inc., Harman International Industries, Sonos Inc., Yamaha Corporation, Altec Lansing Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Speaker Market Strategic Shifts
Computational audio and software-defined acoustic processing are decoupling sound quality from physical enclosure volume, enabling form-factor experimentation across portable, architectural, and automotive applications.
Beamforming microphone arrays with on-device neural processing are overtaking simple far-field voice capture in premium smart speakers. Hospitality and enterprise conferencing buyers are specifying these systems for ambient noise rejection without cloud latency. The shift is compressing margins for commodity far-field microphone suppliers while rewarding semiconductor vendors with dedicated audio DSP IP.
REACH restrictions on SVHC substances in driver adhesives and cone materials are forcing reformulation of traditional paper-pulp and polypropylene composites. German and French manufacturers are accelerating bio-based cellulose and recycled ocean plastic validation programs. The regulatory friction is most acute in DIY replacement driver segments where legacy inventory faces write-down risk.
Direct-to-installer distribution via specialized AV integrator portals is displacing traditional two-step distribution for professional sound reinforcement equipment. Commercial project contractors in the United States and United Kingdom are specifying equipment through these channels to access configuration software and extended warranty terms. The behavioral shift is visible most sharply in house-of-worship and corporate campus verticals where project complexity demands pre-sale technical support.
Global Speaker Market Segmentation
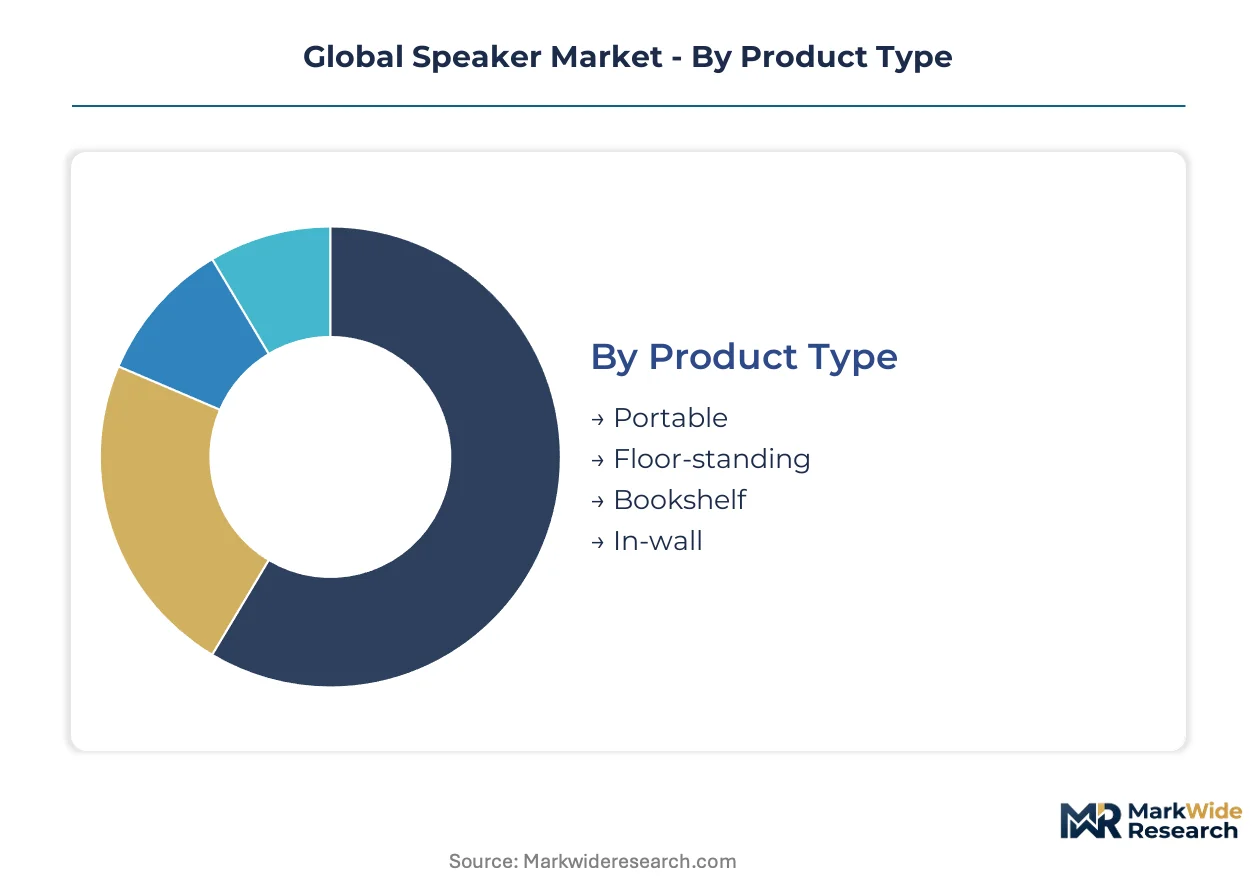
Speaker procurement patterns diverge sharply across use environments, from living-room aesthetics to weatherized stage rigs. Understanding these splits reveals where component sourcing, amplifier design, and distribution investments should concentrate.
Product Type:
Physical form factor governs driver array complexity, enclosure material costs, and retail channel selection.
- Portable:Battery-powered units with sealed enclosures and Class-D amplification dominate unit shipments. Demand concentrates in commuter corridors of Germany and Japan where transit audio consumption is habitual, though margin compression from white-label Shenzhen suppliers constrains branded players.
- Floor-standing:Multi-driver towers with ported bass reflex enclosures and passive radiator configurations anchor premium home theater installations. Procurement clusters in suburban United States markets where dedicated listening rooms remain architecturally feasible, driven by spatial audio format adoption.
- Bookshelf:Compact two-way designs with silk-dome tweeters and woven Kevlar woofers serve desktop and small-room applications.
- In-wall:Flush-mount architectural speakers with paintable grilles integrate into residential construction and commercial fit-outs.
Volume sits with Portable; growth tilts toward In-wall.
Connectivity:
Signal path architecture determines RF certification burden, latency tolerance, and interoperability with source devices.
- Wired:Analog RCA and balanced XLR connections persist in professional monitoring and audiophile segments. Demand concentrates in Nashville and Los Angeles studio complexes where zero-latency tracking is non-negotiable, constrained by legacy infrastructure replacement cycles.
- Bluetooth:Short-range wireless with SBC and aptX codec support saturates entry-level portable shipments. Procurement clusters in mass-market retail channels across China and India, though audio quality limitations push premium buyers toward alternative protocols.
- Wi-Fi:Multi-room streaming with AirPlay 2 and Chromecast integration enables whole-home audio synchronization.
- NFC:Tap-to-pair functionality simplifies Bluetooth pairing for hospitality and automotive aftermarket applications.
Bluetooth captures volume; Wi-Fi climbs the fastest.
Application:
Use-case intensity shapes durability specifications, SPL requirements, and service contract structures.
- Home Theater:5.1 and 7.1 channel configurations with dedicated subwoofer channels anchor residential entertainment systems. Demand concentrates in new construction developments across Texas and Florida where pre-wiring for surround sound is standard, driven by streaming platform spatial audio content expansion.
- Professional Sound:Line arrays and point-source loudspeakers with networked DSP control serve live events and installed venues. Procurement clusters in touring rental fleets operating out of London and Berlin, constrained by skilled technician availability for system optimization.
- Personal Use:Headphone and nearfield monitor segments overlap with speaker peripherals for individual consumption.
- Outdoor Events:Weatherized enclosures with IP ratings and battery power options serve festivals and temporary installations.
Personal Use holds volume; Professional Sound gains share fastest.
End User:
Purchasing authority and budget cycles determine sales cycle length, customization depth, and payment terms.
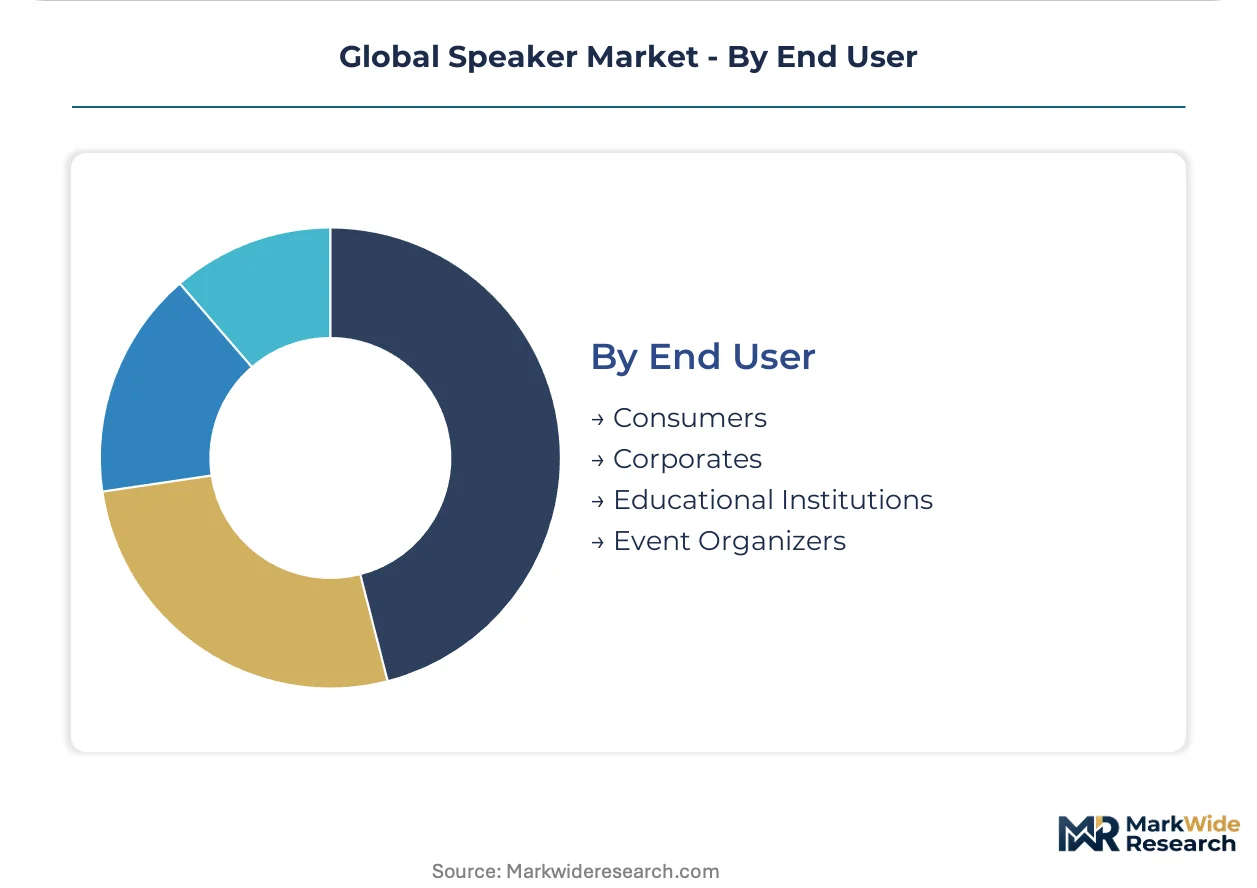
- Consumers:Individual purchasers making discretionary retail decisions. Demand concentrates in e-commerce channels serving Shanghai and São Paulo metropolitan areas, driven by unboxing experience and review-driven selection behavior.
- Corporates:Facilities managers procuring conferencing and background music systems for offices and retail spaces. Procurement clusters in Fortune 500 headquarters renovations across Illinois and California, constrained by IT security review processes for networked audio.
- Educational Institutions:K-12 and university AV departments funding lecture hall and auditorium installations.
- Event Organizers:Rental houses and production companies acquiring inventory for temporary deployments.
Consumers dominate volume; Corporates show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors global speaker manufacturing with its dense ecosystem of driver suppliers, enclosure fabricators, and RF testing laboratories serving both branded OEMs and white-label exporters.
United States
Smart home penetration and automotive embedded audio drive procurement across Texas and California suburban developments. FCC RF emission standards govern wireless speaker certification protocols. Nashville and Los Angeles studio complexes sustain demand for zero-latency wired monitoring systems in professional audio segments.
Germany
Transit audio consumption habits in Berlin and Munich commuter corridors sustain portable Bluetooth shipments despite margin compression. EU Ecodesign Directive mandates accelerate Class-D amplifier R&D investment. Stuttgart automotive suppliers specialize in weatherized coaxial assemblies for electric vehicle platforms requiring 15-20 cabin speakers per vehicle.
China
Mass-market retail channels in Shanghai and Shenzhen concentrate entry-level portable speaker procurement volume. The country's national electronics regulator enforces GB standards for wireless transmission compliance. Pearl River Delta manufacturing clusters dominate white-label production for global export markets.
Japan
Habitual transit audio consumption in Tokyo and Osaka metropolitan areas sustains portable unit demand. METI energy labeling programs shape consumer preference hierarchies for active speaker systems. Nagoya-based suppliers specialize in captive amplifier and power supply design capabilities for premium efficiency-rated products.
India
Sub-5% household voice-controlled speaker adoption creates whitespace for localized Hindi and regional language wake-word models. The Bureau of Indian Standards governs electronics safety certification for imported audio equipment. Bangalore and Delhi-NCR technology corridors concentrate smart home ecosystem development and testing facilities.
Global Speaker Market Competitive Environment
Premium-margin players sit above commodity-margin players across spatial audio software and automotive OEM integration capabilities. The vendor base stratifies into three tiers: cinema-to-consumer audio pipeline specialists, automotive embedded system anchors, and display-soundbar ecosystem integrators. Dominant competitive moves include backward integration into driver magnet supply chains and strategic partnerships with streaming platform operators for spatial audio format licensing.
Within the premium-tier vector, Sony Group Corp. exemplifies the cinema-to-consumer audio pipeline archetype, while Harman International Industries occupies the automotive embedded systems position. Samsung Electronics Co. Ltd. represents the display-soundbar ecosystem integration model. These three entities collectively illustrate how vertical control over adjacent technology domains differentiates positioning against white-label Shenzhen competitors.
| Leading Market Players |
|---|
| Bose Corporation |
| Sony Group Corp. |
| Samsung Electronics Co. Ltd. |
| Apple Inc. |
| Amazon.com Inc. |
| Harman International Industries |
| Sonos Inc. |
| Yamaha Corporation |
| Altec Lansing Inc. |
| Others |
Value Chain & Pricing Dynamics
Acoustic engineering talent scarcity in Stuttgart and Nagoya clusters compresses development-cost differentials between premium spatial-audio systems and commodity Bluetooth units, widening pricing-tier spreads across the value chain.
Pricing Analysis
Value-based pricing anchors on spatial-audio format licensing and room-calibration software outcomes rather than hardware bill-of-materials alone. Three-tier pricing structure across premium, standard, and economy levels separates cinema-to-consumer pipeline specialists from white-label Shenzhen exporters, with certification tier under EU Ecodesign and METI energy labeling programs commanding measurable premiums. Cost compression in entry-level portable segments is intensifying because white-label manufacturers in the Pearl River Delta scale Class-D amplifier production. Corporate AV buyers show lowest price sensitivity given IT security and extended warranty requirements, while mass-market consumers in India and Brazil drive hard bargaining on entry-level Bluetooth units.
Supply Chain Analysis
Single-source vulnerability sits with China's concentration of neodymium magnet processing and GB-standard RF testing laboratories. Manufacturing gravity centers on Shenzhen for white-label assembly, Stuttgart for automotive embedded systems, and Nagoya for captive amplifier design. Raw material dependencies span neodymium magnets, cellulose cone composites, and Wi-Fi 6E chipsets. Tariff exposure on finished electronics from China into the United States and European Union threatens margin structures for brands without regional manufacturing footprints. Distribution runs through direct-to-installer portals for professional sound reinforcement, mass-market retail for portable units, and automotive Tier 1 suppliers for embedded cabin audio.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over driver magnet supply chains and streaming platform licensing terms determines margin capture across spatial-audio tiers.
For Market Incumbents: To counter white-label Shenzhen cost compression, Sony Group Corp. and Harman International Industries should deepen backward integration into neodymium-free magnet R&D and secure exclusive spatial-audio format licensing with streaming operators. Captive amplifier design capabilities in Nagoya and Stuttgart clusters defend efficiency-rating premiums under METI and EU Ecodesign programs. For New Entrants and Emerging Players: The 300-500 dollar price-point gap between Sonos Wi-Fi systems and entry-level Amazon Echo units offers white-space for Hindi and regional-language wake-word models in Indian smart home deployments. Targeting corporate AV integrator portals with Matter-compatible multi-room hardware bypasses saturated consumer retail channels. For Investors and Strategic Acquirers: Re-rating potential sits with automotive embedded audio specialists given electric vehicle platform expansion to 15-20 cabin speakers per vehicle. Long-term viability over a multi-year horizon favors suppliers with weatherized coaxial assembly expertise and Stuttgart OEM relationships. The signal to monitor is Class-D amplifier efficiency breakthroughs that reshape METI labeling hierarchies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Neodymium-free driver R&D insulates against China's 87% processing concentration. |
| Spatial-Audio Format Licensing | Exclusive streaming platform partnerships lock in premium-tier software differentiation. |
| Matter Protocol Certification | Interoperability standardization reduces SKU complexity for multi-room Wi-Fi deployments. |
| Automotive OEM Partnership Expansion | Electric vehicle cabin speaker counts create captive demand for weatherized assemblies. |
| Direct-to-Installer Channel Development | AV integrator portals capture professional sound reinforcement procurement shifting from two-step distribution. |
Study Parameters
Trade databases, regulatory filings from FCC and METI, and streaming platform hardware partnership disclosures formed the secondary backbone for this analysis. Primary interviews with acoustic engineering directors at automotive Tier 1 suppliers, AV integrator procurement managers in London and Berlin, and smart home ecosystem architects in Bangalore and Shenzhen were triangulated against customs records and SEC 10-K segment disclosures. Bottom-up driver unit forecasts and top-down consumer electronics spending patterns were reconciled across the analysis window.
Bottom-up modeling of Class-D amplifier shipments, driver array configurations, and enclosure material costs was cross-checked against top-down smart home penetration rates and automotive production schedules. Segmentation dimensions included product form factor, connectivity protocol, application intensity, and end-user purchasing authority. CAGRs were derived from installed base growth, replacement cycles, and content format adoption curves rather than extrapolated trend lines. Wi-Fi 6E chipset availability and Matter protocol certification timelines shaped connectivity segment trajectories.
Inputs from automotive OEM production planners and professional audio rental fleet operators were available through the study window; gaps in white-label Shenzhen manufacturer cost structures introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding Ecodesign Directive enforcement intensity and rare earth magnet price volatility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Europe Soundbar Market
Consumer Electronics
Smart Connected TV Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Headset Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Earphones Market
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
Global Smart Earbuds Market
Consumer Electronics
Bluetooth Headphones Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Watch Market