
 Portable Smart Speaker Market | 2026-2036
Portable Smart Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Smart Speaker Market Insights
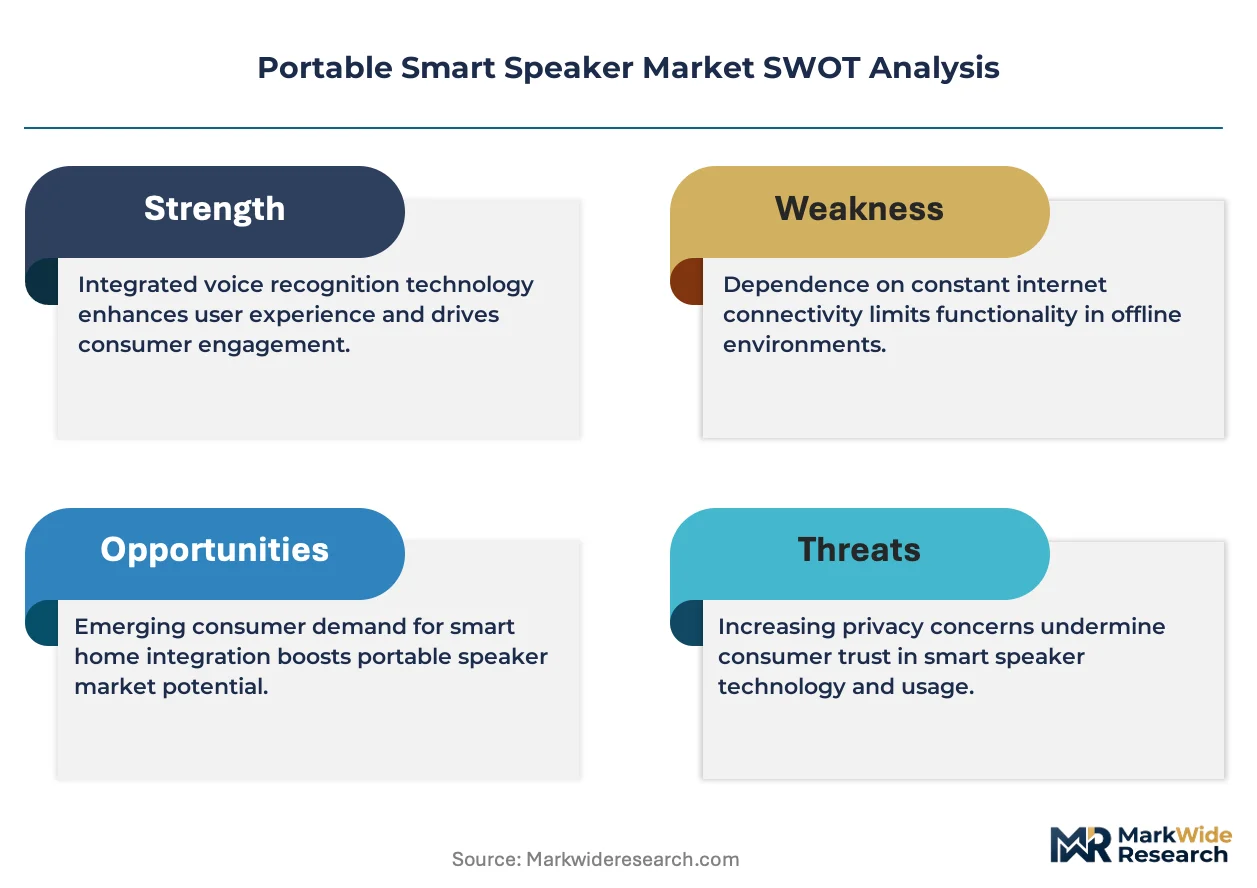
CE marking under the EU Radio Equipment Directive is unwinding competitive access for smaller hardware vendors lacking certified testing facilities. Amazon leverages its Alexa ecosystem to anchor recurring service revenue alongside hardware margins. Bose Corporation differentiates through proprietary acoustic engineering and premium positioning in outdoor-oriented product lines.
A portable smart speaker is a battery-powered wireless audio device integrating microphone arrays, voice recognition firmware, and cloud-connected natural language processing to deliver hands-free music playback, smart home control, and information retrieval. Manufacturing centers on compact driver design, IP-rated enclosure sealing, and low-latency codec optimization for Bluetooth and Wi-Fi transmission. Voice assistant speakers command the largest revenue pool as platform economics reward installed base scale over per-unit margin. Outdoor activities applications represent the fastest-expanding segment, driven by ruggedized designs and extended battery specifications that support camping, hiking, and poolside use cases.
FCC Part 15 regulations in the United States govern unintentional radiators and spread-spectrum transmissions, while REACH compliance in Europe restricts hazardous substances in circuit boards and adhesives. These frameworks elevate compliance costs but also consolidate market access around capitalized manufacturers with dedicated certification teams. Stakeholders must monitor evolving interoperability mandates between proprietary voice platforms and third-party hardware ecosystems as regulatory attention shifts toward data privacy and algorithmic transparency in connected audio devices.
Market Dynamics
Voice-first interface adoption is compressing traditional button-controlled hardware lifecycles while electromagnetic compatibility mandates under EU RED and FCC Part 15 fragment vendor compliance capabilities.
Growth Catalysts
- Outdoor recreation vertical:Ruggedized IP-rated enclosures and extended battery specifications are pulling camping, hiking, and poolside buyers into voice-controlled audio categories previously dominated by manual devices.
- REACH substance restrictions:European hazardous substance rules for circuit boards and adhesives are accelerating material substitution programs that favor capitalized manufacturers with dedicated certification infrastructure.
- Smart home penetration:United States streaming subscription density and connected-device household rates are anchoring replacement demand cycles shorter than traditional consumer electronics norms.
Market Restraints
- Codec licensing fragmentation:Proprietary low-latency audio transmission standards from platform operators impose royalty stacking that erodes hardware margins for unaffiliated vendors.
- Driver magnet supply:Rare earth element processing concentration in specific Asian supply basins creates input cost volatility and forced sourcing compliance risks under conflict mineral disclosure rules.
- Wi-Fi spectrum congestion:Unlicensed 2.4 GHz and 5 GHz band saturation in dense urban deployments degrades voice recognition latency below functional thresholds for real-time command processing.
Strategic Opportunities
- India BIS certification pathway:Local manufacturing incentives and phased import substitution mandates are opening domestic assembly partnerships for brands willing to absorb compliance timeline extension.
- Voice-platform interoperability mandates:Regulatory pressure on proprietary assistant lock-in is creating white-label firmware opportunities for hardware vendors previously excluded from closed ecosystems.
- Bluetooth LE Audio + Auracast convergence:Broadcast audio capability in public venues is enabling new location-based service revenue streams attached to portable hardware sales.
Industry Challenges
- Acoustic engineer scarcity:Compact driver tuning expertise for IP-sealed enclosures sits concentrated with legacy audio brands, constraining rapid product iteration at emerging vendors.
- RED certification timeline:EU electromagnetic compatibility testing queue lengths extend hardware launch windows by 4-6 months versus unregulated consumer electronics categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Smart Speaker Market |
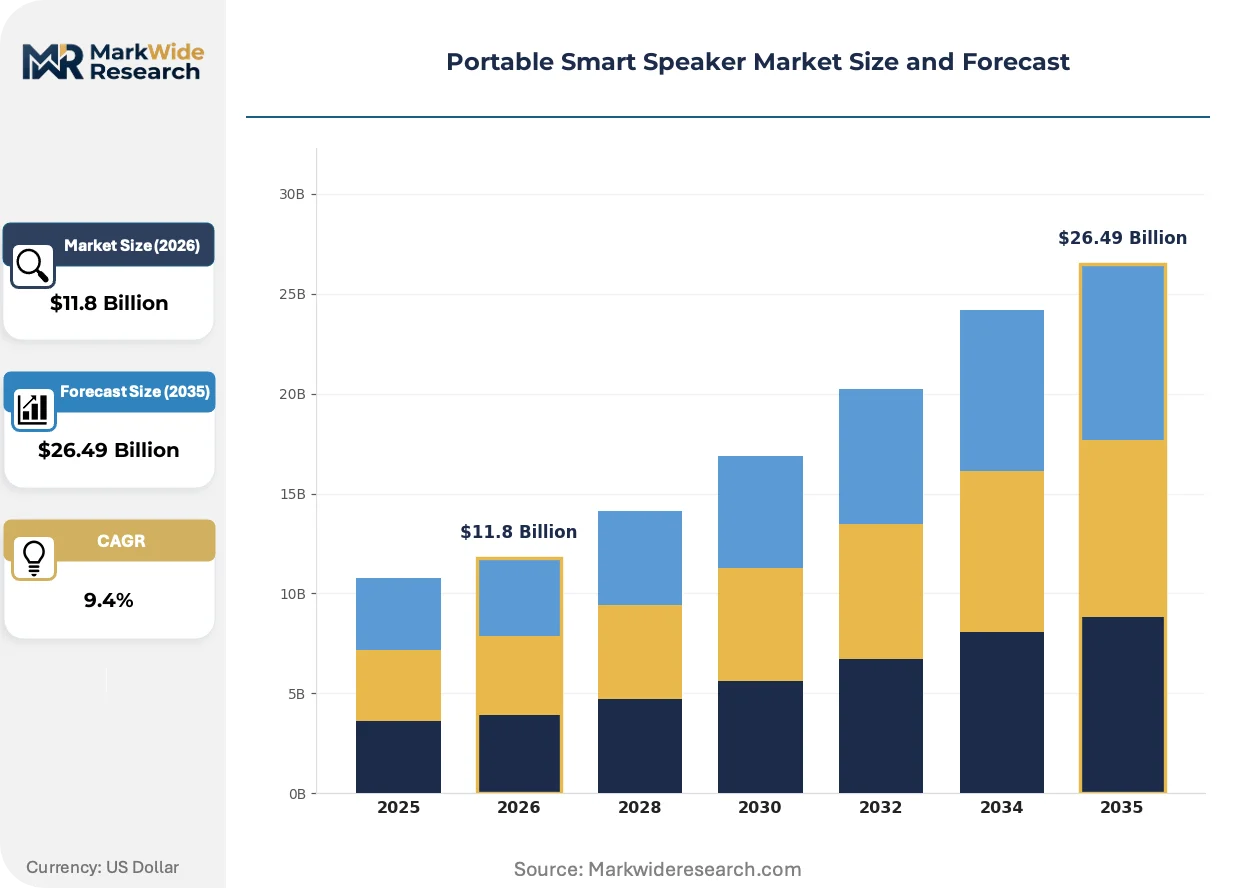
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Speaker, Wi-Fi Speaker, Smart Radio, Voice Assistant Speaker Technology: Voice Recognition, Digital Signal Processing, Cloud Connectivity, Multi-Room Audio Application: Home Use, Outdoor Activities, Office Environment, Automotive Integration End User: Consumers, Businesses, Educational Institutions, Fitness Enthusiasts |
| Companies Covered | Amazon, Google LLC, Apple, Sonos, Bose Corporation, Samsung Electronics, JBL, Sony Corporation, Harman Kardon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Smart Speaker Market Trends and Innovations
Hardware functionality is unbundling from voice assistant platform control, enabling modular firmware architectures that reduce single-platform dependency risks for manufacturers.
Edge-based natural language processing chips are decomposing cloud-dependent voice recognition architectures. Outdoor and mobile-first buyers are adopting on-device command processing to maintain function in bandwidth-constrained environments. This silicon shift is compressing the strategic value of cloud-scale inference infrastructure while elevating semiconductor vendor influence over hardware design specifications.
FCC Part 15 spread-spectrum transmission rules are tightening enforcement on unintentional radiator certification. United States market access now requires pre-market testing documentation that smaller hardware vendors struggle to resource internally. The rule change most affects Wi-Fi-enabled portable speakers targeting multi-room synchronization features, forcing consolidation around testing facility partnerships.
Direct-to-consumer channel preference is displacing traditional retail assortment for premium portable audio. Specialty outdoor retailers and voice-assistant platform storefronts are capturing buyer attention previously directed through big-box electronics. This rotation is most visible in United States coastal metropolitan markets where subscription bundling and expedited fulfillment have normalized platform-native purchasing behavior.
Portable Smart Speaker Market Segmentation
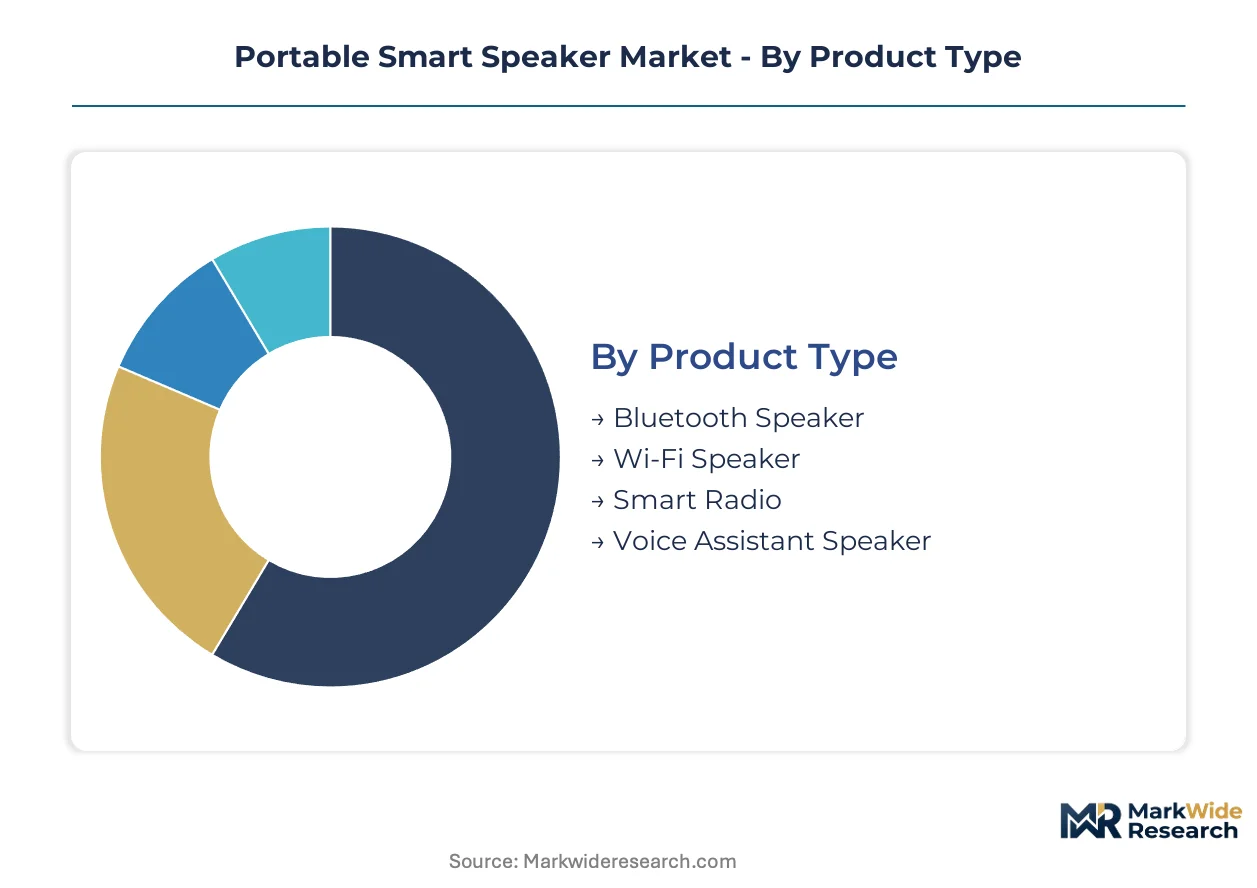
Portable smart speaker segmentation reflects divergent compliance burdens and use-case specifications that reshape vendor resource allocation. Platform economics, outdoor durability standards, and enterprise procurement cycles each demand distinct hardware architectures and certification pathways.
Product Type:
FCC Part 15 spread-spectrum rules and EU RED electromagnetic compatibility thresholds fragment certification requirements across wireless transmission architectures, elevating compliance costs disproportionately for multi-protocol devices.
- Bluetooth Speaker:Point-to-point audio transmission via short-range radio frequency eliminates cloud dependency for basic playback functions. Outdoor recreation buyers in the United States favor these units for campsite audio where cellular backhaul remains unreliable.
- Wi-Fi Speaker:Internet protocol-based streaming enables multi-room synchronization and higher bitrate codec support. Dense urban deployments in United States coastal metropolitan markets suffer 2.4 GHz and 5 GHz band saturation that degrades voice recognition latency below functional thresholds.
- Smart Radio:Hybrid broadcast-digital receivers aggregate terrestrial signals with IP streaming fallback. European households leverage these devices for kitchen and bedroom ambient audio where voice control supplements rather than replaces manual tuning.
- Voice Assistant Speaker:Microphone arrays integrate cloud-connected natural language processing for hands-free command execution. United States smart home penetration and streaming subscription density anchor replacement demand cycles shorter than traditional consumer electronics norms.
Voice Assistant Speaker handles the majority of throughput; Outdoor Activities application expansion is pulling Bluetooth Speaker and Wi-Fi Speaker into fastest share gains.
Technology:
Silicon vendor influence over hardware design specifications climbs as edge-based processing decomposes cloud-dependent architectures, compressing the strategic value of inference infrastructure scale.
- Voice Recognition:On-device natural language processing chips enable command execution in bandwidth-constrained environments. Camping and hiking buyers in the United States adopt these architectures where cellular coverage drops to zero.
- Digital Signal Processing:Real-time acoustic optimization compensates for driver enclosure constraints in IP-sealed ruggedized designs. Bose Corporation and legacy audio brands concentrate compact driver tuning expertise that constrains rapid iteration at emerging vendors.
- Cloud Connectivity:Persistent internet backhaul supports large language model inference and music streaming catalog access. United States metropolitan households with fiber and cable broadband density sustain this architecture as default.
- Multi-Room Audio:Synchronized playback across distributed speakers demands sub-20 millisecond latency coordination. Wi-Fi spectrum congestion in United States urban cores degrades synchronization precision below audiophile thresholds.
Cloud Connectivity commands installed base scale; Voice Recognition is climbing fastest as outdoor and mobile-first buyers prioritize function in dead zones.
Application:
Use-case durability specifications and environmental exposure limits determine IP rating requirements, battery chemistry selection, and enclosure material substitution programs under REACH substance restrictions.
- Home Use:Climate-controlled indoor deployment permits fabric mesh enclosures and standard lithium-ion cells without thermal management complexity. United States smart home penetration anchors replacement cycles driven by voice platform ecosystem upgrades.
- Outdoor Activities:Ruggedized IP67-rated enclosures and extended battery specifications support camping, hiking, and poolside exposure. United States national park visitation and coastal recreation markets expand adoption fastest among manual-control device converts.
- Office Environment:Conference room integration demands beamforming microphone arrays and acoustic echo cancellation for multi-participant calls. Businesses in United States technology sector clusters prioritize Microsoft Teams and Zoom certification compatibility.
- Automotive Integration:Cabin-mounted voice control supplements native infotainment systems for streaming access during vehicle operation. United States electric vehicle manufacturers embed these units in center console storage for portable-to-vehicle handoff.
Home Use retains volume concentration; Outdoor Activities is gaining share fastest as ruggedized designs pull manual-device users into voice-controlled categories.
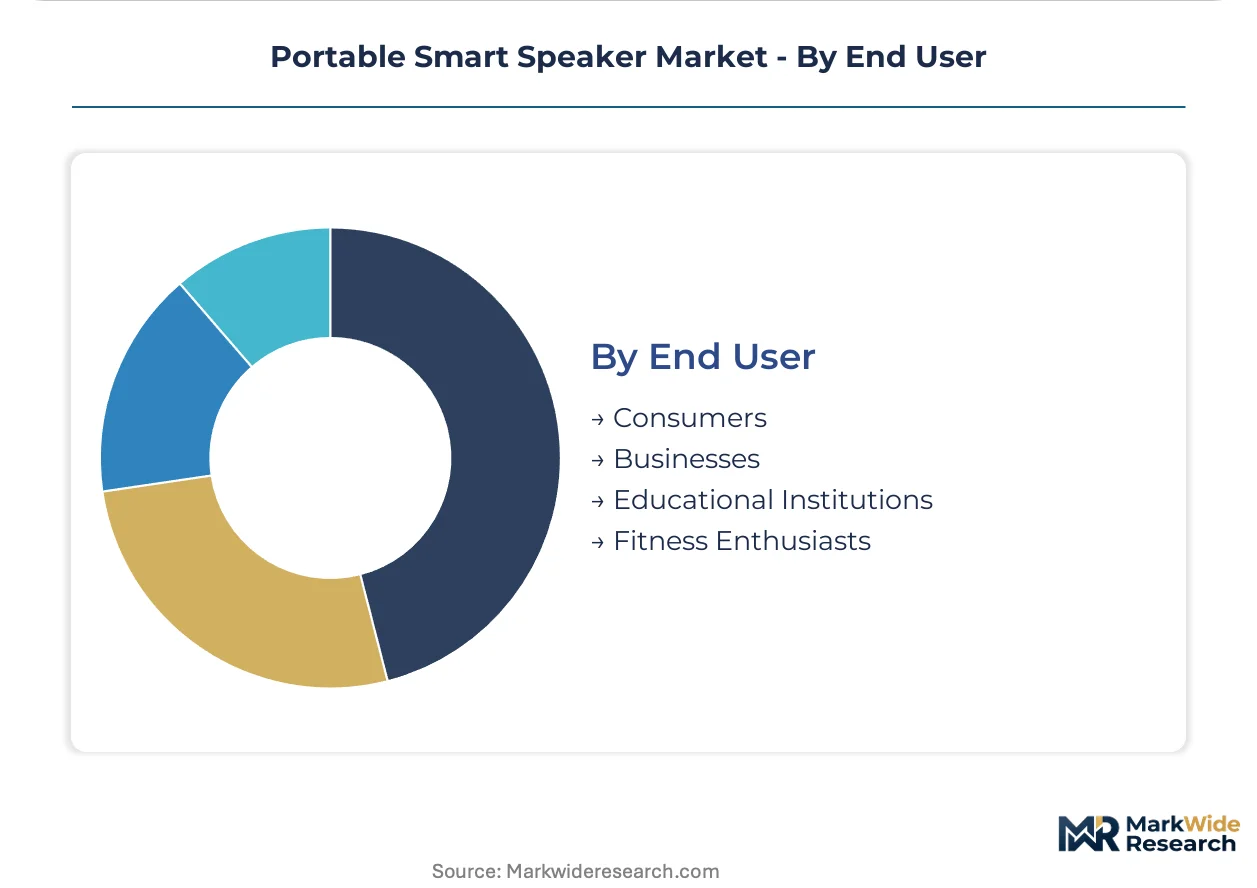
End User:
Procurement authority and volume scale separate consumer impulse purchases from institutional tender processes and enterprise fleet deployment cycles.
- Consumers:Individual household purchasers respond to platform ecosystem lock-in and subscription bundling incentives. Amazon leverages Alexa recurring service revenue alongside hardware margins to subsidize unit economics.
- Businesses:Corporate procurement departments evaluate total cost of ownership across deployment scale and IT integration overhead. United States technology sector firms standardize on certified conference room audio for hybrid work infrastructure.
- Educational Institutions:K-12 and university IT departments prioritize durability and centralized fleet management over premium acoustic performance. United States public school districts batch-purchase through cooperative procurement contracts.
- Fitness Enthusiasts:Gym and studio operators demand sweat-resistant enclosures and high-SPL output for instruction clarity. Boutique fitness chains in United States coastal metropolitan markets deploy these for instructor voice projection.
Consumers drive absolute unit volume; Fitness Enthusiasts is expanding most quickly as boutique studio formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Outdoor recreation buyers in the United States concentrate premium portable smart speaker demand, while European regulatory tightening and Asian manufacturing incentives reshape competitive access across major economies.
United States
Smart home penetration and streaming subscription density anchor replacement cycles shorter than traditional consumer electronics norms. FCC Part 15 spread-spectrum transmission rules tighten enforcement on unintentional radiator certification, elevating pre-market testing documentation requirements. Coastal metropolitan markets from Seattle to Miami normalize platform-native purchasing behavior through subscription bundling and expedited fulfillment.
Germany
European households leverage hybrid broadcast-digital receivers for kitchen and bedroom ambient audio where voice control supplements manual tuning. EU Radio Equipment Directive electromagnetic compatibility thresholds extend hardware launch windows through certified testing queue lengths. Industrial clusters in Bavaria and Baden-Württemberg concentrate acoustic engineering expertise for compact driver tuning in IP-sealed enclosures.
China
Domestic assembly partnerships absorb compliance timeline extensions under local manufacturing incentives and phased import substitution mandates. MIIT radio transmission standards and GB certification requirements govern wireless audio device market access. Shenzhen and Dongguan electronics manufacturing basins concentrate rare earth element processing for driver magnet supply chains.
India
BIS certification pathways open for brands willing to absorb extended compliance timelines under local manufacturing incentives. TRAI spectrum allocation frameworks shape wireless audio transmission standards for unlicensed band operation. Karnataka and Tamil Nadu electronics manufacturing corridors attract domestic assembly partnerships for portable audio hardware.
Japan
Households sustain cloud-dependent voice recognition architectures through fiber and cable broadband density in metropolitan corridors. METI energy efficiency standards influence battery chemistry selection and thermal management specifications. Tokyo-Osaka industrial corridors concentrate semiconductor vendor influence over edge-based natural language processing chip design.
Portable Smart Speaker Market Competitive Landscape
Player mix skews toward platform-anchored technology conglomerates with voice assistant ecosystems and legacy audio specialists with proprietary acoustic engineering capabilities. Consolidation pressure operates through certification cost barriers and codec licensing fragmentation that erodes hardware margins for unaffiliated vendors. Two strategic archetypes dominate: voice-platform operators monetizing recurring service revenue alongside hardware sales, and premium audio brands differentiating through ruggedized outdoor-oriented product lines. Competitive moves concentrate on strategic partnerships for certification facility access and portfolio diversification into edge-based processing architectures.
Within the platform-operator tier, Amazon exemplifies voice-assistant ecosystem monetization through Alexa recurring service revenue subsidizing unit economics. Bose Corporation occupies a position representing premium acoustic engineering differentiation in outdoor-oriented product lines with proprietary driver tuning expertise. Samsung Electronics anchors the diversified electronics conglomerate archetype with vertical integration advantages across semiconductor and display supply chains.
| Leading Market Players |
|---|
| Amazon |
| Google LLC |
| Apple |
| Sonos |
| Bose Corporation |
| Samsung Electronics |
| JBL |
| Sony Corporation |
| Harman Kardon |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with rare earth processors lock in magnet supply access and price visibility for voice-assistant hardware vendors navigating REACH substance restrictions and FCC Part 15 certification timelines. These contracts insulate against neodymium price volatility while committing buyers to minimum offtake volumes that strain working capital at smaller manufacturers.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate driver magnet procurement, with pricing stratifying across premium acoustic engineering tiers, standard Bluetooth-only configurations, and economy private-label units. Certification grade under EU RED electromagnetic compatibility thresholds and FCC Part 15 spread-spectrum rules creates tiered price differentiation between multi-protocol and single-protocol devices. Pricing pressure stems from codec licensing royalty stacking that erodes hardware margins for unaffiliated vendors. Fitness enthusiasts and boutique studio operators exhibit lowest price sensitivity due to durability requirements, while educational institutions drive hardest volume negotiations through cooperative procurement contracts.
Supply Chain Analysis
Rare earth element processing concentration in China's Jiangxi and Inner Mongolia basins creates single-source vulnerability for neodymium-iron-boron magnet supply that feeds driver assembly in Shenzhen and Dongguan manufacturing corridors. Driver voice coils, lithium-ion cells, and edge-based NLP silicon draw from South Korean battery chemistry specialists and Taiwanese semiconductor foundries. Tariff exposure on Chinese rare earth exports threatens input cost stability for vendors lacking diversified magnet sourcing. Distribution runs through voice-assistant platform storefronts and specialty outdoor retailers that displace traditional big-box electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around outdoor recreation verticals where ruggedized IP-rated specifications and extended battery demands outstrip legacy audio brand iteration capacity. Voice-first interface adoption across camping, hiking, and poolside use cases creates niche entry points for specialized hardware vendors.
For Market Incumbents: Secure exclusive certification facility partnerships to compress EU RED electromagnetic compatibility testing timelines that currently extend launch windows by 4-6 months. Defend margin position through backward integration into edge-based natural language processing chip design, neutralizing cloud-dependent architecture commoditization threats from semiconductor vendors. Prioritize acoustic engineer retention in Bavaria and Baden-Württemberg industrial clusters where compact driver tuning expertise concentrates. For New Entrants and Emerging Players: Lead with India BIS certification pathway absorption to capture domestic assembly incentives and phased import substitution mandates before established brands localize production. Target fitness enthusiast segments where boutique studio format proliferation outpaces incumbent ruggedized product development cycles. Pursue white-label firmware opportunities under emerging voice-platform interoperability mandates that erode proprietary assistant lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward edge-based processing chip designers with voice recognition firmware portfolios, as on-device command execution architectures compress cloud-scale inference infrastructure valuations over the coming decade. Monitor Bluetooth LE Audio and Auracast broadcast capability adoption in public venues as inflection signal for location-based service revenue attachment potential.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Based NLP Chip Integration | On-device voice recognition reduces cloud dependency for bandwidth-constrained outdoor buyers. |
| EU RED Certification Partnership | Pre-qualified testing facilities compress hardware launch windows against 4-6 month queue delays. |
| India Domestic Assembly Localization | BIS compliance absorption captures PLI manufacturing incentives and import substitution mandates. |
| Rare Earth Magnet Supply Diversification | Dual-sourcing from Vietnam and Australia mitigates Chinese processing concentration risk. |
| Bluetooth LE Audio Auracast Deployment | Broadcast capability in transit hubs and stadiums enables location-based service bundling. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with acoustic engineering directors, voice platform partnership leads, outdoor retailer category managers, and FCC certification consultants; and secondary validation through SEC hardware vendor filings, EU RAPEX safety alerts, Bluetooth SIG protocol disclosures, and customs trade records for rare earth magnet imports. Bottom-up unit shipment modeling triangulated against top-down consumer electronics spend allocation across smart home and outdoor recreation categories.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning wireless transmission architecture, voice processing technology tier, use-case durability specification, and procurement authority type. CAGRs derived from replacement cycle compression analysis against traditional consumer electronics norms, with voice-assistant ecosystem lock-in rates and streaming subscription density as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FCC Part 15 enforcement tightening and EU RED electromagnetic compatibility threshold stability would require recalibration. Forecasts reflect assumptions regarding rare earth supply chain continuity and voice-platform interoperability mandate progression. Practitioners should keep alternative scenarios live as regulatory attention shifts toward data privacy and algorithmic transparency in connected audio devices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Earphones Market
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
Wireless Mouse Market
Consumer Electronics
Smart Connected Speaker Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Dive Computer Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Gaming Mouse Market
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Electronics
North America Smart TV Market
Consumer Electronics
Pillow Holder for Tablets Market